
 Philippines Used Car Market | 2026-2036
Philippines Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Used Car Market Outlook
The gap between certified pre-owned vehicles and unregulated street sales is repositioning how Filipino consumers evaluate trust and warranty coverage in secondhand transactions. Toyota Certified Philippines leverages its factory-backed inspection programs to anchor buyer confidence in the sedan and SUV categories. AutoDeal Philippines competes through digital price transparency tools that reduce information asymmetry for provincial buyers. Carmudi Philippines extends its platform reach into Mindanao, where dealership density remains thin and private sales dominate.
A used car denotes a previously registered motor vehicle transferred through resale, typically evaluated by model year, odometer reading, service history, and structural integrity against Philippine National Standards for roadworthiness. Its commercial purpose centers on affordable mobility access for households and small enterprises priced out of new-vehicle markets. SUVs and pickups command structural premiums in the archipelago's flood-prone topography and rural infrastructure conditions. The online platform channel is gaining fastest among younger buyers in Metro Manila and Cebu, though traditional dealerships still control financing bundling and warranty fulfillment. Single-owner petrol sedans represent the most liquid inventory pool for certified programs seeking predictable resale margins.
The Land Transportation Office enforces registration transfer protocols and emission compliance under the Clean Air Act, while the Department of Trade and Industry monitors dealer disclosure standards through its consumer protection mandate. These frameworks elevate compliance costs for informal sellers while creating regulatory shelter for organized dealership networks. Stakeholders must monitor how BIR tax enforcement on undocumented vehicle transfers reshapes competitive dynamics between formal and informal channels.
Market Dynamics
The Land Transportation Office's emission testing protocols under the Clean Air Act are compressing the supply of older-model inventory and forcing rapid fleet turnover among ride-hailing operators in Metro Manila and Cebu.
Growth Catalysts
- Ride-hailing fleet replacement cycles:Grab and Angkas drivers in Metro Manila and Cebu face mandatory vehicle age caps, creating sustained demand for late-model sedans and SUVs with documented service histories.
- Clean Air Act enforcement:The Department of Environment and Natural Resources mandates biennial emission certification, disqualifying pre-2010 vehicles from commercial registration in major urban centers.
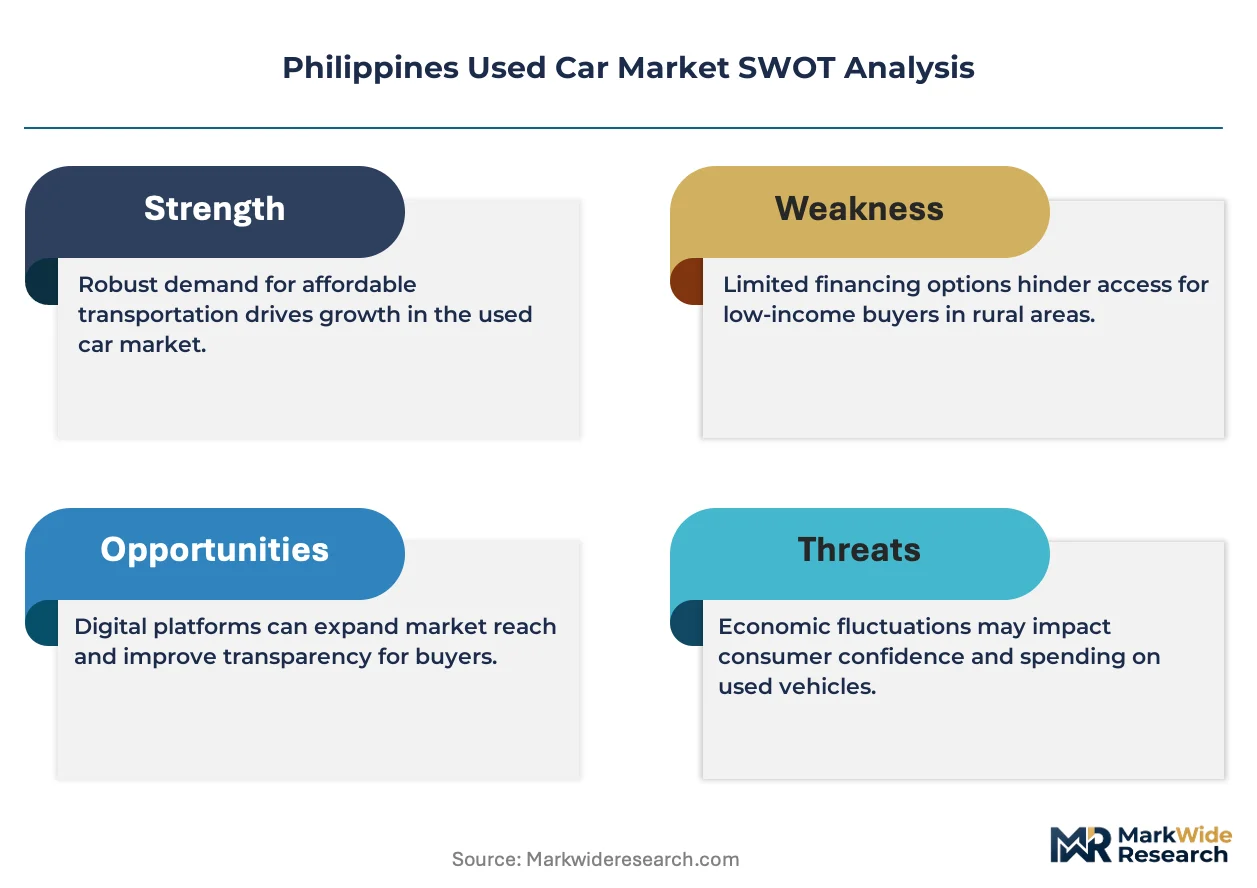
- Digital platform penetration:Online marketplaces reduce search costs for provincial buyers in Mindanao and Visayas, extending certified pre-owned access beyond traditional dealership corridors.
Market Restraints
- Import tariff volatility:The Bureau of Customs applies inconsistent valuation standards on rebuilt Japanese and Korean units, creating landed cost uncertainty for Subic and Cagayan de Oro port operators.
- Financing concentration:Rural banks and cooperatives lack standardized collateral appraisal tools, restricting credit access for buyers outside Metro Manila's formal banking network.
- Flood damage opacity:Undisclosed submerged vehicle histories from typhoon seasons in Bicol and Eastern Visayas erode buyer trust in private-party transactions without structural inspection records.
Strategic Opportunities
- Mindanao dealership expansion:Davao and Cagayan de Oro exhibit the lowest certified pre-owned penetration rates nationally, with private sales dominating due to thin formal distribution.
- Embedded telematics integration:Odometer verification and real-time condition monitoring via connected vehicle platforms address information asymmetry in secondary transactions.
- Department of Trade and Industry disclosure mandates:Pending rules requiring standardized defect documentation would advantage organized dealer networks over informal sidewalk sellers.
Industry Challenges
- Certified technician scarcity:Factory-authorized inspection programs require ASE-equivalent training that remains concentrated in Luzon, limiting quality assurance scale in Visayas and Mindanao.
- Title transfer friction:The Land Transportation Office's digitization backlog creates 45-90 day registration delays, freezing working capital for inventory-heavy dealership operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Used Car Market |
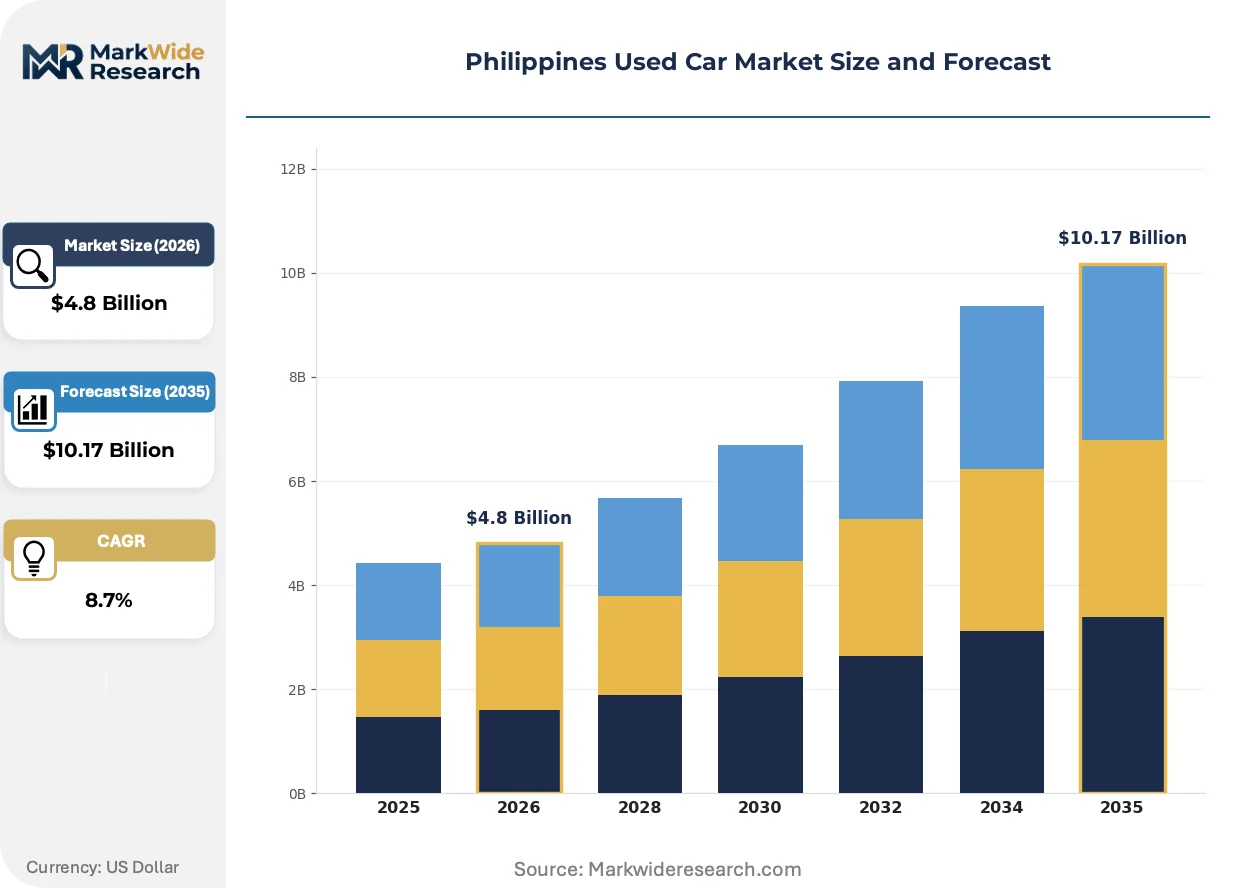
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Pickup Fuel Type: Petrol, Diesel, Electric, Hybrid Ownership History: Single Owner, Multiple Owners, Corporate, Rental Market Channel: Dealerships, Online Platforms, Auctions, Private Sales |
| Companies Covered | Carmix, AutoDeal Philippines, Toyota Certified Philippines, EastWest Bank Philippines, Carmudi Philippines, Nissan Intelligent Choice Philippines, Automart Philippines, BDO Unibank Philippines, Carmax, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Used Car Market Strategic Shifts
Digital verification tools and regulatory compliance automation are restructuring how vehicles circulate between owners, reducing reliance on physical inspection and paper-based documentation.
Blockchain-based title verification is electrifying trust infrastructure in secondary transactions. The technology creates immutable ownership chains that reduce fraud exposure for financing institutions. Major fleet operators in Metro Manila are piloting distributed ledger systems to accelerate collateral verification. This compression of due diligence timelines is electrifying transaction velocity for high-volume dealers.
The Clean Air Act's implementing rules from the Department of Environment and Natural Resources mandate onboard diagnostic testing for all commercial vehicle renewals. Workshops must now invest in standardized scanning equipment to certify compliance. Diesel-powered utility vehicles face disproportionate failure rates under the new protocols. Smaller provincial garages in Cebu and Davao are consolidating to share capital equipment costs.
Subscription-based vehicle access is fragmenting traditional ownership patterns among younger Metro Manila professionals. Monthly fee structures bundle maintenance, insurance, and registration transfer services that eliminate lump-sum purchase requirements. Digital-native platforms are capturing this cohort through app-based inventory browsing and remote financing pre-approval. The model concentrates initially in sedan categories before expanding to flood-prone SUV segments.
Philippines Used Car Market Segmentation
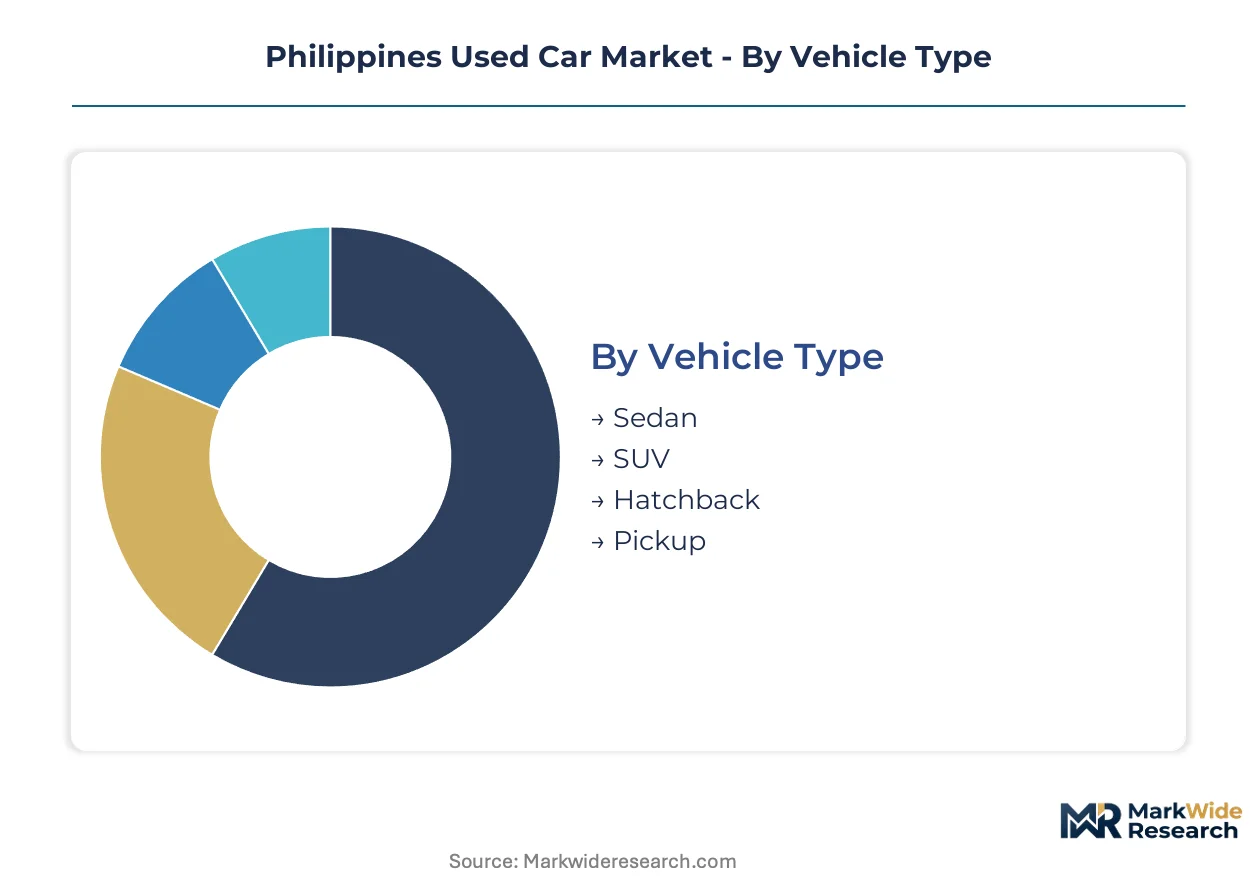
Segmentation in the Philippines used car market determines financing eligibility, warranty coverage, and resale velocity. Distinctions between vehicle types, fuel systems, and sales channels create divergent risk profiles for lenders and fleet operators.
Vehicle Type:
Capital requirements vary sharply across body styles, with SUVs and pickups demanding higher inventory financing due to structural premiums in flood-prone regions.
- Sedan:Three-box passenger vehicles with enclosed trunks dominate Metro Manila ride-hailing fleets. Single-owner petrol units with documented service histories from Toyota and Honda attract the tightest bid-ask spreads in certified pre-owned programs.
- SUV:Sport utility vehicles command price premiums reflecting archipelago topography and rural road conditions. Demand concentrates in Bicol and Eastern Visayas where ground clearance requirements override fuel economy concerns during monsoon seasons.
- Hatchback:Compact two-box designs with rear cargo access suit Cebu and Davao urban corridors where parking scarcity favors shorter wheelbases.
- Pickup:Open-bed utility vehicles serve small enterprises in Mindanao agricultural zones and construction subcontractors across Cavite and Laguna industrial belts.
Most installed capacity flows through Sedan. Expansion is steepest in SUV.
Fuel Type:
Compliance costs under the Clean Air Act restructure competitive economics across propulsion systems, with diesel facing disproportionate testing burdens.
- Petrol:Spark-ignition gasoline engines populate the most liquid secondary market segment. Metro Manila emission testing protocols favor newer petrol inventories with onboard diagnostic compatibility.
- Diesel:Compression-ignition engines power commercial fleets and provincial utility buyers. DENR biennial certification requirements are compressing demand for pre-2010 diesel units in major urban centers.
- Electric:Battery-electric vehicles remain thinly traded with charging infrastructure concentrated in Makati and Taguig central business districts.
- Hybrid:Dual-powertrain systems from Japanese manufacturers attract technology-forward buyers in Cebu and Davao middle-income brackets.
Transaction velocity peaks in Petrol. Regulatory pressure is accelerating most quickly in Diesel.
Ownership History:
Provenance documentation determines collateral value for bank financing, with single-owner vehicles securing preferential loan terms.
- Single Owner:Vehicles with uninterrupted individual registration generate highest confidence in odometer integrity and maintenance continuity. Lenders in Metro Manila formal banking networks require single-owner documentation for prime-rate used car loans.
- Multiple Owners:Successive private transfers accumulate title friction and information asymmetry. These units concentrate in private-party Mindanao transactions where documentation standards remain informal.
- Corporate:Fleet-maintained vehicles from logistics and delivery operators offer standardized service intervals but accelerated depreciation schedules.
- Rental:Former lease fleet units from ride-hailing and short-term rental operators flood the market at mandatory age caps, pressuring sedan resale curves.
Financing access concentrates in Single Owner. Volume expansion is climbing fastest in Corporate.
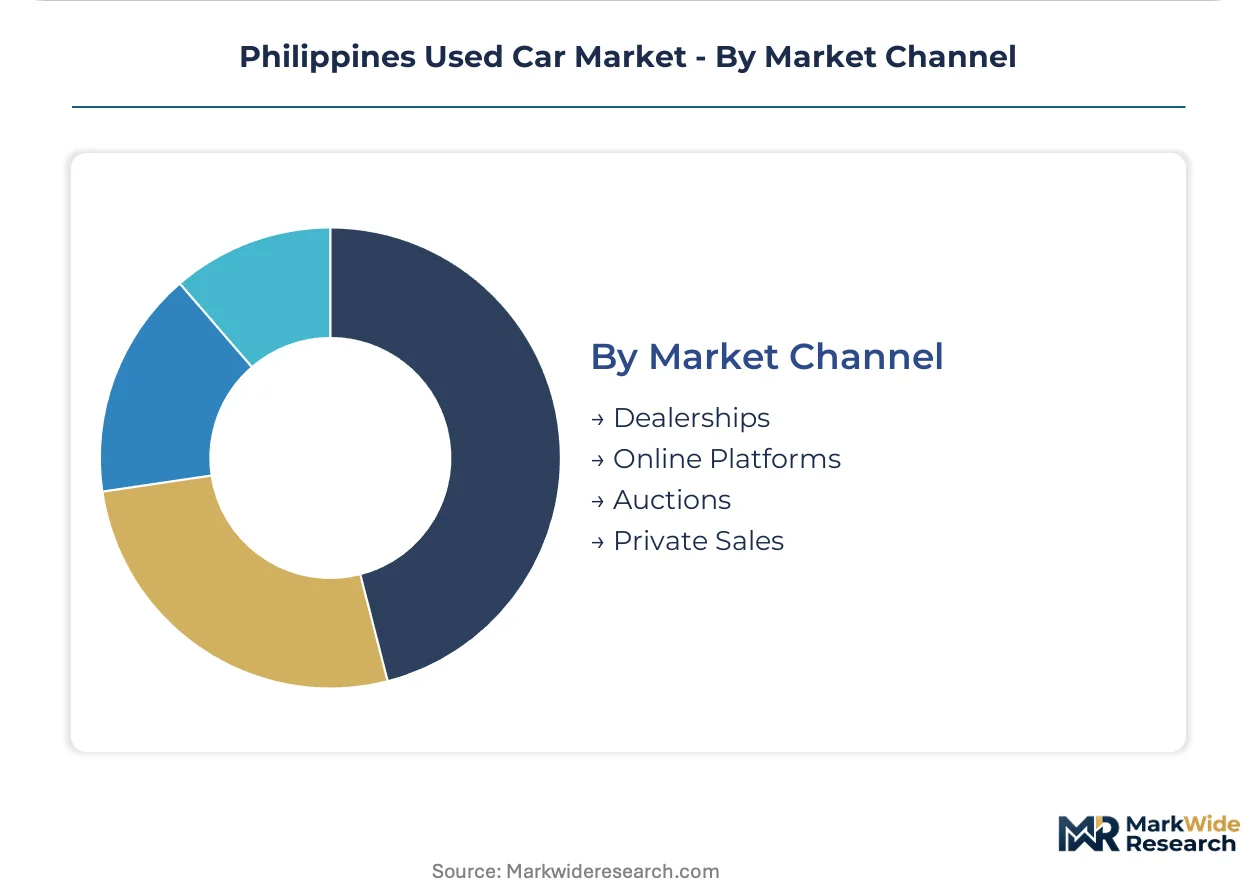
Market Channel:
Channel selection dictates warranty coverage, financing bundling, and regulatory shelter under DTI disclosure mandates.
- Dealerships:Organized dealer networks control certified pre-owned certification and captive financing products. These operators absorb LTO registration transfer delays and provide structural inspection guarantees.
- Online Platforms:Digital marketplaces reduce search costs for provincial buyers in Visayas and Mindanao where physical dealership density remains thin. Price transparency tools compress information asymmetry for comparison shoppers.
- Auctions:Fleet disposal and insurance salvage channels supply dealer inventory with volume certainty but limited individual unit provenance.
- Private Sales:Direct owner-to-buyer transactions dominate rural Mindanao and Bicol corridors where formal distribution has not penetrated. Flood damage opacity and title fraud exposure restrict financing access.
Warranty fulfillment flows predominantly through Dealerships. Digital penetration is gaining share fastest in Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Philippines used car market diverges sharply from regional neighbors where formal certification networks dominate secondary vehicle transactions. Indonesia's fragmented archipelago structure and Thailand's export-oriented manufacturing base produce fundamentally different competitive dynamics for pre-owned inventory circulation.
Metro Manila
Ride-hailing fleet operators in Makati and Quezon City drive concentrated demand for late-model sedans with documented service histories. The Land Transportation Office enforces biennial emission certification under Clean Air Act implementing rules, compressing viable inventory to vehicles manufactured after 2010. Toyota Certified Philippines anchors its flagship inspection facility in Taguig, processing volume for the National Capital Region's formal banking network.
Central Visayas
Cebu's urban corridor exhibits accelerating digital platform penetration as provincial buyers seek price transparency beyond traditional dealership corridors. The Department of Trade and Industry maintains regional consumer protection offices monitoring disclosure standards in Mandaue and Lapu-Lapu commercial zones. Carmudi Philippines extends platform infrastructure into Bohol and Negros Oriental where physical dealership density remains thin.
Southern Mindanao
Davao City's agricultural enterprise base generates sustained pickup demand for small contractors and rural logistics operators. The Bureau of Customs applies inconsistent valuation standards at Cagayan de Oro port, creating landed cost uncertainty for rebuilt Japanese utility vehicles. Private sales dominate inventory circulation across the Davao Region due to minimal formal distribution penetration.
Bicol Region
Flood-prone topography in Albay and Camarines Sur elevates SUV price premiums during monsoon seasons when ground clearance determines vehicle utility. Undisclosed submerged vehicle histories from typhoon damage erode buyer trust in private-party transactions without structural inspection documentation. Informal sidewalk sellers control volume in Legazpi commercial corridors outside DTI regulatory shelter.
Philippines Used Car Market Competitive Environment
Top-tier vendors anchor certified pre-owned certification and captive financing bundling, while mid-tier digital platforms compete on search cost reduction and price transparency. The market structure concentrates warranty fulfillment and registration transfer services within organized dealership networks absorbing Land Transportation Office processing delays. Three strategic archetypes dominate: factory-authorized certification programs, bank-affiliated financing channels, and independent digital marketplaces. Competitive moves center on geographic platform expansion into underserved provinces and embedded telematics integration for condition verification.
Within the factory-authorized tier, Toyota Certified Philippines and Nissan Intelligent Choice Philippines represent vertically integrated certification archetypes leveraging brand equity for buyer confidence. AutoDeal Philippines and Carmudi Philippines occupy digital-native positions reducing information asymmetry through price comparison tools and remote financing pre-approval workflows. EastWest Bank Philippines and BDO Unibank Philippines anchor financial services integration, bundling collateral appraisal with loan origination for formal banking network customers. Carmix and Automart Philippines exemplify independent dealership models competing on inventory velocity in Metro Manila's high-turnover corridors.
| Leading Market Players |
|---|
| Carmix |
| AutoDeal Philippines |
| Toyota Certified Philippines |
| EastWest Bank Philippines |
| Carmudi Philippines |
| Nissan Intelligent Choice Philippines |
| Automart Philippines |
| BDO Unibank Philippines |
| Carmax |
| Others |
Value Chain & Pricing Dynamics
ASE-certified technician concentration in Metro Manila and Cebu compresses labor-cost differentials that separate premium certified-preowned pricing from unregulated street-market tiers. This workforce geography forces provincial dealers to absorb higher inspection outsourcing costs or accept compressed margins in the economy segment.
Pricing Analysis
Bundled warranty-and-registration services from organized dealers command spreads over unbundled private-party transactions where buyers absorb LTO transfer delays and flood-risk uncertainty. Price differentiation rests on Clean Air Act compliance documentation and single-owner provenance verification. Cost compression in the economy tier intensifies as rebuilt Japanese imports from Subic and Cagayan de Oro ports face Bureau of Customs valuation disputes. Ride-hailing fleet operators exhibit lowest price sensitivity due to mandatory age-cap replacement cycles; rural Mindanao agricultural buyers face acute sensitivity where financing access is sparse.
Supply Chain Analysis
Workforce availability for factory-authorized inspection programs concentrates in Luzon, leaving Visayas and Mindanao dependent on traveling technician networks or informal garage certification. Inventory sourcing draws from Japanese auction houses, Korean export channels, and domestic fleet retirements. Single-source vulnerability runs through the Land Transportation Office's digitization backlog, which freezes dealer working capital during 45-90 day registration transfers. Distribution runs through three pathways: organized dealer networks with captive financing, digital platforms reducing search costs for provincial buyers, and informal sidewalk channels dominating Bicol and rural Mindanao.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines used car market reads as a late-cycle quality story where Clean Air Act enforcement is filtering demand toward emission-compliant, documented inventory with verified service histories.
For Market Incumbents: Hedge against margin compression in the sedan segment by securing captive supply agreements with ride-hailing fleet operators facing mandatory replacement cycles. Deepen backward integration into telematics-enabled condition verification to differentiate certified programs from digital platforms lacking physical inspection infrastructure.
For New Entrants and Emerging Players: Rural banking cooperatives offer the most penetrable channel partnership for embedded financing products in Mindanao and Bicol corridors where formal credit access remains thin. Target Davao and Cagayan de Oro for white-space expansion where certified pre-owned penetration rates sit lowest nationally. Deploy mobile inspection units to overcome technician scarcity and build trust in private-sale-dominated regions.
For Investors and Strategic Acquirers: Bank-affiliated financing channels are the most active acquirer in this space, seeking dealership networks that bundle collateral appraisal with loan origination. Long-term viability centers on platforms that compress LTO registration friction and absorb compliance costs informal sellers cannot shoulder. Watch for Department of Trade and Industry disclosure mandate implementation as the inflection signal that would accelerate consolidation toward organized dealer networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Telematics Integration | Odometer verification via connected platforms addresses information asymmetry in secondary transactions. |
| Mindanao Dealership Expansion | Davao and Cagayan de Oro exhibit lowest certified pre-owned penetration with thin formal distribution. |
| Mobile Inspection Unit Deployment | Traveling technician networks overcome ASE-training concentration in Luzon for provincial quality assurance. |
| Captive Fleet Supply Agreements | Grab and Angkas age-cap mandates create predictable volume for late-model sedan inventory pipelines. |
| Blockchain Title Verification | Distributed ledger pilots among Metro Manila fleet operators accelerate collateral verification for financing institutions. |
Study Parameters
Direct dialogue with dealership operations managers, ride-hailing fleet procurement officers, rural banking cooperative lending heads, and Land Transportation Office registration administrators grounded the qualitative foundation. Secondary validation drew from Bureau of Customs trade records, Department of Environment and Natural Resources emission testing compliance databases, Department of Trade and Industry consumer protection filings, and vehicle production statistics from Japanese and Korean export agencies. Bottom-up inventory flow modeling and top-down macroeconomic triangulation produced convergent estimates across the analysis window.
Segment-level outputs tracked vehicle type, fuel system, ownership history, and market channel across the projection horizon. CAGRs derived from regression analysis against ride-hailing fleet growth trajectories, Clean Air Act implementation timelines, and digital platform penetration curves in provincial corridors. Forecast inputs incorporated LTO digitization progress, BIR enforcement intensity on undocumented transfers, and flood damage disclosure standards from pending DTI rulemaking.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement consistency and port valuation standardization. Assumptions reflect current Clean Air Act implementation pace and existing digital platform adoption trajectories. Material deviation in LTO processing efficiency or Bureau of Customs tariff administration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
South Africa Used Car Market
Used Vehicles
Nigeria Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Canada Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Italy Used Car Market
Used Vehicles
China Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
Oman Used Car Market