
 Oman Used Car Market | 2026-2036
Oman Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Used Car Market Insights
Aluminum-intensive body construction is consolidating as a cost-efficiency standard across higher-mileage inventory, reducing curb weight and improving fuel economy for budget-conscious buyers. Omanicar leverages its physical inspection centers across Muscat and Salalah to anchor buyer trust in vehicle condition transparency. Dubizzle Oman competes through classified-listing density and digital payment integration, while YallaMotor.com specializes in price-benchmarking tools that reduce search friction for sedan and SUV shoppers.
A used car denotes a previously registered automobile that has undergone operational service, typically assessed through odometer verification, chassis integrity inspection, and powertrain diagnostic evaluation before resale; its commercial purpose centers on delivering personal mobility at depreciated acquisition cost relative to new vehicle equivalents. SUV inventory commands structural prominence in Oman's secondary market, reflecting terrain demands and family-size requirements across the Sultanate's road network. Certified Pre-Owned vehicles carry concentrated margin pools due to warranty-backed positioning and formal dealer accountability, while petrol-powered automatic transmission units sustain liquidity advantages in resale velocity.
Oman's Ministry of Transport, Communications and Information Technology enforces periodic technical inspection mandates that filter unsafe vehicles from circulation, while the central bank's consumer financing guidelines shape hire-purchase accessibility for used car buyers. The country's national standards body calibrates emission and safety benchmarks that importers must satisfy for market entry. Stakeholders must monitor how electrified powertrain penetration in new car sales reshapes future used car supply composition and technician certification requirements.
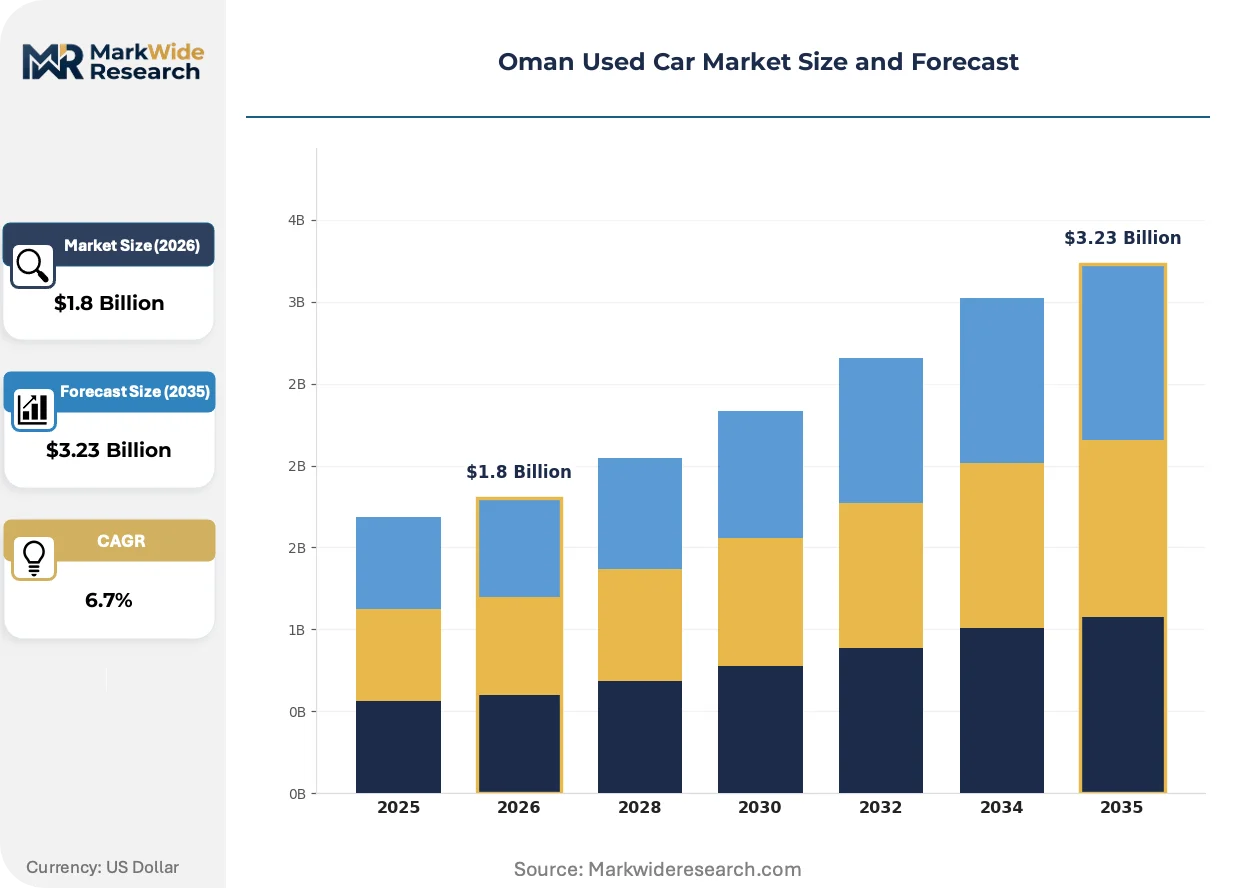
Market Dynamics
Fleet operators and ride-hailing drivers are compressing replacement cycles for pre-owned vehicles as total cost of ownership calculations sharpen procurement discipline across Oman's secondary automotive market.
Growth Catalysts
- Technical Inspection Mandates:The Ministry of Transport, Communications and Information Technology enforces updated vehicle inspection protocols that filter unsafe inventory from circulation, elevating buyer confidence in certified pre-owned transactions.
- Aluminum Body Adoption:Higher-mileage inventory increasingly incorporates aluminum-intensive construction, reducing curb weight and improving fuel economy for budget-conscious buyers navigating Oman's terrain demands.
- Urban Density Concentration:Muscat Governorate's income levels and population density sustain premium SUV and sedan turnover, concentrating liquidity in the Sultanate's most active secondary market corridor.
Market Restraints
- Import Compliance Friction:The national standards body's emission and safety benchmarks impose calibration costs on importers, filtering vehicle eligibility and compressing available supply.
- Financing Accessibility Limits:The central bank's consumer financing guidelines shape hire-purchase terms, constraining credit access for certain buyer segments.
- Electrification Supply Lag:Minimal electrified powertrain penetration in new car sales delays future used EV supply composition, leaving petrol-powered automatic transmissions as the sole liquid asset class.
Strategic Opportunities
- Salalah Corridor Expansion:Physical inspection infrastructure outside Muscat remains underdeveloped, creating white space for condition-transparency services in Oman's second-largest urban center.
- Digital Payment Integration:Classified platforms embedding financing and escrow functions can capture transaction flow currently fragmented across informal channels.
- Technician Certification Programs:Electrified powertrain maintenance skills gaps create training revenue streams as hybrid and battery-electric vehicles eventually enter secondary circulation.
Industry Challenges
- Diagnostic Equipment Capex:Powertrain evaluation tools for modern engine management systems require substantial capital investment from inspection centers.
- Cross-Border Title Verification:Chassis integrity documentation from source markets demands manual authentication, slowing inventory velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Used Car Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Coupe Condition: Certified Pre-Owned, Good, Fair, Poor Fuel Type: Petrol, Diesel, Electric, Hybrid Transmission: Automatic, Manual, CVT, Semi-Automatic |
| Companies Covered | Omanicar, Dubizzle Oman, YallaMotor.com, Kavak, Popular Pre-owned Cars, OpenSooq, Best Cars, Saud Bahwan Group, OTE Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Used Car Market Trends and Innovations
Condition transparency technologies and regulatory digitization are compressing information asymmetries between buyers and sellers across Oman's used car transaction infrastructure.
Artificial intelligence-powered damage detection is automating chassis and bodywork assessment at inspection centers. Fleet operators and certified pre-owned dealers are deploying these systems to standardize condition grading. This compression of manual evaluation time is automating price discovery and reducing dispute frequency in high-value transactions.
The Ministry of Transport, Communications and Information Technology's updated technical compliance rules mandate digital inspection record retention. This policy shift creates searchable vehicle history databases that reduce adverse selection. Sedan and SUV segments with complex electronic systems are most affected, with dealers investing in compliance infrastructure to maintain certification eligibility.
Buyer preference is rotating toward warranty-backed transactions over informal peer-to-peer deals. Price-benchmarking tools reduce search friction, displacing traditional broker intermediaries. This channel disintermediation is most visible in Muscat Governorate, where digital-native buyers concentrate and dealer accountability commands premium positioning.
Oman Used Car Market Segmentation
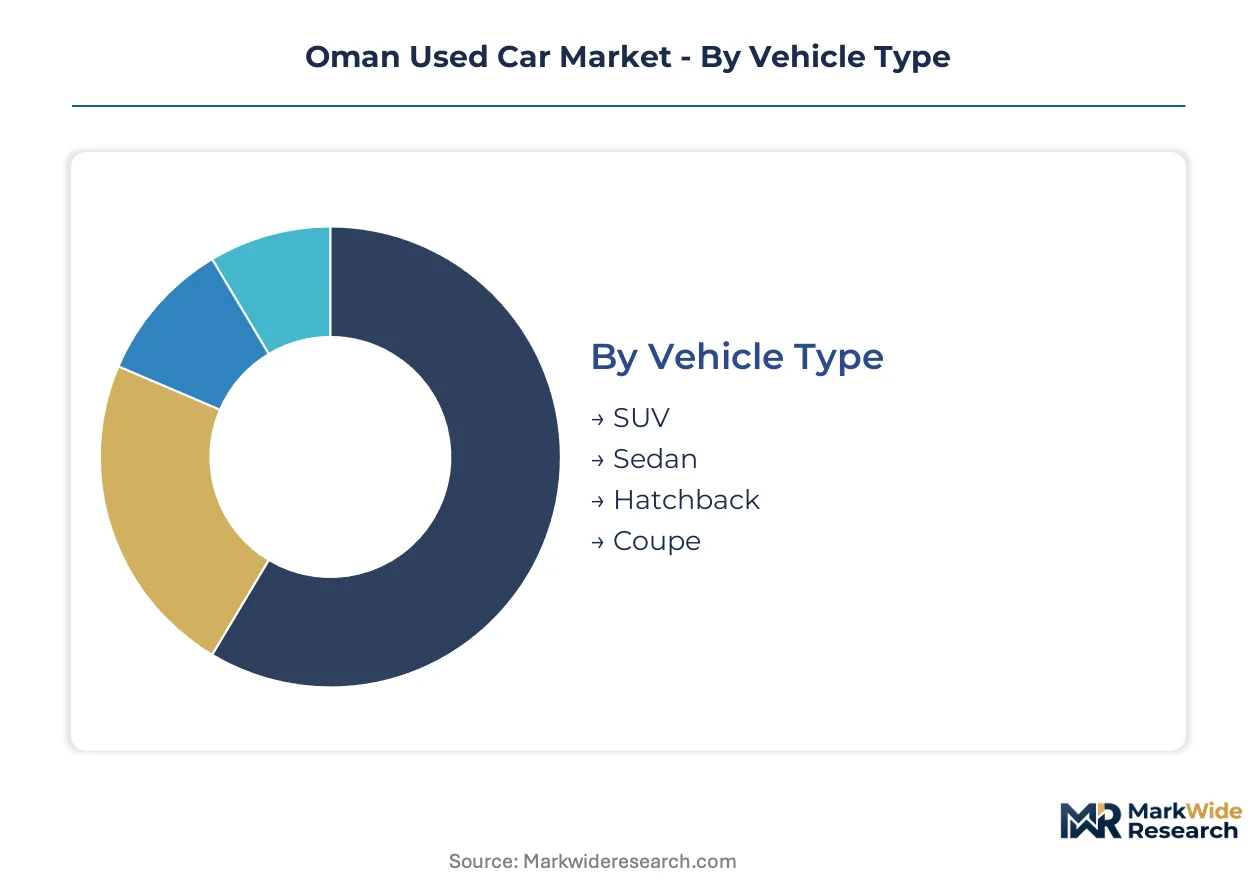
Segmentation in Oman's used car market reflects terrain demands, inspection standards, and financing accessibility that shape buyer trade-offs across vehicle categories. Understanding these partitions reveals where liquidity concentrates and where emerging supply constraints create margin pressure for dealers and fleet operators.
Vehicle Type:
Family size and road conditions drive selection priorities across Oman's governorates, with terrain adaptability commanding premium positioning in secondary transactions.
- SUV:Higher ground clearance and four-wheel-drive configurations dominate inventory turnover in Muscat and interior regions where unpaved access routes remain common. Family buyers prioritize cabin capacity and towing capability for recreational use across the Sultanate's wadi and desert terrain.
- Sedan:Three-box configurations with separate luggage compartments sustain demand among corporate fleet operators and ride-hailing drivers seeking fuel efficiency on paved intercity routes. Urban density in Muscat Governorate supports liquidity for mid-size executive sedans with documented service histories.
- Hatchback:Compact two-box designs with rear cargo access appeal to first-time buyers and single-occupancy commuters in Salalah and smaller urban centers where parking constraints tighten.
- Coupe:Two-door fixed-roof configurations with sport-tuned suspension represent niche liquidity concentrated among enthusiast collectors and expatriate professionals in premium Muscat districts.
Volume sits with SUV; growth tilts toward Sedan as fleet electrification planning begins reshaping procurement specifications.
Condition:
Inspection protocol stringency from the Ministry of Transport, Communications and Information Technology stratifies pricing power and warranty eligibility across the quality spectrum.
- Certified Pre-Owned:Dealer-backed units with extended warranty coverage and multi-point inspection documentation command margin premiums in Muscat's formal retail channels. The Ministry's updated technical compliance rules mandate digital record retention that reinforces buyer confidence in these transactions.
- Good:Operational vehicles with intact chassis integrity and verified odometer readings circulate through established classified platforms where condition transparency tools compress price discovery friction.
- Fair:Higher-mileage inventory with documented repair histories trades in cash-preferred segments where total cost of ownership calculations dominate buyer decision-making.
- Poor:Mechanically compromised units requiring substantial refurbishment face restricted circulation under tightened inspection mandates, compressing supply to informal border-adjacent channels.
Margin concentrates in Certified Pre-Owned; transaction velocity favors Good condition units as digital verification tools expand.
Fuel Type:
Refining infrastructure and technician certification availability constrain powertrain options in Oman's secondary market, preserving incumbent technology dominance.
- Petrol:Spark-ignition engines with established service networks sustain overwhelming liquidity advantages across all vehicle types and price tiers. Automatic transmission pairings with petrol powertrains represent the most fungible asset class for resale velocity.
- Diesel:Compression-ignition configurations with torque advantages for towing and commercial hauling retain niche demand among contractor fleets and rural operators in Dhofar and Al Batinah regions.
- Electric:Battery-electric powertrains with minimal used supply face charging infrastructure gaps and technician certification shortages that suppress secondary market development.
- Hybrid:Dual powertrain systems combining petrol engines with electric motor assist are gaining share fastest among environmentally conscious buyers in Muscat's premium districts, though battery replacement cost uncertainty moderates pricing.
Liquidity anchors in Petrol; technology transition pressure builds in Hybrid as new vehicle sales penetration gradually feeds future supply.
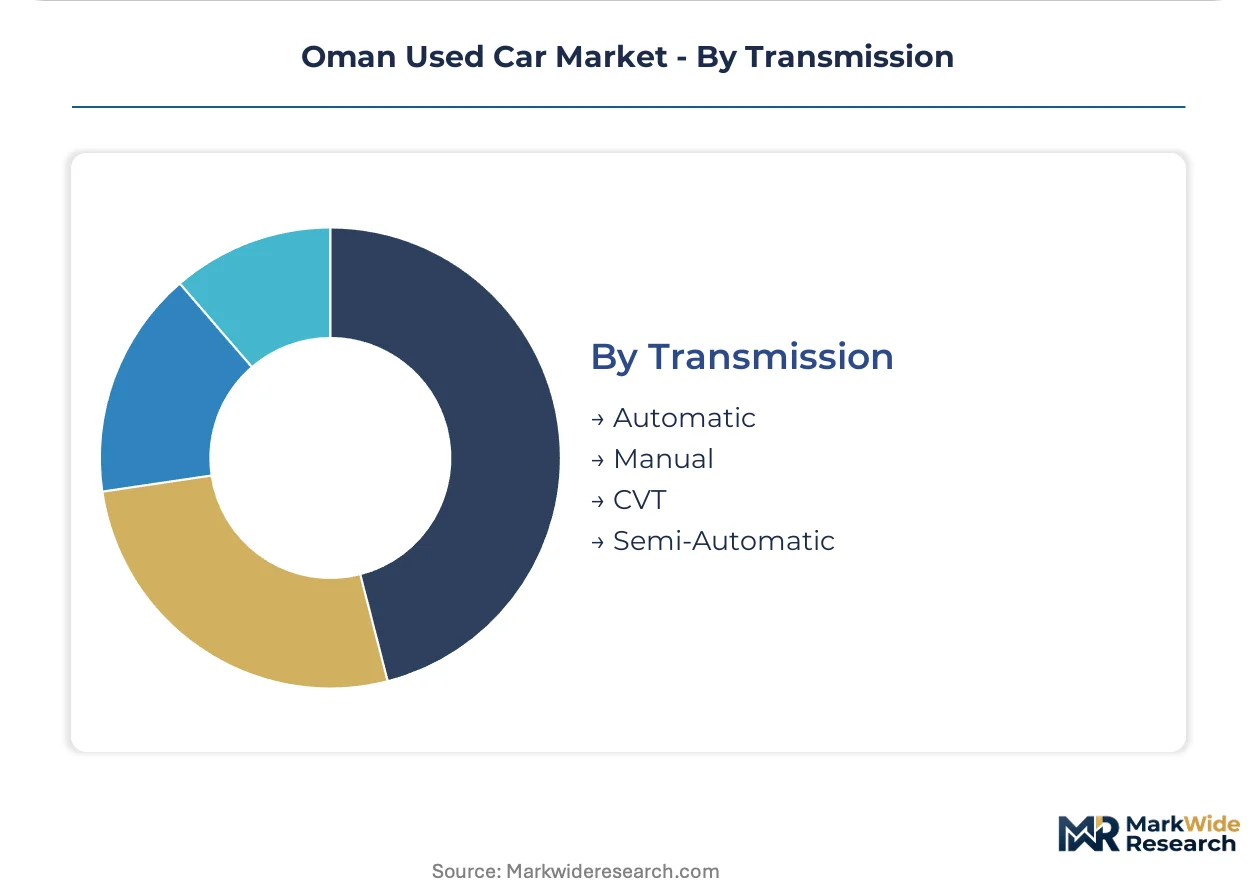
Transmission:
Driver preference and resale risk tolerance segment the gearbox market, with automation commanding premiums in urban congestion and manual retention in cost-sensitive segments.
- Automatic:Torque converter and dual-clutch systems eliminate clutch wear concerns for stop-and-go traffic in Muscat's dense commercial districts. Fleet operators specify automatic exclusively to reduce driver training costs and mechanical abuse exposure.
- Manual:Synchronized gearboxes with clutch pedal operation retain preference in budget tiers and among driving enthusiasts seeking mechanical engagement and lower acquisition cost.
- CVT:Continuously variable ratio systems with belt or chain drive mechanisms penetrate compact segments where fuel economy optimization outweighs traditional driving feel preferences.
- Semi-Automatic:Automated manual transmissions with clutchless shifting represent minimal penetration in Oman's market, constrained by reliability perceptions and limited service expertise.
Automatic commands pricing power; CVT gains traction in fuel economy-sensitive urban buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Secondary vehicle transactions concentrate in Muscat Governorate, where urban density and income distribution sustain premium SUV and sedan liquidity unmatched elsewhere in the Sultanate.
Muscat Governorate
Fleet operators and expatriate professionals drive consistent demand for certified pre-owned SUVs with documented service histories. The Ministry of Transport, Communications and Information Technology enforces digital inspection record retention that elevates buyer confidence in formal retail channels. Al Qurum and Al Khuwair districts host the highest concentration of inspection centers and dealer showrooms.
Dhofar Governorate
Salalah's commercial port activity and cross-border trade with Yemen sustain demand for durable four-wheel-drive vehicles suited to rugged terrain. Updated technical compliance rules from the Ministry filter imported inventory before market entry, compressing supply of non-compliant units. The Salalah Free Zone corridor anchors refurbishment operations serving southern governorates.
Al Batinah Region
Industrial workforce mobility and contractor fleet requirements drive turnover in mid-size sedans and commercial pickups. The central bank's consumer financing guidelines shape hire-purchase accessibility for buyers in this cost-sensitive segment. Sohar port logistics clusters support import processing and pre-sale preparation facilities.
Al Dakhiliyah Governorate
Rural household multi-vehicle ownership patterns sustain demand for affordable hatchbacks and older SUV inventory. Periodic technical inspection mandates filter unsafe vehicles from circulation, redirecting marginal units to informal channels. Nizwa's commercial district serves as the secondary market hub for interior governorate buyers.
Al Sharqiyah Region
Oil and gas sector employment stabilizes demand for premium sedans among professional households in Sur and Ibra. National standards body emission benchmarks impose calibration costs on importers, limiting available supply of compliant European models. The Sur industrial zone anchors fleet servicing infrastructure supporting corporate vehicle rotation cycles.
Oman Used Car Market Competitive Landscape
Physical inspection infrastructure expansion dominates the current landscape as dealers differentiate on condition transparency rather than price alone. The vendor base spans digital-native classified platforms, established dealer groups, and hybrid operators blending physical showrooms with online discovery tools. Three strategic archetypes prevail: inspection-centric certifiers, listing-density aggregators, and manufacturer-affiliated pre-owned channels. Capacity expansion into secondary cities and technology licensing for automated damage detection represent the dominant competitive moves.
Within the inspection-centric tier, Omanicar anchors physical presence through Muscat and Salalah centers that standardize condition grading. Dubizzle Oman and YallaMotor.com exemplify the digital-aggregator archetype, with the former competing through transaction-flow integration and the latter through price-benchmarking specialization. These three operators collectively represent the spectrum of buyer trust mechanisms—physical verification, digital convenience, and data transparency—shaping competitive positioning across the Sultanate's secondary automotive market.
| Leading Market Players |
|---|
| Omanicar |
| Dubizzle Oman |
| YallaMotor.com |
| Kavak |
| Popular Pre-owned Cars |
| OpenSooq |
| Best Cars |
| Saud Bahwan Group |
| OTE Group |
| Others |
Pricing and Supply Chain Analysis
Artificial intelligence-powered damage detection systems are compressing inspection labor costs while concentrating pricing power among inspection-capable dealers across Muscat and Salalah. This technology shift simultaneously reduces per-unit certification overhead and elevates buyer willingness to pay for verified condition transparency in Oman's Ministry of Transport-mandated compliance environment.
Pricing Analysis
Volume concentrates in petrol-powered automatic SUVs trading through informal peer-to-peer channels, while margin pools in certified pre-owned dealer transactions backed by extended warranty coverage. Price differentiation rests on inspection documentation depth and digital record accessibility under updated technical compliance rules from the Ministry of Transport, Communications and Information Technology. Pricing pressure intensifies in fair-condition tiers as tightened inspection mandates filter marginal inventory toward border-adjacent informal markets. Fleet operators exhibit lowest price sensitivity due to total cost of ownership discipline, while first-time hatchback buyers in Salalah and interior governorates drive hardest bargain.
Supply Chain Analysis
Domestic-content rules for inspection center licensing and technician certification are reshaping sourcing toward locally established physical infrastructure operators. Vehicle supply draws from Japan, the United Arab Emirates, and the United States as primary source markets for Oman's import-dependent secondary market. Chassis integrity documentation, odometer verification equipment, and diagnostic tool calibration feed operational dependencies for inspection centers. Single-source vulnerability concentrates in Japanese compact SUV supply channels serving family buyer segments. Distribution runs through hybrid models blending physical showroom verification with digital discovery platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
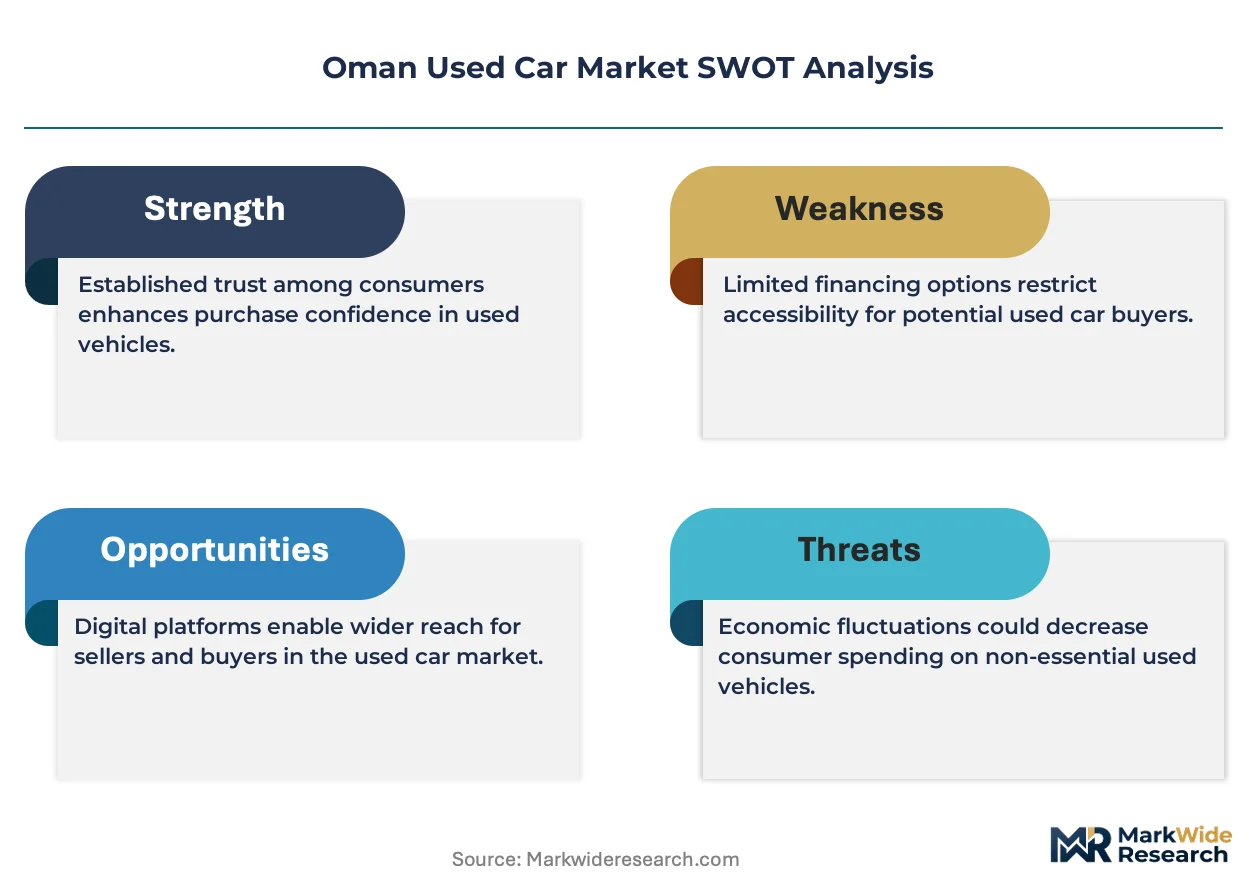
Oman's used car market is consolidating around inspection-capable operators as the Ministry of Transport's digital compliance mandates raise capital barriers for informal sellers. Technical certification requirements and diagnostic equipment capex are forcing weaker players toward exit or acquisition.
For Market Incumbents: Extend physical inspection infrastructure into Salalah and Nizwa corridors before regional competitors establish condition-transparency anchor points. Invest in artificial intelligence-powered damage detection systems to standardize grading velocity and reduce manual evaluation labor costs. Backward integration into refurbishment facilities at Sohar and Salalah Free Zone clusters secures supply pipeline control against import compliance friction. For New Entrants and Emerging Players: Technology-first automated valuation models offer entry wedge into price-benchmarking services currently dominated by established aggregators. Target underpenetrated hybrid powertrain segments in Muscat's premium districts where battery replacement cost uncertainty creates information arbitrage for algorithmic pricing tools. White space exists in technician certification programs addressing future electrified powertrain maintenance skills gaps. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by manufacturer-affiliated pre-owned channels seeking inspection infrastructure scale. Long-term viability favors vertically integrated operators controlling physical verification, digital transaction flow, and after-sales service capacity. Watch electrified powertrain penetration in new vehicle sales as inflection signal for hybrid and battery-electric used supply composition shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Inspection Infrastructure Expansion | Physical center buildout in Salalah and Nizwa captures white-space demand outside Muscat's saturated corridor. |
| AI-Powered Damage Detection Deployment | Automated chassis assessment reduces evaluation time while standardizing condition grades for buyer trust. |
| Digital Payment Integration | Embedded financing and escrow functions capture transaction flow fragmented across informal cash channels. |
| Technician Certification Programs | Electrified powertrain training revenue streams prepare for hybrid and battery-electric secondary circulation. |
| Cross-Border Title Verification System | Blockchain-based chassis documentation authentication accelerates import velocity and reduces dispute frequency. |
Research Methodology
Document review covered customs and trade data, vehicle registration databases, and Ministry of Transport regulatory filings, complemented by interviews with dealership operations managers, fleet procurement directors, classified platform executives, and automotive technician training providers. Secondary validation drew from central bank consumer financing guidelines, national standards body emission benchmarks, and inspection protocol documentation. Bottom-up transaction flow modeling triangulated against top-down market sizing from import volume and fleet rotation cycle analysis.
Output projections span value and volume across vehicle type, condition tier, fuel category, and transmission configuration over the projection horizon. Segmentation modeling incorporated terrain demands, inspection stringency thresholds, and financing accessibility patterns specific to Oman's governorates. CAGRs derived from regression analysis of historical replacement cycle compression, fleet operator procurement discipline, and ride-hailing driver vehicle turnover rates.
Several conditions sit outside the modeled scope, including abrupt shifts in Ministry of Transport inspection enforcement intensity, currency volatility affecting import landed costs, and accelerated electrification policy mandates that could reshape powertrain supply composition. Forecasts reflect documented assumptions regarding fleet operator behavior continuity and central bank financing guideline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Belgium Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
India Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Nigeria Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
United Arab Emirates Used Car Market