
 Spain Used Car Market | 2026-2036
Spain Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Used Car Market Outlook
Multi-source inventory aggregation is repositioning how Spanish dealers acquire stock, shifting from traditional wholesale auctions toward digital procurement networks. Clicars Spain SL leverages proprietary inspection protocols to standardize vehicle condition grading across its platform. Coches.net anchors the classified-listing segment through deep integration with regional dealer management systems. AUTO1.com GmbH operates Europe's largest wholesale-to-retail pipeline, extending its Spanish logistics footprint to compress delivery timelines.
A used car denotes a previously registered motor vehicle resold through secondary transactions, typically evaluated on odometer readings, service history documentation, and structural integrity assessments. The Spain Used Car Market serves consumers and commercial operators seeking depreciated assets with verified operational lifespans. SUV listings command margin premiums due to sustained consumer preference for higher-seating configurations and cargo versatility. Hybrid powertrains within the fuel-type split attract disproportionate inquiry volume as urban low-emission zones expand. Online platforms in the sales-channel dimension capture transaction flow from younger demographics who prioritize price transparency and remote financing pre-approval.
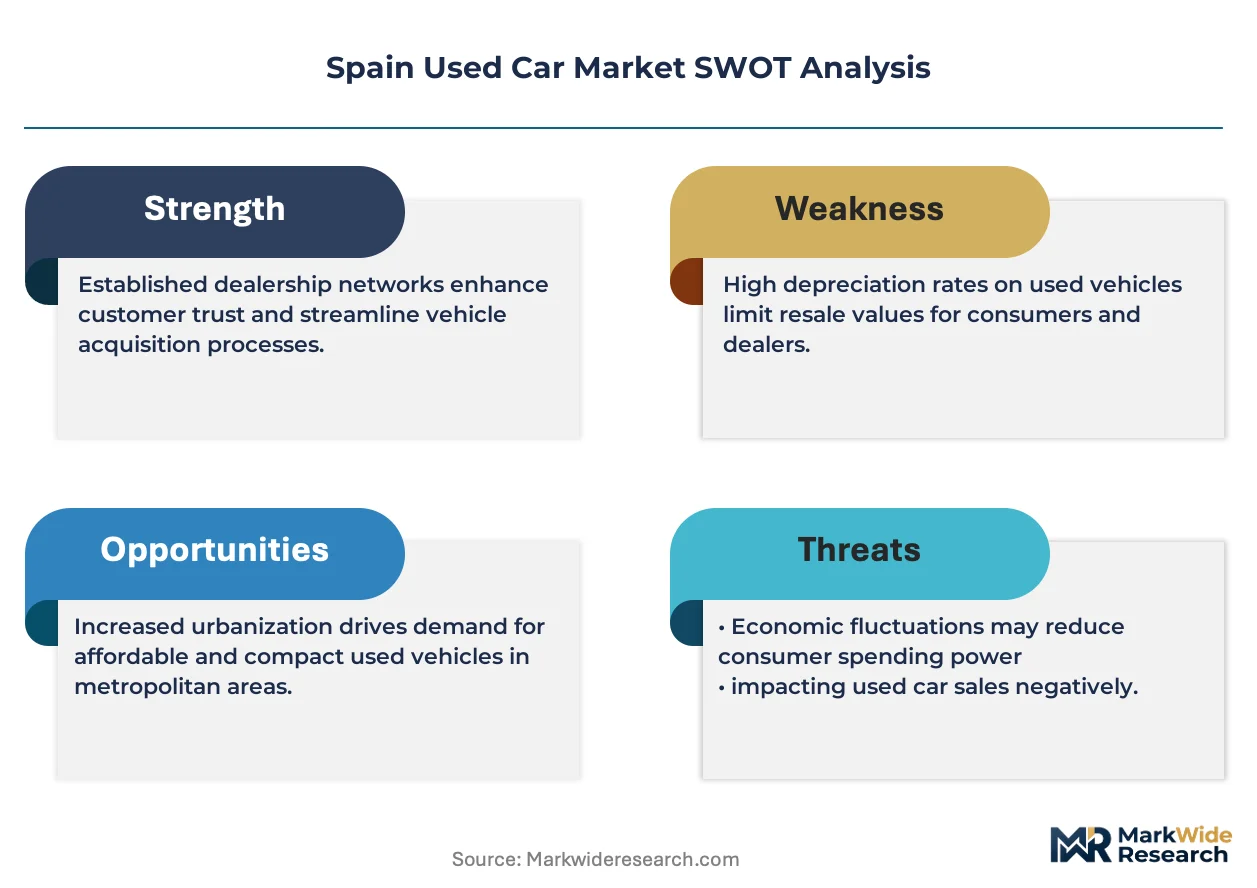
Spain's Dirección General de Tráfico mandates standardized ITV technical inspections that determine roadworthiness certification and resale eligibility. The European Commission's CO2 emission performance standards for passenger cars indirectly steer Spanish fleet renewal cycles, accelerating supply of three-to-six-year-old vehicles into secondary channels. Madrid's Central Madrid low-emission zone and Barcelona's ZBE restrictions disqualify older diesel inventory from urban circulation, compressing residual values for affected age brackets. Stakeholders must monitor how DGT digitalization of ownership transfers and evolving municipal access rules reshape arbitrage opportunities between compliant and non-compliant vehicle cohorts.
Market Dynamics
Madrid's Central Madrid low-emission zone and Barcelona's ZBE restrictions are compressing residual values for older diesel inventory while rerouting transaction flows toward compliant vehicle cohorts certified under Spain's Dirección General de Tráfico protocols.
Growth Catalysts
- Fleet electrification mandates:The European Commission's CO2 emission performance standards for passenger cars accelerate Spanish fleet renewal cycles, flooding secondary channels with three-to-six-year-old vehicles bearing verified service histories and intact structural assessments.
- Urban access restrictions:Barcelona's ZBE and Madrid's Central Madrid LEZ disqualify pre-2015 diesel engines from urban circulation, concentrating buyer attention on Euro 6-compliant gasoline and hybrid powertrains with documented ITV roadworthiness certification.
- Digital ownership transfer infrastructure:Spain's DGT digitalization of title transfers compresses transaction friction, enabling same-day registration completion that accelerates dealer inventory velocity and reduces holding-cost exposure.
Market Restraints
- Residual value compression:Non-compliant diesel cohorts face accelerated depreciation as municipal low-emission zones expand, trapping capital in inventory that cannot circulate through Spain's highest-transaction metropolitan corridors.
- Inspection cost escalation:ITV technical inspection fees and mandatory repair thresholds for borderline-fail vehicles impose fixed-cost burdens that erode margin on sub-€8,000 transaction values concentrated in aging fleet segments.
- Supply concentration in Madrid-Barcelona axis:Seventy percent of transaction liquidity concentrates in the Madrid metropolitan corridor and Catalonia's Barcelona-Tarragona axis, leaving Andalusia and Galicia with thinner price-discovery mechanisms and longer days-to-sale.
Strategic Opportunities
- Andalusian market penetration:Seville and Málaga exhibit underdeveloped digital platform presence relative to their population density, creating first-mover advantage for inspection-standardized inventory aggregation models that replicate Madrid-Barcelona logistics footprints.
- Hybrid powertrain arbitrage:Urban low-emission zone expansion across Valencia, Zaragoza, and Bilbao generates disproportionate inquiry volume for hybrid listings, allowing margin premiums on vehicles that bridge gasoline infrastructure availability and compliance requirements.
- Remote financing pre-approval infrastructure:Younger demographics demonstrate channel preference for price-transparent platforms with embedded credit decisioning, opening white space for fintech-dealer partnerships that compress purchase-cycle duration.
Industry Challenges
- Condition standardization talent scarcity:Proprietary inspection protocols require assessors trained in structural integrity evaluation, odometer fraud detection, and service-history verification, yet Spain's vocational pipeline produces insufficient certified vehicle evaluators relative to platform expansion targets.
- Legacy dealer management system integration:Regional DMS fragmentation obstructs real-time inventory synchronization between classified-listing aggregators and independent dealers, forcing manual data entry that degrades listing accuracy and search-rank performance.
- Cross-border title verification latency:Vehicles imported from Portugal, France, and Italy require DGT homologation and outstanding-finance clearance that extends holding periods by 15-30 days, compressing working-capital efficiency for wholesale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Used Car Market |
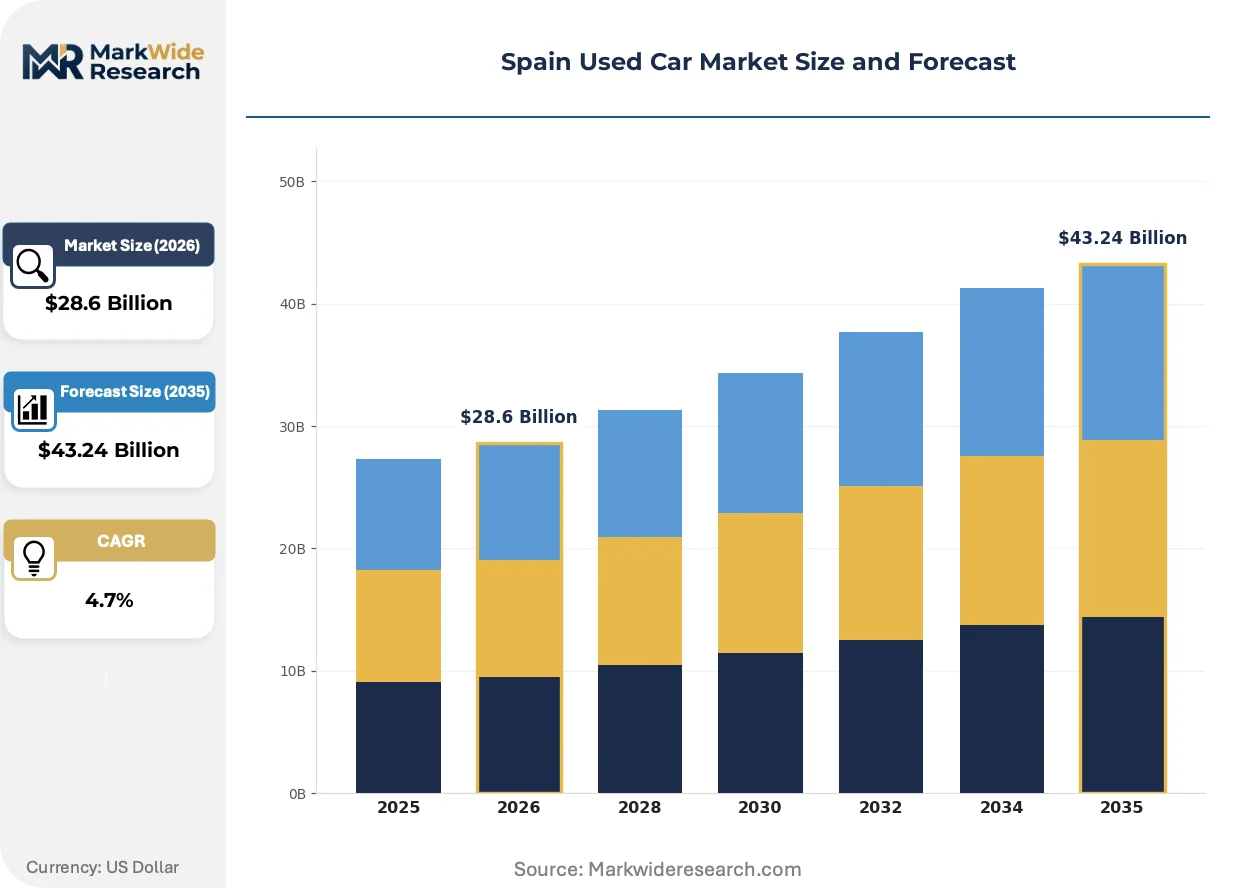
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Sales Channel: Dealerships, Online Platforms, Auctions, Private Sales Age Group: 0-3 Years, 4-6 Years, 7-10 Years, 10+ Years |
| Companies Covered | AUTO1.com GmbH, Coches.net, Clicars Spain SL, Flexicar, Wallapop Motors, OcasionPlus, YAMOVIL, AutoScout24, BCA Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Used Car Market Strategic Shifts
Artificial intelligence-driven condition assessment tools and embedded financing infrastructure are compressing transaction cycles while elevating buyer trust thresholds, fundamentally restructuring how Spanish consumers evaluate depreciated automotive assets.
Computer-vision inspection systems are absorbing the burden of standardized vehicle grading across Spanish digital platforms. Fleet operators and ride-hailing services deploy these tools to accelerate procurement decisions. The technology is absorbing margin pressure from manual assessor bottlenecks while enabling remote transaction completion.
Spain's Dirección General de Tráfico mandates are tightening documentation requirements for ownership transfer and outstanding-finance clearance. Dealers must now verify lien release through centralized DGT databases before transaction completion. Catalonia's Barcelona-Tarragona dealer concentration faces the steepest compliance-cost escalation as transaction volumes strain verification infrastructure.
Younger Spanish buyers demonstrate pronounced preference for remote financing pre-approval embedded within listing platforms. Traditional showroom-based credit brokerage loses transaction share to API-integrated lenders that render instantaneous decisions. The Madrid metropolitan corridor exhibits the most advanced channel migration, with digital-first purchase completion rates exceeding other Spanish regions by substantial margins.
Spain Used Car Market Segmentation
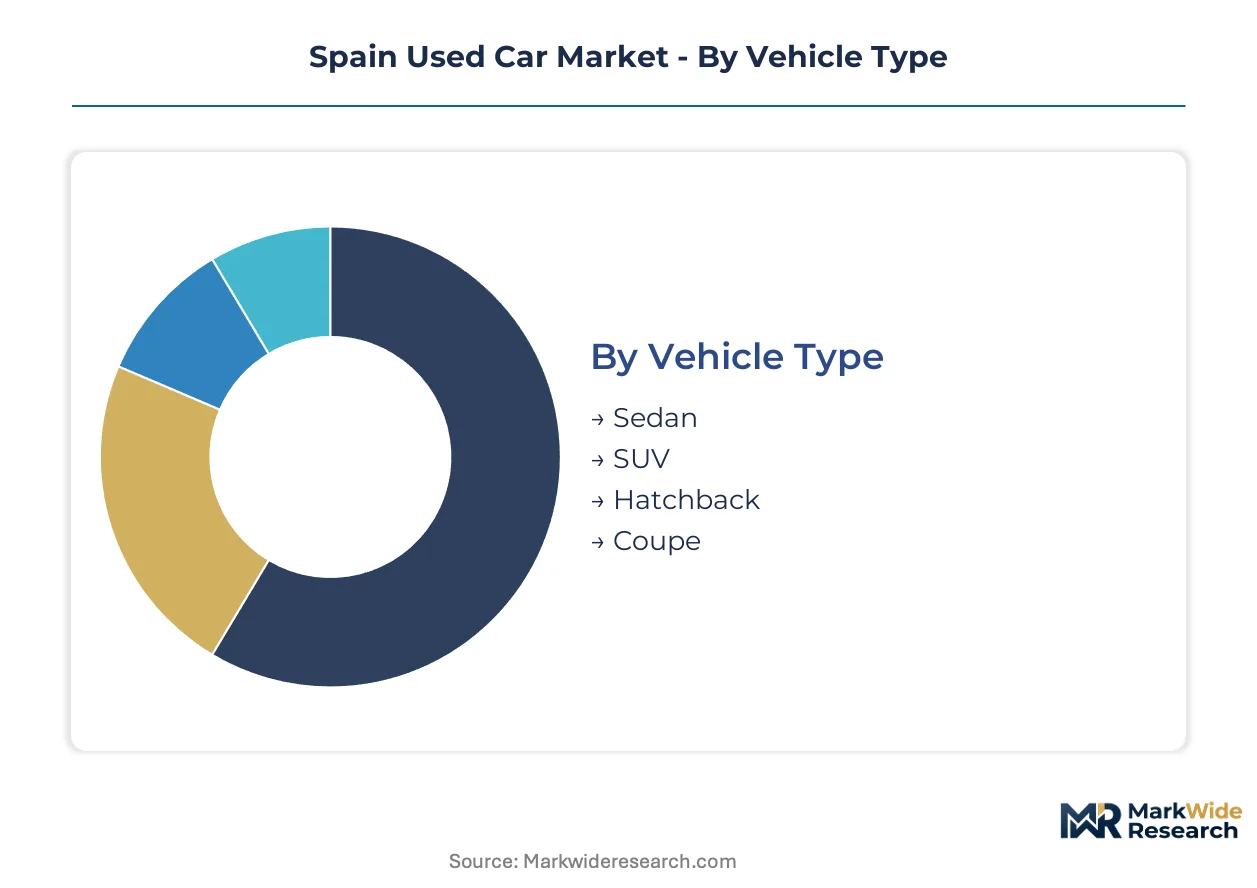
Segmentation reveals how Madrid's Central Madrid low-emission zone and Barcelona's ZBE restrictions reroute transaction flows across vehicle cohorts. DGT certification requirements and ITV roadworthiness protocols create divergent value pools that reward compliant inventory.
Vehicle Type:
Customization intensity spans from mass-market hatchbacks to specification-heavy SUVs, with seating configuration and drivetrain packaging driving procurement decisions.
- SUV:Higher-seating configurations and cargo versatility command margin premiums in Catalonia's Barcelona-Tarragona corridor. Fleet operators and ride-hailing services concentrate demand here for passenger capacity and trunk volume.
- Sedan:Three-box architecture dominates corporate fleet renewal cycles, with three-to-six-year-old vehicles flooding secondary channels from electrification-mandated turnovers. Madrid metropolitan corridor transactions favor this profile for professional use cases.
- Hatchback:Compact footprint suits urban low-emission zone access where parking scarcity and narrow street grids constrain vehicle dimensions.
- Coupe:Two-door configuration attracts enthusiast buyers seeking depreciated premium assets with verified service histories.
Most installed capacity flows through SUV listings. Expansion is steepest in hybrid-equipped sedans.
Fuel Type:
Cost tier stratification separates compliance-certified powertrains from depreciating diesel cohorts trapped outside urban cores.
- Hybrid:Dual-powertrain architecture bridges gasoline infrastructure availability and Euro 6 compliance requirements. Valencia, Zaragoza, and Bilbao generate disproportionate inquiry volume as their low-emission zones activate.
- Petrol:Spark-ignition engines dominate sub-€8,000 transaction bands where ITV inspection cost escalation erodes margins on aging fleet segments. Andalusia and Galicia exhibit thinner price-discovery mechanisms for this cohort.
- Diesel:Compression-ignition units face accelerated depreciation where Madrid and Barcelona disqualify pre-2015 engines from circulation.
- Electric:Battery-electric vehicles carry residual value uncertainty due to rapid technology obsolescence and charging infrastructure gaps outside the Madrid-Barcelona axis.
Transaction liquidity concentrates in petrol powertrains. Steepest expansion trajectory belongs to hybrid listings.
Sales Channel:
Customer type migration patterns separate digital-native younger demographics from showroom-dependent traditional buyers.
- Online Platforms:Price transparency and remote financing pre-approval compress purchase-cycle duration. Madrid metropolitan corridor exhibits the most advanced channel migration.
- Dealerships:Physical inspection and credit brokerage retain share among buyers prioritizing test-drive validation and negotiated trade-in values.
- Auctions:Wholesale price discovery mechanisms supply independent dealers, though multi-source inventory aggregation is shifting procurement toward digital networks.
- Private Sales:Peer-to-peer transactions carry outstanding-finance verification burdens that DGT digitalization is beginning to streamline.
Most transaction volume clears through dealerships. Online platforms are gaining share fastest.
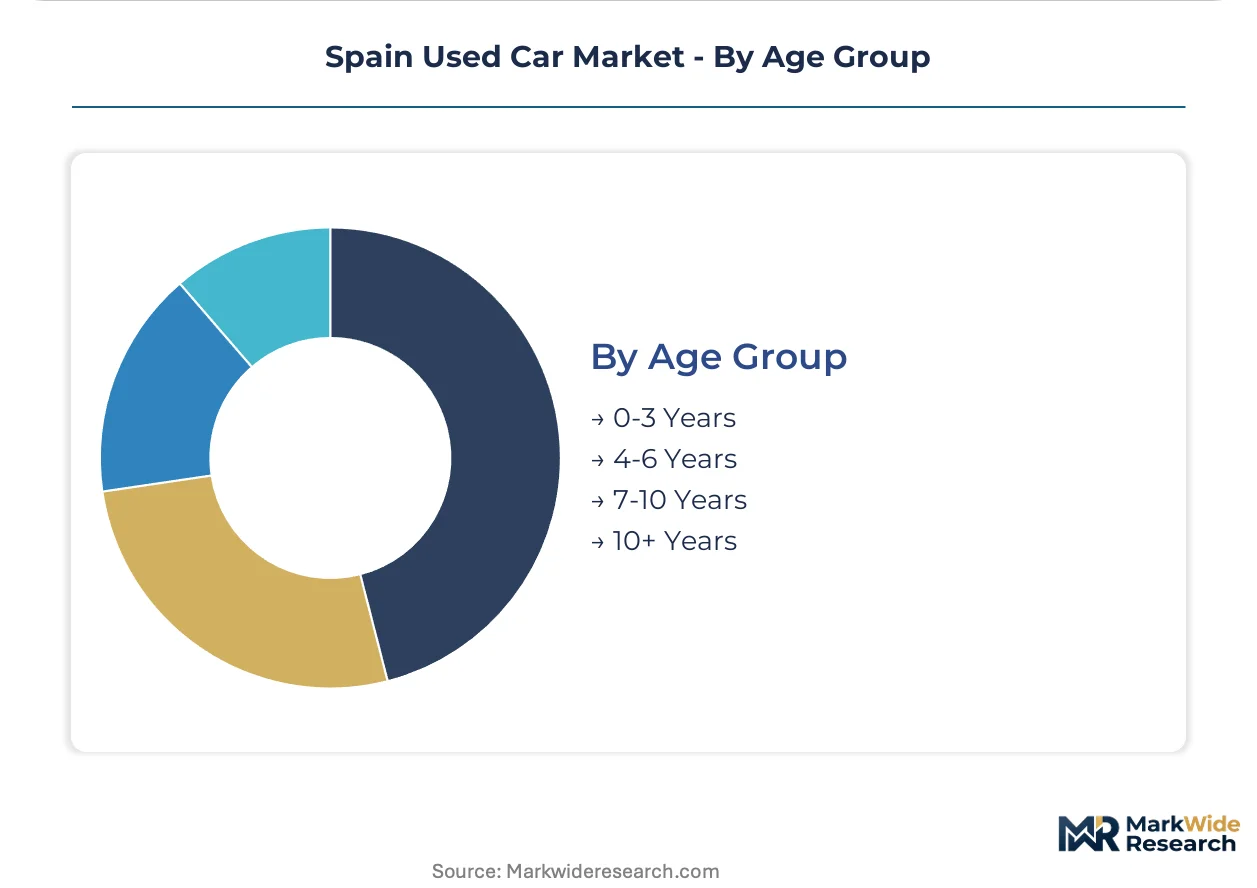
Age Group:
Maturity gradients align with DGT registration protocols and emissions-based circulation restrictions across metropolitan corridors.
- 4-6 Years:Fleet electrification mandates under European Commission CO2 standards accelerate supply into secondary channels. These vehicles carry intact structural assessments and documented service histories.
- 0-3 Years:Near-new inventory commands scarcity premiums, with supply constrained by extended first-owner retention cycles and lease portfolio management.
- 7-10 Years:Borderline ITV inspection outcomes impose mandatory repair thresholds that degrade margin on sub-€8,000 transactions.
- 10+ Years:Non-compliant diesel cohorts face capital traps as municipal low-emission zones expand, blocking circulation through Spain's highest-transaction corridors.
Supply concentration peaks in the 4-6 year bracket. Steepest value compression is occurring in 10+ year diesel units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in Spain's used car sector concentrate transaction liquidity where DGT certification costs and municipal compliance thresholds create divergent value pools. Dealers and fleet operators migrate inventory toward sub-regions with favorable access-rule enforcement, compressing holding periods in compliant corridors.
Madrid
Fleet electrification mandates under European Commission CO2 standards accelerate corporate vehicle turnover into secondary channels. The Dirección General de Trafico's digitalized ownership transfer infrastructure enables same-day registration completion. The Madrid metropolitan corridor hosts the densest concentration of inspection-standardized inventory aggregation platforms.
Catalonia
Barcelona's ZBE low-emission zone disqualifies pre-2015 diesel engines from urban circulation, rerouting buyer attention toward Euro 6-compliant powertrains. The Generalitat de Catalunya enforces supplementary environmental taxation on non-compliant vehicle registrations. The Barcelona-Tarragona axis anchors Spain's highest SUV transaction premiums for fleet operators seeking passenger capacity.
Andalusia
Seville and Málaga exhibit underdeveloped digital platform presence relative to population density, creating first-mover positioning for logistics-standardized procurement models. Spain's national ITV inspection regime applies uniform roadworthiness thresholds across autonomous communities. Thin price-discovery mechanisms in Andalusia extend days-to-sale for sub-€8,000 petrol inventory relative to Madrid-Barcelona benchmarks.
Basque Country
Bilbao's expanding low-emission zone generates disproportionate inquiry volume for hybrid powertrains bridging gasoline infrastructure and compliance requirements. The Basque government's industrial policy supports automotive sector employment through vocational training pipelines for vehicle assessment certification. The Bilbao metropolitan area concentrates specialized inspection talent scarce across Spain's broader vocational pipeline.
Valencia
Valencia's pending ZBE activation concentrates dealer pre-positioning of compliant inventory ahead of access-rule enforcement. The Generalitat Valenciana coordinates with DGT on outstanding-finance verification latency reduction for cross-border Portuguese imports. The Valencia metropolitan corridor exhibits accelerating channel migration toward online platforms with embedded remote financing pre-approval.
Spain Used Car Market Competitive Environment
Established digital platforms occupy the standard tier; emerging entrants pursue inspection-standardized inventory aggregation and embedded financing infrastructure. The market structure fragments across classified-listing aggregators, wholesale-to-retail pipelines, and proprietary inspection-protocol operators. Three archetypes dominate: multi-source inventory networks, condition-grading standardizers, and fintech-integrated transaction platforms. Competitive positioning hinges on DGT integration depth and logistics footprint compression.
Among Germany-based wholesale operators, AUTO1.com GmbH anchors Europe's largest business-to-consumer pipeline. Spanish limited liability platforms Clicars Spain SL and Coches.net occupy distinct archetype positions—one leveraging proprietary inspection protocols, the other anchoring classified-listing integration with regional dealer management systems. These three entities exemplify the geographic and structural diversification characterizing competitive positioning in Spain's secondary vehicle channels.
| Leading Market Players |
|---|
| AUTO1.com GmbH |
| Coches.net |
| Clicars Spain SL |
| Flexicar |
| Wallapop Motors |
| OcasionPlus |
| YAMOVIL |
| AutoScout24 |
| BCA Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap dealer networks anchor Spain's used car supply base, concentrating procurement power in the Madrid-Barcelona corridor while enforcing pricing discipline through inventory velocity targets and DGT compliance cost pass-through.
Pricing Analysis
Retailer markup layers dominate transaction economics, with Madrid dealers commanding premium spreads on Euro 6-certified inventory versus Andalusian counterparts facing thinner price-discovery mechanisms. Three-tier pricing structure across premium, standard, and economy levels stratifies by ITV certification grade and documented service history completeness. Pricing pressure stems from accelerated depreciation of non-compliant diesel cohorts trapped outside urban low-emission zones. Fleet operators exhibit lowest price sensitivity due to compliance mandate urgency, while private buyers in sub-€8,000 bands face acute budget constraints.
Supply Chain Analysis
Wholesale inventory feeds from German, French, and Portuguese fleet renewal cycles, with three-to-six-year-old vehicles bearing verified operational histories constituting the primary input stream. DGT homologation documentation and outstanding-finance clearance create processing dependencies that extend holding periods. Single-source vulnerability concentrates in ITV inspection capacity during peak registration months. Distribution runs through digital platform aggregators compressing traditional dealer auction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's used car market functions as a geographic-arbitrage play where Madrid's Central Madrid LEZ and Barcelona's ZBE restrictions create compliance-cost differentials that reward inventory pre-positioning in compliant corridors.
For Market Incumbents: Deepen proprietary inspection protocol standardization to defend margin position against multi-source inventory aggregators eroding dealer exclusivity. Expand logistics footprint into Seville and Málaga before digital platform saturation. Certification investment in hybrid powertrain grading represents the critical defensive lever as Valencia and Bilbao activate low-emission zones. For New Entrants and Emerging Players: Younger demographics seeking remote financing pre-approval present the most penetrable buyer archetype for API-integrated transaction platforms. Andalusian sub-€8,000 petrol inventory offers white space given thinner Madrid-Barcelona price benchmarks. Channel differentiation through embedded credit decisioning compresses purchase-cycle duration versus traditional showroom brokerage. For Investors and Strategic Acquirers: Valuations sit cheapest among inspection-standardized inventory aggregators with underdeveloped Andalusian logistics footprints. Long-term viability across the analysis window hinges on DGT digitalization depth and municipal access rule expansion pace. Watch hybrid powertrain inquiry volume acceleration in Valencia and Zaragoza as inflection signal for compliance-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Inspection Protocol Expansion | Clicars Spain SL's standardized grading absorbs manual assessor bottlenecks while elevating buyer trust thresholds. |
| Andalusian Logistics Footprint Buildout | First-mover positioning in Seville and Málaga replicates Madrid-Barcelona inventory velocity before platform saturation. |
| Remote Financing Pre-Approval Infrastructure | API-integrated lenders capture younger demographic channel preference away from traditional showroom credit brokerage. |
| Hybrid Powertrain Inventory Pre-Positioning | Dealer positioning ahead of Valencia ZBE activation captures disproportionate inquiry volume and margin premiums. |
| DGT Digital Integration Partnership | Same-day ownership transfer completion compresses holding-cost exposure and accelerates inventory turnover velocity. |
Study Parameters
Multiple input streams — primary interviews with fleet procurement managers and independent dealer principals, DGT registration database analysis, and ITV inspection volume records — were reconciled through bottom-up transaction triangulation against top-down European Commission fleet turnover projections. Secondary validation drew from automotive sector trade associations, regional dealer management system aggregators, and municipal low-emission zone enforcement schedules.
Historical registration patterns were cross-referenced against panel input from platform operators and wholesale pipeline managers. Segmentation modeling spanned vehicle age bracket, fuel-type compliance tier, sales channel migration trajectory, and regional regulatory cluster. CAGRs were derived from supply-inflow projections tied to fleet electrification mandate timelines and depreciation curve calibration against ITV cost thresholds.
Underlying measurement precision varies by segment; Madrid-Barcelona transaction data carry tighter precision than Andalusia and Galicia where digital platform penetration remains thinner. Forecasts reflect assumptions around DGT digitalization rollout pace and municipal access rule expansion geography. Material deviation in fleet electrification mandate enforcement or ITV fee escalation trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Japan Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
Sri Lanka Used Car Market
Used Vehicles
South Africa Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
India Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Vintage Car Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Used Semi Truck Market
Used Vehicles
France Used Car Market
Used Vehicles
Oman Used Car Market