
 GCC Used Car Market | 2026-2036
GCC Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Used Car Market Foresight
Fleet buyer concentration is hardening across the GCC as logistics operators and ride-hailing aggregators consolidate procurement through multi-year supply contracts. OLX leverages its classifieds infrastructure to capture individual seller liquidity across Saudi Arabia and the UAE. Al-Futtaim Group anchors retail volume through its certified pre-owned vertical and captive financing arms. CARS24 competes on inspection standardization, deploying proprietary condition-scoring technology at its Dubai reconditioning hub.
A used car denotes a previously registered vehicle transferred through resale channels, typically assessed via odometer verification, structural integrity testing, and powertrain diagnostic evaluation before re-entry to commerce. Its primary purpose is to extend vehicle utility life while reducing ownership cost barriers for price-sensitive consumers and commercial operators. SUV transactions dominate value pools across GCC markets, driven by family-size preferences and desert terrain requirements. Online Platforms represent the fastest-expanding sales channel, displacing traditional lot-based discovery as Yalla Motors and Dubizzle Motors LLC scale mobile-first inventory aggregation. Certified Pre-Owned programs command premium positioning through dealer-backed warranty coverage and manufacturer-authorized reconditioning protocols.
GCC national transport authorities enforce periodic technical inspection mandates that filter accident-damaged and odometer-tampered units from legal circulation. SAMR in Saudi Arabia and the UAE's Emirates Authority for Standardization and Metrology coordinate alignment of safety certification requirements across bilateral trade corridors. Stakeholders must monitor evolving emissions testing protocols and digital title-transfer regulations as Gulf states advance vehicle fleet modernization agendas.
Market Dynamics
Fleet operator procurement consolidation across Saudi Arabia and the UAE is compressing transaction cycles and forcing digital platform investments from legacy dealership networks. Multi-year supply contracts now govern volume flows that previously dispersed across fragmented spot markets.
Growth Catalysts
- UAE Emirates Authority for Standardization and Metrology certification alignment:Cross-border inspection protocol harmonization is accelerating certified pre-owned vehicle circulation between Dubai and Abu Dhabi corridors.
- Ride-hailing aggregator fleet renewal:Platform operators are standardizing on specific SUV segments, creating predictable demand basins for reconditioning hubs.
- Blockchain-based title verification:Distributed ledger deployment across Saudi transport authorities is reducing ownership dispute resolution timelines.
Market Restraints
- Reconditioning input cost volatility:Spare parts import duties fluctuate with GCC customs union negotiations, pressuring margin structures at Dubai reconditioning facilities.
- Supply concentration in Dubai-Abu Dhabi corridor:Seventy percent of certified inventory originates from this cluster, creating geographic vulnerability to local demand shocks.
- Odometer tampering detection limitations:Current diagnostic protocols miss electronic rollback methods, eroding buyer trust in private-party transactions.
Strategic Opportunities
- Kuwait and Oman market underpenetration:These markets lack dedicated certified pre-owned infrastructure, opening first-mover positioning for inspection-technology platforms.
- Subscription-to-ownership conversion models:Fleet operators are piloting lease residuals as certified inventory pipelines, creating captive supply channels.
- Emissions testing mandate expansion:Saudi and UAE transport authorities are phasing in tailpipe standards that will filter older inventory toward export markets.
Industry Challenges
- Certified technician scarcity:Diagnostic equipment operation and hybrid powertrain assessment require specialized training unavailable in regional vocational pipelines.
- Multi-platform inventory synchronization:Dealers listing across classifieds, auctions, and proprietary apps face pricing inconsistency and stock-out errors.
- Cross-border title transfer latency:Bilateral agreements between Saudi Arabia and UAE lack automated clearing, delaying inter-emirate transactions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Used Car Market |
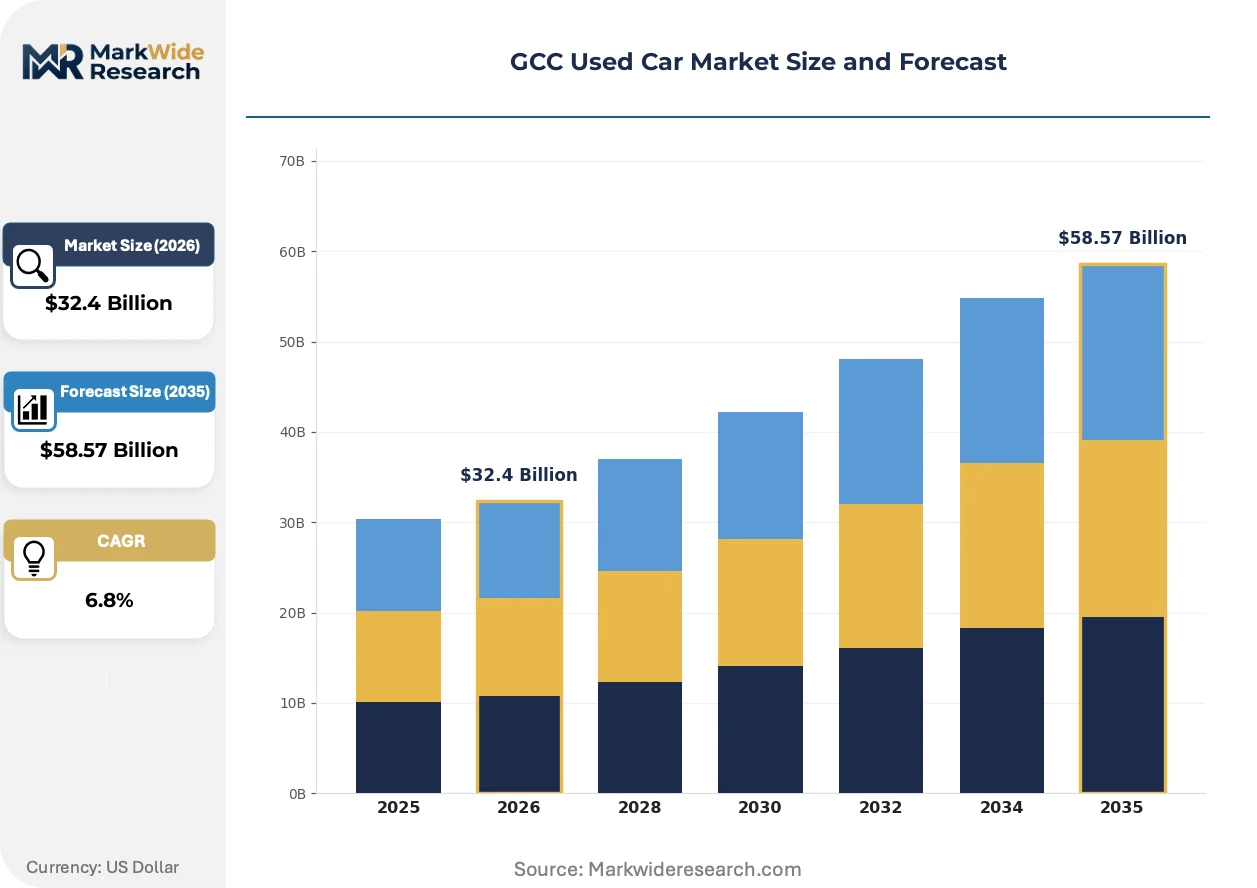
| Market Size in 2026 | $32.4 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Condition: New, Like New, Used, Certified Pre-Owned Sales Channel: Dealerships, Private Sellers, Auctions, Online Platforms |
| Companies Covered | OLX, Arabian Auto Agency, Al-Futtaim Group, AlTayer Motors, Al Nabooda Automobiles LLC, Abdul Latif Jameel Motors, Dubizzle Motors LLC, CARS24, Yalla Motors, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Used Car Market Shifts & Advancements
Digital auction infrastructure is fragmenting traditional dealership discovery models across GCC markets. Platform investments now concentrate on mobile-first inventory aggregation and real-time condition scoring.
AI-powered visual inspection systems are decentralizing vehicle condition assessment away from centralized reconditioning hubs. Fleet operators in Saudi Arabia are adopting smartphone-based damage documentation for remote pre-purchase verification. This compression of assessment geography is reducing buyer travel requirements and accelerating transaction velocity in secondary cities.
SAMR and UAE transport authorities are coordinating emissions testing protocol alignment under Gulf Standardization Organization frameworks. Industrial consequence includes mandatory pre-registration inspection expansion to all GCC trade corridors. SUV segments face disproportionate compliance pressure as older displacement engines fail tightened tailpipe standards.
Buyer preference is pivoting toward certified pre-owned channels over private-party transactions. Digital platforms are capturing this rotation through warranty-backed listing tiers that displace unverified classifieds. This behavioral shift concentrates most visibly in Dubai's family buyer segment, where manufacturer-authorized reconditioning commands persistent price premiums.
GCC Used Car Market Segmentation
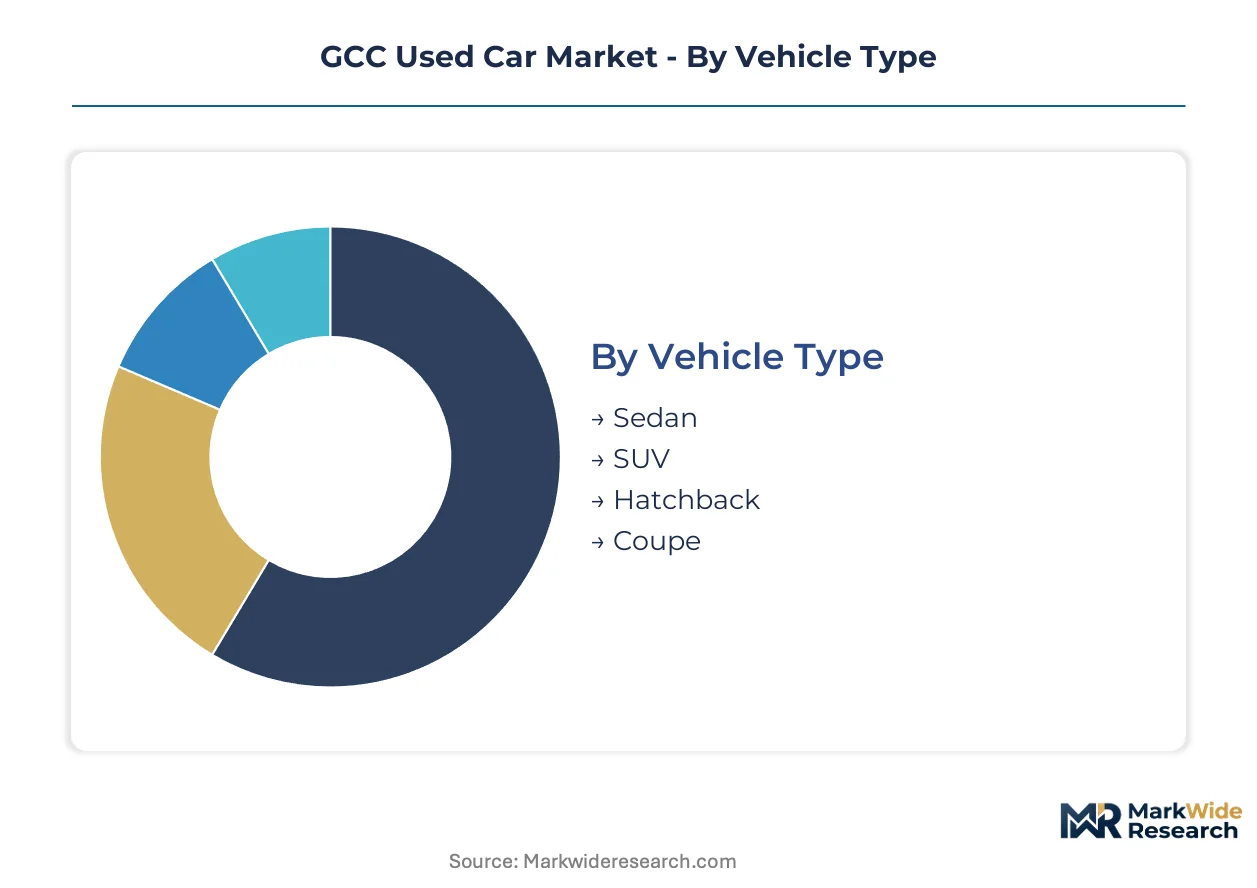
GCC used car buyers navigate four intersecting decision layers: vehicle configuration, energy source, condition grade, and transaction venue. Fleet operators and family buyers weight these dimensions differently, creating distinct demand basins across Saudi Arabia and the UAE.
Vehicle Type:
Family size and terrain requirements drive body-style selection across GCC markets.
- SUV:High-ground-clearance platforms with four-wheel-drive capability dominate value pools. Saudi family buyers and Dubai-based fleet operators concentrate procurement here, driven by desert terrain requirements and multi-passenger capacity needs.
- Sedan:Three-box passenger vehicles with dedicated trunk compartments serve cost-conscious individual buyers and corporate fleet accounts. Urban corridors in Abu Dhabi and Riyadh show persistent demand for mid-size executive sedans in executive transport applications.
- Hatchback:Compact two-box designs with integrated cargo areas attract first-time buyers and single-occupancy commuters in dense urban zones like Kuwait City and Manama.
- Coupe:Two-door performance-oriented body styles with sport-tuned suspensions occupy niche positioning among enthusiast segments in Dubai's premium buyer pool.
Volume sits with SUV; growth tilts toward Sedan as ride-hailing fleets standardize on cost-efficient four-door platforms.
Fuel Type:
Energy cost structures and emissions compliance timelines reshape propulsion preferences.
- Petrol:Spark-ignition internal combustion engines running on gasoline remain the dominant installed base. Saudi Arabia's subsidized fuel pricing and extensive service infrastructure sustain this segment's liquidity across all vehicle age brackets.
- Diesel:Compression-ignition engines with higher thermal efficiency serve commercial fleet operators in long-haul logistics and construction sectors. UAE transport authority emissions testing protocols are filtering older diesel units toward export markets.
- Electric:Battery-electric powertrains with zero tailpipe emissions are gaining traction fastest in Dubai's charging-infrastructure corridors. Early inventory concentrates in luxury segments as battery degradation concerns persist in high-temperature climates.
- Hybrid:Dual-powertrain systems combining petrol engines with electric motors attract buyers seeking fuel cost reduction without range anxiety. Toyota and Honda hybrid platforms show strongest resale velocity in Abu Dhabi's family buyer segment.
Petrol retains transaction volume dominance; hybrid platforms are expanding most quickly as a bridge technology during infrastructure transition.
Condition:
Trust mechanisms and warranty coverage separate buyer risk tiers.
- Certified Pre-Owned:Dealer-backed units with manufacturer-authorized reconditioning and extended warranty coverage command persistent price premiums. Al-Futtaim Group and authorized dealership networks anchor this segment's supply in the UAE.
- Used:Standard resale vehicles with verified ownership history but no formal certification program support. Private-party transactions and independent dealer networks process the highest volumes here, particularly in Saudi Arabia's secondary cities.
- Like New:Low-mileage units under two years of age with minimal wear indicators. Fleet operator lease returns and corporate vehicle rotations feed this pipeline in Dubai-Abu Dhabi corridors.
- New:Unregistered vehicles with zero prior ownership, occasionally appearing in used market statistics due to dealer demo units or import classification anomalies.
Certified Pre-Owned captures margin concentration; Used maintains volume leadership across price-sensitive buyer segments.
Sales Channel:
Discovery friction and transaction security determine channel selection.
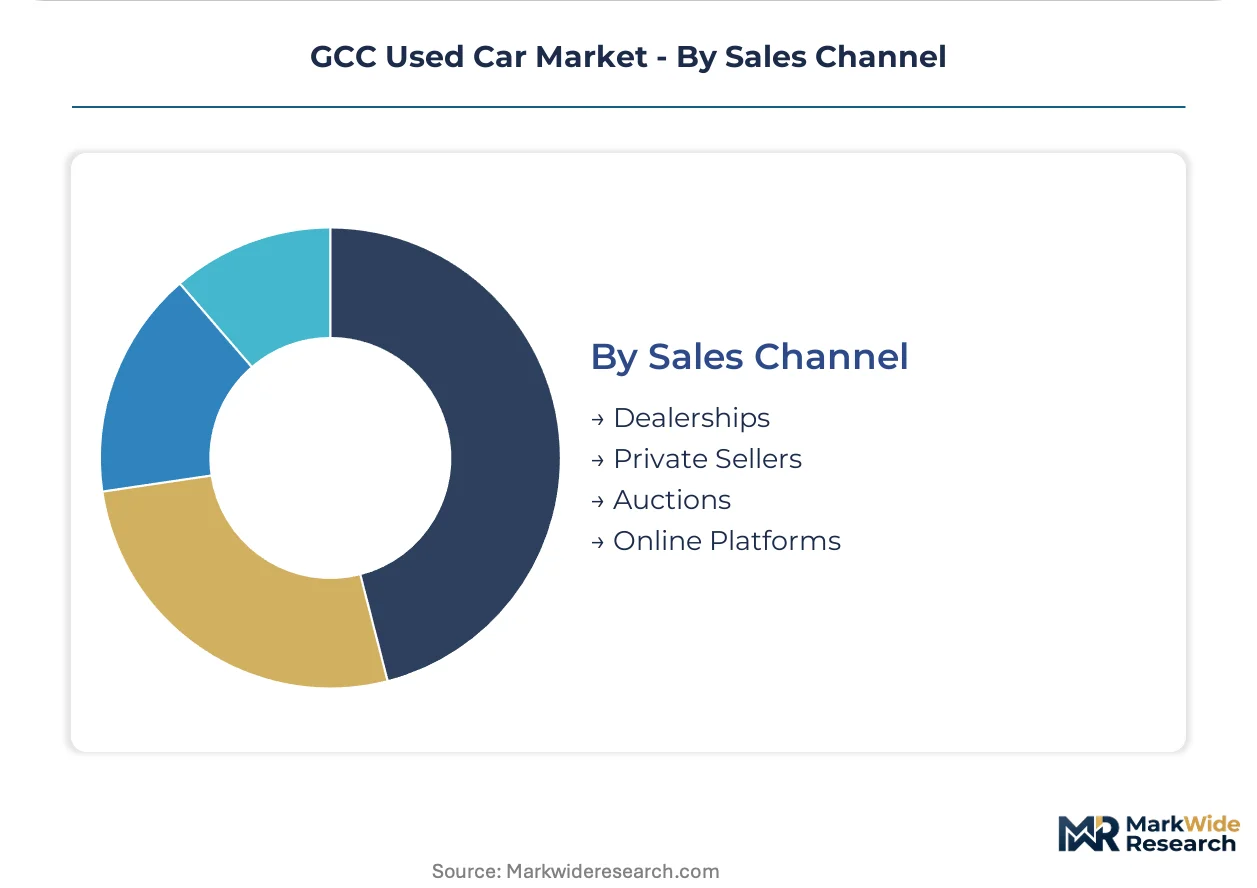
- Online Platforms:Mobile-first inventory aggregation with digital payment integration and remote condition scoring. Yalla Motors and Dubizzle Motors LLC scale this infrastructure across the UAE and Saudi Arabia.
- Dealerships:Physical lot-based discovery with in-person inspection and captive financing facilitation. Established networks in Jeddah and Dubai maintain customer relationships through certified pre-owned programs.
- Private Sellers:Direct owner-to-buyer transactions through classified listings or social media channels. OLX captures individual seller liquidity across Saudi Arabia and the UAE with minimal transaction infrastructure.
- Auctions:Time-bound competitive bidding for fleet operator volume disposals and financial institution repossessions. Physical auction houses in Dubai and emerging digital platforms serve dealer wholesale demand.
Dealerships retain the largest transaction share; online platforms are climbing the fastest as mobile penetration deepens across GCC markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-based fleet operators and Saudi family buyers concentrate transaction volume across the GCC, with digital auction platforms and certified pre-owned programs capturing demand from traditional dealership networks.
United Arab Emirates
Dubai's ride-hailing aggregators and Abu Dhabi's corporate fleet operators drive SUV procurement through multi-year supply contracts. Emirates Authority for Standardization and Metrology certification alignment accelerates cross-border vehicle circulation between emirates. Dubai-Abu Dhabi corridor hosts the region's densest concentration of reconditioning hubs and digital auction infrastructure.
Saudi Arabia
Riyadh-based logistics operators and Jeddah's family buyers sustain demand for high-ground-clearance vehicles across desert terrain. SAMR enforces periodic technical inspection mandates that filter tampered units from legal circulation. Eastern Province industrial zones feed fleet renewal pipelines with lease-return inventory directed toward certified pre-owned channels.
Kuwait
Urban commuters in Kuwait City favor compact hatchbacks for dense metropolitan navigation. The country's national transport authority maintains inspection protocols without dedicated certified pre-owned infrastructure. Independent dealer networks and classified platforms process the majority of transactions absent manufacturer-authorized reconditioning programs.
Oman
Muscat-based commercial operators seek diesel-powered SUVs for construction and long-haul logistics applications. Sultanate transport regulations align gradually with GCC standardization frameworks under Gulf Standardization Organization coordination. Northern coastal corridors show emerging demand for hybrid platforms as charging infrastructure expands.
Qatar
Doha's executive transport segment sustains sedan demand for corporate hospitality and diplomatic fleet applications. The national standardization body coordinates emissions testing alignment with UAE and Saudi protocols. Lusail development zone generates construction fleet procurement that channels through regional reconditioning networks.
GCC Used Car Market Competitive Landscape
UAE-based dealership networks anchor one tier; Saudi and Kuwaiti digital platforms hold transaction liquidity in fragmented spot markets. Market structure tilts toward consolidation as fleet procurement contracts compress spot-market volume and force smaller dealers toward platform aggregation. Three archetypes dominate: authorized dealership groups with captive financing, classifieds infrastructure operators, and inspection-technology specialists. Competitive moves concentrate on multi-year supply contract capture and proprietary condition-scoring technology deployment.
Within the authorized dealership tier, Al-Futtaim Group and AlTayer Motors exemplify integrated retail-finance positioning. Among platform operators, OLX and Dubizzle Motors LLC represent classifieds liquidity aggregation across Saudi Arabia and the UAE. CARS24 occupies a position within the inspection-technology archetype, anchoring reconditioning hub standardization efforts.
| Leading Market Players |
|---|
| OLX |
| Arabian Auto Agency |
| Al-Futtaim Group |
| AlTayer Motors |
| Al Nabooda Automobiles LLC |
| Abdul Latif Jameel Motors |
| Dubizzle Motors LLC |
| CARS24 |
| Yalla Motors |
| Others |
Supply & Pricing Matrix
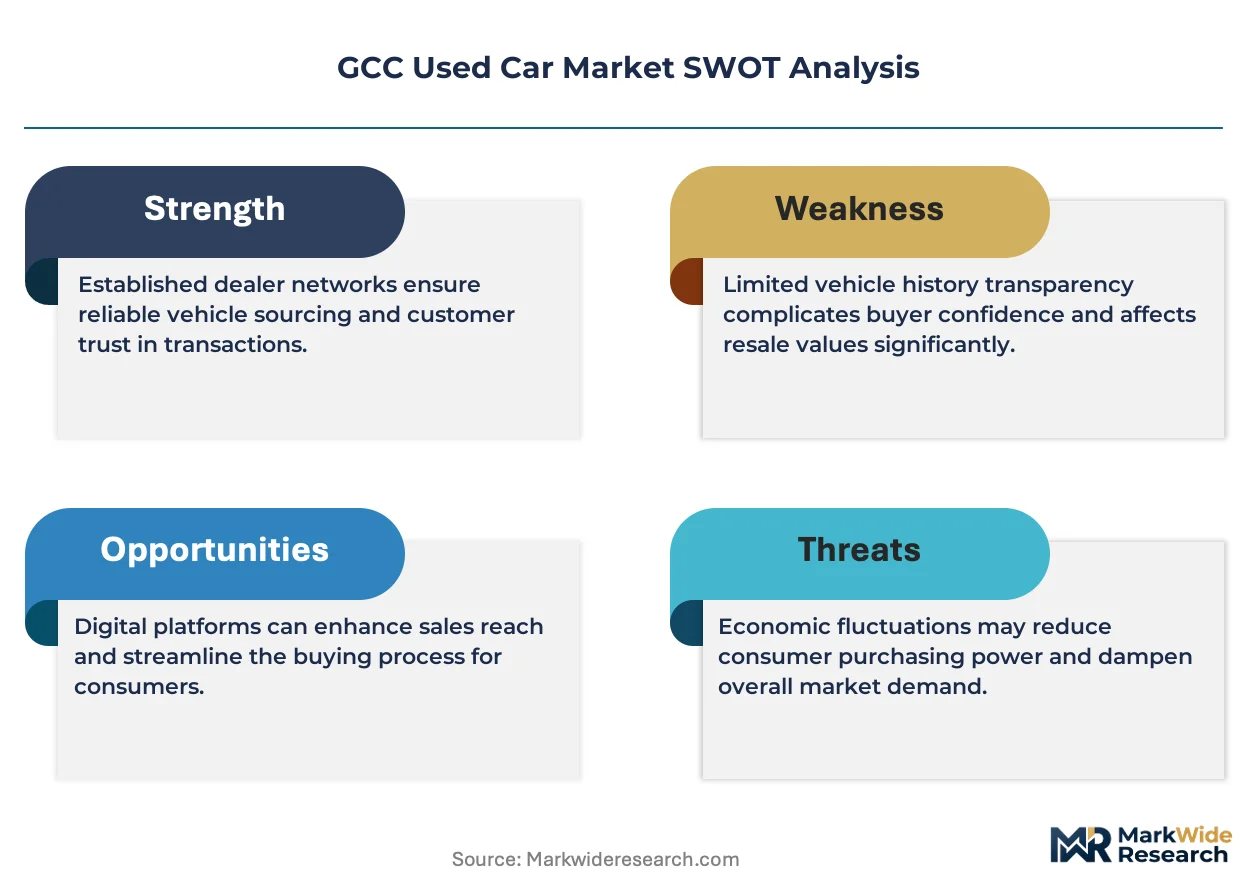
Captive reconditioning hub operations anchor both supply positioning and pricing power across GCC used car markets. Al-Futtaim Group and authorized dealership networks leverage in-house refurbishment capacity to command certified pre-owned premiums while insulating margin structures from third-party service volatility.
Pricing Analysis
Volume concentrates in uncertified private-party transactions while margin pools accrue to dealer-backed certified channels. Three-tier pricing structure across certified, verified, and unverified inventory levels separates warranty-backed units from inspection-only and sight-unseen listings. Pricing pressure stems from spare parts import duty fluctuations during GCC customs union negotiations, compressing reconditioning hub margins. Fleet operators exhibit lowest price sensitivity due to multi-year contract lock-ins, whereas first-time family buyers in Saudi Arabia's secondary cities drive hardest bargain hunting.
Supply Chain Analysis
Dual-sourcing requirements from fleet operators mandate qualification of multiple reconditioning hubs and parts distributors before contract award. Parts procurement draws from Japan, South Korea, and Germany for OEM components, with aftermarket alternatives sourced from China and India. Inventory feeds from Dubai-Abu Dhabi corridor reconditioning clusters, creating geographic concentration risk to local demand shocks. Distribution runs through authorized dealership networks for certified units, while digital platforms and classifieds handle fragmented spot-market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation functions as a market-clearing mechanism, forcing sub-scale dealers toward platform aggregation or exit as multi-year contracts compress spot-market volume.
For Market Incumbents: Acquire inspection-technology capabilities to defend certified pre-owned positioning against CARS24 and emerging scoring platforms. Secure captive financing licenses in Saudi Arabia and the UAE to lock in buyer loyalty through installment penetration. SAMR emissions testing expansion threatens older inventory liquidity; accelerate reconditioning throughput before regulatory filtering intensifies. For New Entrants and Emerging Players: Capture Kuwait and Oman whitespace where certified pre-owned infrastructure remains undeveloped and manufacturer-authorized programs hold zero presence. Deploy mobile-first inspection apps to bypass capital-intensive hub requirements and aggregate seller liquidity through remote condition scoring. Partner with emerging charging infrastructure operators to front-run hybrid and electric vehicle resale pipelines as GCC fleet electrification advances. For Investors and Strategic Acquirers: Exit pathways concentrate in platform rollup transactions as classifieds infrastructure operators seek inspection-technology capabilities to close the certification gap. Five-to-ten year viability hinges on regulatory alignment across SAMR, Emirates Authority for Standardization and Metrology, and Gulf Standardization Organization frameworks. Watch blockchain title verification deployment velocity across Saudi transport authorities as the inflection signal for transaction friction reduction and multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Fleet Supply Contract | Locks volume basins for reconditioning hubs against spot-market volatility. |
| Proprietary Condition-Scoring Technology | Enables CARS24 to standardize remote assessment and reduce buyer travel friction. |
| Certified Pre-Owned Program Expansion | Allows Al-Futtaim Group to capture warranty-backed price premiums in Dubai family segment. |
| Blockchain Title Verification Deployment | Reduces ownership dispute resolution timelines across Saudi transport authority jurisdictions. |
| Cross-Border Inspection Protocol Harmonization | Accelerates certified vehicle circulation between Dubai and Abu Dhabi corridors under Emirates Authority alignment. |
Research Methodology
Multi-period observation of transaction velocity, certification penetration rates, and platform market share anchored the trend analysis, supplemented by interviews with fleet procurement directors, dealership operations managers, reconditioning hub technicians, and classifieds platform executives. Secondary validation drew from SAMR regulatory filings, Emirates Authority for Standardization and Metrology certification databases, vehicle registration statistics, and GCC customs union negotiation records. Bottom-up transaction modeling triangulated against top-down fleet replacement cycle analysis.
Input-output matrix structure connected vehicle age distribution, reconditioning cost curves, and buyer segment willingness-to-pay across the projection horizon. Segmentation dimensions spanned vehicle type, fuel architecture, condition grade, and sales channel, with regional regulatory cluster as an additional modeled layer. CAGRs derived from fitted trend extrapolation moderated by fleet contract renewal schedules and emissions compliance phase-in timelines. Forecast inputs included spare parts import duty sensitivity and digital platform penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GCC customs union completion, blockchain title verification adoption velocity, and hybrid powertrain technician pipeline development. Deviation in SAMR or Emirates Authority emissions testing enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Sri Lanka Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
Vintage Car Market
Used Vehicles
Used Cars Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
North America Used Car Market
Used Vehicles
Spain Used Car Market