
 Ethiopia Used Car Market | 2026-2036
Ethiopia Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Ethiopia Used Car Market Insights
Multi-source procurement from Dubai, Japan, and European auction houses is rebalancing toward consolidated direct relationships with Japanese exporters. Nyala Motors leverages its long-standing dealership network to secure consistent inventory of certified pre-owned Toyotas. Marathon Motors Engineering anchors its position through captive service centers that sustain repeat business. Megebeya.com competes by operating a digital-first platform that connects private sellers directly with urban buyers.
A used car in Ethiopia denotes a secondhand passenger or light commercial vehicle imported primarily from right-hand-drive markets, typically with odometer readings between 50,000 and 150,000 kilometers and subject to pre-shipment inspection for roadworthiness. These vehicles serve household mobility, commercial transport, and fleet operations in a country where new vehicle prices exceed per capita income by extreme multiples. Sedan and SUV imports dominate transaction volumes, though hatchbacks capture growing interest among first-time urban buyers constrained by parking scarcity and fuel costs. Online marketplaces and dealership channels are expanding fastest, while auction-based procurement remains concentrated among bulk importers in Addis Ababa.
The Ministry of Transport and Logistics enforces the eight-year age limit on imported used vehicles, while the Ethiopian Revenue and Customs Authority applies escalating duty schedules that favor lower-displacement engines. These frameworks compress importable supply and redirect demand toward newer, smaller-engined units that command premium pricing. Stakeholders must monitor potential harmonization of East African Community vehicle standards and decide whether to build regional inspection capacity or deepen bilateral agreements with Japanese export authorities.
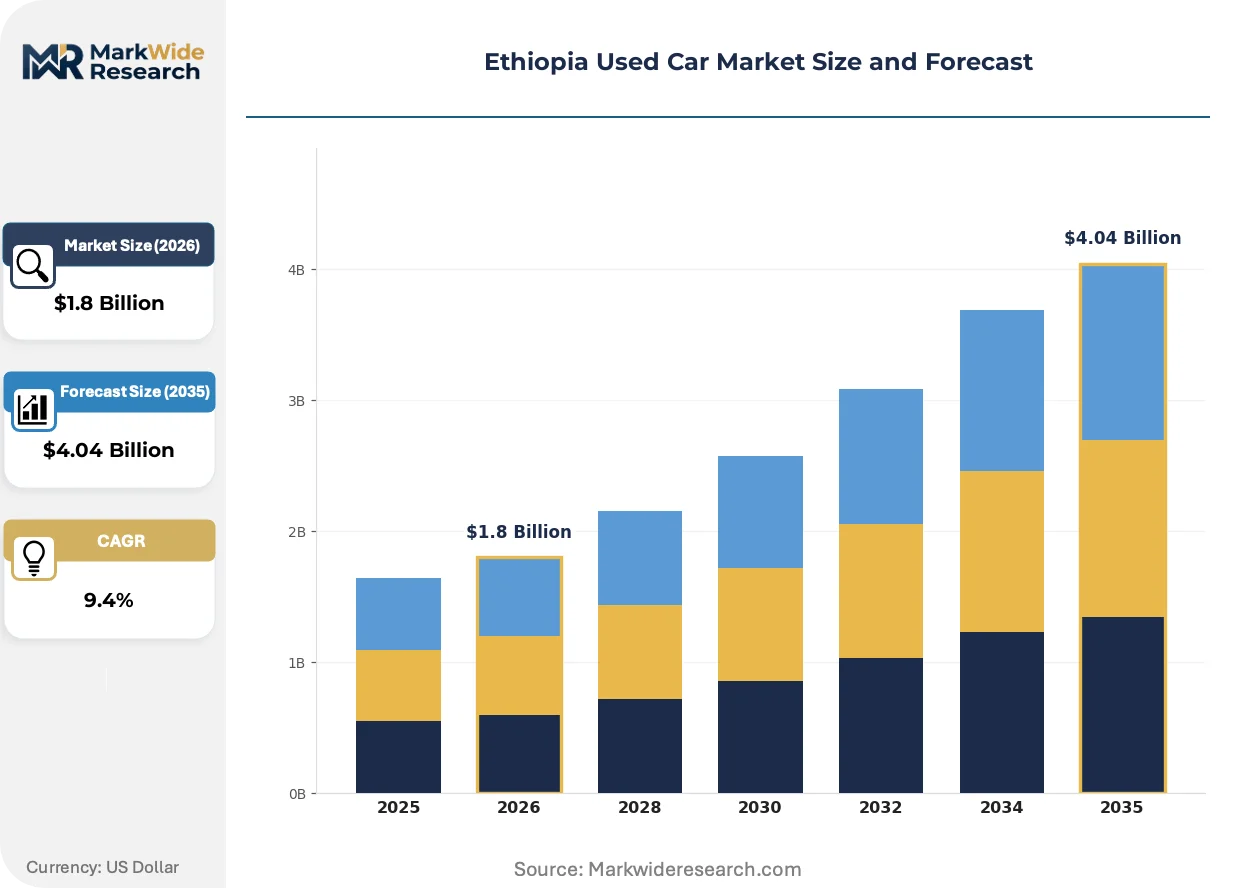
Market Dynamics
The Ethiopia Ministry of Transport and Logistics eight-year age restriction on imported used vehicles is compressing eligible supply and redirecting procurement toward newer, higher-cost inventory that reshapes dealer margins and buyer financing structures.
Growth Catalysts
- Ride-hailing cooperative expansion:Addis Ababa-based transport cooperatives are scaling fleet acquisitions to serve urban mobility demand, creating concentrated bulk purchasing power that pulls newer sedan and SUV imports through formal dealership channels.
- Duty schedules favoring sub-1.3L engines:The Ethiopian Revenue and Customs Authority's escalating tariff structure incentivizes lower-displacement powertrains, redirecting importer sourcing toward Japanese compact hatchbacks that match first-time urban buyer constraints.
- Digital marketplace penetration:Platform-based transaction infrastructure is expanding into secondary cities, reducing information asymmetry between private sellers and buyers in the Oromia Special Zone corridor.
Market Restraints
- Import source concentration:Over-reliance on Japanese auction houses and Dubai re-export hubs creates vulnerability to yen-dirham exchange volatility and shipping lane disruptions affecting Red Sea transit.
- Pre-shipment inspection bottlenecks:Roadworthiness certification requirements administered by contracted foreign inspectors introduce timeline friction and per-unit cost escalation before vessels depart origin ports.
- Right-hand-drive technical lock-in:The national vehicle stock's RHD configuration limits alternative sourcing from left-hand-drive European markets, constraining price competition and model diversity.
Strategic Opportunities
- Regional inspection capacity development:Establishing bilateral technical agreements with Japanese export authorities could streamline certification workflows and reduce pre-shipment delays for Ethiopian importers.
- Captive service center networks:After-sales infrastructure anchored in Addis Ababa is expanding into Hawassa and Bahir Dar, capturing maintenance revenue streams that sustain repeat vehicle transactions.
- Hybrid powertrain early positioning:Toyota Aqua and Honda Fit hybrid inventories are penetrating the eight-year eligibility window, enabling dealers to differentiate on fuel efficiency as pump prices escalate.
Industry Challenges
- Automotive technician certification gaps:Diagnostic capability for electronic fuel injection and hybrid systems remains concentrated in Addis Ababa, limiting service quality consistency in regional markets.
- Spare parts customs clearance latency:Critical component imports face unpredictable duty classification disputes that extend vehicle downtime and erode fleet operator utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethiopia Used Car Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Pickup Fuel Type: Petrol, Diesel, LPG, Electric Condition: New, Certified Pre-Owned, Used, Damaged Sales Channel: Dealerships, Private Sellers, Online Marketplaces, Auctions |
| Companies Covered | Nyala Motors, Marathon Motors Engineering, Megebeya.com, Black Diamond, ALEM International PLC, Cars 4 Africa, Ultimate Motor, Mekina.net, Proxima Auto Car Dealer, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethiopia Used Car Market Trends and Innovations
Digital transaction infrastructure and regulatory compression are restructuring how vehicles flow from foreign auction lanes to Ethiopian owners, with platform intermediation and age-based eligibility creating new competitive battlegrounds.
Telematics-enabled fleet management systems are expanding into commercial transport operations, allowing ride-hailing cooperatives to monitor driver behavior and vehicle health in real time. Operators in Addis Ababa are adopting these tools fastest, using aggregated data to negotiate insurance premiums and optimize maintenance scheduling. This technology diffusion is compressing information advantages that traditional dealers previously held over fragmented private sellers.
The Ministry of Transport and Logistics is harmonizing vehicle inspection protocols with emerging East African Community standards, creating pressure to upgrade domestic certification infrastructure. This regulatory convergence will likely mandate additional emissions testing equipment and technician training investments. Importers serving cross-border fleet operators in the Oromia corridor are pre-positioning inventory that anticipates stricter regional technical requirements.
Buyer preference is rotating toward certified pre-owned programs that bundle warranty coverage with service packages, displacing raw auction-sourced transactions. First-time urban purchasers in Addis Ababa are driving this shift, prioritizing predictable maintenance costs over minimal acquisition price. Dealerships with captive technical capacity are capturing this demand migration, while pure digital platforms face pressure to develop inspection and guarantee capabilities.
Ethiopia Used Car Market Segmentation
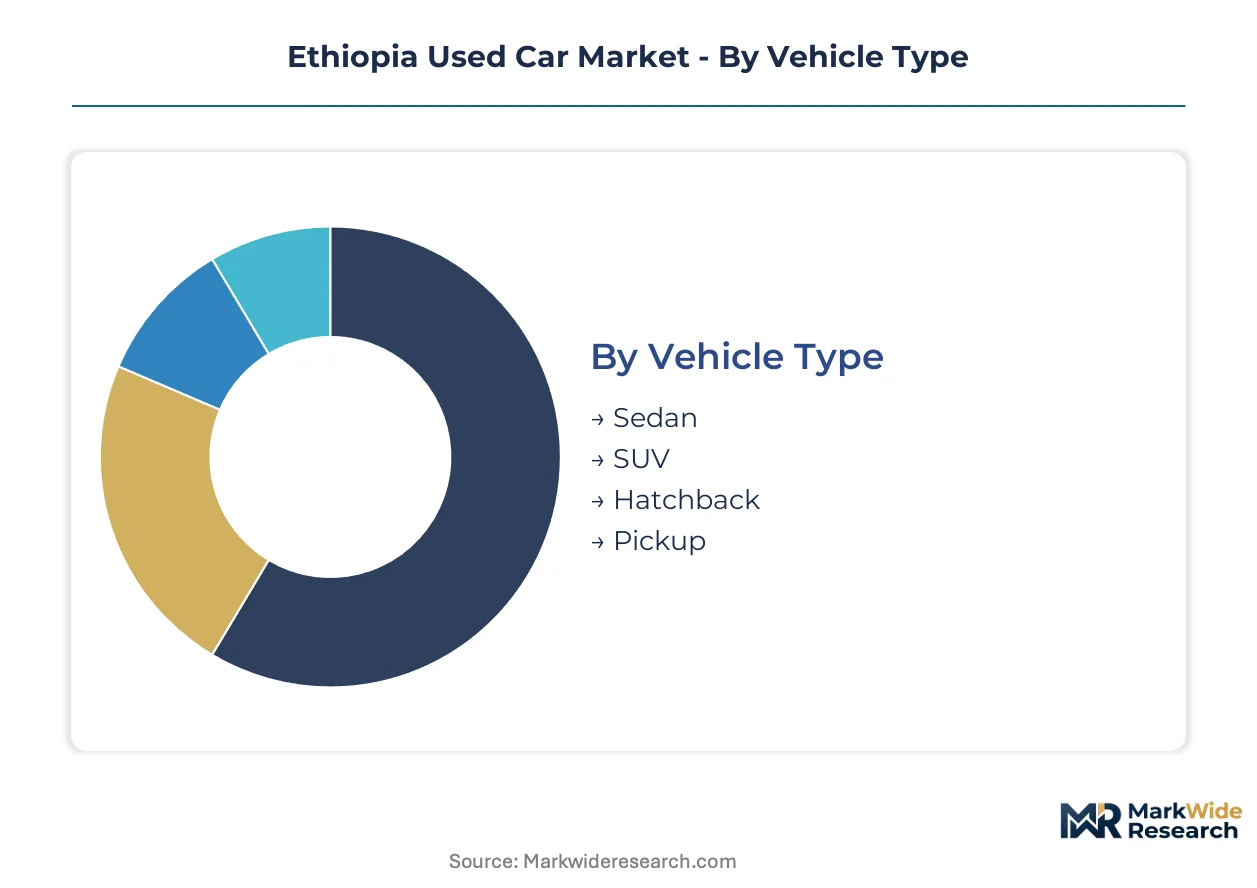
Segmentation in Ethiopia's used car market reveals how regulatory compression and buyer constraints reshape transaction flows. The eight-year import age limit and duty structures on engine displacement create divergent demand patterns across vehicle configurations and procurement channels.
Vehicle Type:
Urban mobility requirements and commercial fleet economics differentiate buyer priorities across body styles.
- Sedan:Three-box passenger configurations dominate ride-hailing cooperative procurement in Addis Ababa. Fleet operators favor Toyota Corolla and Honda Civic vintages for their service network density and parts interchangeability.
- SUV:Higher ground clearance and seating capacity command premium positioning among household buyers in the Oromia Special Zone corridor. Duty penalties on larger displacements compress importable supply to sub-2.0L compact crossovers.
- Hatchback:Parking-constrained urban first-time buyers are redirecting demand toward Japanese compact hatches. The Ethiopian Revenue and Customs Authority's tariff schedule amplifies this shift through engine-based duty escalation.
- Pickup:Commercial operators in regional trade routes utilize light trucks for goods transport. Pre-shipment inspection requirements for commercial classification introduce additional certification friction.
Sedan imports lead volumes today; hatchback transactions are gaining share fastest.
Fuel Type:
Refining infrastructure limitations and import duty architecture determine viable powertrain options for Ethiopian buyers.
- Petrol:Widest retail fuel availability supports dominant transaction share. Japanese auction-sourced petrol engines align with right-hand-drive technical standards enforced by the Ministry of Transport and Logistics.
- Diesel:Commercial fleet operators prioritize torque density for loaded operation. Higher per-liter pricing and particulate inspection requirements constrain adoption outside long-haul applications.
- LPG:Aftermarket conversion market serves cost-sensitive operators seeking pump price arbitrage. Conversion kit quality variability creates safety inspection challenges at port entry.
- Electric:Grid reliability constraints and charging infrastructure gaps limit penetration. Used Nissan Leaf imports from Japanese auction lanes are testing price-elastic early adopter demand in Addis Ababa.
Petrol powertrains anchor current supply; hybrid configurations are climbing the fastest as eight-year eligibility windows capture Toyota Aqua and Honda Fit inventories.
Condition:
Buyer risk tolerance and financing access create stratified procurement behavior across certification tiers.
- Certified Pre-Owned:Dealer-backed warranty programs bundle inspection documentation with service packages. Nyala Motors and Marathon Motors Engineering leverage captive technical capacity to capture risk-averse urban household demand.
- Used:Private auction-sourced vehicles without warranty coverage dominate price-sensitive transactions. Information asymmetry between sellers and buyers drives platform-based intermediation through Megebeya.com.
- New:Extreme price multiples relative to per capita income restrict volume to diplomatic and corporate fleet channels. Official distributor relationships with Toyota and Hyundai anchor this thin segment.
- Damaged:Repairable write-offs from Japanese insurance auctions supply parts recovery and rebuild operations. Customs classification disputes over salvage versus used status create clearance timeline uncertainty.
Uncertified used vehicles lead transaction volumes today; certified pre-owned programs are expanding most quickly as dealership networks professionalize.
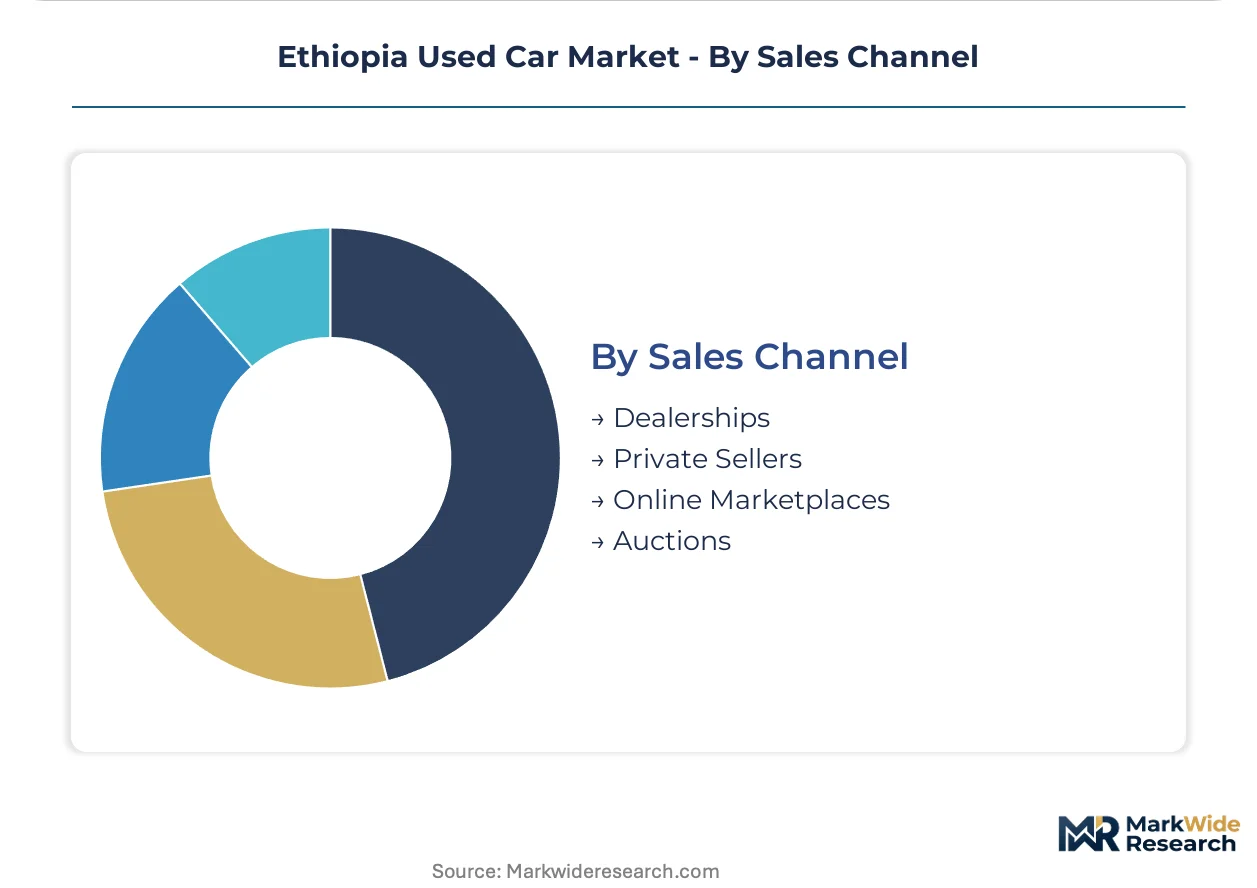
Sales Channel:
Information access and trust mechanisms determine how buyers match with inventory across procurement modalities.
- Online Marketplaces:Platform-based price discovery reduces search costs for urban buyers comparing private seller listings. Megebeya.com's digital infrastructure is extending into Hawassa and Bahir Dar secondary markets.
- Dealerships:Physical inspection capacity and financing facilitation anchor formal channel preference among cooperative fleet buyers. Captive service centers sustain repeat transaction relationships.
- Private Sellers:Direct owner-to-buyer transfers minimize intermediary margins for cash-constrained transactions. Title verification and mechanical condition assessment burden falls entirely on purchasers.
- Auctions:Bulk import concentration among Addis Ababa-based traders supplies downstream retail channels. Japanese auction house relationships require yen-denominated settlement exposure and pre-shipment inspection coordination.
Dealership and private seller channels split volume leadership today; online marketplace penetration is accelerating fastest as mobile data costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory compression in Addis Ababa is redirecting procurement toward newer inventory that commands premium pricing, while secondary markets exploit compliance cost differentials to capture price-sensitive demand migrating from the capital.
Addis Ababa
Ride-hailing cooperatives and diplomatic fleet operators concentrate bulk purchasing power in the capital. The Ministry of Transport and Logistics enforces the eight-year age limit most stringently at Bole and Modjo port entry points. Dealership clusters in Kirkos and Bole sub-cities anchor certified pre-owned distribution networks serving risk-averse household buyers.
Oromia Special Zone
Urbanization spillover from Addis Ababa is accelerating vehicle ownership in Adama and Bishoftu. The Oromia regional transport bureau applies national standards with variable inspection rigor, creating arbitrage opportunities for older inventory. Adama's position along the Mojo-Djibouti corridor positions it as a secondary distribution node for commercial pickup imports.
Amhara Region
Bahir Dar's hospitality and tourism sector generates demand for SUV configurations suited to Lake Tana access roads. Regional customs offices at Kombolcha process lower volumes with extended clearance timelines. Emerging dealership presence in Bahir Dar is capturing maintenance revenue previously diverted to Addis Ababa service centers.
Tigray Region
Mekelle's reconstruction-phase commercial transport requirements favor durable pickup configurations for construction material haulage. The regional administration has temporarily relaxed certain import documentation requirements to accelerate fleet renewal. Cross-border trade corridors toward Djibouti are reactivating, pulling commercial vehicle demand through Mekelle-based intermediaries.
Southern Nations, Nationalities, and Peoples Region
Hawassa's industrial park expansion is generating staff transport demand among garment and textile factory workforces. The regional transport authority is piloting cooperative fleet registration programs to formalize commercial operations. Digital marketplace penetration is extending from Addis Ababa into Hawassa's secondary market, reducing information asymmetry for private transactions.
Ethiopia Used Car Market Competitive Landscape
Established dealership networks occupy the standard tier; emerging digital platforms pursue intermediation efficiency and price transparency as their competitive wedge. The market structure fragments across three operational models: integrated dealership-service centers, pure digital marketplaces, and hybrid auction-import specialists. Strategic archetypes include captive infrastructure players, platform intermediaries, and bulk import aggregators. Dominant competitive moves center on service center geographic expansion and pre-shipment inspection workflow streamlining.
Among dealership-based operators, Nyala Motors and Marathon Motors Engineering exemplify the captive infrastructure archetype through their established service center networks. Megebeya.com occupies the digital-first intermediary position, representing platform-based challengers that reduce transaction friction between private sellers and urban buyers. These three entities anchor the competitive spectrum from physical-dominant to digital-native procurement modalities.
| Leading Market Players |
|---|
| Nyala Motors |
| Marathon Motors Engineering |
| Megebeya.com |
| Black Diamond |
| ALEM International PLC |
| Cars 4 Africa |
| Ultimate Motor |
| Mekina.net |
| Proxima Auto Car Dealer |
| Others |
Pricing and Supply Chain Analysis
Diagnostic technician concentration in Addis Ababa compresses service-labor costs for certified pre-owned programs while inflating pricing spreads between dealership-backed and uncertified private transactions. The Ethiopian Revenue and Customs Authority's engine-displacement duty schedule amplifies these tier effects by redirecting procurement toward smaller-engined units that cluster in economy pricing bands.
Pricing Analysis
Retailer markup layers dominate transaction economics, with dealership service-bundling commanding 15-25% premiums over auction-sourced private sales. Price differentiation rests on certification grade and after-sales warranty coverage, separating Nyala Motors-backed Toyotas from Megebeya.com private listings. Cost compression in the hatchback segment is intensifying because first-time urban buyers prioritize fuel efficiency over displacement. Cooperative fleet operators show least price sensitivity, absorbing premium sedan pricing for predictable maintenance scheduling.
Supply Chain Analysis
Refurbishment flows from Japanese insurance auctions feed parts recovery operations in Addis Ababa's Kirkos district, extending vehicle economic life beyond primary ownership cycles. Geographic supply concentrates in Japan, Dubai re-export hubs, and limited European right-hand-drive markets. Component dependencies center on electronic fuel injection systems, hybrid battery packs, and emission control modules. Single-source vulnerability to yen-dirham exchange volatility threatens margin stability. Distribution runs through bulk import aggregators in Addis Ababa before radiating to Oromia Special Zone secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
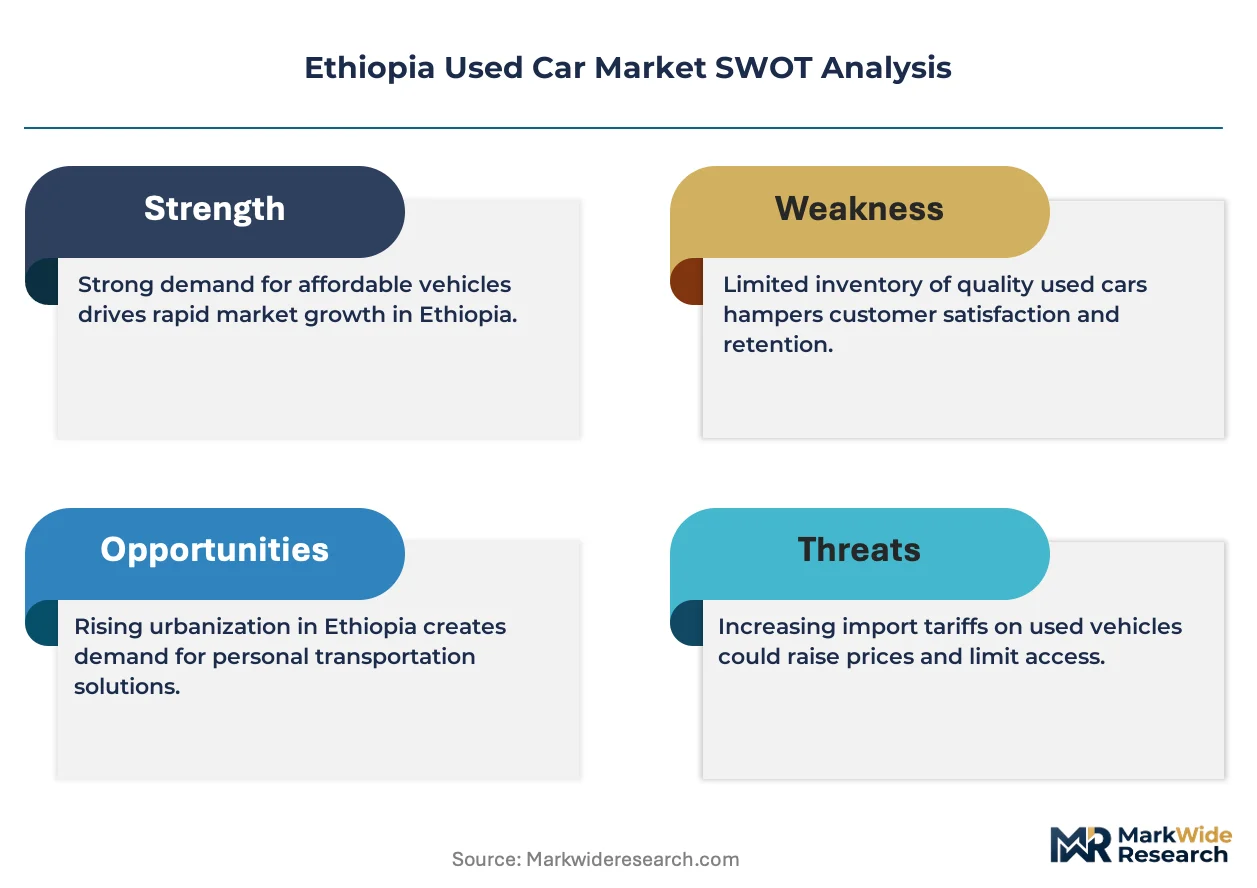
The Ethiopia used car market operates as a regulatory compounder where the Ministry of Transport and Logistics eight-year age restriction continuously compresses eligible supply and redirects demand toward newer, higher-margin inventory.
For Market Incumbents: Deepen captive service center networks in Hawassa and Bahir Dar to capture maintenance revenue streams that sustain repeat transactions. Expand bilateral technical agreements with Japanese export authorities to streamline pre-shipment inspection workflows and reduce timeline friction. Vertical integration into spare parts customs clearance operations addresses classification dispute risks that erode fleet operator utilization rates.
For New Entrants and Emerging Players: Telematics-enabled fleet management platforms offer a technology-first wedge into ride-hailing cooperative procurement. Target the Oromia Special Zone corridor where digital marketplace penetration remains nascent and information asymmetry between private sellers and buyers persists. A mobile-first inspection and escrow service addresses trust deficits in secondary city transactions.
For Investors and Strategic Acquirers: Regional dealership networks with captive technical capacity are the most active acquirer in this space, consolidating fragmented service infrastructure. Long-term viability hinges on positioning for hybrid powertrain service capability as Toyota Aqua and Honda Fit inventories penetrate the eight-year eligibility window. Monitor East African Community emissions harmonization timelines as inflection indicators for certification equipment investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Shipment Inspection Workflow Streamlining | Bilateral agreements with Japanese export authorities reduce port-entry delays at Bole and Modjo. |
| Captive Service Center Geographic Expansion | Maintenance revenue capture in Hawassa and Bahir Dar sustains repeat transaction relationships. |
| Telematics Platform Integration | Real-time vehicle monitoring enables Addis Ababa cooperatives to negotiate insurance premiums. |
| Hybrid Powertrain Technical Certification | Early positioning on Toyota Aqua and Honda Fit service capability differentiates dealer networks. |
| Digital Marketplace Infrastructure Extension | Mobile-based price discovery reduces search costs in Oromia Special Zone secondary markets. |
Research Methodology
Multiple input streams — structured interviews with dealership operations managers, bulk import aggregators, and ride-hailing cooperative fleet administrators; trade flow documentation from Ethiopian Revenue and Customs Authority disclosures; and vehicle registration databases — were reconciled through bottom-up transaction enumeration and top-down market sizing validation. Secondary sources included Ministry of Transport and Logistics directive filings, Japanese auction house export statistics, and regional customs clearance records. Primary fieldwork captured pricing behavior and procurement decision criteria across certified pre-owned, auction-sourced, and private seller channels.
Data-stream reconciliation anchored volume projections to observed fleet renewal cycles, engine-displacement duty schedule elasticities, and urbanization-driven ownership penetration patterns across the analysis window. Segmentation dimensions modeled encompassed vehicle body configuration, powertrain architecture, certification tier, and sales channel modality. CAGRs were derived from fitted growth curves calibrated to historical import volumes and projected cooperative fleet expansion trajectories. Forecast inputs incorporated right-hand-drive sourcing constraints and pre-shipment inspection capacity bottlenecks.
The model holds under stable enforcement of the eight-year age restriction and sustained yen-denominated settlement exposure; deviation in East African Community emissions harmonization timelines or Red Sea shipping lane disruptions would shift supply availability and pricing tier distributions. Practitioners should monitor regulatory convergence signals and exchange rate volatility for early indicators of procurement cost structure changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
UAE Used Cars Industry Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
China Used Car Market
Used Vehicles
India Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
South Africa Used Car Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Switzerland Used Car Market