
 Europe Used Car Market | 2026-2036
Europe Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Used Car Market Analysis
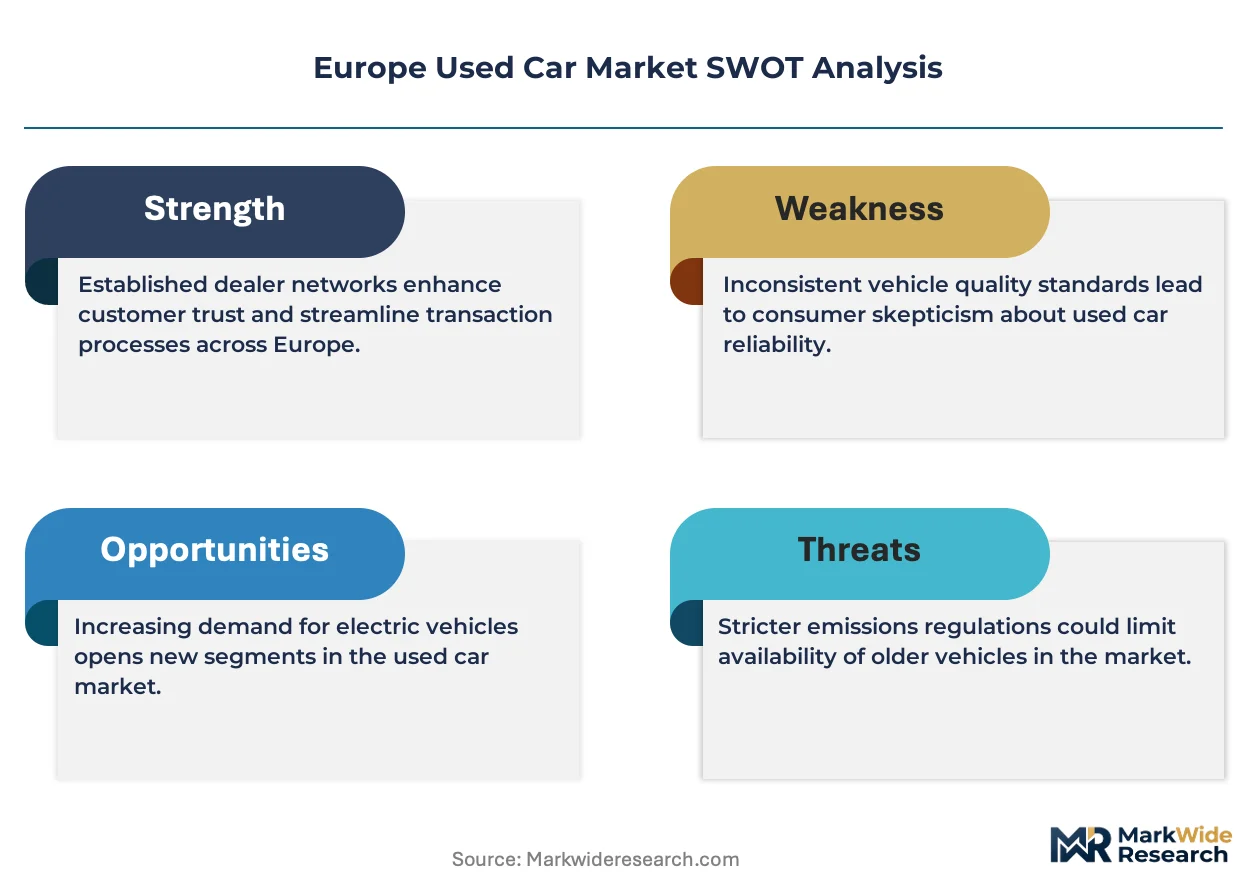
The capital-intensity gap between legacy dealer networks and digital-native platforms is collapsing as online valuation engines and logistics automation erase scale advantages. AUTO1 Group SE leverages proprietary pricing algorithms and pan-European fulfillment infrastructure to compete against established physical networks. Volkswagen AG anchors certified pre-owned volume through manufacturer-backed warranty programs and captive finance arms. Pendragon Plc sustains market position by integrating digital retail tools with its UK dealership footprint, though margin pressure from pure-play disruptors intensifies.
A used car denotes a previously registered motor vehicle transferred through secondary ownership channels, typically assessed via odometer verification, structural integrity inspection, and service history documentation before resale. These vehicles serve price-sensitive consumers, fleet operators, and mobility services seeking depreciated assets with remaining operational life. SUVs and hatchbacks dominate volume turnover across European exchanges as utility preferences and urban parking constraints shape selection patterns. Electric and hybrid segments within fuel type classification are attracting disproportionate margin pools as battery health certification and residual value guarantees emerge as differentiation tools. Franchise dealerships and online platforms now split transaction flow, with auction channels concentrating institutional fleet disposals and trade-ins.
EU Green Deal emission targets, REACH chemical compliance for interior materials, and national low-emission zone frameworks are reshaping vehicle eligibility and resale value curves across member states. EMA and national transport regulators coordinate type-approval reciprocity standards that determine cross-border market access for imported used vehicles. Buyers and sellers must monitor battery state-of-health protocols for electrified powertrains and the evolving patchwork of city access restrictions that will determine which vehicle ages and technologies retain liquidity.
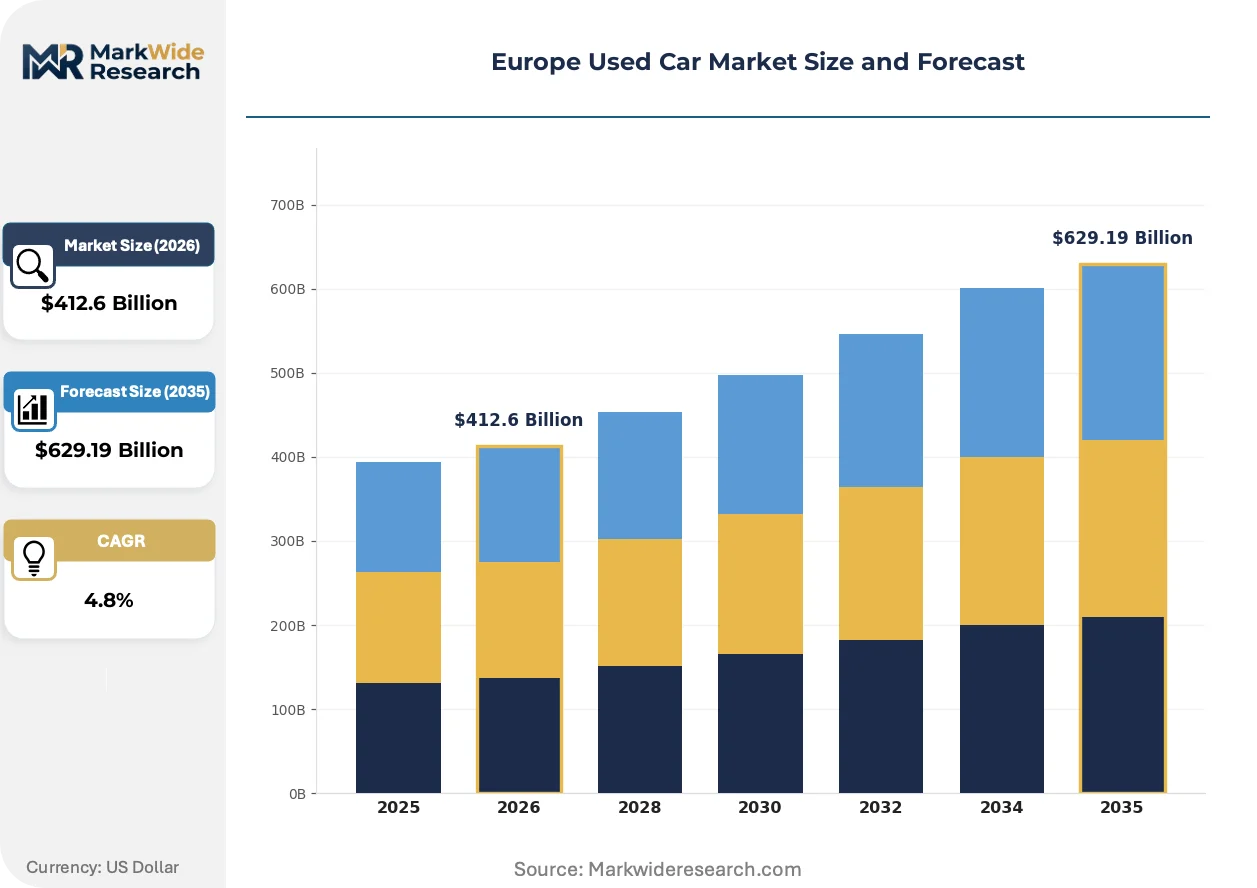
Market Dynamics
EU Green Deal emission targets are compressing diesel residual values while battery health certification protocols are creating new liquidity tiers for electrified used vehicles across member state markets.
Growth Catalysts
- Low-emission zone expansion:Cities including London, Paris, and Berlin are tightening vehicle access rules, accelerating trade-ins of older combustion models into secondary channels. Buyers seeking compliant mobility are redirecting demand toward younger used stock.
- Fleet electrification cascades:Corporate and ride-hailing operators are rotating battery-electric vehicles into their fleets every 24-36 months, flooding exchanges with nearly-new units carrying manufacturer warranties.
- Digital valuation engines:Automated pricing algorithms using real-time transaction data are collapsing information asymmetries between buyers and sellers, compressing negotiation friction and accelerating turnover velocity.
Market Restraints
- Battery degradation uncertainty:Absence of standardized state-of-health testing protocols across France, Germany, and Italy creates valuation disputes that stall electric used vehicle transactions.
- Cross-border type-approval fragmentation:EMA coordination with national transport regulators produces inconsistent import eligibility rules that trap liquidity in domestic markets.
- Semiconductor supply volatility:Persistent shortages of automotive chips constrain new vehicle production, paradoxically inflating used prices beyond fundamental value and deterring price-sensitive entrants.
Strategic Opportunities
- Certified pre-owned battery programs:Manufacturer-backed residual value guarantees for electric powertrains can unlock hesitant buyer segments in Poland and Czechia where charging infrastructure remains sparse.
- Subscription-to-own transitions:Mobility service operators with large captive fleets can structure lease residuals into retail used channels, capturing margin from both utilization and resale.
- REACH compliance arbitrage:Early investment in interior material documentation and chemical traceability positions sellers ahead of 2025 enforcement windows that will disqualify non-compliant inventory.
Industry Challenges
- Diagnostic technician scarcity:Electrified powertrain assessment requires skills absent from traditional mechanical training pipelines, creating bottlenecks at inspection centers.
- Data interoperability gaps:Service history records trapped in proprietary manufacturer systems resist aggregation into unified vehicle provenance reports that buyers demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Used Car Market |
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $629.19 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedans, SUVs, Hatchbacks, Coupes Fuel Type: Diesel, Petrol, Electric, Hybrid Sales Channel: Franchise Dealerships, Independent Dealers, Online Platforms, Auctions Age Category: 1-3 Years, 4-6 Years, 7-10 Years, 10+ Years |
| Companies Covered | Pendragon Plc, Volkswagen AG, AUTO1 Group SE, BMW Group, Renault Group, Lookers Plc, Aramis Group SA, Arval, Emil Frey AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Used Car Market Emerging Trajectories
Digital retail infrastructure is collapsing the traditional separation between wholesale auction and consumer-facing transaction, enabling direct fleet-to-buyer matching that bypasses layered intermediary markups.
Blockchain-based vehicle provenance systems are miniaturizing trust costs in cross-border transactions. Dutch and Belgian platforms are piloting immutable service records linked to VIN registries. This compression of verification overhead is enabling smaller dealers to compete for international sourcing previously dominated by scaled networks.
REACH chemical compliance deadlines are forcing interior material overhauls in vehicles manufactured before 2020. ECHA enforcement coordination with national environmental agencies is creating a two-tier market where documented compliance commands measurable premiums. German inspection associations are developing rapid testing protocols to certify eligible inventory ahead of 2025 cutoff dates.
Subscription fatigue among urban professionals is redirecting demand toward flexible ownership models. Younger buyers in Barcelona, Amsterdam, and Copenhagen are rejecting long-term finance commitments in favor of shorter-hold used purchases with embedded upgrade rights. Digital-native platforms are capturing this cohort through app-based trade-in triggers and home delivery logistics.
Europe Used Car Market Segmentation
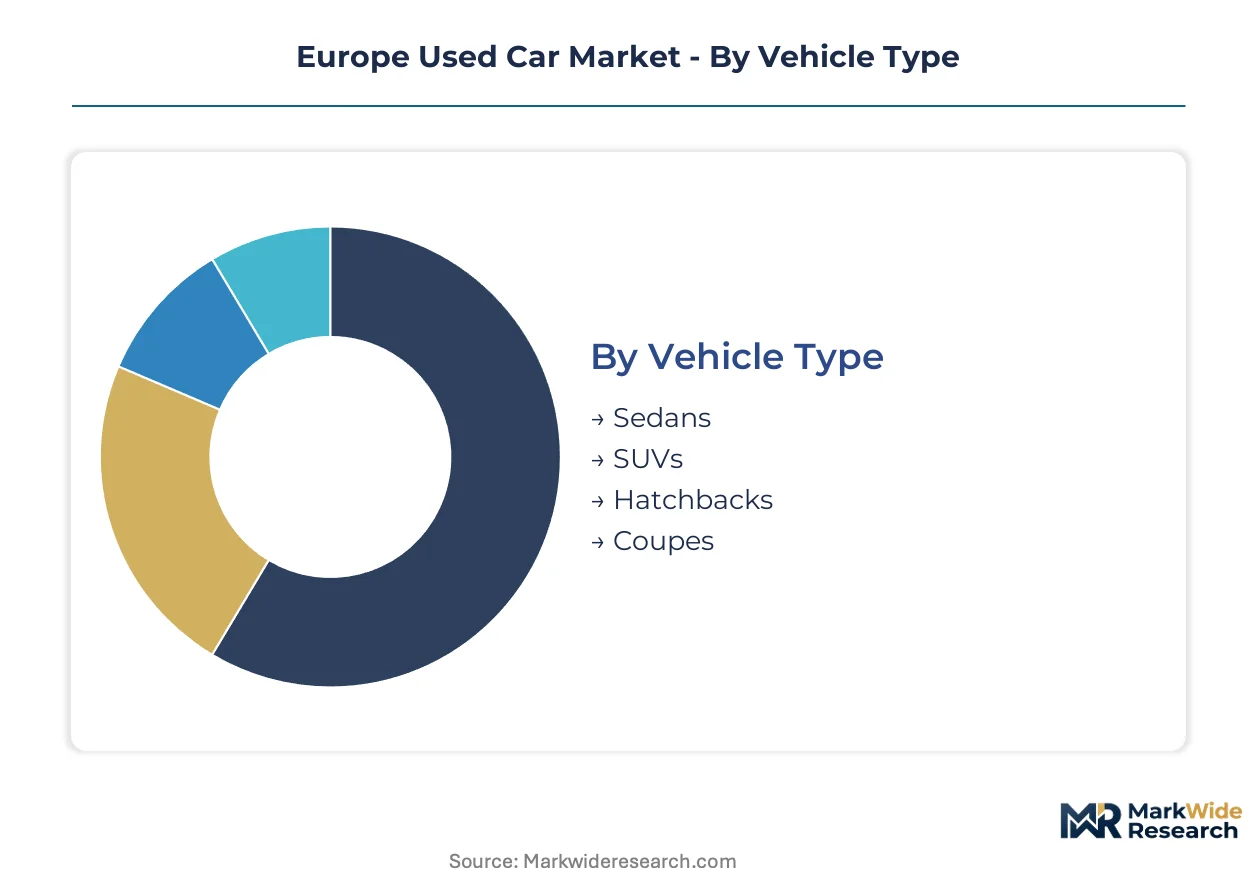
Segmentation in the Europe Used Car Market reveals how regulatory pressure and consumer preference shifts are reallocating liquidity across vehicle categories. Understanding these divisions exposes which inventory pools face obsolescence risk and which command premium positioning.
Vehicle Type:
Substitution pressure from electrified powertrains and urban access restrictions is reshaping which body styles retain resale viability across European exchanges.
- SUVs:Elevated seating position and cargo flexibility sustain demand among family buyers and fleet operators in Germany and France. Low-emission zone expansion in Paris and Berlin favors newer SUV vintages with Euro 6d compliance, compressing residual values for older diesel variants.
- Hatchbacks:Compact dimensions suit urban parking constraints in Amsterdam, Barcelona, and Copenhagen where subscription-to-own models are gaining traction. Electrified hatchbacks from corporate fleet rotations dominate nearly-new supply channels.
- Sedans:Corporate fleet disposals in the United Kingdom and Italy maintain volume flow, though buyer preference is shifting toward crossover proportions.
- Coupes:Enthusiast segments in southern European markets sustain niche liquidity for performance-oriented two-doors with documented service histories.
SUVs retain volume leadership; electric hatchbacks hold the steepest expansion curve.
Fuel Type:
Cost tier stratification is intensifying as compliance costs and charging infrastructure availability segment buyers into divergent total-ownership calculations.
- Electric:Battery state-of-health certification gaps create valuation disputes in France, Germany, and Italy. Manufacturer-backed residual guarantees unlock hesitant buyer segments in Poland and Czechia where public charging remains sparse.
- Diesel:EU Green Deal targets and national low-emission zones are compressing residual values for pre-2020 vintages. Trade-in cascades from fleet operators are flooding auctions with compliant younger diesel stock.
- Hybrid:Urban professionals in London and Paris favor plug-in variants for congestion charge exemptions. Toyota and Hyundai captive finance programs sustain certified pre-owned liquidity.
- Petrol:Price-sensitive entrants in Spain and Portugal gravitate toward smaller-displacement engines with established maintenance networks.
Diesel retains transaction volume leadership; electric powertrains are climbing the fastest as battery certification protocols mature.
Sales Channel:
Customer type differentiation is collapsing as digital-native platforms erode the information advantages once held by physical dealer networks.
- Online Platforms:AUTO1 Group SE and similar operators leverage proprietary pricing algorithms and pan-European fulfillment to compress negotiation friction. Home delivery logistics and app-based trade-in triggers capture younger buyer cohorts in Amsterdam and Copenhagen.
- Franchise Dealerships:Volkswagen AG and manufacturer-backed warranty programs anchor certified pre-owned volume. Captive finance arms integrate digital retail tools with physical inspection infrastructure.
- Independent Dealers:Margin pressure from pure-play disruptors intensifies, though rapid REACH compliance testing capabilities create service differentiation.
- Auctions:Institutional fleet disposals and lease returns concentrate in Belgian and Dutch wholesale exchanges with blockchain-based provenance pilots.
Franchise dealerships retain volume leadership; online platforms are gaining share fastest as logistics automation scales.
Age Category:
Application-based segmentation separates mobility-service procurement from price-sensitive retail entry as fleet electrification cascades reshape supply timing.
- 1-3 Years:Nearly-new battery-electric vehicles from corporate and ride-hailing fleet rotations carry manufacturer warranties. These units attract buyers seeking compliant mobility without new-vehicle delivery delays.
- 4-6 Years:Euro 6 compliance thresholds position this cohort for low-emission zone access in London, Paris, and Berlin. Diesel variants face accelerated depreciation as city restrictions tighten.
- 7-10 Years:Price-sensitive entrants in southern European markets sustain demand for well-documented petrol and hybrid stock with established maintenance histories.
- 10+ Years:REACH chemical compliance documentation becomes critical as ECHA enforcement windows approach. Non-compliant interior materials risk market disqualification.
The 4-6 year cohort retains volume leadership; 1-3 year electric stock shows the steepest expansion trajectory as fleet rotation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in southern European markets display the highest price elasticity, gravitating toward older petrol vehicles with established maintenance networks, while northern European purchasers absorb premiums for younger electrified stock compliant with tightening urban access rules.
Germany
Fleet electrification cascades from corporate operators flood exchanges with nearly-new battery-electric units carrying manufacturer warranties. The KBA enforces type-approval reciprocity standards that determine cross-border import eligibility for used vehicles. Berlin and Munich concentrate digital-native platform activity where AUTO1 Group SE leverages proprietary pricing algorithms to compress negotiation friction.
United Kingdom
Subscription fatigue among urban professionals redirects demand toward flexible ownership models with embedded upgrade rights. London's Ultra Low Emission Zone expansion accelerates trade-ins of older combustion models into secondary channels. Pendragon Plc sustains market position by integrating digital retail tools with its UK dealership footprint.
France
Urban professionals in Paris favor plug-in hybrid variants for congestion charge exemptions under tightening access rules. ANSM and national transport regulators coordinate REACH chemical compliance deadlines that force interior material documentation for pre-2020 vehicles. The Paris metropolitan area anchors certified pre-owned volume through manufacturer-backed warranty programs.
Italy
Price-sensitive entrants sustain demand for well-documented 7-10 year petrol and hybrid stock with established service histories. Absence of standardized battery state-of-health testing protocols creates valuation disputes that stall electric used vehicle transactions. Milan and Rome concentrate independent dealer networks facing margin pressure from pure-play digital disruptors.
Netherlands
Blockchain-based vehicle provenance pilots in Dutch wholesale exchanges miniaturize trust costs in cross-border transactions. ECHA enforcement coordination with national environmental agencies creates a two-tier market where documented REACH compliance commands measurable premiums. Amsterdam captures younger buyer cohorts through app-based trade-in triggers and home delivery logistics.
Europe Used Car Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Europe Used Car Market. The competitive structure fragments across three tiers: manufacturer-backed franchise networks with captive finance arms, pure-play digital platforms with algorithmic pricing engines, and independent dealers with physical inspection infrastructure. Two strategic moves dominate competitive positioning: pan-European logistics automation to compress fulfillment costs, and certified pre-owned battery programs to unlock hesitant electric vehicle buyers.
Within the digital-native platform tier, AUTO1 Group SE exemplifies algorithmic pricing and pan-European fulfillment infrastructure. Among manufacturer-backed operators, Volkswagen AG anchors certified pre-owned volume through warranty programs and captive finance integration. On the hybrid physical-digital vector, Pendragon Plc occupies a position bridging UK dealership footprints with digital retail tools.
| Leading Market Players |
|---|
| Pendragon Plc |
| Volkswagen AG |
| AUTO1 Group SE |
| BMW Group |
| Renault Group |
| Lookers Plc |
| Aramis Group SA |
| Arval |
| Emil Frey AG |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty days of inventory turnover at German wholesale exchanges concentrates pricing power with fleet disposal aggregators who control young electric vehicle flow. This lead-time compression tightens margins for independent dealers while amplifying residual value guarantees from manufacturer-backed programs.
Pricing Analysis
Extended warranty and battery health certification revenue drives lifetime value in electrified used vehicle transactions. Three-tier pricing structure across certified pre-owned, standard inspected, and auction-grade vehicles segments buyers by risk tolerance. Cost compression in diesel stock intensifies because EU Green Deal targets accelerate obsolescence timelines. Price-sensitive entrants in southern European markets gravitate toward older petrol variants with established maintenance networks, while fleet operators absorb premiums for younger electrified units.
Supply Chain Analysis
Germany, Belgium, and the Netherlands anchor wholesale auction infrastructure and cross-border logistics hubs for European used vehicle redistribution. Inventory sourcing draws from corporate fleet rotations, lease returns, and trade-in cascades from digital retail platforms. Single-source vulnerability concentrates in pan-European fulfillment networks where AUTO1 Group SE and similar operators control algorithmic pricing engines. Distribution runs through layered channels: auction-to-dealer for institutional volume, direct platform-to-consumer for younger stock, and independent dealer networks for price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from mobility-as-a-service platforms that convert ownership demand into subscription utilization, eroding the retail buyer base for traditional used vehicle channels.
For Market Incumbents: Fortify certified pre-owned battery programs with manufacturer-backed residual guarantees to defend against pure-play digital platforms. Deepen inspection infrastructure for electrified powertrains to offset diagnostic technician scarcity. Lock in fleet disposal relationships with corporate operators rotating battery-electric vehicles every twenty-four to thirty-six months.
For New Entrants and Emerging Players: Lead with blockchain-based provenance systems in Belgian and Dutch wholesale exchanges where trust-cost compression unlocks cross-border sourcing previously dominated by scaled networks. Target Poland and Czechia with battery health certification services where charging infrastructure gaps create hesitant buyer segments. Structure home delivery logistics and app-based trade-in triggers to capture younger urban cohorts in Amsterdam and Copenhagen.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because algorithmic pricing and logistics automation favor scaled platforms over fragmented independent dealer networks. Acquisition targets should combine physical inspection infrastructure with digital retail capabilities. Watch battery state-of-health protocol standardization across France, Germany, and Italy as the inflection signal for electric used vehicle liquidity unlock.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Pre-Owned Battery Program | Manufacturer-backed residual guarantees unlock hesitant electric vehicle buyers in charging-constrained markets. |
| Pan-European Logistics Automation | Proprietary fulfillment infrastructure compresses delivery costs against established physical dealer networks. |
| Blockchain Provenance Integration | Immutable service records linked to VIN registries miniaturize trust costs in cross-border transactions. |
| REACH Compliance Documentation | Early investment in interior material traceability positions sellers ahead of ECHA enforcement windows. |
| Fleet Disposal Relationship Lock | Corporate and ride-hailing rotations flood exchanges with nearly-new units carrying manufacturer warranties. |
Methodological Framework
A standing panel of fleet procurement managers, dealership operations directors, digital platform pricing analysts, and aftermarket service heads provided ongoing calibration against transaction flow data. Primary fieldwork combined structured interviews with secondary validation from vehicle registration databases, auction transaction records, and EU regulatory filings. Bottom-up volume triangulation across vehicle age, fuel type, and sales channel segments was cross-checked against top-down macroeconomic indicators.
Consistency checks validated projections against external benchmarks including IHS Markit registration data and national transport authority statistics. The analytical framework modeled demand across vehicle type, fuel architecture, sales channel, and age category dimensions throughout the forecast period. CAGRs were derived from segment-level growth trajectories weighted by base-year volume contributions, with electric powertrain adoption curves and low-emission zone expansion timelines as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside EU Green Deal implementation pace or battery certification protocol harmonization would require recalibration. Forecasts reflect assumptions around fleet electrification rotation rates, REACH enforcement intensity, and semiconductor supply normalization. Recalibration cycles align with material shifts in emission target deadlines, charging infrastructure deployment, and algorithmic pricing engine adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
GCC Used Car Market
Used Vehicles
Spain Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Vintage Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
Switzerland Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Italy Used Car Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Thailand Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
South Korea Used Car Market