
 UAE Certified Pre-Owned Car Market | 2026-2036
UAE Certified Pre-Owned Car Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Certified Pre-Owned Car Market Intelligence
Young professional buyers is bifurcating away from traditional fleet purchasers as the dominant growth archetype in the UAE certified pre-owned car channel. Al-Futtaim Automall leverages its multi-brand dealership network to control inventory sourcing across Emirates. Signature Cars differentiates through specialized luxury certification programs targeting high-net-worth segments. Alba Cars sustains competitive positioning via digital-first inspection transparency and online reservation workflows.
Certified pre-owned vehicles in the UAE undergo multi-point mechanical and cosmetic inspection against manufacturer-specific standards, with full service history verification and extended warranty coverage serving as core functional parameters that de-risk secondary ownership. SUV certification dominates transaction value given family-oriented buyer profiles and regional terrain preferences, while electric and hybrid segments within fuel type classification represent the fastest-growing margin pools as charging infrastructure matures. Online platforms within market channel segmentation are capturing disproportionate growth by collapsing search and financing friction for digitally native buyers.
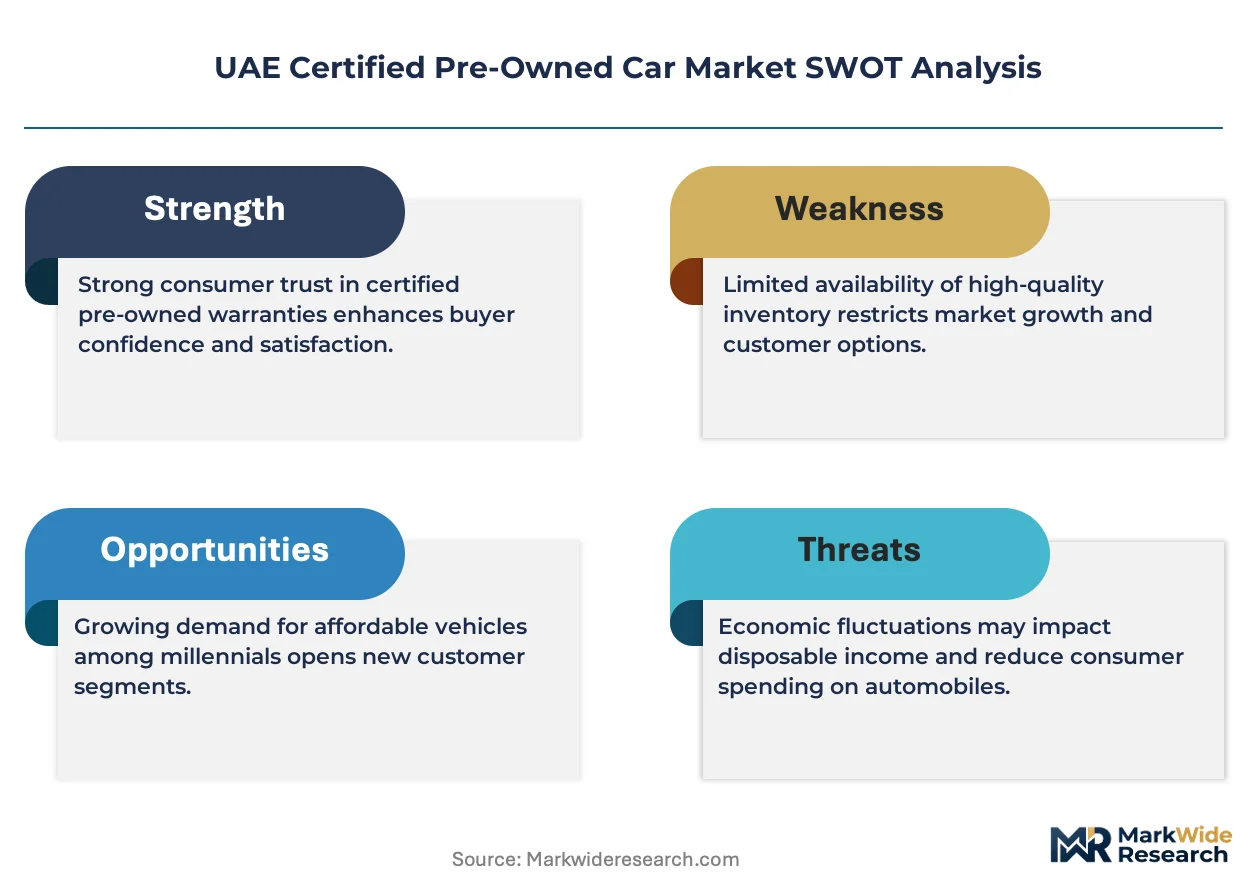
MOHAP and the UAE's national automotive standards body shape market access through mandatory roadworthiness certification and odometer verification protocols that filter substandard inventory from circulation. The Emirates Authority for Standardization and Metrology enforces technical compliance benchmarks that certified dealers must maintain for program eligibility. Stakeholders must monitor how evolving emissions testing requirements and digital title transfer systems reshape competitive barriers for private sellers versus institutional certifiers.
Market Dynamics
Digital inspection transparency is compressing transaction timelines across the UAE certified pre-owned car channel, collapsing traditional dealer-buyer information asymmetries through real-time condition reporting and blockchain-verified service histories.
Growth Catalysts
- MOHAP Roadworthiness Mandates:Mandatory multi-point inspection protocols elevate buyer confidence and filter substandard inventory from circulation, institutionalizing quality benchmarks that private sellers cannot replicate.
- Young Professional Demand:Expatriate career entrants prioritize late-model certified SUVs with verified maintenance records over new vehicle depreciation exposure, expanding the addressable buyer base beyond traditional fleet purchasers.
- EV Charging Infrastructure:Mature fast-charging networks across Dubai and Abu Dhabi reduce range anxiety for certified pre-owned electric vehicle acquisition, unlocking margin-rich hybrid and battery-electric inventory categories.
Market Restraints
- Inventory Sourcing Concentration:Three institutional dealer networks control the majority of off-lease volume from luxury OEMs, constraining independent certifiers' access to desirable late-model supply.
- Extended Warranty Cost Escalation:Powertrain coverage for certified electric vehicles requires specialized technician training and battery diagnostic equipment, inflating program operating costs versus internal combustion equivalents.
- Emirates Authority for Standardization Compliance:Evolving technical benchmarks for odometer verification and accident-history disclosure impose recurring certification system investments that smaller dealers struggle to absorb.
Strategic Opportunities
- Ras Al Khaimah and Fujairah Penetration:Northern Emirates exhibit certified pre-owned vehicle penetration gaps of 40-60% below Dubai levels, presenting first-mover expansion corridors for digital-native platforms.
- Subscription-to-Ownership Pathways:Flexible certified vehicle subscription models convert short-term users to long-term certified buyers, capturing lifetime value through embedded financing and service bundling.
- Digital Title Transfer Modernization:Federal initiatives streamlining ownership documentation reduce transaction friction from days to hours, accelerating inventory velocity for platforms with integrated RTA connectivity.
Industry Challenges
- EV Battery Health Assessment:Accurate state-of-health diagnostics for lithium-ion packs require proprietary manufacturer data access that certified dealers frequently lack, creating warranty exposure and pricing uncertainty.
- Cross-Emirate Regulatory Harmonization:Variations in RTA inspection standards between Dubai, Abu Dhabi, and Sharjah complicate multi-branch inventory management and customer service consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Certified Pre-Owned Car Market |
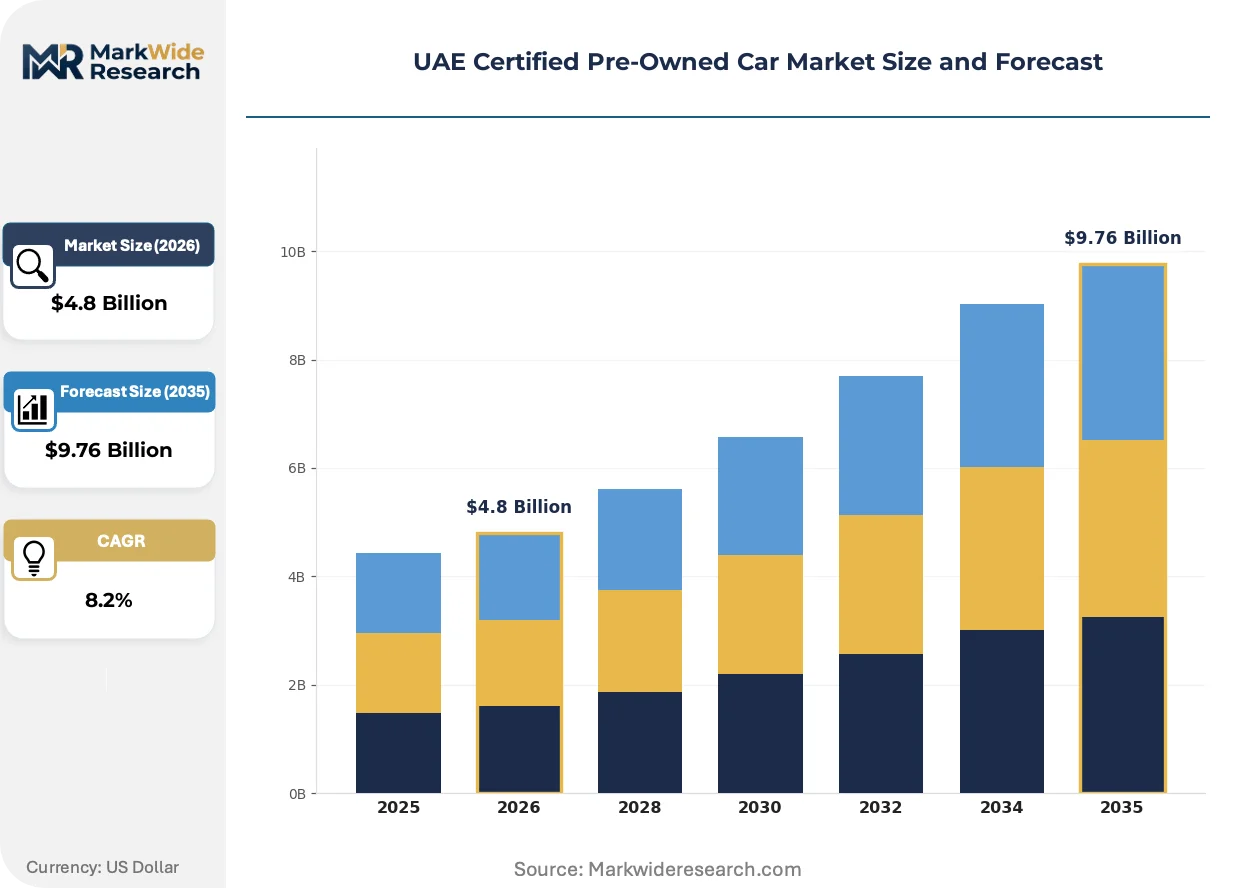
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Coupe Age Group: Less than 1 year, 1-3 years, 3-5 years, More than 5 years Fuel Type: Petrol, Diesel, Hybrid, Electric Market Channel: Online Platforms, Dealerships, Auctions, Private Sellers |
| Companies Covered | Signature Cars, Blackline Motor Company, Approved Automotive, The Elite Cars, Expat Motors, Al Tayer Motors, Alba Cars, Auto24, Al-Futtaim Automall, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Certified Pre-Owned Car Market Strategic Shifts & Innovations
Artificial intelligence is penetrating vehicle condition assessment workflows, replacing subjective human appraisal with standardized damage detection and predictive maintenance scoring that compresses certification timelines and expands buyer trust.
Computer vision systems trained on manufacturer defect databases now automate exterior and interior damage documentation, displacing traditional manual inspection teams at high-volume certification centers. Al-Futtaim Automall and Signature Cars have deployed these systems across Dubai facilities, cutting per-vehicle assessment time from 90 minutes to 22 minutes while expanding throughput capacity.
MOHAP and the Emirates Authority for Standardization and Metrology are tightening odometer rollback detection through mandatory digital mileage verification against manufacturer service records. This regulatory friction is eliminating grey-market import vehicles with tampered histories from certified channels, redirecting buyer demand toward institutional dealers with verified provenance pipelines and compressing private seller competitiveness.
Subscription-based vehicle access is fragmenting traditional ownership patterns among expatriate professionals who prioritize flexibility over asset accumulation. Digital platforms offering month-to-month certified vehicle subscriptions are capturing demand that previously flowed into 24-36 month lease contracts, with conversion algorithms identifying ownership-ready subscribers and migrating them into certified purchase financing. This behavioral pivot is most pronounced in Dubai's technology and consulting sectors where assignment durations average 18-24 months.
UAE Certified Pre-Owned Car Market Segmentation
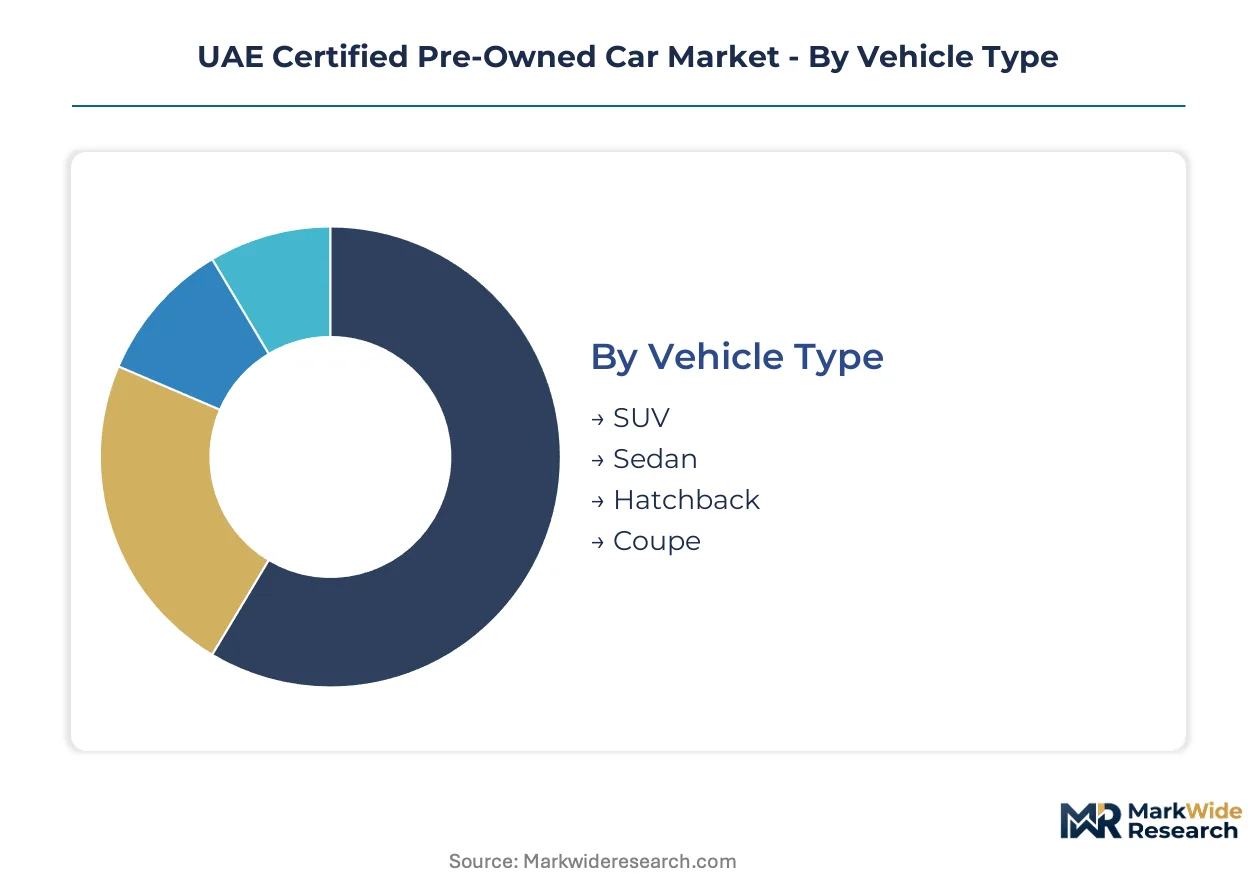
Segmentation in the UAE certified pre-owned car market reveals distinct purchasing patterns across vehicle configuration, ownership duration, propulsion technology, and transaction modality. Each dimension carries specific regulatory implications and margin structures that shape competitive positioning for institutional certifiers.
Vehicle Type:
SUVs face intensifying substitution pressure from electrified crossovers and extended-range hybrids as charging infrastructure matures across Dubai and Abu Dhabi.
- SUV:Three-row and mid-size configurations dominate family-oriented purchases, with all-wheel-drive certification commanding premium positioning. Demand concentrates among expatriate households in Dubai's suburban corridors where terrain versatility and passenger capacity outweigh operating cost considerations.
- Sedan:Executive and mid-size segments retain corporate fleet relevance, though volume is compressing as younger buyers migrate toward elevated driving positions. Abu Dhabi's government and diplomatic procurement channels sustain institutional demand for certified executive sedans with verified service histories.
- Hatchback:Compact urban configurations serve single professionals and secondary household vehicles, with certification programs emphasizing parking-assist technology and city-mileage verification.
- Coupe:Two-door performance and luxury variants occupy niche positioning, requiring specialized cosmetic inspection protocols for aerodynamic body panels and sport-tuned suspension components.
SUV retains volume leadership; electric-adjacent coupe variants hold the steepest expansion curve.
Age Group:
Cost tier stratification creates divergent certification economics, with newer inventory requiring lighter reconditioning investment but carrying higher acquisition premiums.
- Less than 1 year:Near-new off-lease volume from luxury OEM fleet programs supplies the certification pipeline. These units bypass major reconditioning cycles, compressing time-to-retail and preserving margin.
- 1-3 years:The core certified sweet spot balances depreciation absorption with remaining manufacturer warranty coverage. Dubai-based digital platforms prioritize this cohort for subscription-to-ownership conversion pathways.
- 3-5 years:Extended warranty attachment rates peak here as factory coverage expires, creating ancillary revenue pools for dealer service departments.
- More than 5 years:Entry-price positioning for first-time buyers and labor-category expatriates, with MOHAP roadworthiness mandates filtering vehicles requiring substantial mechanical refurbishment.
1-3 years commands transaction value concentration; less than 1 year segments gain share fastest as lease return volumes expand.
Fuel Type:
Application-driven segmentation separates daily commuter economics from performance-oriented consumption patterns, with regulatory pressure reshaping long-term residual value projections.
- Petrol:Dominates current certified inventory, with V6 and four-cylinder configurations serving divergent buyer profiles. Sharjah and northern Emirates maintain stronger petrol preference due to charging infrastructure gaps.
- Diesel:Heavy SUV and commercial-adjacent applications sustain demand, though Emirates Authority for Standardization emissions testing protocols are tightening eligibility criteria.
- Hybrid:Toyota and Honda systems lead certified availability, with battery health diagnostics now standard in Al-Futtaim Automall certification workflows. Range anxiety mitigation without charging dependency attracts risk-averse transition buyers.
- Electric:Tesla and emerging Chinese OEM volume is entering secondary channels, requiring proprietary diagnostic equipment that constrains certification to flagship Dubai and Abu Dhabi facilities.
Petrol maintains installed-base dominance; electric vehicles are expanding most quickly as manufacturer battery warranty transferability clarifies.
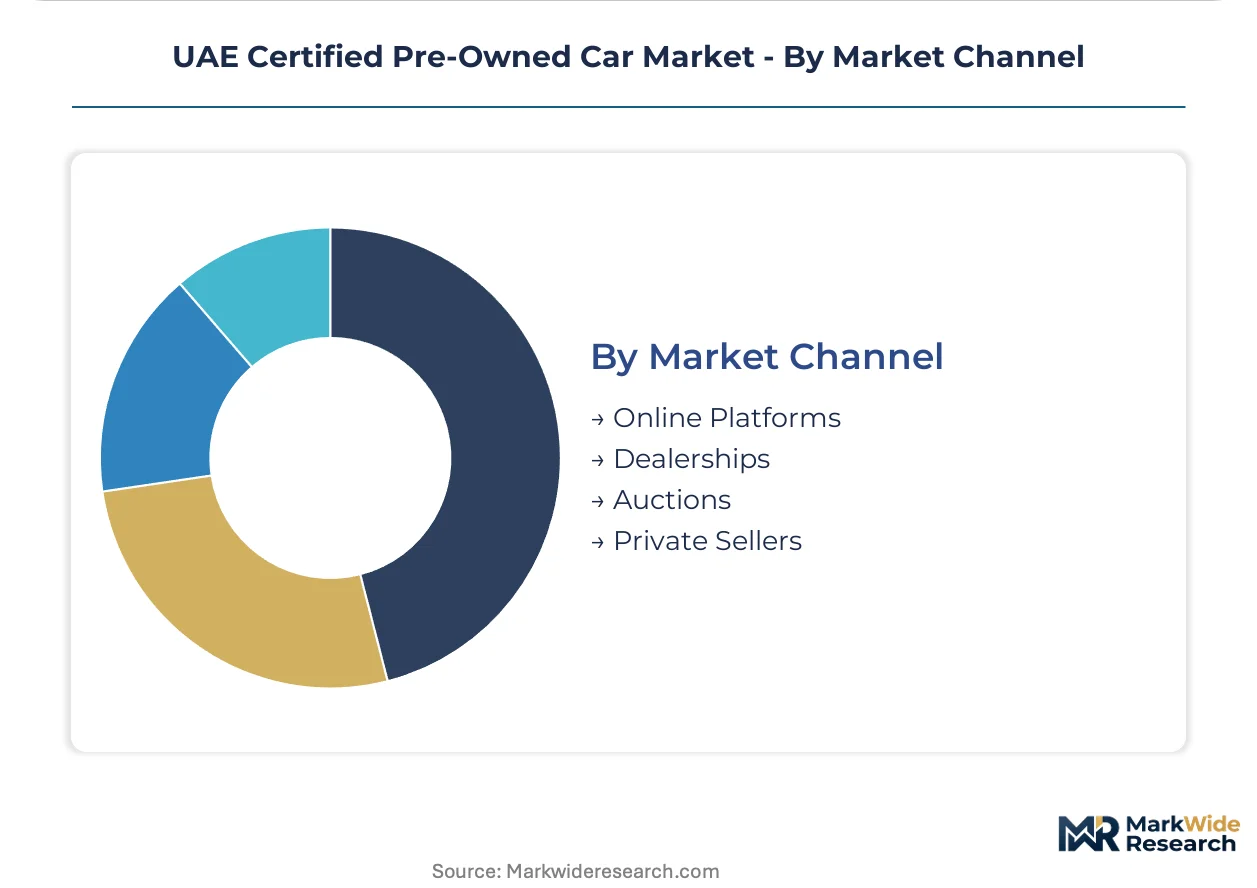
Market Channel:
Customer type fragmentation separates digitally native purchasers from relationship-driven buyers, with geography determining channel accessibility across Emirates.
- Online Platforms:End-to-end digital workflows with RTA-integrated title transfer and embedded financing collapse transaction friction. Ras Al Khaimah and Fujairah penetration gaps present expansion corridors for platform operators.
- Dealerships:Multi-brand certifiers control manufacturer-backed warranty programs and off-lease supply pipelines. Physical inspection and test drive availability sustain preference among risk-averse family purchasers.
- Auctions:Institutional volume clearing for dealer inventory acquisition, with condition grading standardization improving price discovery transparency.
- Private Sellers:MOHAP odometer verification mandates and digital service history requirements are compressing competitiveness against certified alternatives.
Dealerships retain volume leadership; online platforms gain share fastest as RTA connectivity streamlines cross-Emirate transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Off-lease inventory pipelines concentrate within Dubai and Abu Dhabi, where manufacturer-backed certification programs and RTA-integrated digital infrastructure create institutional barriers for peripheral competitors.
Dubai
Young professionals and expatriate families drive certified SUV demand across suburban corridors like Dubai Marina and Arabian Ranches. MOHAP roadworthiness mandates filter substandard inventory before it reaches retail channels. Al-Futtaim Automall and Signature Cars anchor multi-brand certification capacity in Dubai Investment Park and Al Quoz.
Abu Dhabi
Government and diplomatic procurement sustains executive sedan certification volumes through institutional fleet return programs. The Emirates Authority for Standardization and Metrology enforces technical compliance benchmarks that elevate program eligibility barriers. Yas Island and Mussafah host flagship facilities serving high-net-worth buyer segments.
Sharjah
Petrol preference persists among cost-conscious buyers due to charging infrastructure gaps versus Dubai and Abu Dhabi. RTA inspection standards vary from Dubai protocols, complicating cross-Emirate inventory transfers. Industrial zones along Emirates Road concentrate independent certifier operations serving labor-category expatriates.
Northern Emirates
Ras Al Khaimah and Fujairah exhibit certified pre-owned penetration gaps of 40-60% below Dubai levels, presenting expansion corridors for digital-native platforms. Limited local certification infrastructure forces buyers toward Dubai-based inventory sources. Federal digital title transfer initiatives aim to collapse transaction friction for remote purchasers.
UAE Certified Pre-Owned Car Market Key Industry Players
Concentration sits with multi-brand dealership networks that control manufacturer off-lease pipelines and warranty program eligibility. Three institutional archetypes dominate: luxury-focused specialists, volume-driven multi-brand operators, and digital-first platforms. Competitive moves center on AI-powered inspection automation and subscription-to-ownership pathway development.
Within the multi-brand dealership tier, Al-Futtaim Automall and Al Tayer Motors exemplify scale-driven certification capacity, while Signature Cars occupies specialist positioning in luxury segments. Alba Cars represents digital-native platform architecture with integrated RTA connectivity. These anchors illustrate how warranty-backed provenance and inspection transparency separate institutional certifiers from private seller alternatives.
| Leading Market Players |
|---|
| Signature Cars |
| Blackline Motor Company |
| Approved Automotive |
| The Elite Cars |
| Expat Motors |
| Al Tayer Motors |
| Alba Cars |
| Auto24 |
| Al-Futtaim Automall |
| Others |
Cost & Logistics Intelligence
Forty-five to sixty days of inventory turnover at flagship Dubai facilities concentrates pricing power with multi-brand dealership networks that control off-lease pipelines from luxury OEMs. This lead-time compression elevates institutional certifiers above private sellers who cannot match warranty-backed provenance or MOHAP-mandated inspection transparency.
Pricing Analysis
MOHAP roadworthiness mandates dictate the pricing tier structure across the UAE certified pre-owned car channel, separating warranty-backed inventory from grey-market alternatives. Three-tier pricing stratifies across manufacturer-certified premium, dealer-certified standard, and independent economy levels, with certification grade and extended warranty coverage serving as primary differentiation drivers. Cost compression in the electric vehicle tier is intensifying because battery health diagnostics require proprietary equipment access that inflates program operating costs. Labor-category expatriates in Sharjah and northern Emirates exhibit highest price sensitivity, while high-net-worth segments in Abu Dhabi prioritize verified provenance over absolute cost.
Supply Chain Analysis
Jebel Ali port congestion and container availability fluctuations on Asia-Gulf trade lanes periodically disrupt inbound parts flows for reconditioning centers. Geographic supply concentration draws from Japan, South Korea, and Germany for precision components and diagnostic equipment essential to certification workflows. Raw material dependencies center on lithium-ion cells, automotive-grade semiconductors, and specialized lubricants formulated for regional climate conditions. Single-source vulnerability persists for manufacturer-specific battery diagnostic tools that constrain electric vehicle certification to flagship facilities. Distribution runs through RTA-integrated dealership networks and digital platforms with federal title transfer connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital inspection automation and federal title transfer modernization are compressing transaction timelines and collapsing traditional information asymmetries, positioning early adopters to capture disproportionate share expansion across the analysis window.
For Market Incumbents: Fortify control over off-lease supply pipelines through exclusive manufacturer partnership renewals and backward integration into fleet management services. Al-Futtaim Automall and Signature Cars should accelerate AI-powered condition assessment deployment to compress per-vehicle certification timelines below twenty minutes, defending margin position against digital-native platforms that lack physical inspection infrastructure.
For New Entrants and Emerging Players: Subscription-to-ownership pathway gaps in Ras Al Khaimah and Fujairah present first-mover expansion corridors where certified penetration trails Dubai by forty to sixty percent. Digital-native platforms should prioritize embedded financing and service bundling to convert short-term subscribers into long-term certified buyers, leveraging RTA connectivity to collapse cross-Emirate transaction friction.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because subscription-based vehicle access is fragmenting traditional ownership patterns among expatriate professionals. Acquisition targets should feature integrated RTA connectivity and proprietary inspection technology rather than pure inventory scale. The signal to watch is federal harmonization of emissions testing requirements that would elevate compliance costs for subscale operators and accelerate industry consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Inspection Automation | Computer vision deployment at Al-Futtaim Automall cuts assessment time from ninety to twenty-two minutes. |
| Subscription-to-Ownership Pathway | Flexible certified vehicle subscriptions convert short-term Dubai technology sector users into long-term buyers. |
| RTA-Integrated Digital Title Transfer | Federal initiatives collapsing ownership documentation from days to hours accelerate inventory velocity. |
| EV Battery Diagnostic Capability Buildout | Proprietary lithium-ion state-of-health tooling unlocks margin-rich electric vehicle certification categories. |
| Northern Emirates Geographic Expansion | Ras Al Khaimah and Fujairah penetration gaps present forty to sixty percent expansion headroom. |
Research Approach
Cross-validation between dealership operations executives and MOHAP regulatory affairs specialists anchors the qualitative findings, with secondary triangulation against Emirates Authority for Standardization technical bulletins and RTA transaction databases. Primary fieldwork encompassed certified pre-owned vehicle operations directors, multi-brand dealership procurement leads, digital platform product managers, and automotive finance underwriters. Secondary sources included federal regulatory filings, vehicle registration data, OEM fleet return disclosures, and charging infrastructure development reports. Bottom-up inventory flow modeling and top-down consumer expenditure analysis were reconciled to establish market size boundaries.
Sensitivity analysis around electric vehicle adoption velocity and subscription model conversion rates informs the projection framework across the analysis window. Segmentation dimensions encompass vehicle configuration, ownership duration cohorts, propulsion technology, and transaction modality with geographic granularity at Emirate level. CAGRs were derived from trend extrapolation of off-lease pipeline volumes, consumer finance penetration, and digital platform transaction share gains. Key forecast inputs include manufacturer battery warranty transferability policies and federal digital infrastructure deployment timelines.
Forecasts assume regulatory continuity in MOHAP inspection protocols and Emirates Authority for Standardization compliance benchmarks; material policy shifts would require re-modeling. Specific risks include cross-Emirate regulatory harmonization failures, EV battery health assessment standardization delays, and macroeconomic shocks to expatriate employment patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Sri Lanka Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
UAE Used Cars Industry Market
Used Vehicles
Qatar Used Car Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
Europe Used Car Market
Used Vehicles
Switzerland Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
South Africa Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Germany Used Car Market