
 Used Cars in Russia Market | 2026-2036
Used Cars in Russia Market Size, Share, and Industry Trends Forecast 2026-2036
Used Cars in Russia Market Insights
EU sanctions on automotive exports to Russia is hardening the supply structure for used vehicle imports from Europe. ROLF leverages its established dealer network across Moscow and Saint Petersburg to sustain certified pre-owned sales. Klyuchavto anchors its position through backward integration into refurbishment centers. Avtomir competes by dominating digital auction channels for trade-in vehicles.
A used car in Russia denotes a previously registered passenger vehicle resold through dealer, auction, or peer-to-peer channels, typically evaluated by mileage, accident history, and compliance with GOST R 52653 technical inspection standards; its commercial purpose centers on affordable mobility for buyers excluded from shrinking new-vehicle supply. Sedan and SUV segments occupy the largest transaction volumes due to established servicing infrastructure and parts availability. The certified pre-owned condition tier captures margin concentration as dealer groups invest in warranty-backed refurbishment to differentiate from as-is gray-market imports. Electric and hybrid fuel types remain nascent but attract enthusiast buyer segments seeking technology novelty amid limited new EV supply.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) enforces GOST certification for imported used vehicles, while the Eurasian Economic Commission harmonizes customs duties and recycling fees across member states. The Central Bank of Russia monitors auto loan portfolios, with rate policy directly influencing monthly payment affordability for budget-conscious and first-time buyer segments. Stakeholders must track regulatory adjustments to recycling fee scales and parallel import corridor permissions as primary determinants of inventory cost and competitive positioning.
Market Dynamics
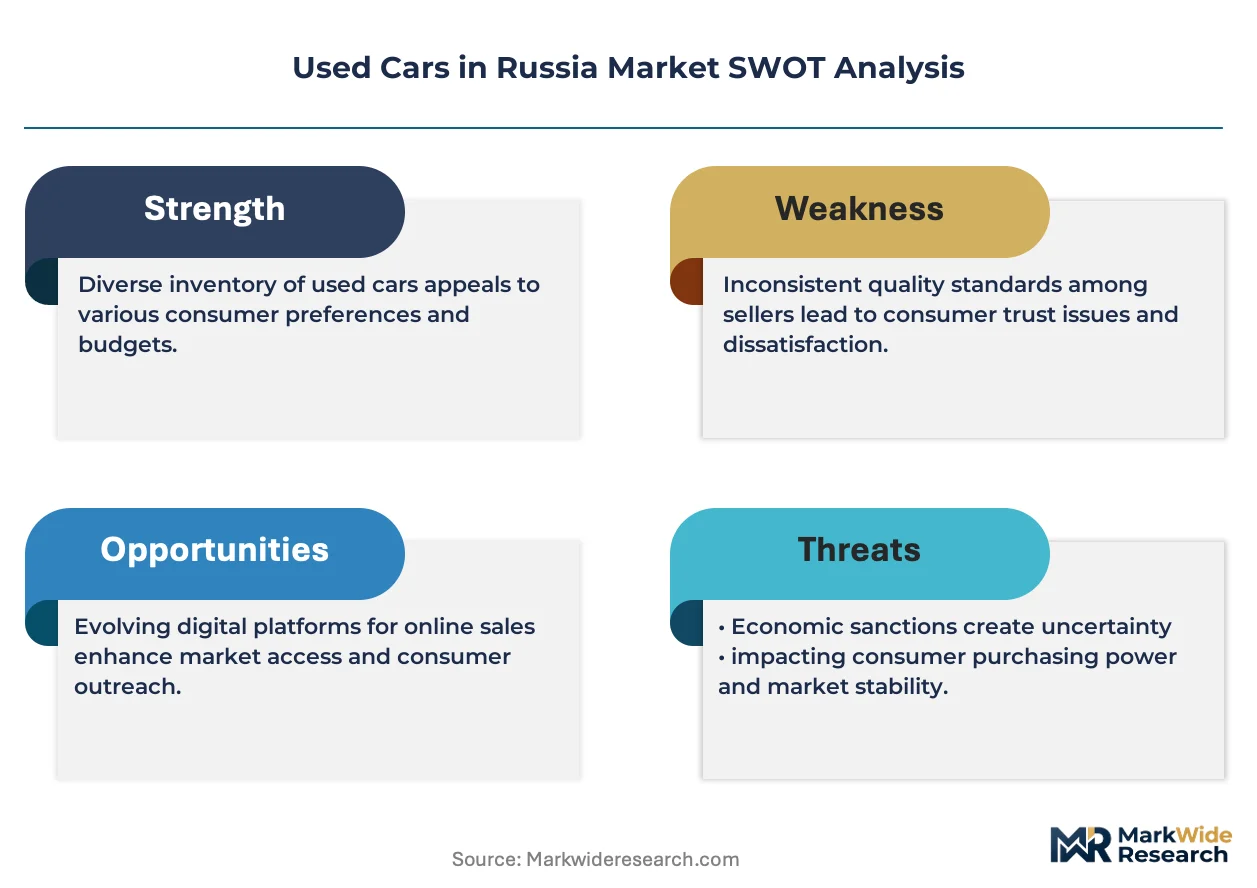
Sanctions-driven supply compression has restructured vehicle procurement patterns across Russia, redirecting fleet operators and individual buyers toward certified pre-owned channels as parallel import corridors face tightening customs scrutiny.
Growth Catalysts
- Fleet Modernization Pressure:Logistics operators in Moscow and Saint Petersburg are expanding pre-owned SUV and sedan procurement to maintain service coverage as new vehicle pipelines constrict.
- Rosstandart GOST R 52653:Mandatory technical inspection standards for imported used vehicles are filtering gray-market inventory and elevating certified pre-owned transaction volumes through compliant dealer networks.
- Eurasian Economic Union Harmonization:Unified recycling fee scales and customs duty structures across member states are reducing cross-border arbitrage complexity for regional importers.
Market Restraints
- Import Corridor Concentration:Reliance on limited parallel import pathways through Kazakhstan and Belarus creates bottleneck vulnerability when border enforcement tightens.
- Currency Volatility:Ruble fluctuation against euro and dollar denominations directly compresses margin structures for dealers holding foreign-denominated inventory.
- Spare Parts Scarcity:European OEM supply restrictions extend to replacement components, elevating total cost of ownership for vehicles lacking domestic aftermarket support.
Strategic Opportunities
- Central Federal District Saturation:Moscow's dealer infrastructure density enables premium certified pre-owned positioning unavailable in peripheral regions.
- Digital Auction Platforms:Online trade-in and wholesale channels are capturing volume from traditional physical auction yards, reducing intermediation layers.
- Electric Vehicle Niche:Limited new EV supply is creating secondary market appetite for imported used hybrids and battery electrics among technology-focused buyer segments.
Industry Challenges
- Refurbishment Skill Shortage:Certified pre-owned warranty programs require diagnostic technicians trained on multi-brand electronic systems, a capability pool concentrated in major urban centers.
- Compliance Timeline Compression:Rosstandart type-approval documentation for imported vehicles faces processing delays that extend inventory holding periods and working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Cars in Russia Market |
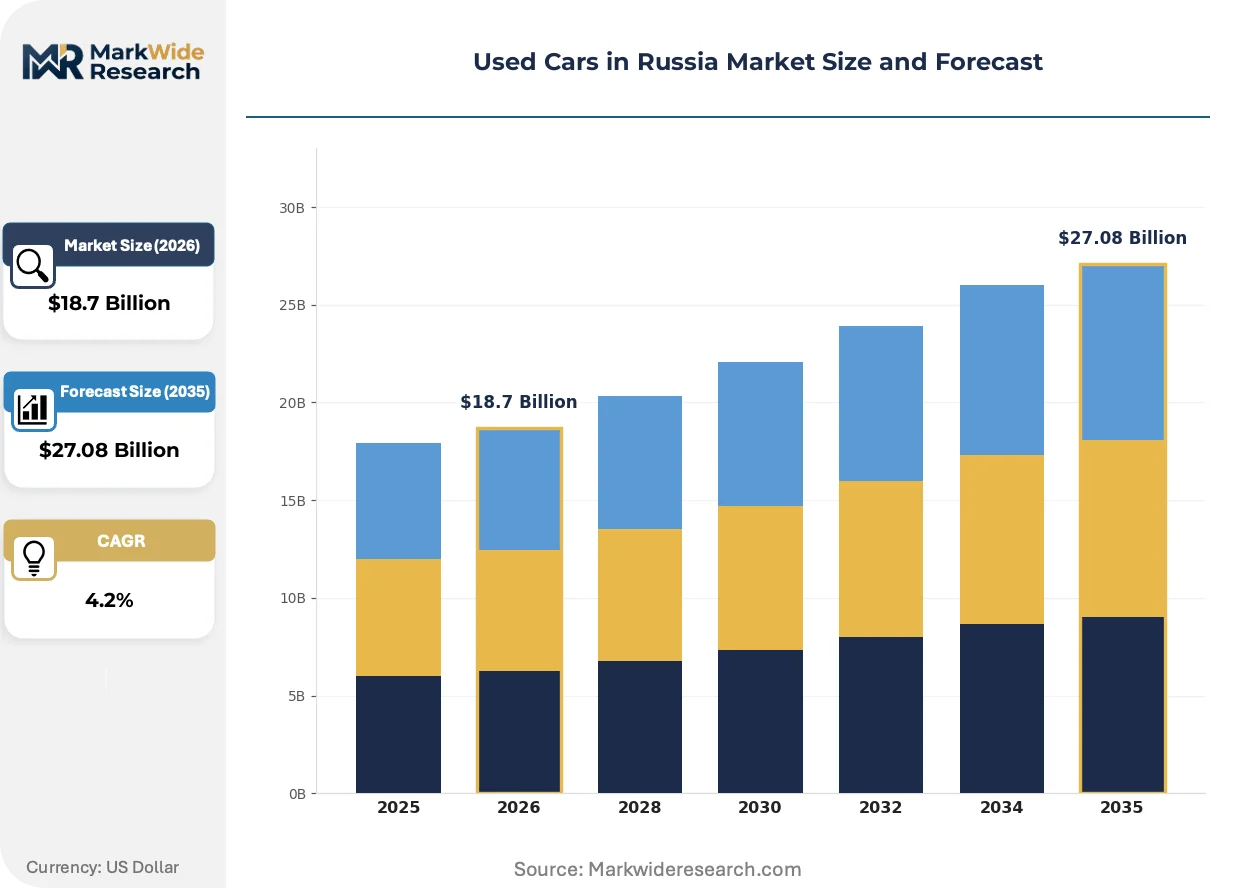
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Pickup Condition: Certified Pre-Owned, Warranty Available, As-Is, Damaged Fuel Type: Petrol, Diesel, Electric, Hybrid Buyer Profile: First-Time Buyers, Family Buyers, Budget-Conscious, Enthusiasts |
| Companies Covered | Drome, Favorit Motors, ROLF, Avtomir, Klyuchavto, Fresh Auto, Gesner Auto, Major, Inchcape Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Cars in Russia Market Trends and Innovations
Digital verification tools and regulatory compliance automation are restructuring how vehicle provenance is established and transacted across Russian used car channels.
Blockchain-based ownership history systems are consolidating trust mechanisms in peer-to-peer transactions. Individual buyers in Moscow and Saint Petersburg are adopting VIN-linked digital records at accelerating rates. Dealer groups are consolidating market position by integrating these verification layers into certified pre-owned warranty offerings.
Rosstandart enforcement of GOST R 52653 inspection protocols is tightening eligibility for official resale channels. Importers must now document mileage verification and accident history through approved laboratories. Siberian and Far Eastern Federal Districts are responding by developing regional certification partnerships to reduce Moscow-centric processing delays.
Fleet procurement patterns are rotating toward subscription and operational lease structures for used vehicles. Logistics operators are displacing outright purchase models with usage-based contracts that bundle maintenance and residual value risk. This shift concentrates most visibly in the Central Federal District where dealer networks possess balance sheet capacity to underwrite such arrangements.
Used Cars in Russia Market Segmentation
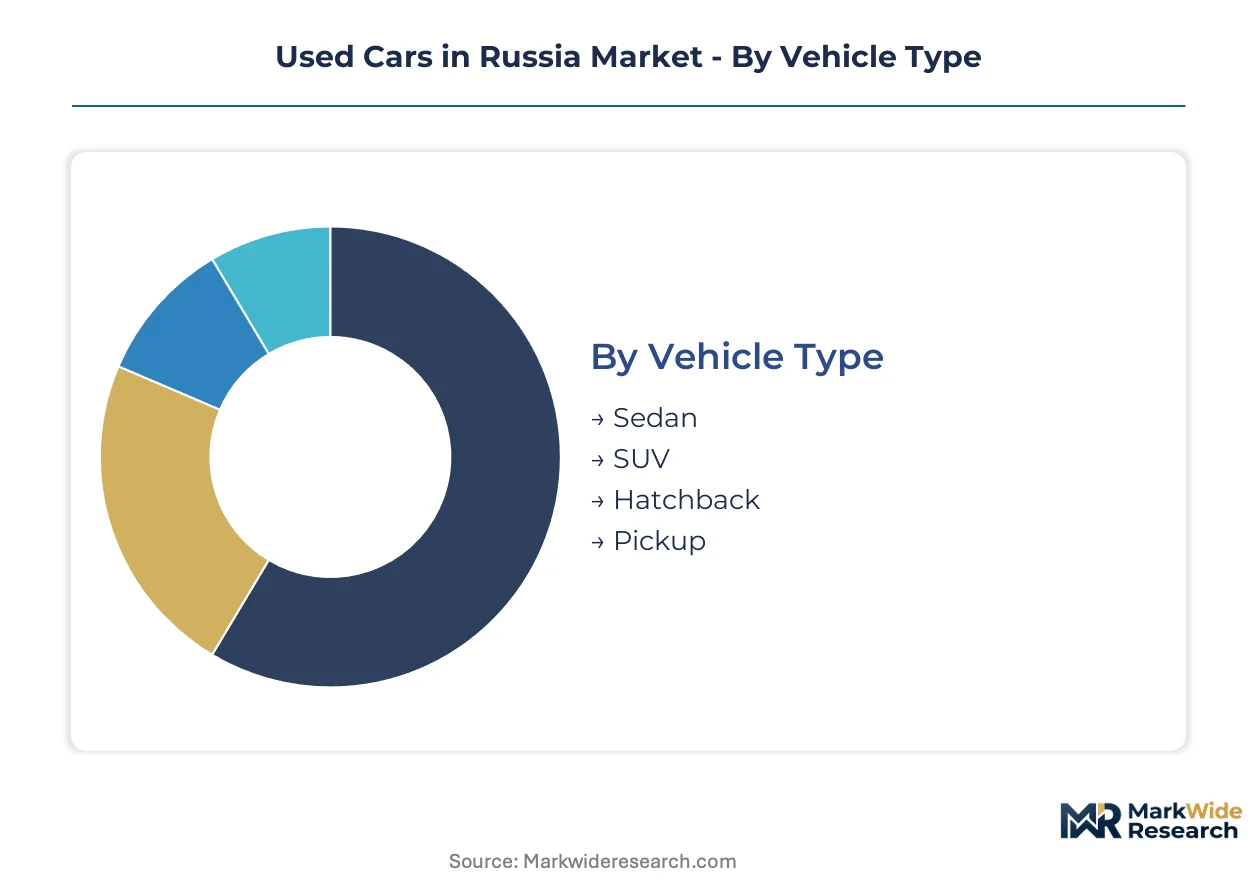
Segmentation in Russia's used car market reveals how sanctions-driven supply compression has fragmented demand across distinct procurement channels. Buyers sort themselves by risk tolerance, technical capability, and access to compliant dealer networks rather than simple price sensitivity.
Vehicle Type:
Supply concentration favors body styles with established domestic aftermarket support and cross-border parts availability.
- Sedan:Three-box passenger vehicles dominate transaction volumes through certified dealer channels. Moscow and Saint Petersburg fleet operators prioritize sedans for logistics contracts due to proven maintenance infrastructure and GOST R 52653 compliance documentation availability.
- SUV:Sport utility vehicles command premium positioning in the Central Federal District where dealer groups underwrite warranty-backed refurbishment programs. Regional importers face elevated recycling fee burdens when sourcing SUVs through parallel import corridors.
- Hatchback:Compact two-box designs attract budget-conscious buyers in peripheral Federal Districts with limited certified pre-owned infrastructure.
- Pickup:Light commercial cab configurations serve Siberian and Far Eastern operators requiring all-terrain capability where road infrastructure deteriorates seasonally.
Today's leader: Sedan. Tomorrow's challenger: SUV.
Condition:
Margin structures diverge sharply based on documentation completeness and warranty backing.
- Certified Pre-Owned:Dealer-refurbished vehicles with documented GOST R 52653 inspection and limited warranty coverage. Rosstandart enforcement is filtering gray-market competition and elevating transaction premiums in Moscow's dense dealer network.
- Warranty Available:Third-party or dealer-backed protection plans covering powertrain components. First-time buyers in the Central Federal District gravitate toward this tier as a risk mitigation mechanism against undisclosed mechanical defects.
- As-Is:Unwarranted vehicles sold without post-transaction recourse, dominating peer-to-peer channels.
- Damaged:Accident-impaired inventory requiring reconstruction, concentrated in wholesale auction yards serving refurbishment specialists.
Certified Pre-Owned captures current margin concentration. Warranty Available is climbing the fastest as risk-averse buyer segments expand.
Fuel Type:
Refueling infrastructure and parts availability determine geographic penetration patterns.
- Petrol:Internal combustion engines with spark ignition dominate rural and small-city transactions where service technician training concentrates on conventional powertrains.
- Diesel:Compression-ignition variants sustain demand among long-distance fleet operators despite European OEM supply restrictions on replacement injection components.
- Electric:Battery-powered vehicles attract technology-focused enthusiasts in Moscow and Saint Petersburg where charging infrastructure density supports daily usability.
- Hybrid:Dual-powertrain configurations bridge range anxiety concerns while offering novelty appeal to buyers excluded from shrinking new-vehicle supply.
Petrol retains volume leadership. Electric represents the steepest expansion trajectory among enthusiast buyer segments.
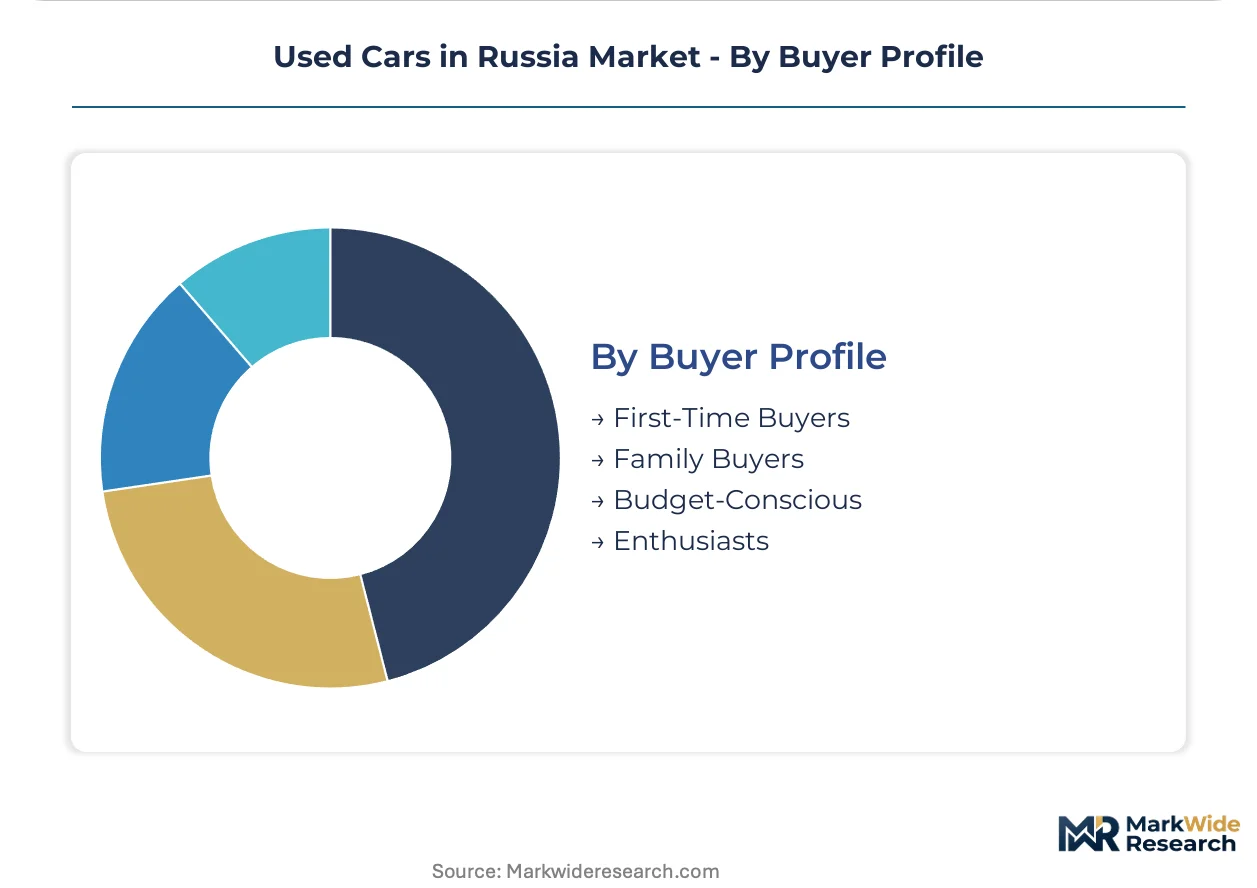
Buyer Profile:
Procurement sophistication varies with financial leverage and technical evaluation capacity.
- First-Time Buyers:Entry-level purchasers with limited credit history and minimal vehicle assessment experience. Central Bank of Russia rate policy directly shapes monthly payment affordability for this segment.
- Family Buyers:Multi-occupant households prioritizing safety ratings and cabin volume over performance specifications.
- Budget-Conscious:Price-sensitive purchasers accepting elevated mechanical risk in exchange for lower acquisition cost, concentrated in As-Is transaction channels.
- Enthusiasts:Technology-motivated buyers seeking specific powertrain configurations or performance characteristics, driving niche demand for imported used hybrids and electrics.
Family Buyers anchor current transaction volumes. First-Time Buyers are gaining share fastest as auto loan accessibility fluctuates with monetary policy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified diagnostic technicians and refurbishment specialists concentrate disproportionately in Russia's Central Federal District, creating a talent gradient that shapes regional market development patterns.
Central Federal District
Moscow anchors transaction volumes through dense dealer infrastructure and GOST R 52653 compliance laboratories. Rosstandart maintains its primary certification facilities in the capital, filtering gray-market inventory before official resale channels. Fleet operators in the Moscow metropolitan area rotate procurement toward subscription-based used vehicle contracts.
Northwestern Federal District
Saint Petersburg sustains premium certified pre-owned positioning through proximity to Baltic import corridors and established refurbishment centers. The Eurasian Economic Commission's harmonized customs duties reduce cross-border arbitrage complexity for regional importers sourcing from Belarus. Dealer groups in the city underwrite warranty-backed programs unavailable in peripheral districts.
Siberian Federal District
Novosibirsk and Krasnoyarsk concentrate demand for pickup configurations requiring all-terrain capability where road infrastructure deteriorates seasonally. Regional certification partnerships are developing to reduce Moscow-centric processing delays for GOST documentation. Local fleet operators prioritize diesel powertrains for long-distance logistics routes.
Far Eastern Federal District
Vladivostok functions as a secondary import gateway for Asian-sourced used vehicles, though Rosstandart enforcement creates compliance bottlenecks. The Central Bank of Russia's regional branches monitor auto loan portfolios with tighter scrutiny due to currency volatility exposure. Charging infrastructure density in the district remains insufficient for electric vehicle penetration.
Volga Federal District
Nizhny Novgorod and Kazan exhibit hatchback-dominant transaction patterns among budget-conscious buyers with limited certified pre-owned infrastructure. Recycling fee scales under Eurasian Economic Union harmonization elevate cost structures for SUVs sourced through parallel import corridors. Regional refurbishment skill shortages compress warranty program availability.
Used Cars in Russia Market Competitive Landscape
Capital-heavy dealer groups with captive refurbishment infrastructure compete with asset-light digital platforms and auction intermediaries. The vendor base stratifies across three tiers: integrated dealer networks underwriting certified pre-owned warranties, regional multi-brand aggregators, and peer-to-peer listing platforms. Dominant competitive moves include backward integration into refurbishment centers and digital auction channel consolidation.
Within the integrated dealer network tier, ROLF and Klyuchavto exemplify divergent strategic positioning. ROLF occupies a position anchored in Moscow and Saint Petersburg metropolitan density, while Klyuchavto represents backward integration into captive refurbishment capabilities. Avtomir sits within the digital-first archetype, concentrating auction channel dominance for trade-in vehicle sourcing.
| Leading Market Players |
|---|
| Drome |
| Favorit Motors |
| ROLF |
| Avtomir |
| Klyuchavto |
| Fresh Auto |
| Gesner Auto |
| Major |
| Inchcape Plc |
| Others |
Pricing and Supply Chain Analysis
Family-owned dealer networks across Russia's Central Federal District anchor both supply discipline and pricing power through captive refurbishment infrastructure and direct auction channel control. Their balance sheet capacity to hold GOST R 52653-compliant inventory creates tiered pricing separation between certified pre-owned warranties and gray-market as-is transactions.
Pricing Analysis
Bundled warranty-plus-refurbishment packages command premium positioning against unbundled as-is transactions in Moscow and Saint Petersburg. Pricing stratifies across certified pre-owned, warranty-backed, and as-is tiers based on GOST R 52653 documentation completeness and dealer brand reputation. Cost compression in the as-is tier is intensifying because currency volatility erodes margins for importers holding foreign-denominated inventory. First-time buyers exhibit highest price sensitivity and gravitate toward third-party warranty tiers as risk mitigation.
Supply Chain Analysis
Reverse-logistics flows for trade-in vehicles feed refurbishment centers in Moscow and Saint Petersburg before re-entering certified pre-owned channels. Supply draws from parallel import corridors through Kazakhstan and Belarus, with secondary flows from Asian sourcing via Vladivostok. Raw material dependencies center on European OEM spare parts, diagnostic equipment, and replacement electronics now restricted by sanctions. Single-source vulnerability concentrates in injection component supply for diesel powertrains. Distribution runs through digital auction platforms consolidating trade-in volume from traditional physical yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's used car market functions as a stable compounder where sanctions-driven new vehicle supply compression sustains steady demand migration toward certified pre-owned channels.
For Market Incumbents: Deepen backward integration into captive refurbishment centers to defend margin structures against gray-market price competition. Expand GOST R 52653 certification laboratory partnerships in Siberian and Far Eastern Federal Districts to reduce Moscow-centric processing delays that extend working capital cycles. For New Entrants and Emerging Players: Budget-conscious buyers in peripheral Federal Districts represent the most penetrable white-space target given limited certified pre-owned infrastructure. Target diesel pickup configurations serving Siberian logistics operators through regional refurbishment partnerships. Launch digital-first trade-in platforms with VIN-linked blockchain verification to bypass incumbent auction channel control. For Investors and Strategic Acquirers: Valuations sit cheapest among regional multi-brand aggregators lacking integrated refurbishment capabilities. Five-to-ten year viability hinges on Eurasian Economic Union recycling fee harmonization sustaining cross-border arbitrage economics. Monitor Rosstandart enforcement intensity and parallel import corridor permissions as primary inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refurbishment Centers | Captive GOST R 52653 compliance capacity filters gray-market competition and sustains warranty-backed premiums. |
| Digital Auction Platform Consolidation | Online trade-in channels disintermediate physical yards and concentrate volume for dealer network sourcing. |
| Regional Certification Partnership Development | Siberian and Far Eastern laboratory networks reduce Moscow-centric processing delays for imported inventory. |
| Subscription-Based Fleet Contract Expansion | Usage-based models bundle maintenance and residual risk for logistics operators in the Central Federal District. |
| Blockchain-Based Provenance Verification | VIN-linked digital records consolidate trust mechanisms in peer-to-peer transactions across metropolitan markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate market sizing and competitive positioning. Primary fieldwork engaged dealer group operations directors, Rosstandart certification laboratory managers, fleet procurement heads at logistics operators, and Central Bank of Russia regional lending officers. Secondary validation drew from Eurasian Economic Commission customs harmonization documents, Central Bank auto loan portfolio disclosures, vehicle registration databases, and recycling fee schedule amendments. Bottom-up transaction volume estimates and top-down macroeconomic anchoring were cross-referenced for consistency.
Segment-weighting approaches distributed forecast contributions across vehicle type, condition tier, fuel type, and buyer profile dimensions. CAGR derivation applied historical trajectory analysis and elasticity modeling against sanctions-adjusted new vehicle supply assumptions. Modeled inputs incorporated fleet operator procurement pattern shifts, Rosstandart enforcement intensity scenarios, and Eurasian Economic Union duty harmonization schedules across the projection horizon.
Underlying measurement precision varies by segment; certified pre-owned transactions in Moscow carry tighter precision than gray-market peer-to-peer flows in peripheral districts. Forecasts incorporate documented assumptions regarding recycling fee stability and parallel import corridor access. Practitioners should monitor Rosstandart type-approval processing timelines and Central Bank rate policy shifts for early signals of demand elasticity changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
South Korea Used Car Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
Nigeria Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
UAE Used Cars Industry Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
United States Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Sri Lanka Used Car Market