
 Canada Used Car Market | 2026-2036
Canada Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Used Car Market Insights
Certified automotive technician shortages across Ontario and British Columbia is reorganizing how dealers manage reconditioning throughput and inventory velocity. AutoCanada sustains coast-to-coast coverage through its multi-brand dealership network, while Kijiji Autos dominates peer-to-peer listing traffic with minimal transaction friction. Canada Drives differentiates by embedding digital financing pre-approval directly into its search-to-purchase workflow.
A used car denotes a previously registered motor vehicle offered for resale through commercial or private channels, typically assessed via odometer reading, structural integrity verification, and powertrain diagnostic output to determine residual service life and pricing. Its commercial purpose centers on transferring depreciated but functional mobility assets to secondary owners at price points below equivalent new vehicles. SUVs and trucks anchor Canadian resale volume due to winter drivetrain preferences and towing utility requirements, while electric fuel type segments are attracting disproportionate buyer attention as charging infrastructure expands. Online platforms are capturing margin pools formerly held by physical dealerships through lower customer acquisition costs and national inventory aggregation.
Health Canada and Transport Canada shape vehicle safety recall enforcement and import eligibility standards that determine which used vehicles legally enter Canadian commerce. Environment and Climate Change Canada regulations on tailpipe emissions influence provincial registration fees and resale desirability of older combustion models. The country's national pharmaceutical regulator has no direct role here, but provincial consumer protection offices enforce disclosure requirements on odometer accuracy and accident history. Stakeholders must monitor how federal zero-emission vehicle mandates cascade into used-car certification criteria and lender collateral valuation methodologies.
Market Dynamics
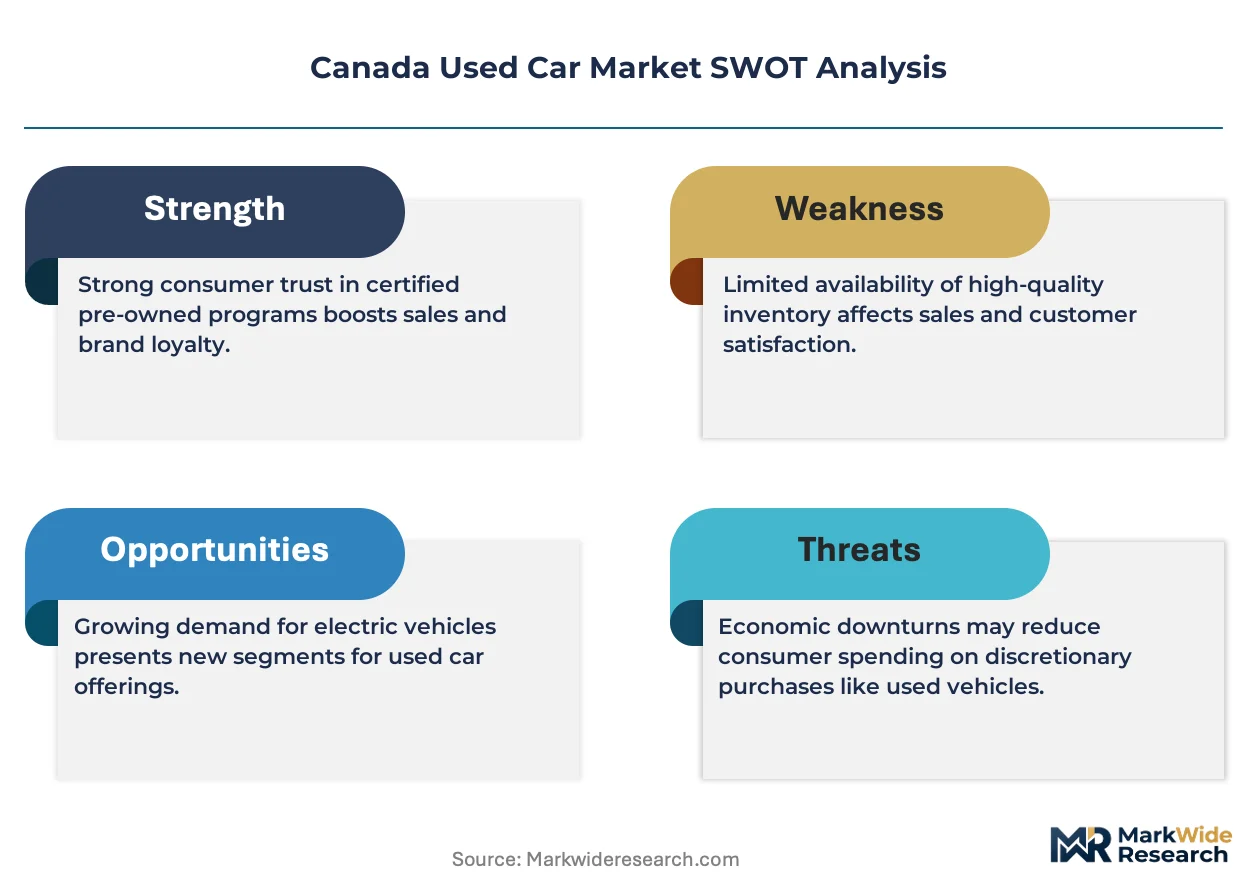
Environment and Climate Change Canada's tightening tailpipe emissions standards are compressing resale values of older combustion vehicles while elevating certified pre-owned hybrid and electric inventory premiums across Canadian dealer networks.
Growth Catalysts
- First-time buyer economics:Affordability thresholds for new vehicles have pushed entry-level consumers toward pre-owned SUVs and trucks in Ontario's Greater Toronto Area, where financing liquidity concentrates.
- Zero-emission vehicle mandates:Federal ZEV targets are accelerating lender collateral revaluation methodologies that favor certified hybrid units with verified battery health diagnostics.
- Gig-economy fleet expansion:Ride-share and delivery drivers in Vancouver and Calgary are absorbing higher-mileage inventory segments that traditional retail buyers bypass.
Market Restraints
- Certified technician scarcity:Ontario and British Columbia face acute shortages of automotive technicians capable of executing hybrid powertrain reconditioning, throttling dealer throughput.
- Import eligibility barriers:Transport Canada's safety recall enforcement blocks cross-border inventory arbitrage from US auction channels, constraining supply elasticity.
- Battery degradation opacity:Residual value uncertainty for used electric vehicles without standardized state-of-health certification depresses lender advance rates.
Strategic Opportunities
- Prairie province penetration:Alberta and Saskatchewan exhibit underdeveloped certified pre-owned infrastructure relative to Ontario, creating whitespace for digital-first platforms with embedded financing.
- Telematics-enabled pricing:Real-time vehicle usage data from connected car platforms allows dynamic residual value indexing that traditional depreciation schedules cannot match.
- Provincial consumer protection alignment:Harmonized disclosure requirements for odometer accuracy and accident history across provincial offices would reduce cross-jurisdictional transaction friction.
Industry Challenges
- Diagnostic equipment capex:Dealer groups must deploy specialized EV battery testing infrastructure without clear recovery timelines on investment.
- Reconditioning workflow integration:Legacy dealer management systems lack API connectivity to third-party vehicle history aggregators, forcing manual data reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Used Car Market |
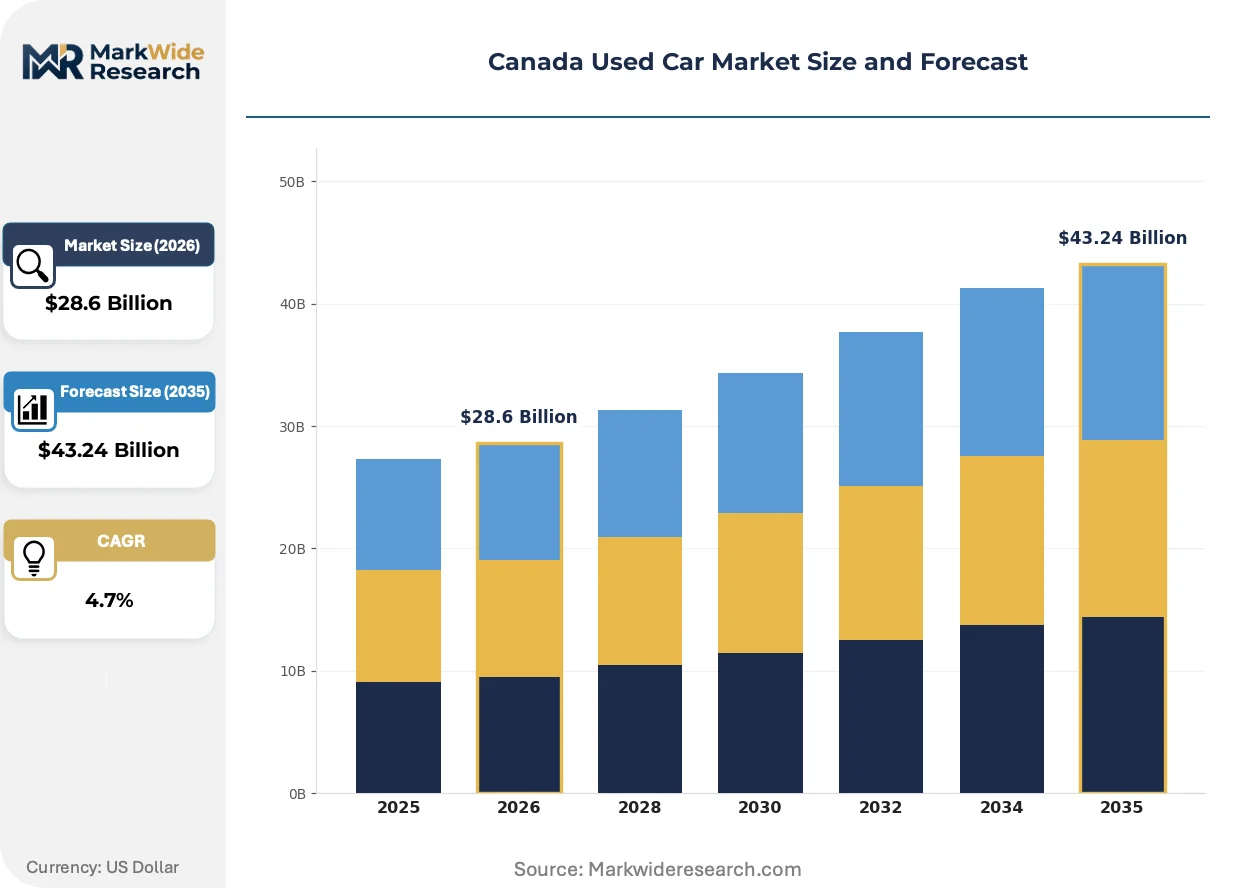
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Truck Fuel Type: Petrol, Diesel, Hybrid, Electric Sale Channel: Dealerships, Private Sale, Auction, Online Platforms Condition: Certified Pre-Owned, Used, As-Is, Salvage |
| Companies Covered | AutoCanada, Kijiji Autos, Canada Drives, HGregoire, Clutch Technologies, CarGurus, TRADER Corporation, Carpages.ca, Dilawri Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Used Car Market Trends and Innovations
Digital financing pre-approval embedded directly into search workflows is collapsing the traditional separation between inventory discovery and credit underwriting in Canadian used vehicle commerce.
Artificial intelligence-powered vehicle condition assessment is supplanting physical auction lane inspections for wholesale acquisition decisions. Major dealer groups in Toronto and Montreal are adopting computer-vision damage detection at scale. This compression of evaluation cycles is enabling same-day inventory turns that previously required 72-hour holding periods.
Environment and Climate Change Canada's phased emissions standards are forcing provincial registration fee structures to penalize older combustion models. British Columbia and Quebec have aligned provincial incentives with federal ZEV mandates. Used electric vehicle inventory in these provinces commands certification premiums that Ontario dealers are now replicating.
Subscription-style vehicle access models are fragmenting traditional ownership patterns among urban millennials. Toronto-based platforms now bundle insurance, maintenance, and swap privileges into monthly payments. This behavioral pivot is most concentrated among gig-economy drivers who prioritize flexibility over equity accumulation.
Canada Used Car Market Segmentation
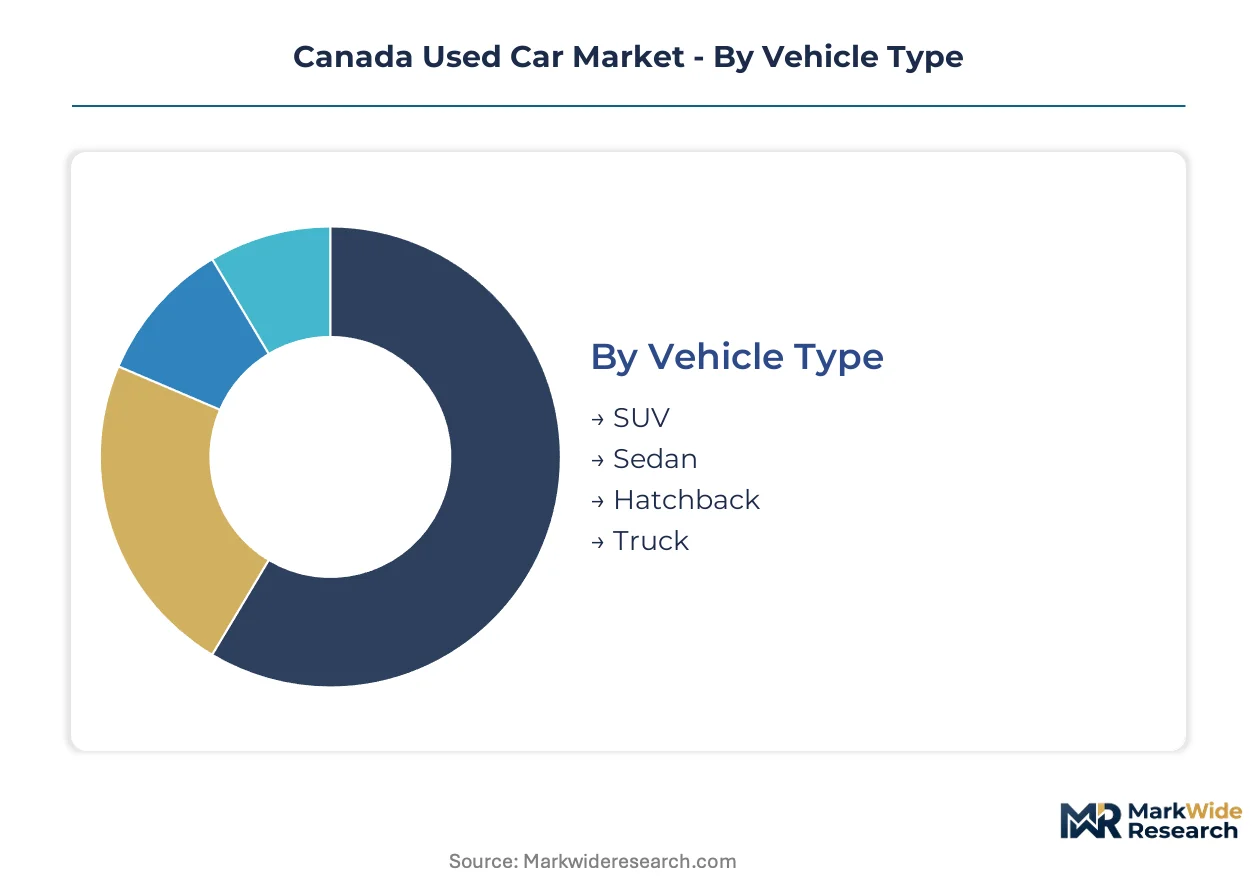
Segmentation in Canada's used car market determines how inventory flows through financing channels, reconditioning networks, and provincial regulatory checkpoints. Each dimension shapes pricing transparency, buyer trust thresholds, and dealer margin structures differently.
Vehicle Type:
Channel-mix patterns show SUVs and trucks commanding higher dealership penetration due to financing complexity, while sedans and hatchbacks concentrate in private sales and auction liquidation.
- SUV:Four-wheel-drive architectures and elevated ground clearance specifications dominate winter drivetrain preferences across Ontario and Alberta. Greater Toronto Area dealerships prioritize SUV inventory for certified pre-owned programs where lender collateral requirements favor utility segments. Quebec's suburban corridors absorb compact SUVs for family mobility.
- Truck:Heavy-duty towing configurations anchor commercial fleet turnover in Alberta's energy corridor and Saskatchewan's agricultural regions. Calgary and Edmonton dealers maintain dedicated truck reconditioning bays to handle payload-rated chassis inspections. Financing pre-approval rates run highest for half-ton pickup segments.
- Sedan:Lower price points concentrate demand among first-time buyers in Vancouver's dense urban core where parking constraints limit vehicle size.
- Hatchback:Compact footprints attract gig-economy delivery drivers in Montreal seeking maneuverability and fuel economy.
Trucks dominate installed base across Prairie provinces. SUVs represent where expansion concentrates in Ontario's certified pre-owned infrastructure.
Fuel Type:
Cost-tier stratification separates premium hybrid inventory with verified battery diagnostics from economy-grade petrol units facing emissions-related registration penalties.
- Petrol:Internal combustion engines without electrification components face compressed resale values under Environment and Climate Change Canada's tightening tailpipe standards. Ontario provincial registration fees now scale with emission intensity, pushing older petrol inventory toward auction channels.
- Hybrid:Dual-powertrain architectures with battery-electric assist command certification premiums in British Columbia and Quebec where provincial incentives align with federal ZEV mandates. Vancouver dealers report fastest inventory velocity for Toyota and Honda hybrid certified pre-owned units.
- Diesel:Compression-ignition engines retain niche demand for long-haul towing in Alberta's commercial segments.
- Electric:Battery-electric platforms suffer residual value uncertainty without standardized state-of-health certification, depressing lender advance rates.
Petrol units dominate transaction volume. Hybrid segments are climbing the fastest as charging infrastructure expands and diagnostic standardization matures.
Sale Channel:
Customer-type differentiation separates institutional fleet buyers at auction from retail consumers requiring financing integration and warranty backing.
- Dealerships:Brick-and-mortar networks with manufacturer affiliations provide certified pre-owned warranties and captive finance arrangements. AutoCanada's coast-to-coast presence anchors this channel with multi-brand inventory aggregation and reconditioning standardization.
- Online Platforms:Digital-native marketplaces collapse search-to-purchase friction through embedded financing pre-approval and national inventory visibility. Canada Drives differentiates here with credit underwriting integrated directly into vehicle discovery workflows.
- Private Sale:Peer-to-peer transactions concentrate in Kijiji Autos traffic with minimal transaction infrastructure and buyer protection gaps.
- Auction:Wholesale liquidation channels handle off-lease fleet returns and dealer trade-ins requiring rapid inventory turns.
Dealerships dominate transaction value capture. Online platforms represent where margin expansion concentrates through lower customer acquisition costs.
Condition:
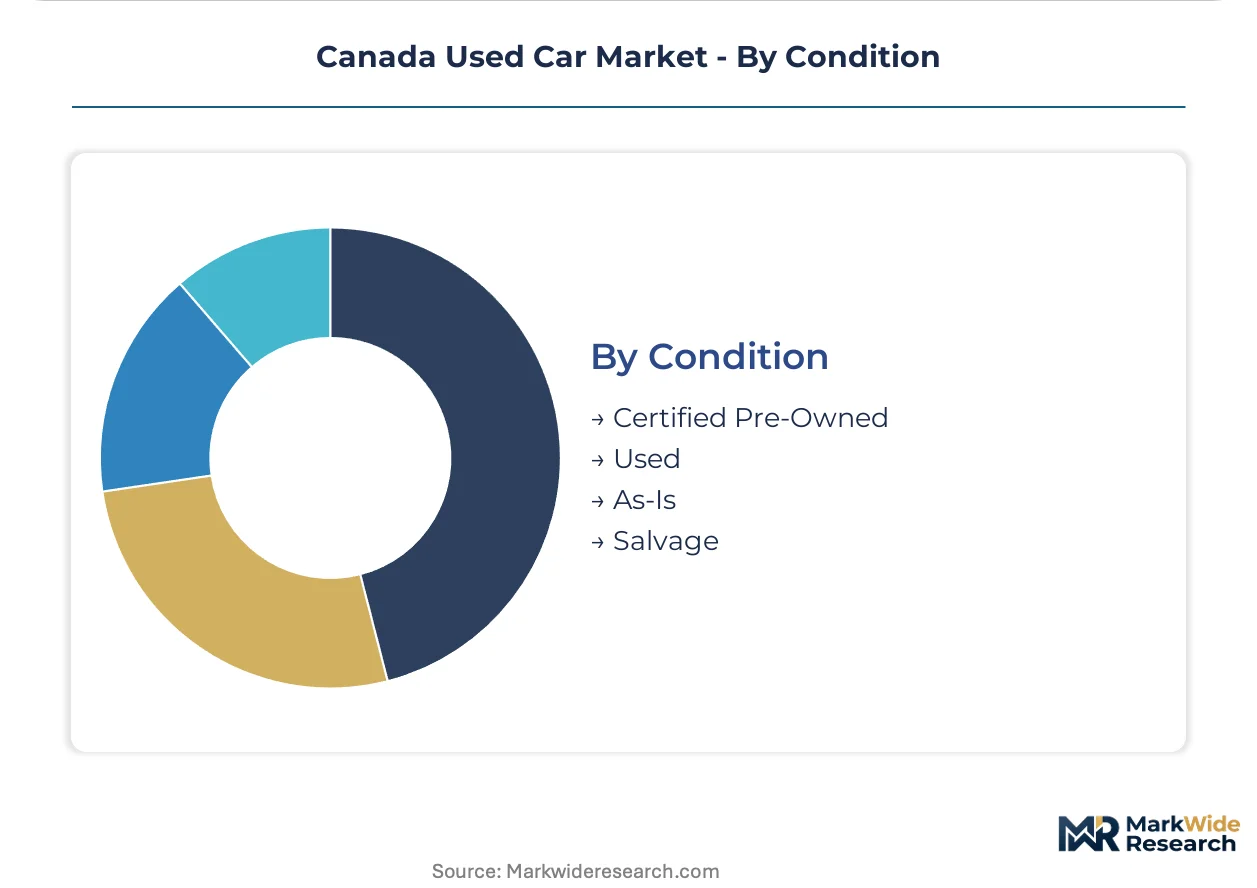
Maturity-stage segmentation separates late-model certified inventory with warranty backing from salvage-grade units requiring rebuild certification.
- Certified Pre-Owned:Manufacturer-backed inspection programs with extended warranties command price premiums of 15-25% above non-certified equivalents. Ontario dealers invest in specialized diagnostic equipment to qualify hybrid and electric units for this designation.
- Used:Standard pre-owned vehicles without manufacturer certification rely on third-party vehicle history disclosure and provincial consumer protection enforcement for transaction trust.
- As-Is:Unwarranted sales carry disclosure requirements under provincial consumer protection offices with limited recourse for undisclosed defects.
- Salvage:Insurance-totaled vehicles requiring structural integrity rebuilding and provincial safety inspections before registration eligibility.
Used units dominate transaction frequency. Certified Pre-Owned segments are gaining share fastest as lender collateral methodologies evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Canadian provinces. Ontario buyers prioritize certified pre-owned SUVs with financing integration, while Prairie provinces absorb higher-mileage trucks for commercial applications. Quebec's regulatory alignment with federal zero-emission mandates accelerates hybrid adoption faster than western markets.
Ontario
Greater Toronto Area dealerships concentrate certified pre-owned infrastructure and captive finance arrangements. Environment and Climate Change Canada's emissions standards compress resale values for older combustion vehicles in provincial urban corridors. Toronto's suburban clusters absorb compact SUVs for family mobility, while downtown cores favor sedans for parking-constrained households.
Quebec
Provincial incentives align with federal ZEV mandates, elevating hybrid inventory premiums above national benchmarks. Transport Canada safety recall enforcement blocks non-compliant US imports at Montreal port facilities. Quebec City dealers replicate British Columbia's certification premiums for battery-electric units with verified diagnostics.
British Columbia
Vancouver's dense urban core concentrates demand for compact hatchbacks among gig-economy delivery drivers. Provincial registration fee structures penalize older combustion models under Environment and Climate Change Canada's phased standards. Lower Mainland dealers report fastest inventory velocity for Toyota and Honda hybrid certified pre-owned segments.
Alberta
Calgary and Edmonton maintain dedicated truck reconditioning bays for payload-rated chassis inspections. Energy corridor commercial fleets drive heavy-duty towing configuration turnover. Prairie province penetration remains underdeveloped for digital-first platforms with embedded financing relative to Ontario benchmarks.
Atlantic Canada
Halifax anchors regional inventory liquidity with limited certified pre-owned infrastructure relative to central Canada. Provincial consumer protection offices enforce disclosure requirements on odometer accuracy with limited cross-jurisdictional harmonization. Maritime buyers rely on private sale channels with minimal transaction infrastructure.
Canada Used Car Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Canada's used car commerce. National dealership networks with manufacturer affiliations control certified pre-owned warranty distribution and captive finance arrangements. Digital-native platforms aggregate inventory visibility without physical reconditioning overhead. Competitive moves concentrate on embedded financing integration and telematics-enabled pricing methodologies.
Within the multi-brand dealership tier, AutoCanada anchors coast-to-coast coverage through standardized reconditioning protocols. Among digital marketplaces, Kijiji Autos occupies a position exemplifying peer-to-peer listing traffic with minimal transaction friction. Canada Drives represents the financing-integrated archetype, embedding credit pre-approval directly into search-to-purchase workflows.
| Leading Market Players |
|---|
| AutoCanada |
| Kijiji Autos |
| Canada Drives |
| HGregoire |
| Clutch Technologies |
| CarGurus |
| TRADER Corporation |
| Carpages.ca |
| Dilawri Group |
| Others |
Pricing and Supply Chain Analysis
Spot-auction liquidity in cross-border wholesale channels locks in inventory access for Ontario dealers while compressing price visibility for Prairie province buyers lacking equivalent auction infrastructure. Long-term floor-plan financing arrangements with captive lenders anchor pricing stability for certified pre-owned inventory, shielding reconditioned units from spot-market volatility that erodes margins on as-is trade-ins.
Pricing Analysis
Long-term floor-plan arrangements dominate dealer acquisition economics, securing inventory access against spot-auction volatility that punishes unfinanced buyers. Price differentiation rests on certification grade—manufacturer-backed CPO units command premiums over third-party inspected inventory—and geographic delivery cost asymmetries between Ontario's liquid GTA corridor and Atlantic Canada's fragmented channels. Pricing pressure intensifies for older petrol-powered SUVs as Environment and Climate Change Canada's phased emissions standards elevate provincial registration penalties. First-time buyers in Vancouver's dense core exhibit highest price sensitivity, while Alberta commercial fleet operators absorb premium truck configurations with limited elasticity.
Supply Chain Analysis
Inventory lead times stretch longest for hybrid-certified units requiring specialized battery diagnostics unavailable at volume in Quebec and Atlantic Canada. Supply concentrates in Ontario's Greater Toronto Area for reconditioned retail-ready inventory, Michigan and Ohio for off-lease fleet returns, and Japan for compact hybrid powertrain components. Raw material dependencies include lithium-ion battery cells, aluminum body panels, and semiconductor-rich infotainment modules. Single-source vulnerability in EV battery testing equipment constrains dealer throughput expansion. Distribution runs through manufacturer-affiliated auction networks for wholesale allocation, with digital platforms capturing last-mile retail margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's used car market sits in early-cycle expansion as federal zero-emission vehicle mandates cascade into lender collateral revaluation methodologies that favor certified hybrid inventory.
For Market Incumbents: Fortify reconditioning throughput by deploying captive EV battery diagnostic infrastructure before technician scarcity hardens in Ontario and British Columbia. Deepen backward integration into wholesale auction access through long-term offtake agreements with US fleet lessors, insulating inventory supply against Transport Canada import eligibility barriers. For New Entrants and Emerging Players: Anchor in Alberta and Saskatchewan's underdeveloped certified pre-owned infrastructure where digital-first platforms with embedded financing face limited incumbent saturation. Target gig-economy fleet operators in Calgary and Edmonton with subscription-style vehicle access bundling insurance and maintenance into monthly payments. For Investors and Strategic Acquirers: Capital is best deployed toward regional dealership groups with established reconditioning bays and captive finance arrangements in Ontario's GTA corridor. The signal to watch is harmonization of provincial consumer protection disclosure requirements, which would reduce cross-jurisdictional transaction friction and accelerate national platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| EV Battery Diagnostic Infrastructure Deployment | Ontario dealers qualifying hybrid units for CPO designation capture lender-preferred collateral pools. |
| Embedded Financing Integration | Canada Drives' credit pre-approval workflow collapses search-to-purchase friction below dealership benchmarks. |
| Prairie Province Digital Platform Expansion | Alberta and Saskatchewan whitespace offers first-mover advantage before incumbent reconditioning networks mature. |
| Telematics-Enabled Dynamic Pricing | Real-time usage data from connected platforms indexes residual value beyond static depreciation schedules. |
| Provincial Consumer Protection Harmonization | Aligned odometer and accident disclosure standards reduce cross-border transaction friction for national aggregators. |
Research Methodology
A spread of perspectives from dealership operations directors, captive finance underwriters, provincial consumer protection officers, and gig-economy fleet managers converged on the working assumptions governing inventory velocity and pricing elasticity. Primary fieldwork combined structured interviews with secondary validation against Transport Canada safety recall databases, Environment and Climate Change Canada emissions filings, and provincial registration fee schedules. Bottom-up vehicle transaction modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include vehicle class, propulsion architecture, sale channel, and provincial regulatory cluster. CAGRs were derived from demand-side adoption curves and supply-side reconditioning capacity constraints. Forecast inputs incorporated federal ZEV mandate penetration trajectories and certified technician pipeline data from Ontario and British Columbia training institutions.
Decision-makers should treat outputs as directional under assumptions of sustained federal emissions standard tightening and stable floor-plan financing availability; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Used Cars Market
Used Vehicles
Italy Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Qatar Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
Europe Used Car Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
Spain Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Used Semi Truck Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Hong Kong Used Car Market