
 Germany Used Car Market | 2026-2036
Germany Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Used Car Market Analysis
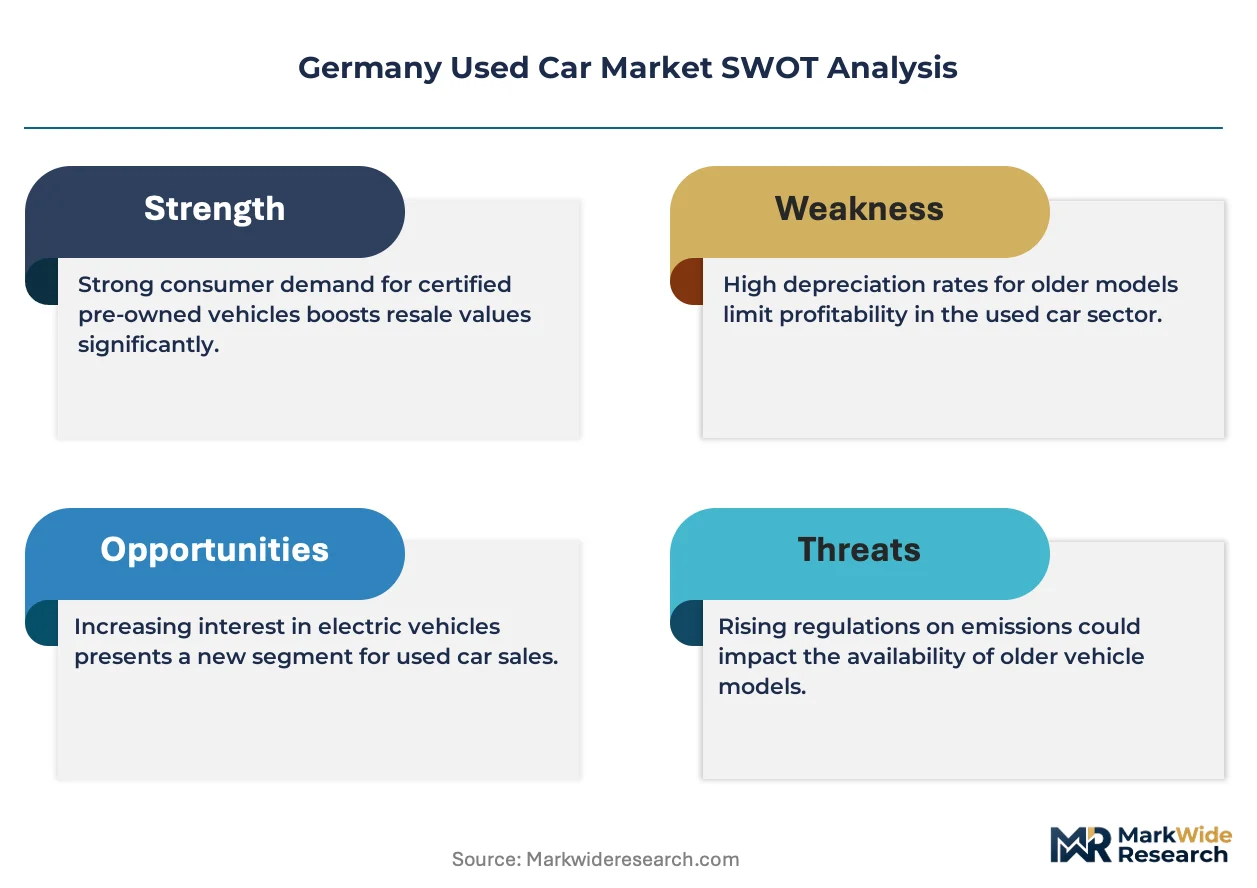
The EU Green Deal is restructuring Germany's used car landscape by accelerating depreciation timelines for diesel inventories and elevating residual values for battery-electric models. AUTO1 Group SE leverages its pan-European wholesale platform to capture cross-border arbitrage on electrified stock. heycar GmbH competes through OEM-certified inventory partnerships that sustain premium pricing power. mobile.de GmbH dominates classified advertising reach, extending its data advantage into automated valuation services.
A used car denotes a previously registered motor vehicle sold through secondary channels, typically assessed via standardized condition grading, odometer verification, and service history documentation to determine residual utility and pricing. Its commercial purpose centers on capital-efficient mobility access for price-sensitive buyers and fleet operators seeking to avoid steep new-vehicle depreciation curves. SUV and hatchback segments lead transaction volumes, with SUVs commanding margin premiums due to sustained family-buyer preference for elevated seating positions and cargo flexibility. Electric and hybrid fuel types represent the fastest-growing pool, though petrol retains absolute volume dominance across rural postcodes where charging infrastructure remains sparse.
KBA enforces mandatory vehicle inspection protocols that filter substandard inventory from circulation, while the F-Gas Regulation shapes air-conditioning system refurbishment costs and compliance burdens for dealers. The EU AI Act introduces emerging transparency requirements for algorithmic pricing tools deployed by digital marketplaces. Stakeholders must monitor how KBA emissions-test tightening and platform liability rules redistribute bargaining power between auction houses, certified dealers, and direct-to-consumer channels.
Market Dynamics
The EU Green Deal's ICE phase-out mandate is compressing diesel residual values while elevating battery-electric premiums, forcing dealers to reprice inventory across powertrain categories simultaneously.
Growth Catalysts
- Fleet electrification mandates:Corporate mobility managers in Bavaria and Baden-Württemberg are redirecting procurement budgets toward certified pre-owned EVs to meet Scope 3 targets without absorbing new-vehicle depreciation.
- KBA inspection protocol tightening:Stricter emissions testing filters substandard diesel stock from circulation, reducing supply-side competition for compliant vehicles and sustaining transaction premiums.
- Charging infrastructure densification:Urban clusters in Munich, Stuttgart, and Frankfurt are eliminating range anxiety barriers that previously suppressed rural EV demand.
Market Restraints
- Battery replacement cost volatility:Lithium carbonate price swings and cell supply bottlenecks create residual value uncertainty for 8-10 year old electric inventory.
- Rural charging deserts:Postcodes in Mecklenburg-Vorpommern and Saxony-Anhalt lack fast-charging density, trapping petrol as the dominant fuel type outside metropolitan corridors.
- F-Gas Regulation compliance burdens:Air-conditioning system refurbishment costs for R134a-to-R1234yf conversions compress dealer margins on older SUV stock.
Strategic Opportunities
- Algorithmic pricing transparency:The EU AI Act creates first-mover advantage for marketplaces deploying explainable valuation models that satisfy emerging audit requirements.
- OEM-certified channel expansion:Direct manufacturer partnerships enable guaranteed battery health warranties that command 12-18% transaction premiums over independent dealer stock.
- Cross-border arbitrage platforms:Pan-European wholesale networks capture price differentials between German EV oversupply and Southern European demand pockets.
Industry Challenges
- Battery health assessment standardization:Absent unified state-of-health testing protocols, dealers face warranty exposure and consumer litigation risk on high-mileage electric inventory.
- Technician electrification training:Independent workshops in Thuringia and Brandenburg lack HV-qualified personnel to service EV powertrains, ceding after-sales revenue to authorized networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Used Car Market |
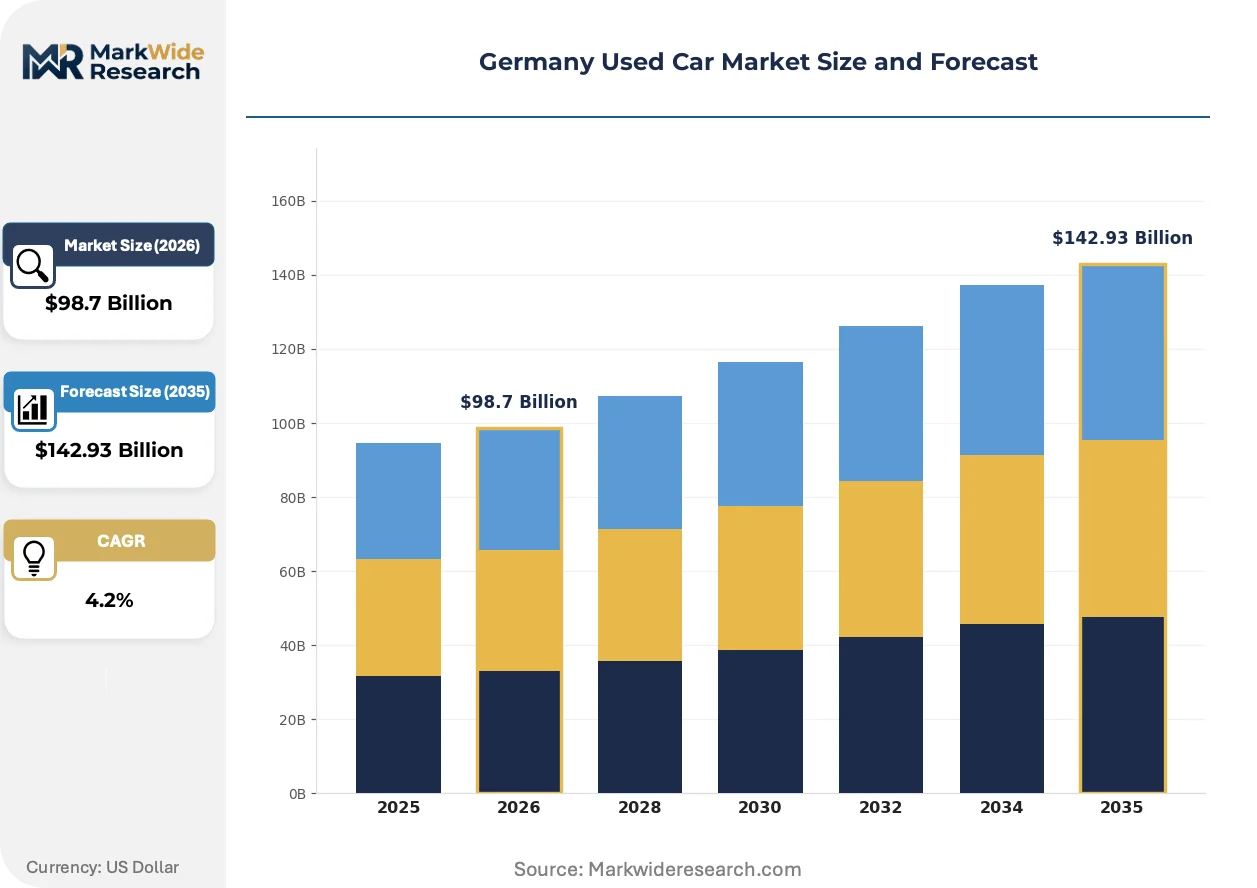
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $142.93 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Condition: Certified Pre-Owned, Non-Certified, Salvage, Used Ownership History: Single Owner, Multiple Owners, Lease Returns, Dealer Trade-ins |
| Companies Covered | CarNext.com, heycar GmbH, AUTO1 Group SE, DAT AUTOHUS, Emil Frey Gruppe, mobile.de GmbH, BCA Autoauktionen GmbH, VGRD GmbH, AutoScout24 GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Used Car Market Emerging Trajectories
Digital marketplaces are weaponizing transaction data to automate pricing and compress search friction, while regulatory pressure on emissions transparency restructures how condition grades are communicated to buyers.
Artificial intelligence-driven valuation engines are absorbing historical transaction feeds, inspection reports, and battery telemetry to generate instant price estimates that previously required manual appraisal. Fleet operators and large dealer groups in Hamburg and Cologne are adopting these tools at accelerating velocity to reduce acquisition cycle times. The compression of pricing information asymmetry is absorbing margin from traditional auction intermediaries and redistributing it toward data-integrated platforms.
The EU AI Act imposes algorithmic transparency requirements on automated pricing systems deployed by classified marketplaces and dealer management software. This regulatory friction forces vendors to document training data provenance and decision logic, increasing compliance overhead but reducing discriminatory pricing exposure. Bavarian dealer groups are responding by consolidating onto certified software stacks that satisfy audit trails ahead of enforcement timelines.
Subscription-based mobility access is fragmenting traditional ownership patterns among urban professionals in Berlin and Munich who prioritize flexibility over asset accumulation. Fleet aggregators and OEM mobility subsidiaries are capturing this demand through monthly EV access contracts that bundle insurance, maintenance, and charging. The shift from discrete transaction to recurring revenue relationships is most visible in metropolitan postcodes where parking scarcity and congestion charges depreciate ownership utility.
Germany Used Car Market Segmentation
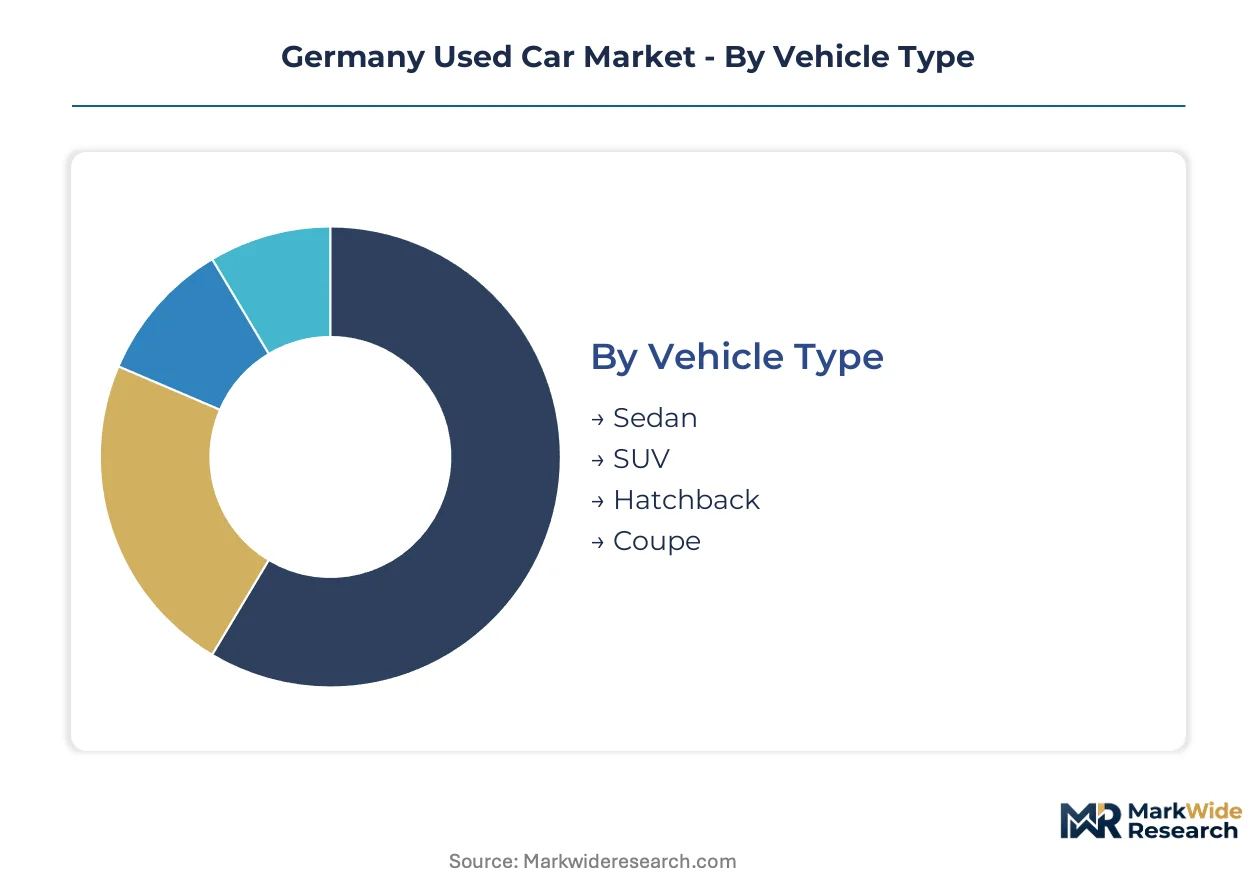
Segmentation in Germany's used car market determines how inventory flows through distinct valuation and distribution channels. Powertrain classification and certification status increasingly dominate pricing algorithms as electrification accelerates and KBA inspection protocols tighten.
Vehicle Type:
Standalone vehicle architectures command premium transaction multiples versus embedded platform derivatives that share underpinnings across segments.
- SUV:Elevated seating positions and cargo flexibility sustain family-buyer preference in Bavaria and Baden-Württemberg manufacturing clusters. Munich and Stuttgart dealer networks capture margin premiums on mid-size SUV stock as corporate fleet managers prioritize image-conscious mobility procurement.
- Hatchback:Compact footprint and parking efficiency dominate urban transaction volumes in Berlin and Hamburg. Young professional demand concentrates on three-door variants where subscription mobility providers absorb depreciation risk through flexible access contracts.
- Sedan:Traditional three-box configuration retains fleet procurement share among executive mobility services in Frankfurt's financial district.
- Coupe:Two-door specialty segment attracts enthusiast collectors in Cologne and Düsseldorf premium dealer networks.
Volume placements concentrate in Hatchback; the faster expansion belongs to SUV.
Fuel Type:
Powertrain segmentation now splits between compliance-driven electrification in metropolitan corridors and infrastructure-constrained combustion persistence in rural postcodes.
- Electric:Battery-electric drivetrains carry residual value premiums as EU Green Deal ICE phase-out deadlines approach. Munich, Stuttgart, and Frankfurt charging densification eliminates range anxiety barriers that previously suppressed secondary-market demand.
- Hybrid:Plug-in and full-hybrid systems bridge infrastructure gaps in transitional regions like Thuringia and Saxony. Corporate mobility managers in Hamburg redirect procurement toward certified pre-owned hybrids to meet interim Scope 3 targets without full electrification commitment.
- Petrol:Internal combustion retains absolute volume dominance across Mecklenburg-Vorpommern and Saxony-Anhalt postcodes where fast-charging networks remain sparse.
- Diesel:Compression-ignition stock faces accelerated depreciation as KBA emissions-test tightening filters non-compliant inventory from circulation.
Petrol maintains the largest transaction base; electric powertrains are gaining share fastest.
Condition:
Certification tier determines warranty backing and financing access, creating pricing stratification that separates institutional from private-sale channels.
- Certified Pre-Owned:OEM-backed inspection protocols and guaranteed battery health warranties command 12-18% transaction premiums over independent dealer stock. Bavarian dealer groups consolidate procurement around manufacturer-certified channels to satisfy audit trails ahead of EU AI Act enforcement timelines.
- Non-Certified:Independent dealer inventory without manufacturer backing competes on price in volume-oriented segments across Berlin and Cologne.
- Used:Standard secondary-market classification encompasses the broad middle tier of transaction flow.
- Salvage:Insurance-totaled vehicles requiring structural or powertrain reconstruction filter through specialized auction channels with restricted title status.
Used vehicles dominate absolute placements; certified pre-owned climbs the fastest.
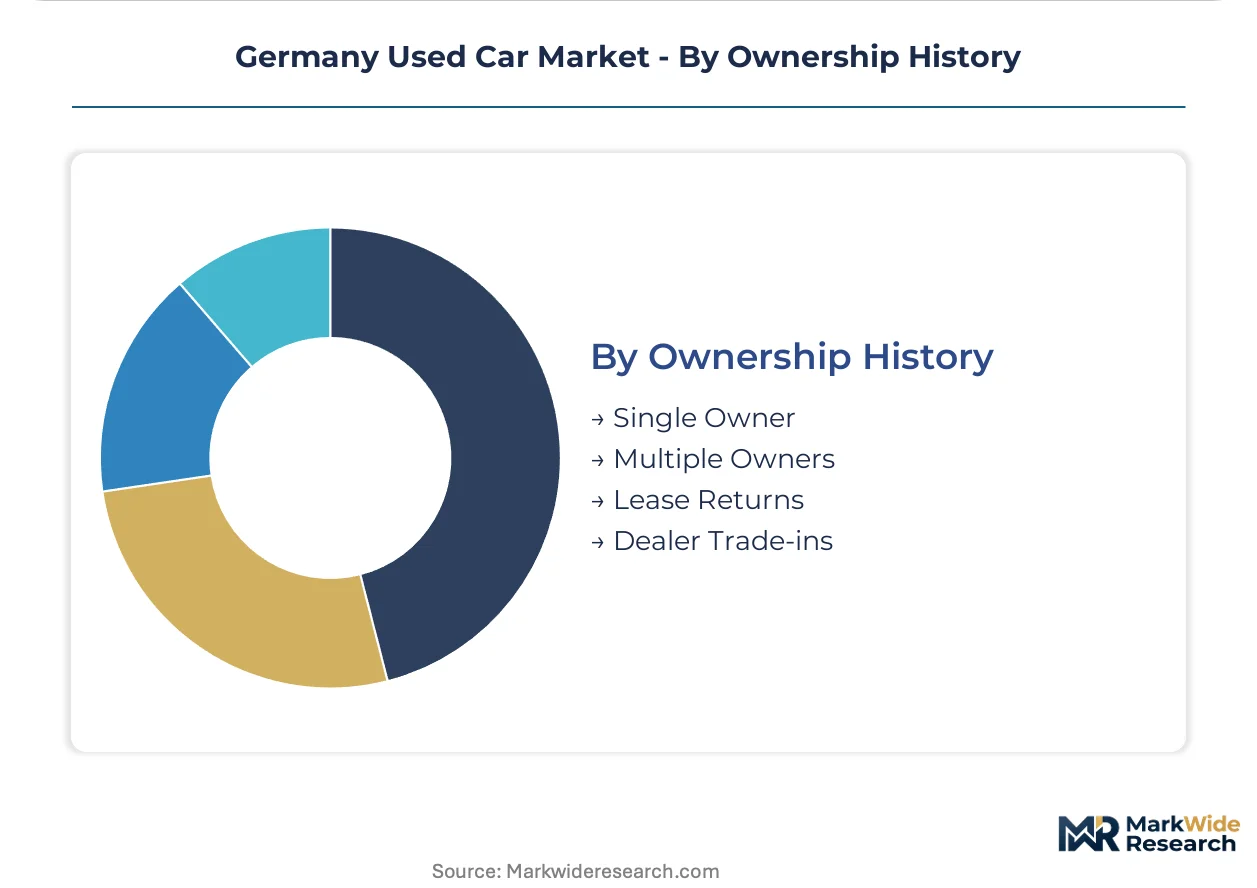
Ownership History:
Provenance documentation shapes residual confidence, with single-source vehicles commanding transparency premiums in algorithmic pricing models.
- Lease Returns:Fleet-maintained vehicles with complete service documentation attract corporate procurement managers in Baden-Württemberg seeking predictable maintenance cost profiles.
- Single Owner:Uninterrupted provenance sustains valuation premiums in Munich and Stuttgart premium segments where buyer risk aversion runs highest.
- Dealer Trade-ins:Immediate resale inventory cycles through auction houses and digital marketplaces with compressed holding periods.
- Multiple Owners:Fragmented history requires enhanced inspection investment, concentrating this stock in value-oriented independent dealer channels.
Dealer trade-ins drive volume velocity; lease returns show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors Germany's used car trade volume, with Bavaria's manufacturing clusters sustaining higher disposable incomes and dealer density than any other state.
Bavaria
Corporate fleet managers in Munich redirect procurement toward certified pre-owned EVs to meet Scope 3 targets without absorbing new-vehicle depreciation. KBA inspection protocol tightening filters substandard diesel stock from circulation, reducing supply-side competition. Stuttgart dealer networks capture margin premiums on mid-size SUV stock as image-conscious mobility procurement accelerates.
Baden-Württemberg
Manufacturing clusters around Stuttgart sustain stronger dealer density and higher transaction premiums than northern states. EU Green Deal ICE phase-out deadlines elevate battery-electric residual values while compressing diesel pricing. Charging infrastructure densification in Stuttgart and Karlsruhe eliminates range anxiety barriers that previously suppressed secondary-market EV demand.
North Rhine-Westphalia
Cologne and Düsseldorf premium dealer networks attract enthusiast collectors seeking two-door specialty segments. F-Gas Regulation compliance burdens compress dealer margins on older SUV stock requiring air-conditioning system refurbishment. Independent workshops in the Ruhr region lack HV-qualified personnel to service EV powertrains, ceding after-sales revenue to authorized networks.
Hesse
Frankfurt's financial district sustains fleet procurement share among executive mobility services favoring traditional three-box sedan configurations. Corporate mobility managers redirect budgets toward certified pre-owned hybrids to meet interim Scope 3 targets without full electrification commitment. Algorithmic pricing tools deployed by digital marketplaces face emerging transparency requirements under the EU AI Act.
Berlin-Brandenburg
Subscription-based mobility access fragments traditional ownership patterns among urban professionals prioritizing flexibility over asset accumulation. Young professional demand concentrates on three-door hatchback variants where subscription mobility providers absorb depreciation risk. Fleet aggregators capture this demand through monthly EV access contracts bundling insurance, maintenance, and charging.
Germany Used Car Market Vendor Landscape
The competitive structure tilts toward digital marketplace platforms with data-integrated valuation capabilities. Auction houses and certified dealer networks occupy secondary positions, with independent operators facing margin compression from algorithmic pricing transparency. Three archetypes dominate: pan-European wholesale platforms, OEM-certified inventory partnerships, and classified advertising reach extenders. Consolidation pressure favors M&A activity among mid-tier dealer groups, while technology licensing agreements proliferate between marketplace operators and battery health assessment providers.
Within the digital marketplace tier, mobile.de GmbH and AutoScout24 GmbH exemplify classified advertising reach extenders that have absorbed historical transaction feeds to automate valuation services. AUTO1 Group SE represents the pan-European wholesale platform archetype, positioned to capture cross-border arbitrage on electrified stock. heycar GmbH occupies the OEM-certified channel position, sustaining premium pricing power through manufacturer-backed inspection protocols and guaranteed battery health warranties that command transaction premiums over independent dealer inventory.
| Leading Market Players |
|---|
| CarNext.com |
| heycar GmbH |
| AUTO1 Group SE |
| DAT AUTOHUS |
| Emil Frey Gruppe |
| mobile.de GmbH |
| BCA Autoauktionen GmbH |
| VGRD GmbH |
| AutoScout24 GmbH |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up dealer groups in Bavaria and Baden-Württemberg concentrate procurement leverage through centralized auction bidding, compressing acquisition costs while sustaining retail pricing power through OEM-certified inventory premiums. This ownership structure feeds directly into supply chain choices, favoring pan-European wholesale platforms over fragmented independent sourcing to defend margin discipline.
Pricing Analysis
Outcome-based pricing anchored to guaranteed battery health warranties commands 12-18% transaction premiums over independent dealer stock. Certification tier and geographic delivery cost differentiate price levels, with Munich and Stuttgart dealer networks capturing premiums on mid-size SUVs. Cost compression in diesel inventory intensifies as KBA emissions-test tightening accelerates depreciation timelines. Fleet operators in Frankfurt's financial district exhibit lowest price sensitivity due to Scope 3 compliance mandates, while rural private buyers in Mecklenburg-Vorpommern remain most price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with battery cell supply concentrated in China, South Korea, and Japan, creating exposure to lithium carbonate price volatility and trade policy friction. Used vehicle sourcing draws from lease returns, corporate fleet rotations, and dealer trade-ins, with inventory quality tethered to KBA inspection protocol compliance. Tariff exposure on replacement battery modules compresses margins on 8-10 year old electric stock. Distribution runs through digital marketplace platforms, auction houses, and OEM-certified dealer networks in descending volume share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliant vehicle scarcity props pricing power as KBA inspection tightening filters substandard diesel stock from circulation faster than certified replacement supply can replenish channels.
For Market Incumbents: Deepen OEM-certified channel partnerships to secure guaranteed battery health warranties that sustain transaction premiums. Add capacity in charging-dense metropolitan corridors to capture fleet electrification procurement. Defend against algorithmic pricing transparency by consolidating onto audit-compliant software stacks ahead of EU AI Act enforcement timelines. For New Entrants and Emerging Players: Launch via subscription-based mobility contracts targeting Berlin and Munich urban professionals prioritizing flexibility over ownership. Target rural postcodes in Saxony-Anhalt where petrol inventory retains demand and competition from electrified platforms remains sparse. Deploy battery health assessment standardization as a differentiation wedge against warranty-exposed independent dealers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier dealer groups in Thuringia and Brandenburg lacking HV-qualified technician capacity, where authorized networks will consolidate after-sales revenue. Five-to-ten year viability hinges on electrification transition execution rather than combustion legacy preservation. Watch battery replacement cost volatility as the inflection signal determining residual value confidence for 8-10 year old electric inventory.| Strategic Initiative | Industry Significance |
|---|---|
| OEM-Certified Channel Expansion | Manufacturer-backed battery warranties command 12-18% pricing premiums over independent stock. |
| Algorithmic Pricing Transparency Investment | EU AI Act compliance creates first-mover advantage for explainable valuation models. |
| Cross-Border Arbitrage Platform Development | Pan-European wholesale networks capture price differentials between German EV oversupply and Southern European demand. |
| Technician Electrification Training Programs | HV-qualified personnel scarcity in Thuringia cedes after-sales revenue to authorized networks. |
| Subscription Mobility Contract Bundling | Monthly EV access contracts absorb depreciation risk for Berlin and Munich urban professionals. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet procurement managers, dealership operations directors, auction house specialists, and KBA compliance officers. KBA vehicle registration databases, EU emissions compliance reports, and platform transaction feeds provided volume and pricing benchmarks. Bottom-up dealer network analysis triangulated against top-down market sizing from automotive trade associations.
Reconciliation of vehicle registration flows, auction transaction volumes, and certified pre-owned certification data shaped the analytical framework across the analysis window. Segmentation dimensions modeled include vehicle architecture, powertrain category, certification tier, ownership history, and regional charging infrastructure density. CAGRs derived from trend extrapolation of electrification penetration rates and diesel depreciation curves, with battery replacement cost volatility and F-Gas Regulation compliance burdens as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization or hydrogen fuel cell penetration would alter the outlook. Forecasts reflect assumptions on KBA inspection protocol enforcement intensity and EU Green Deal ICE phase-out timeline adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Online Car Buying Market
Used Vehicles
North America Used Truck Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
Thailand Used Car Market
Used Vehicles
Vintage Car Market
Used Vehicles
Canada Used Car Market
Used Vehicles
UAE Used Cars Industry Market