
 Finland Used Car Market | 2026-2036
Finland Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Finland Used Car Market Insights
The capability gap between capital-heavy dealership networks and lean digital platforms is reorganizing competitive dynamics in Finland's pre-owned vehicle trade. Kamux Corporation leverages its multi-channel retail footprint to sustain national coverage across urban and semi-urban catchments. J Rinta-Jouppi Oy anchors its position through specialized volume handling in the southern growth corridor. AUTO1.com competes via technology-driven pricing transparency that reduces information asymmetry between buyers and sellers.
Finland used cars encompass previously registered passenger and light commercial vehicles that undergo mandatory periodic technical inspection under Traficom-administered Katsastus protocols measuring brake efficiency, emission compliance, and structural integrity before resale eligibility. These vehicles serve secondary ownership cycles for cost-conscious consumers, fleet operators, and ride-hailing drivers seeking depreciated assets with verified maintenance histories. Hatchback and sedan segments retain liquidity due to lower entry prices, while hybrid powertrains within the fuel type category attract buyers navigating Finland's vehicle taxation structure that favors electrified drivetrains. The certified pre-owned condition tier commands margin premiums through dealer-backed warranty programs and documented service records that reduce buyer risk perception.
Traficom enforces Katsastus inspection intervals and emission thresholds that determine roadworthiness certification and thus tradability of used vehicles. The Finnish Competition and Consumer Authority monitors pricing transparency and contract terms in dealer-to-consumer transactions. Finland's alignment with EU Green Deal mobility targets shapes residual value expectations for internal combustion engine assets. Stakeholders must monitor how battery health verification standards for electric used cars evolve and whether inspection regimes expand to cover battery state-of-health metrics as a tradability precondition.
Market Dynamics
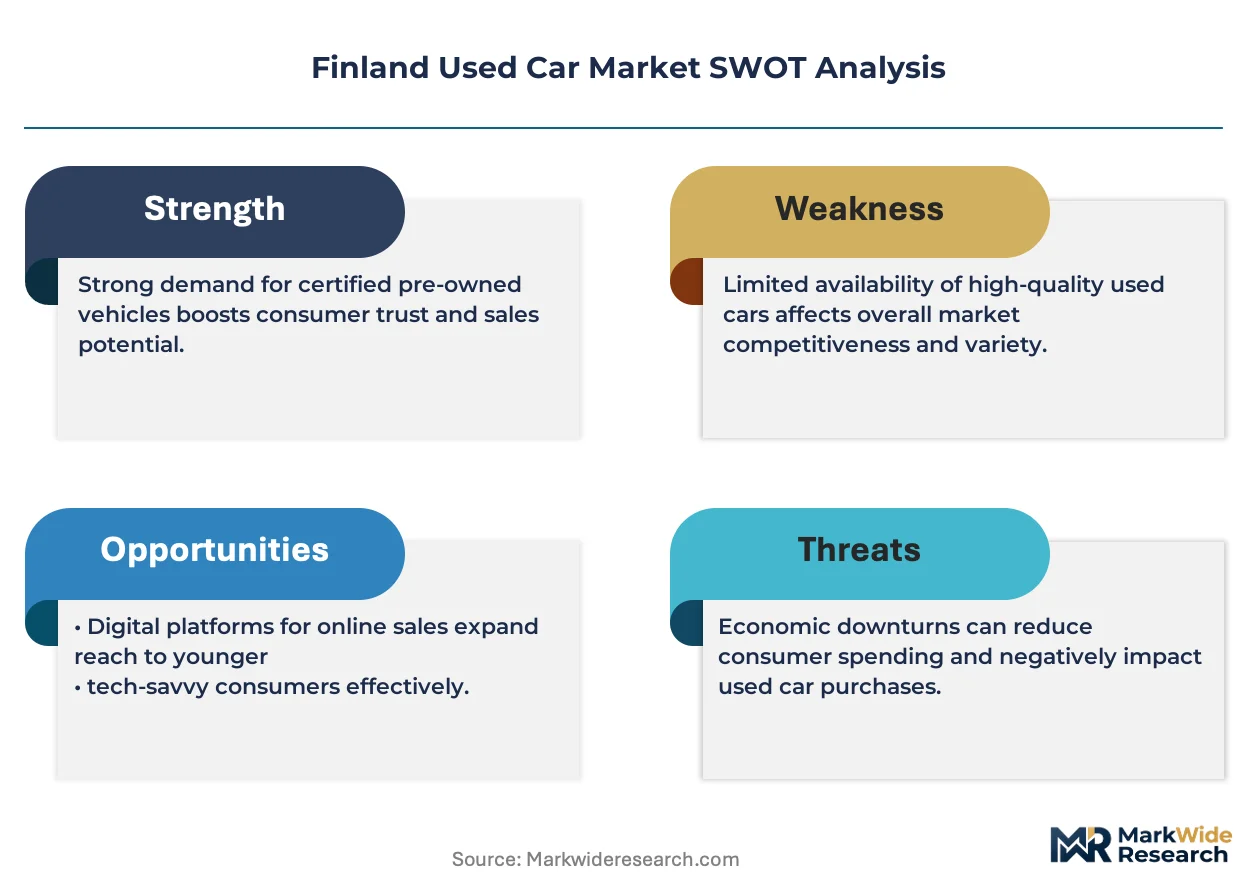
Traficom's Katsastus inspection regime is compressing tradability windows for aging internal combustion vehicles while elevating certified pre-owned electric units into premium pricing tiers. This regulatory pressure is redistributing transaction volumes toward younger vehicle cohorts and digitally intermediated sales channels.
Growth Catalysts
- EU Green Deal alignment:Finland's vehicle taxation structure favors electrified drivetrains, pulling fleet operators toward hybrid and battery-electric used acquisitions.
- Helsinki-Tampere-Turku corridor density:Population concentration in southern Finland sustains higher transaction liquidity and faster inventory turnover.
- First-time buyer demographics:Younger consumers entering ownership cycles prioritize depreciated assets with verified Katsastus histories over new vehicle financing.
Market Restraints
- Battery state-of-health verification gaps:Absence of standardized electric vehicle battery health metrics in Katsastus protocols creates valuation uncertainty for buyers.
- Semi-urban inspection access:Sparse Katsastus station coverage in northern and eastern Finland extends transaction friction for rural sellers.
- Residual value compression:EU-wide emission threshold tightening accelerates depreciation curves for diesel-powered used inventory.
Strategic Opportunities
- Digital auction platforms:Technology-driven pricing transparency reduces information asymmetry between private sellers and institutional buyers.
- Certified pre-owned warranty programs:Dealer-backed service records and extended coverage reduce buyer risk perception and command margin premiums.
- Finnish Competition and Consumer Authority transparency mandates:Regulatory pressure on contract standardization favors scaled operators with compliance infrastructure.
Industry Challenges
- Technician training deficits:Battery-electric vehicle diagnostic and repair capabilities lag behind inventory mix shifts in dealership networks.
- Legacy system integration:Established dealer management software requires reconfiguration to accommodate battery health data feeds and digital marketplace connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland Used Car Market |
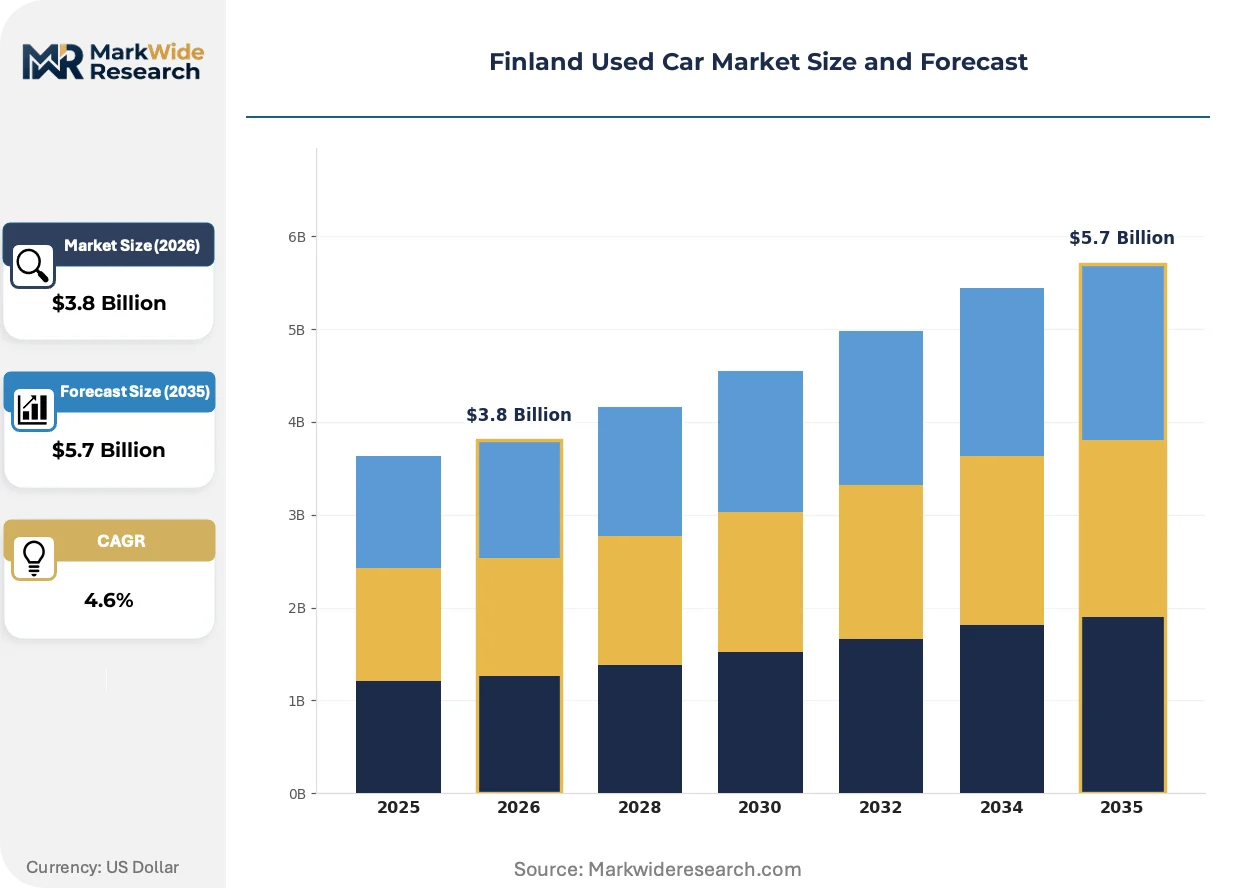
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Hatchback, Sedan, SUV, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Sales Channel: Dealership, Private Seller, Auction, Online Marketplace Condition: Certified Pre-Owned, Non-Certified, Damaged, Maintained |
| Companies Covered | Kamux Corporation, AutoCorner, Hedin Automotive Oy, Alltvex Oy, AUTO1.com, Ayvens Finland, J Rinta-Jouppi Oy, LänsiAuto Oy, VR FleetCare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland Used Car Market Trends and Innovations
Finland's used car market is experiencing channel restructuring as inspection data digitization and electrified inventory reshape how buyers evaluate and acquire pre-owned vehicles. Three converging developments are altering competitive positioning and transaction economics.
Telematics-enabled vehicle history reporting is decomposing traditional information asymmetries between sellers and buyers. Fleet operators and ride-hailing drivers now transmit real-time maintenance and utilization data to valuation platforms. This transparency compression reduces due diligence costs and accelerates price discovery in digital marketplaces.
Traficom's administration of Katsastus protocols is tightening emission compliance thresholds ahead of EU Green Deal mobility targets. The industrial consequence is accelerated obsolescence for older diesel inventory and elevated certification requirements for resale eligibility. Southern Finland dealerships are responding by front-loading hybrid acquisitions and negotiating battery health guarantees with trade-in suppliers.
Subscription and short-term ownership models are fragmenting traditional purchase cycles among urban professionals. Digital-native platforms displace physical lot browsing for Helsinki metropolitan buyers seeking flexible tenure arrangements. This behavioral pivot concentrates transaction volume in technology-mediated channels and compresses dealer hold periods for inventory financing.
Finland Used Car Market Segmentation
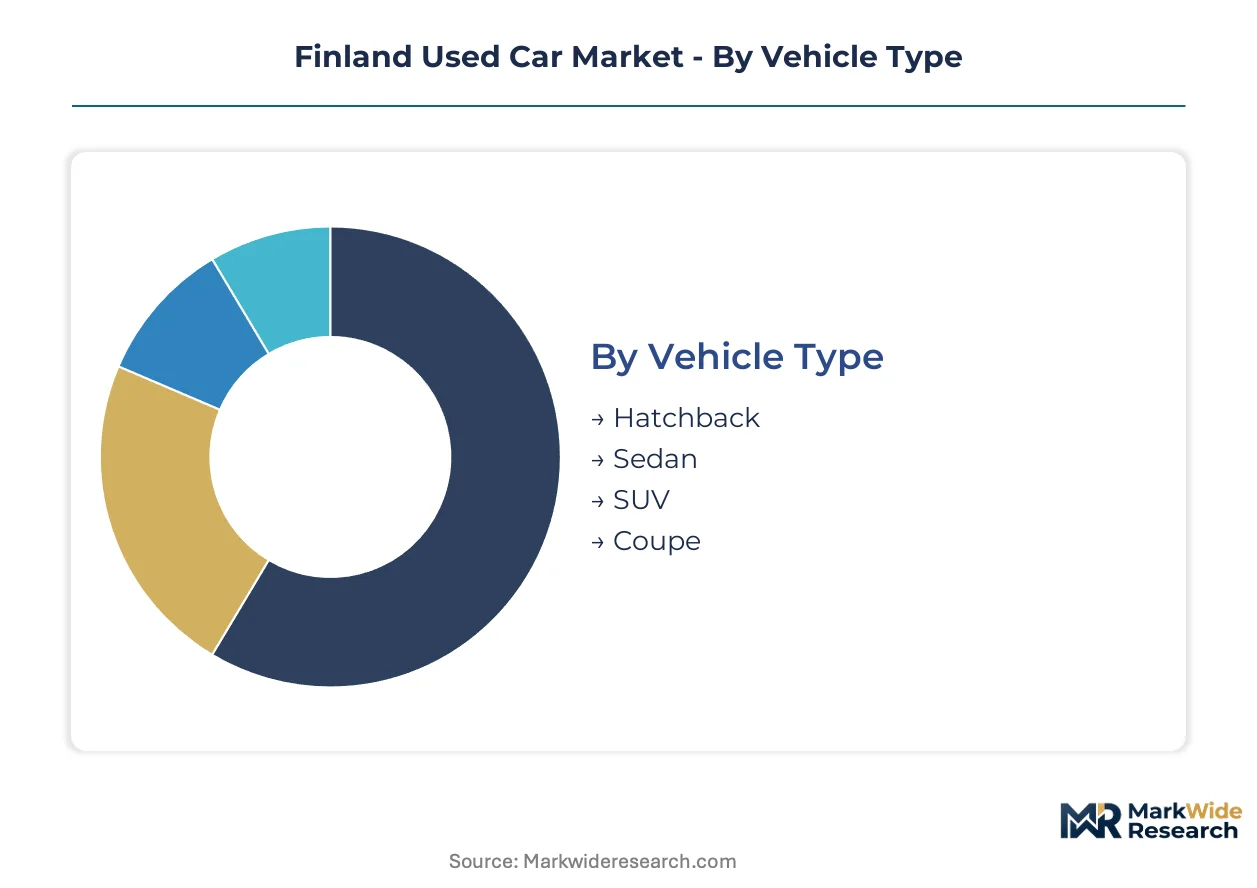
Segmentation in Finland's used car market reveals how Katsastus inspection regimes and electrification policy reshape transaction flows across vehicle categories. Buyers sort inventory by fuel compliance thresholds and digital channel accessibility rather than traditional body-style preferences alone.
Vehicle Type:
Substitution pressure runs strongest through body-style segments as electrification favors platforms with battery packaging efficiency and urban maneuverability.
- Hatchback:Compact dimensions and lower curb weights accommodate smaller battery packs efficiently. Helsinki-Tampere corridor fleet operators favor hatchbacks for ride-hailing deployment where parking scarcity and narrow street grids dominate.
- Sedan:Three-box architecture delivers superior aerodynamic efficiency for highway-biased southern Finland commuting patterns. Corporate fleet renewals concentrate in sedan acquisitions for sales representative mobility.
- SUV:Higher ground clearance and all-wheel-drive configurations attract rural buyers navigating snow-heavy northern Finland road conditions.
- Coupe:Two-door configurations with sport-tuned suspensions retain niche liquidity among enthusiast collectors in Turku metropolitan area.
Hatchback retains volume leadership; SUV holds the steepest expansion curve as electrified platforms gain share.
Fuel Type:
Cost tier stratification separates taxation-advantaged electrified drivetrains from depreciation-burdened combustion alternatives.
- Petrol:Spark-ignition engines dominate sub-100,000 kilometer inventory where Katsastus compliance remains straightforward. First-time buyers in southern Finland urban centers prioritize petrol units for predictable maintenance budgeting.
- Diesel:Compression-ignition powertrains face accelerating residual value compression under EU Green Deal emission threshold tightening. Long-distance commercial operators in the Helsinki-Tampere-Turku corridor still absorb diesel inventory for highway fuel economy.
- Electric:Battery-electric vehicles command premium pricing tiers where Traficom inspection data verifies battery state-of-health metrics.
- Hybrid:Dual-powertrain configurations split demand between mild-hybrid cost efficiency and plug-in hybrid taxation advantages.
Hybrid captures margin leadership; electric climbs the fastest as charging infrastructure density improves.
Sales Channel:
Customer type fragmentation separates institutional volume handlers from peer-to-peer liquidity seekers.
- Dealership:Brick-and-mortar networks with Katsastus certification capabilities anchor certified pre-owned warranty distribution. Kamux Corporation and J Rinta-Jouppi Oy leverage multi-location presence across southern Finland population clusters.
- Private Seller:Direct owner-to-buyer transactions concentrate in semi-urban areas where inspection station proximity reduces transaction friction.
- Auction:Wholesale disposal channels absorb fleet decommission volume from corporate and rental operators.
- Online Marketplace:AUTO1.com and digital-native platforms compress price discovery timelines through algorithmic valuation transparency.
Dealership retains transaction volume leadership; online marketplace gains share fastest among Helsinki metropolitan professionals.
Condition:
Margin concentration stratifies around inspection-verified tiers versus as-is disposal alternatives.
- Certified Pre-Owned:Dealer-backed warranty programs and documented service histories reduce buyer risk perception. Southern Finland premium segments absorb certified inventory at 15-25% price premiums over non-certified equivalents.
- Non-Certified:As-is transactions without warranty coverage concentrate in price-sensitive first-time buyer demographics.
- Damaged:Collision-compromised units flow to repair specialists and parts harvesters where structural integrity failures preclude Katsastus clearance.
- Maintained:Verified service record tiers occupy intermediate pricing between certified and non-certified classifications.
Certified Pre-Owned commands pricing leadership; Maintained expands most quickly as digital service record verification improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finland's used car market operates as a net importer of pre-owned vehicles from neighboring EU member states, with cross-border flows from Germany and Sweden supplementing domestic de-fleet volume. Export activity remains minimal given the country's peripheral geography and stringent Katsastus inspection requirements that limit outbound resale eligibility.
Uusimaa
The Helsinki metropolitan area concentrates transaction liquidity through dense dealership networks and digital platform penetration. Traficom's administration of vehicle registration and inspection protocols anchors regulatory compliance costs in this region. Espoo and Vantaa satellite municipalities absorb fleet decommission volume from corporate operators seeking rapid inventory turnover.
Pirkanmaa
Tampere anchors central Finland's secondary vehicle trade with manufacturing heritage sustaining technician skill pools for complex diagnostics. EU Green Deal alignment pressures local dealers to front-load hybrid acquisitions ahead of emission threshold tightening. The Tampere-Hämeenlinna corridor channels wholesale volume toward Helsinki buyers.
Varsinais-Suomi
Turku's port city status enables direct import channels from Swedish and German wholesale markets. Finnish Competition and Consumer Authority oversight of contract standardization concentrates enforcement activity in this high-transaction region. Salo and Raisio suburban clusters support semi-urban inspection station coverage.
Pohjois-Pohjanmaa
Oulu's technology sector employment base generates distinct demand patterns favoring newer electrified inventory with verified battery health metrics. Sparse Katsastus station density across northern Finland extends transaction friction and elevates digital marketplace reliance. Rural buyers prioritize SUV configurations for snow-heavy road conditions.
Finland Used Car Market Competitive Landscape
Concentration sits with multi-location dealership networks that combine physical inspection capabilities with digital inventory distribution. National coverage requires capital-heavy real estate footprints across southern Finland population clusters, creating barriers for pure-play online entrants. Three archetypes dominate: vertically integrated retail chains, technology-driven pricing platforms, and fleet-focused volume handlers. Competitive moves center on certified pre-owned warranty program expansion and battery health verification service development.
Within the integrated retail tier, Kamux Corporation and J Rinta-Jouppi Oy exemplify multi-channel operators leveraging geographic scale across the Helsinki-Tampere-Turku corridor. AUTO1.com occupies a position representing technology-native platforms that compress price discovery timelines through algorithmic transparency. These three anchors illustrate how capital deployment strategies diverge between physical infrastructure builders and digital marketplace developers.
| Leading Market Players |
|---|
| Kamux Corporation |
| AutoCorner |
| Hedin Automotive Oy |
| Alltvex Oy |
| AUTO1.com |
| Ayvens Finland |
| J Rinta-Jouppi Oy |
| LänsiAuto Oy |
| VR FleetCare |
| Others |
Pricing and Supply Chain Analysis
Traficom-administered Katsastus certification tiers gate both supply qualification and price differentiation simultaneously, compressing margins for non-compliant inventory while elevating certified pre-owned units into premium pricing bands. Dealership networks leverage inspection infrastructure as a barrier to entry that protects pricing power in southern Finland's dense transaction corridors.
Pricing Analysis
Fleet operators and corporate buyers anchor Finland's used car pricing structure around certified pre-owned tiers with verified battery health metrics. Three-tier pricing stratifies across certified premium, maintained standard, and non-certified economy levels, with Katsastus compliance status and documented service histories driving price differentiation. Cost compression in diesel-powered inventory is intensifying because EU Green Deal emission threshold tightening accelerates depreciation curves. First-time buyers in Helsinki metropolitan areas exhibit highest price sensitivity, while corporate fleet procurement demonstrates lowest sensitivity due to taxation-advantaged electrified drivetrain preferences.
Supply Chain Analysis
Inventory turnover cycles in Finland's used car market run shorter in southern population clusters than in northern regions with sparse Katsastus station coverage. Supply concentrates in Germany, Sweden, and domestic Finnish fleet decommission channels, with cross-border wholesale flows from Central Europe feeding Helsinki-Tampere-Turku dealership networks. Battery-electric vehicle diagnostic equipment and certified technician labor represent critical input dependencies. Single-source vulnerability sits with Traficom's centralized inspection protocol administration. Distribution runs through multi-location dealership chains with integrated certification capabilities, supplemented by digital marketplace platforms for peer-to-peer liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finland's used car market presents a defensive-moat story anchored in Traficom's regulatory entrenchment, where Katsastus infrastructure requirements create switching costs that protect incumbent dealership networks from pure-play digital disruption.
For Market Incumbents: Secure battery health verification service capabilities ahead of anticipated Traficom protocol expansion, and consolidate inspection station access in semi-urban northern catchments where sparse coverage extends transaction friction. Vertical integration into telematics-enabled vehicle history reporting counters technology-native platform threats. Certification investment in technician training for electric vehicle diagnostics protects margin position as inventory mix shifts.
For New Entrants and Emerging Players: Battery state-of-health verification gaps in current Katsastus protocols create a service-layer opportunity for specialized diagnostic platforms that reduce buyer valuation uncertainty. Rural and semi-urban northern Finland represents the most penetrable geography where inspection access friction disadvantages incumbent dealership density. A go-to-market angle anchored in mobile inspection unit deployment bypasses fixed infrastructure requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive group captive finance arms seeking to monetize non-core remarketing operations. Long-term viability favors operators with hybrid physical-digital capabilities that balance certification infrastructure with algorithmic pricing transparency. Monitor Traficom regulatory filings for battery health metric inclusion as a signal of certification tier restructuring that would reshape residual value calculations.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Health Verification Service | Specialized diagnostic capabilities capture premium pricing as Traficom protocols evolve. |
| Mobile Inspection Unit Deployment | Semi-urban coverage gaps in northern Finland create first-mover infrastructure advantages. |
| Telematics Data Platform Integration | Real-time maintenance histories reduce information asymmetry in digital marketplaces. |
| Certified Pre-Owned Warranty Expansion | Dealer-backed coverage programs command 15-25% price premiums in southern corridors. |
| Technician Training Academy Development | Electric vehicle diagnostic capabilities lag behind inventory mix shifts in dealership networks. |
Research Methodology
Cross-validation between dealer operations executives and Traficom regulatory filings anchors the qualitative findings in this study. Primary interviews with fleet procurement managers, certified pre-owned program directors, Katsastus station operators, and digital marketplace platform engineers combined with secondary validation from vehicle registration databases, EU emission compliance records, and automotive group financial disclosures. Bottom-up transaction volume modeling and top-down macroeconomic triangulation ensure consistency across estimation approaches.
Sensitivity analysis around battery health verification adoption timelines and EU Green Deal implementation pace shapes the forecast framework. Segmentation dimensions modeled include vehicle class, propulsion architecture, sales channel, and regional inspection infrastructure density across the projection horizon. CAGRs derive from historical transaction velocity patterns adjusted for electrification policy inflection points. Charging infrastructure deployment curves and fleet operator renewal cycles serve as industry-specific forecast inputs.
Material uncertainties — regulatory protocol revisions, battery technology obsolescence curves, and cross-border wholesale flow disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about Katsastus compliance threshold stability and taxation structure continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Qatar Used Car Market
Used Vehicles
Nigeria Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Used Cars Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
Indonesia Used Car Financing Market