
 Poland Used Car Market | 2026-2036
Poland Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Used Car Market Analytics
Market Context
The capability gap between capital-heavy dealership networks and lean digital platforms is rotating competitive dynamics across Poland's used car sector. AAA AUTO leverages its nationwide physical infrastructure and reconditioning centers to sustain margin capture on higher-value inventory. Otomoto competes through proprietary pricing algorithms and digital-first customer acquisition that reduces per-unit overhead. Sobiesław Zasada Automotive anchors its position in premium import segments through specialized sourcing relationships with Western European markets.
Technical Definition and Structural Segments
A used car denotes a previously registered passenger vehicle transferred through secondary sales channels, typically evaluated by mileage accumulation, structural integrity assessments, and powertrain condition against manufacturer specifications. The primary commercial purpose centers on value recovery for original owners while providing affordable mobility access to subsequent buyers below new-vehicle price points. SUV inventory within the vehicle type segment commands disproportionate margin pools as Polish consumers prioritize cabin versatility and residual value retention. Electric and hybrid units under fuel type represent the fastest-appreciating category, though petrol vehicles still dominate transaction volume across all age categories. Online platforms within sales channel are displacing traditional dealership foot traffic, particularly among buyers aged 25-40 seeking transparent pricing and remote financing pre-approval.
Regulatory Framework and Outlook
Poland's Central Vehicle Register (CEP) and the country's national transport inspectorate enforce ownership documentation and roadworthiness certification that filters non-compliant inventory from formal circulation. EU REACH regulations on hazardous substance management and the F-Gas Regulation on air conditioning systems constrain reconditioning practices for older imports. Poland's alignment with EU Green Deal mobility targets is tightening permissible emissions thresholds for vehicles registered in major urban zones. Stakeholders must monitor how Warsaw and Krakow low-emission zone implementations reshape permissible inventory age and engine specifications.
Market Dynamics
EU Green Deal mobility targets and tightening emissions thresholds for Warsaw and Krakow low-emission zones are compressing permissible inventory age and engine specifications across Poland's used car sector.
Growth Catalysts
- First-time buyer expansion:Young Polish consumers entering vehicle ownership prioritize affordable pre-owned units over new-vehicle price points, expanding transaction volume in the 5-10 year age segment.
- Fleet operator rotation:Commercial leasing companies accelerate replacement cycles to maintain EU emissions compliance, feeding quality supply into secondary channels.
- Digital platform penetration:Online marketplaces with transparent pricing algorithms reduce information asymmetry and financing friction for buyers aged 25-40.
Market Restraints
- Import supply concentration:Western European sourcing corridors dominate quality inventory inflow, exposing Polish dealers to euro exchange volatility and cross-border documentation delays.
- REACH reconditioning costs:EU hazardous substance management rules constrain refurbishment practices for older vehicle interiors, elevating per-unit preparation expenses.
- Petrol residual compression:Anticipated diesel and petrol restrictions in urban low-emission zones accelerate depreciation for internal combustion inventory relative to hybrid alternatives.
Strategic Opportunities
- Mazovia province density:Warsaw metropolitan concentration of affluent buyers supports premium SUV and electric vehicle remarketing at above-national margin rates.
- CEP integration services:Central Vehicle Register data layering enables fraud-resistant ownership verification and financing pre-approval products.
- Hybrid technology convergence:Battery-electric drivetrain knowledge transfer from Western European markets positions Polish reconditioners for emerging plug-in inventory categories.
Industry Challenges
- Diagnostic technician scarcity:Advanced powertrain electrification requires skills absent from traditional mechanical training pipelines.
- F-Gas certification timelines:Air conditioning system compliance under EU refrigerant regulations extends vehicle preparation cycles.
- Legacy platform integration:Dealer management system upgrades to accommodate online sales channels strain mid-sized operator capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Used Car Market |
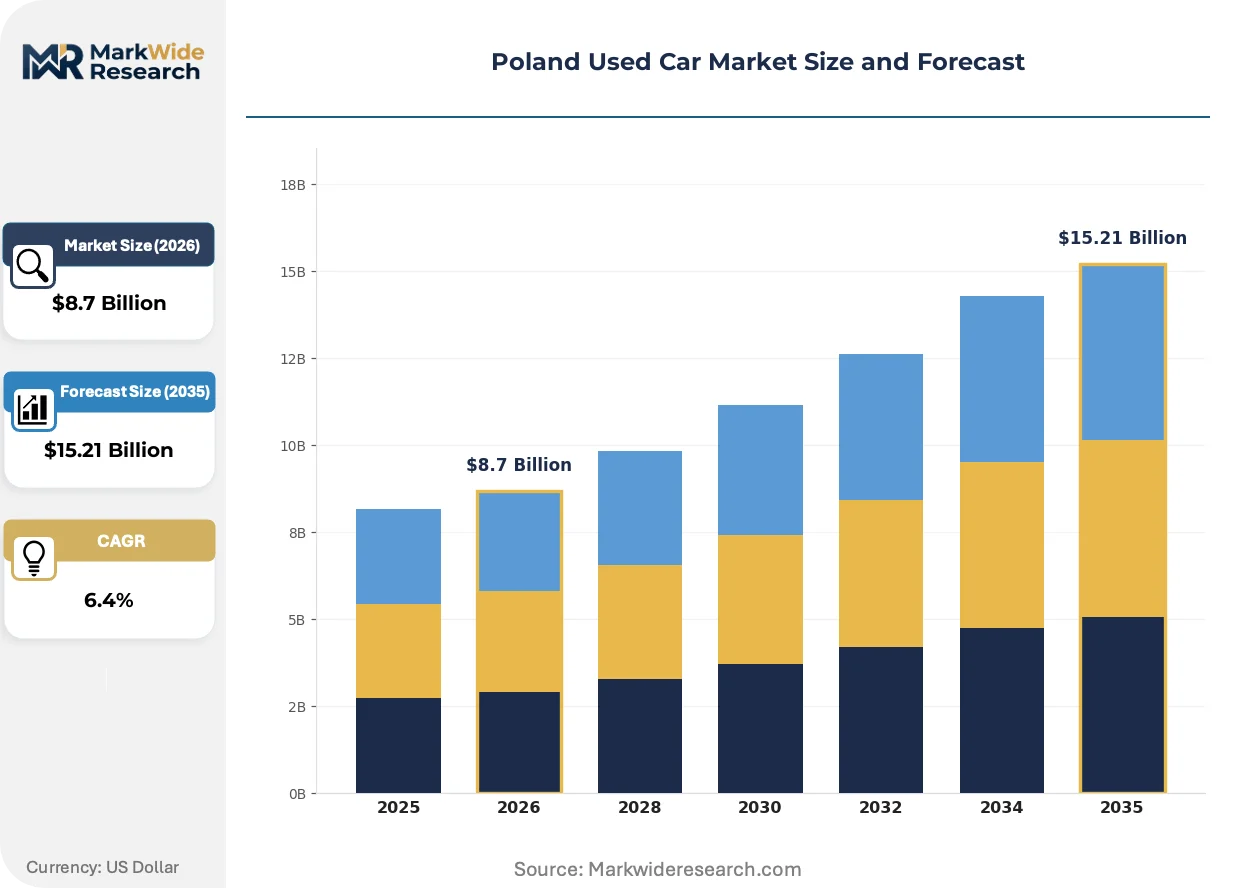
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, Hatchback, SUV, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Age Category: 0-3 Years, 4-6 Years, 7-10 Years, 10+ Years Sales Channel: Dealerships, Private Sellers, Auctions, Online Platforms |
| Companies Covered | AAA AUTO, Emil Frey Polska, ALD Automotive, Otomoto, Plichta Group, Sobiesław Zasada Automotive, Volkswagen Group Polska, Oruga Group, CDG Poland, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Used Car Market Evolving Landscape
Digital infrastructure, emissions compliance architecture, and buyer behavior patterns are converging to reshape inventory flow and margin capture across Poland's secondary vehicle market.
Blockchain-enabled provenance verification is fragmenting trust mechanisms in high-value transactions. Premium segment buyers now demand immutable service history records. This technology is fragmenting traditional dealership reliance on physical documentation and verbal warranty claims.
EU F-Gas Regulation enforcement is tightening refrigerant handling requirements across vehicle reconditioning operations. Workshop operators must retrofit recovery equipment and certify technicians. SUV and luxury segments face extended preparation timelines as climate system compliance becomes mandatory pre-sale.
Remote financing pre-approval is displacing in-person credit negotiations at traditional dealership locations. Digital-native buyers complete loan arrangements through platform-integrated banking APIs before physical inspection. This shift concentrates transaction velocity in Warsaw and Krakow where fintech penetration exceeds national averages.
Poland Used Car Market Segmentation
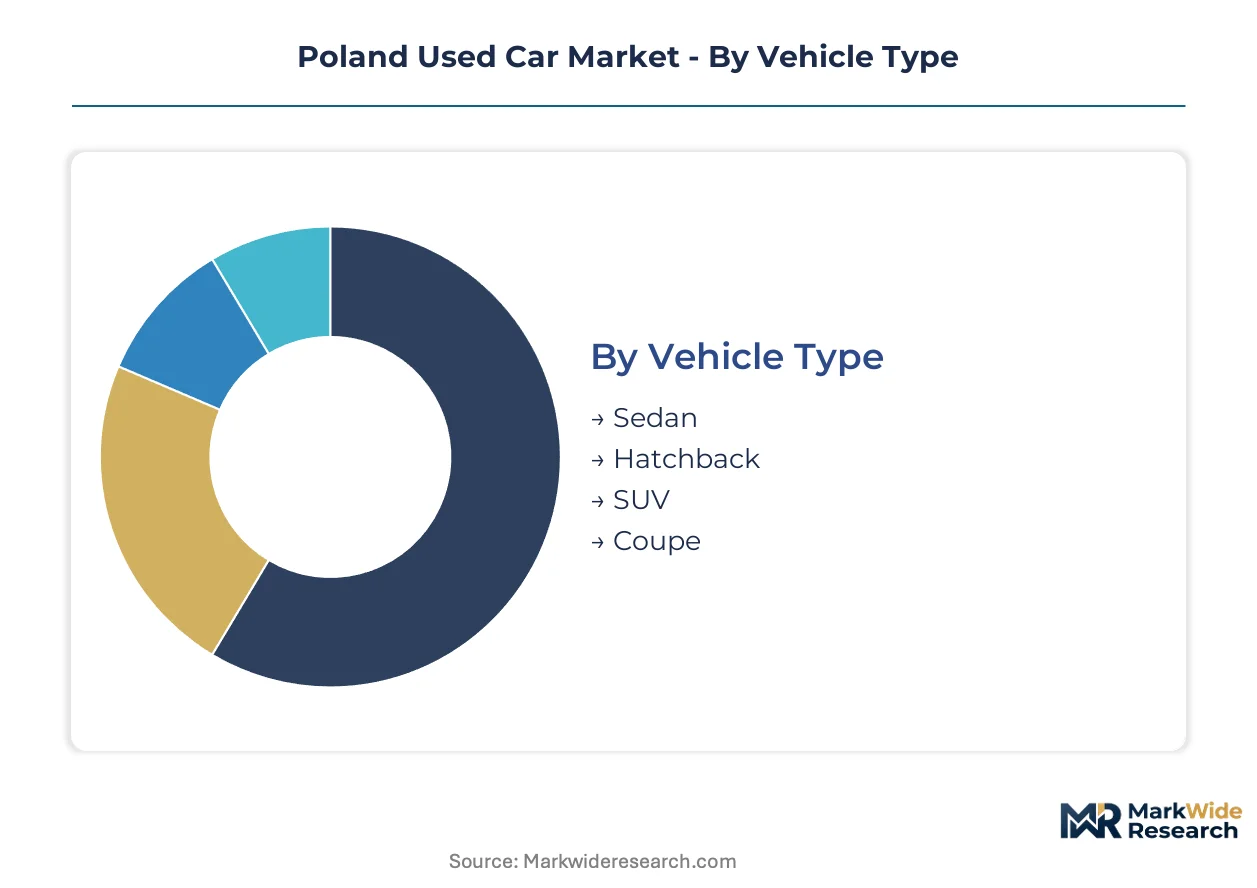
Poland's used car market fragments across four structural dimensions that determine inventory sourcing, reconditioning investment, and channel strategy. Each segmentation layer reveals distinct margin profiles and buyer concentration patterns that shape competitive positioning.
Vehicle Type:
SUV inventory commands premium pricing through Warsaw metropolitan dealerships while hatchbacks dominate volume flows through digital auction channels.
- SUV:Higher ground clearance and cabin versatility attract Polish families navigating deteriorating rural road infrastructure. Demand concentrates in Mazovia province where affluent buyers prioritize residual value retention over acquisition cost.
- Hatchback:Compact dimensions suit urban parking constraints in Krakow and Wroclaw city centers. First-time buyers aged 25-35 favor this segment through Otomoto's algorithmic pricing platform.
- Sedan:Traditional three-box configuration retains corporate fleet demand for executive transport.
- Coupe:Two-door specialty units circulate through premium import channels from German sourcing corridors.
By volume, Hatchback leads. By growth pace, SUV is ahead.
Fuel Type:
Powertrain segmentation determines regulatory compliance timelines and urban access permissions across Poland's tightening emissions architecture.
- Petrol:Dominates transaction frequency across all age categories due to lower maintenance complexity and widespread service infrastructure. Warsaw low-emission zone exemptions for newer petrol units sustain demand concentration.
- Hybrid:Battery-electric assistance reduces urban emissions exposure while avoiding range anxiety. Fleet operators rotating toward EU Green Deal compliance feed quality supply into secondary channels.
- Diesel:Compression-ignition engines face accelerating depreciation as Krakow implements nitrogen oxide thresholds.
- Electric:Full battery platforms require specialized diagnostic capabilities absent from traditional Polish mechanical training pipelines.
By transaction frequency, Petrol dominates. By appreciation trajectory, Hybrid is expanding most quickly.
Age Category:
Vehicle age stratifies preparation costs, financing availability, and warranty positioning across Poland's inspection-regulated secondary market.
- 4-6 Years:Balance of depreciation capture and remaining manufacturer warranty coverage attracts value-conscious buyers. AAA AUTO's reconditioning centers specialize in this segment's cosmetic refurbishment and powertrain verification.
- 7-10 Years:Price accessibility aligns with first-time buyer budgets while CEP registration history enables fraud-resistant ownership verification.
- 0-3 Years:Near-new inventory originates primarily from accelerated fleet rotation cycles.
- 10+ Years:Older units face REACH reconditioning cost elevation and restricted urban zone access.
By financing penetration, 4-6 Years leads. By buyer entry volume, 7-10 Years is climbing the fastest.
Sales Channel:
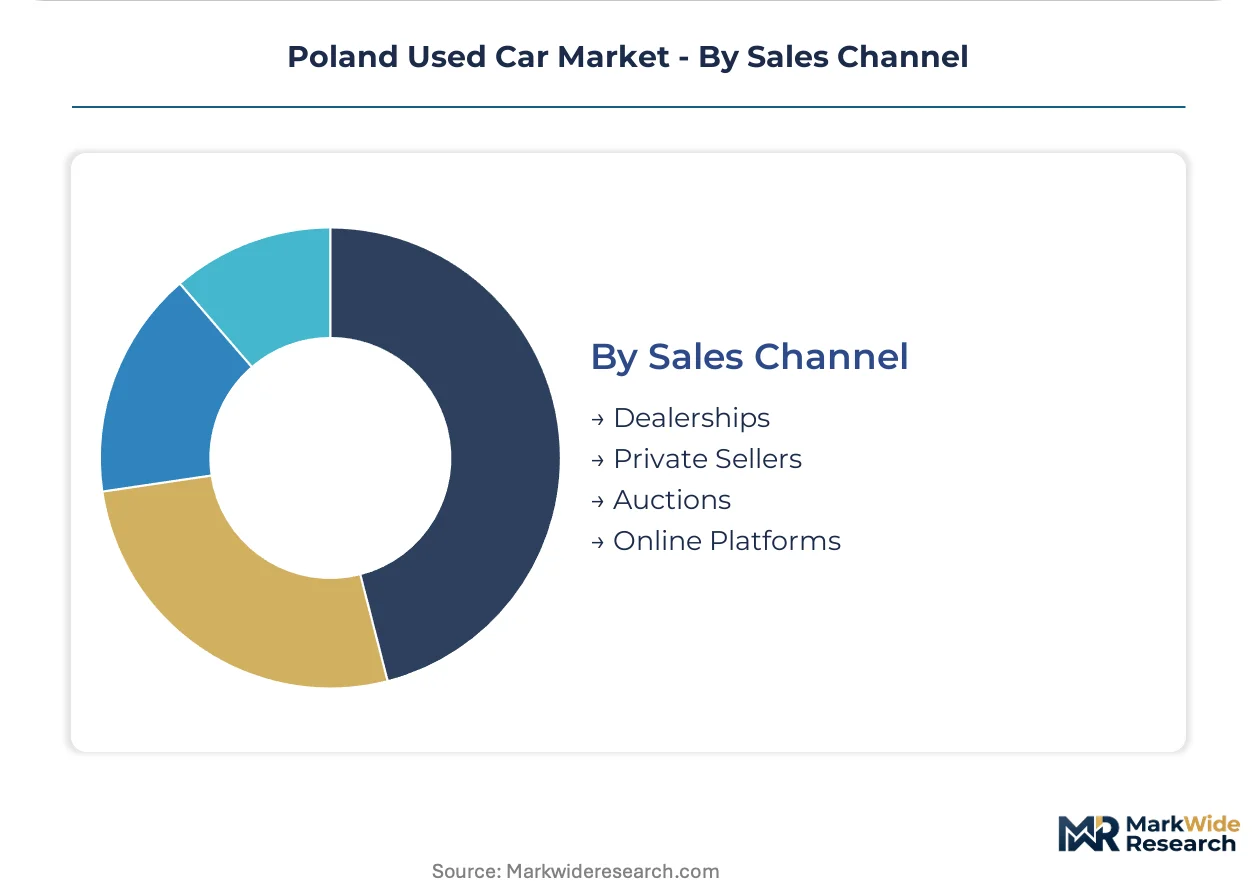
Channel selection determines buyer demographics, pricing transparency, and transaction velocity across Poland's hybrid physical-digital marketplace.
- Online Platforms:Proprietary algorithms reduce information asymmetry while integrated banking APIs enable remote financing pre-approval. Buyers aged 25-40 in Warsaw and Krakow concentrate here.
- Dealerships:Physical infrastructure supports inspection, test drive, and immediate delivery for risk-averse purchasers. Nationwide networks capture margin on higher-value inventory through reconditioning value-add.
- Private Sellers:Direct transactions bypass intermediary fees but expose buyers to documentation verification burdens.
- Auctions:Wholesale volumes feed dealer inventory acquisition with limited retail buyer participation.
By transaction velocity, Online Platforms lead. By margin capture, Dealerships sustain the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw commands pricing premiums that outpace Krakow and Wroclaw by substantial margins, reflecting Mazovia province's concentration of affluent buyers and fleet operator headquarters. This metropolitan pricing-power asymmetry shapes inventory flow patterns across Poland's secondary vehicle market.
Mazovia Province
Warsaw metropolitan demand concentrates premium SUV and electric vehicle remarketing at above-national margin rates. EU Green Deal alignment through Poland's national transport inspectorate tightens permissible emissions thresholds for vehicles registered in the capital's emerging low-emission zone. AAA AUTO leverages its nationwide physical infrastructure and reconditioning centers to sustain margin capture on higher-value inventory circulating through this corridor.
Lesser Poland Province
Krakow's nitrogen oxide thresholds accelerate diesel depreciation while elevating hybrid transaction premiums among university-educated professionals. REACH regulations on hazardous substance management constrain reconditioning practices for older imports entering through southern cross-border corridors. Sobiesław Zasada Automotive anchors its position in premium import segments through specialized sourcing relationships with Western European markets feeding this sub-region.
Lower Silesia Province
Wroclaw's technology sector expansion generates first-time buyer expansion among young professionals aged 25-35 prioritizing affordable pre-owned units. Poland's Central Vehicle Register enforces ownership documentation and roadworthiness certification that filters non-compliant inventory from formal circulation. Otomoto competes through proprietary pricing algorithms and digital-first customer acquisition that reduces per-unit overhead in this price-sensitive market.
Greater Poland Province
Poznan's manufacturing base sustains corporate fleet operator rotation cycles feeding quality supply into secondary channels. F-Gas Regulation on air conditioning systems constrains reconditioning practices for older imports, extending vehicle preparation timelines. Digital platform penetration concentrates transaction velocity among buyers seeking transparent pricing and remote financing pre-approval.
Pomerania Province
Gdansk port infrastructure facilitates Western European sourcing corridors dominating quality inventory inflow, exposing dealers to euro exchange volatility. Poland's vehicle inspection system tightens compliance requirements for older vehicles entering through northern maritime routes. Fleet operator rotation accelerates replacement cycles to maintain EU emissions compliance, feeding near-new inventory into this sub-regional market.
Poland Used Car Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Poland's used car sector. Capital-heavy dealership networks with reconditioning infrastructure compete against lean digital platforms with algorithmic pricing engines. Three archetypes dominate: nationwide physical networks, digital-first marketplaces, and specialized premium importers. Competitive moves concentrate on geographic densification in Mazovia province and CEP data integration for financing pre-approval products.
Within the physical network tier, AAA AUTO exemplifies the nationwide infrastructure archetype through its reconditioning center footprint. Otomoto occupies the digital-native position, leveraging platform-integrated banking APIs to concentrate buyers aged 25-40. Sobiesław Zasada Automotive represents the specialized import segment, anchoring premium Western European sourcing relationships.
| Leading Market Players |
|---|
| AAA AUTO |
| Emil Frey Polska |
| ALD Automotive |
| Otomoto |
| Plichta Group |
| Sobiesław Zasada Automotive |
| Volkswagen Group Polska |
| Oruga Group |
| CDG Poland |
| Others |
Value Network & Pricing Analysis
Hybrid powertrain substitution for diesel inventory simultaneously reshapes supply geography toward Western European sourcing corridors and compresses pricing economics for internal combustion units facing Krakow and Warsaw low-emission zone restrictions. This displacement dynamic concentrates margin capture in reconditioning centers capable of battery-electric verification while elevating per-unit preparation costs for legacy powertrain inventory.
Pricing Analysis
The customization-premium spread between configured-to-order imports and standard domestic inventory defines margin architecture across Poland's secondary vehicle market. Three-tier pricing structure across premium, standard, and economy levels stratifies by reconditioning depth and CEP documentation completeness. Price differentiation hinges on certification grade against EU emissions thresholds and after-sales warranty bundling. Cost compression in petrol-dominated inventory is intensifying because anticipated urban access restrictions accelerate depreciation curves. First-time buyers aged 25-35 exhibit highest price sensitivity through Otomoto's algorithmic platform, while fleet operators demonstrate lowest sensitivity due to replacement cycle mandates.
Supply Chain Analysis
Inbound logistics costs through Gdansk port infrastructure and Rhine-Ruhr corridor road networks expose Polish dealers to euro exchange volatility and cross-border documentation delays. Geographic supply concentration centers on Germany, France, and Belgium as primary sourcing markets for quality pre-owned inventory. Raw material dependencies include lithium-ion battery components, catalytic converter precious metals, and semiconductor-based diagnostic systems. Single-source vulnerability permeates Western European auction channels feeding Mazovia province demand. Distribution runs through AAA AUTO's nationwide reconditioning network and Otomoto's platform-integrated logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among digital-native consumers aged 25-40, fragmenting traditional dealership negotiation leverage and forcing margin compression across physical network operators.
For Market Incumbents: Fortify reconditioning center capabilities in hybrid and electric powertrain diagnostics to counter technician scarcity threatening preparation cycle timelines. Deepen backward integration into CEP data services for fraud-resistant ownership verification products. Prioritize certification investment against EU F-Gas Regulation compliance to extend margin capture on SUV and luxury climate system refurbishment. For New Entrants and Emerging Players: Differentiate on blockchain-enabled provenance verification for premium segment transactions demanding immutable service history records. Target Mazovia province's affluent buyer concentration with specialized electric vehicle remarketing. Pursue white-space in 7-10 year age category financing pre-approval through platform-integrated banking API partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward digital-first marketplace archetypes with algorithmic pricing engines and established fintech integrations. Long-term viability favors operators capturing Warsaw-Krakow transaction velocity through remote financing infrastructure. Monitor EU Green Deal implementation timelines as inflection indicator for hybrid inventory appreciation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| CEP Data Integration Partnership | Enables fraud-resistant ownership verification and financing pre-approval products for digital-native buyers. |
| Hybrid Powertrain Reconditioning Scale-Up | Positions operators for EU Green Deal compliance and Warsaw low-emission zone inventory demand. |
| Blockchain Provenance Platform Launch | Captures premium segment buyers demanding immutable service history records for high-value transactions. |
| F-Gas Certification Program Expansion | Extends preparation capabilities for SUV and luxury climate system compliance under EU refrigerant regulations. |
| Mazovia Province Geographic Densification | Concentrates margin capture on above-national pricing for premium SUV and electric vehicle remarketing. |
Research Methodology
Desk research of vehicle registration databases, EU regulatory filings, and automotive trade publications preceded structured interviews with dealership operations directors, reconditioning center managers, digital platform product leads, and fleet procurement officers. Primary fieldwork combined with secondary validation against Central Vehicle Register transaction records and national transport inspectorate compliance data. Bottom-up unit economics triangulated against top-down market sizing from production and import flow analysis.
Variance decomposition across vehicle type, fuel architecture, age category, and sales channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling incorporating fleet rotation cycle acceleration, digital platform penetration curves, and emissions regulation implementation phasing. Industry-specific forecast inputs included EU Green Deal mobility target alignment and low-emission zone rollout schedules for Warsaw and Krakow.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory tightening or accelerated electrification adoption would require recalibration. Forecasts reflect documented assumptions regarding exchange rate stability in Western European sourcing corridors and technician training pipeline development. Specific risk factors encompass REACH reconditioning cost escalation and diagnostic capability gaps for battery-electric powertrains. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
Used Cars Market
Used Vehicles
France Used Car Market
Used Vehicles
Vintage Car Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
India Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
China Used Car Market