
 Bangladesh Used Car Market | 2026-2036
Bangladesh Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Used Car Market Insights
Multi-source vehicle procurement from auction houses, individual sellers, and import channels is recalibrating inventory strategies across Dhaka-based dealerships. Bhalogari.com leverages its digital-first platform to aggregate scattered supply from individual owners, reducing information asymmetry in price discovery. Executive Motors Limited sustains its position through certified pre-owned programs backed by in-house service infrastructure. Carbarn Bangladesh specializes in Japanese import sourcing, dominating the grey-market pipeline through Chattogram port relationships.
A used car constitutes a previously registered motor vehicle offered for resale through dealer networks, peer-to-peer platforms, or import channels, typically evaluated by odometer reading, chassis integrity, and engine diagnostic performance as core quality parameters. Sedan and hatchback categories anchor transaction volumes in Bangladesh, reflecting narrow urban road widths and fuel-cost sensitivity among owner-operators. CNG conversions represent a distinct value-add segment, with retrofit demand surging as factory-CNG vehicles command premium pricing in the secondary market. The 2016-2020 model-year bracket captures the fastest inventory turnover, balancing modern safety features against depreciation curves that preserve affordability for first-time buyers.
The Bangladesh Road Transport Authority enforces biennial fitness certifications that disqualify vehicles exceeding emission thresholds, directly constraining eligible supply and elevating prices for compliant inventory. BIS standards for brake systems and headlamp specifications further filter import eligibility, particularly for Japanese auction-sourced units. The National Board of Revenue's tariff structure on reconditioned imports shapes the cost economics that dealers and end-users must navigate. Stakeholders should monitor fitness-certification backlogs and potential digitization of ownership-transfer processes as structural variables that will determine margin capture and inventory velocity.
Market Dynamics
The Bangladesh Road Transport Authority's biennial fitness certification regime is compressing eligible vehicle supply and elevating pricing power for compliant inventory holders across Dhaka-based dealer networks.
Growth Catalysts
- Ride-hailing fleet conversion:Fleet operators in Dhaka and Chattogram are accelerating pre-owned acquisitions to optimize capital deployment against thin per-trip margins.
- BRTA fitness digitization:The Bangladesh Road Transport Authority's pending online transfer system promises to compress ownership-change timelines from weeks to days.
- CNG retrofit infrastructure:Aftermarket conversion workshops in Narayanganj and Gazipur are expanding capacity to serve petrol-vehicle owners seeking fuel-cost arbitrage.
Market Restraints
- Import tariff structure:The National Board of Revenue's cascading duties on reconditioned Japanese units inflate landed costs beyond middle-class affordability thresholds.
- Chattogram port concentration:Grey-market pipeline dependence on a single maritime gateway creates inventory bottlenecks during monsoon shipping disruptions.
- Emission threshold rigidity:BRTA fitness standards lack graduated phase-in periods, abruptly disqualifying older diesel variants from urban registration.
Strategic Opportunities
- Sylhet Division penetration:Underdeveloped dealer infrastructure in northeastern districts offers first-mover positioning for platform-based aggregators.
- Embedded finance partnerships:Microfinance institutions are piloting vehicle-secured lending products tailored to owner-operator cash-flow patterns.
- Blockchain title verification:Distributed ledger pilots at BRTA could eliminate duplicate-registration fraud and accelerate buyer confidence.
Industry Challenges
- Diagnostic technician scarcity:Engine-computer analysis capability concentrates in Dhaka, leaving regional dealers dependent on visual inspection.
- Fitness certification backlog:BRTA inspection queue delays strand inventory capital for 30-60 days beyond planned turnover cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Used Car Market |
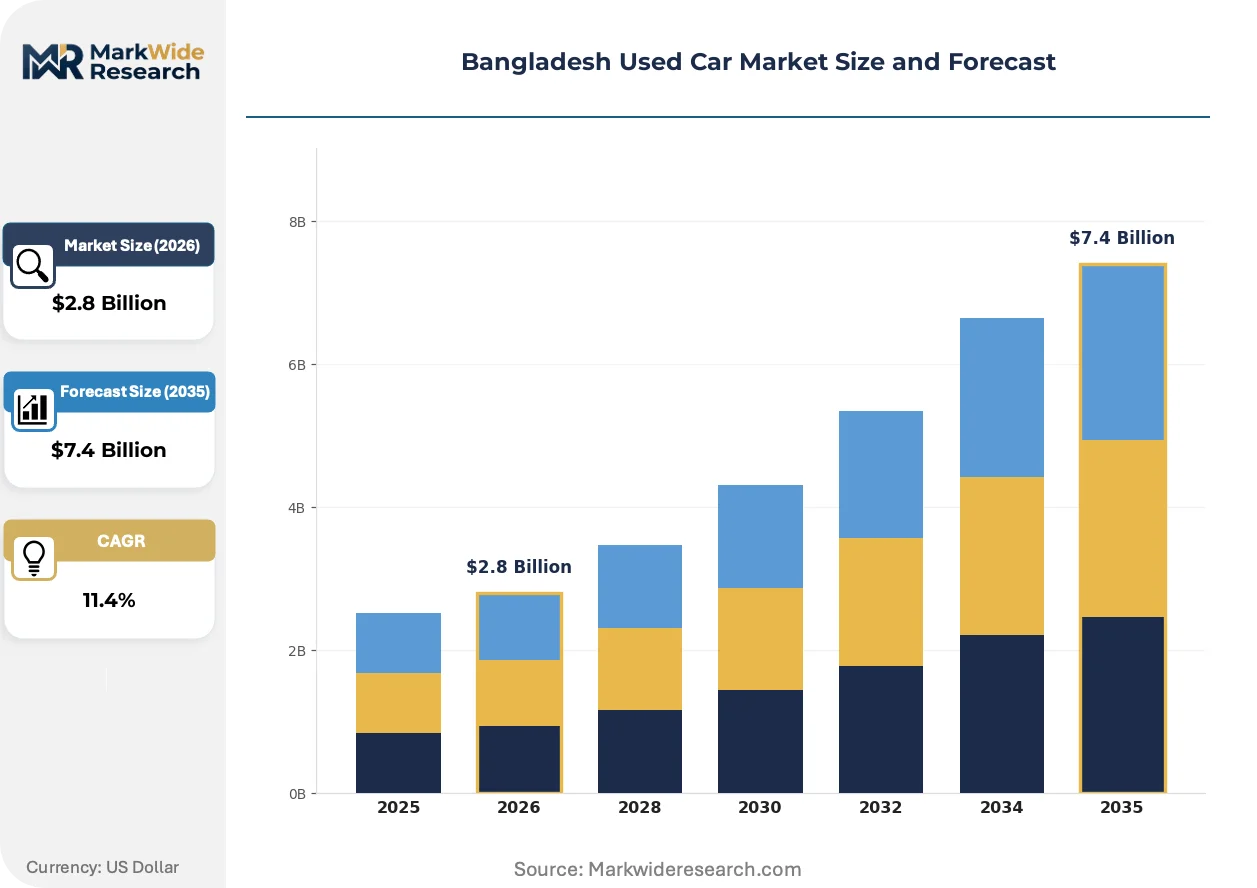
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Pickup Fuel Type: Petrol, Diesel, CNG, Electric Model Year: 2010-2015, 2016-2020, 2021-2022, 2023 Transmission: Automatic, Manual, Semi-Automatic, CVT |
| Companies Covered | HNS Automobiles, Bhalogari.com, Executive Motors Limited, Carbarn Bangladesh, Car Haat, Continental Motors, Auto Museum Ltd, Garirbazar.com, Biswas Imports, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Used Car Market Trends and Innovations
Digital aggregation platforms are compressing information asymmetry between scattered rural sellers and urban buyer pools, while regulatory digitization promises to reshape title-transfer velocity.
Telematics-enabled condition scoring is unifying odometer verification with engine-diagnostic data streams. Ride-hailing fleet managers are adopting these tools to standardize procurement decisions across decentralized buying teams. This unifying capability is compressing price negotiation cycles and reducing post-purchase mechanical dispute rates.
BRTA's phased fitness-certification digitization is mandating biometric owner verification and centralized emission-database integration. Workshop operators must now upload diagnostic reports directly to authority servers before certificate issuance. Chattogram-based importers are responding by pre-certifying inventory at Japanese auction-source facilities to bypass domestic inspection queues.
Peer-to-peer transaction platforms are displacing traditional dealer intermediation for sub-500,000 Taka vehicle segments. Younger buyers in Dhaka's Dhanmondi and Gulshan districts are prioritizing platform-verified listings over physical lot visits. This behavioral pivot is most pronounced among first-time purchasers financing through mobile-wallet-integrated lenders.
Bangladesh Used Car Market Segmentation
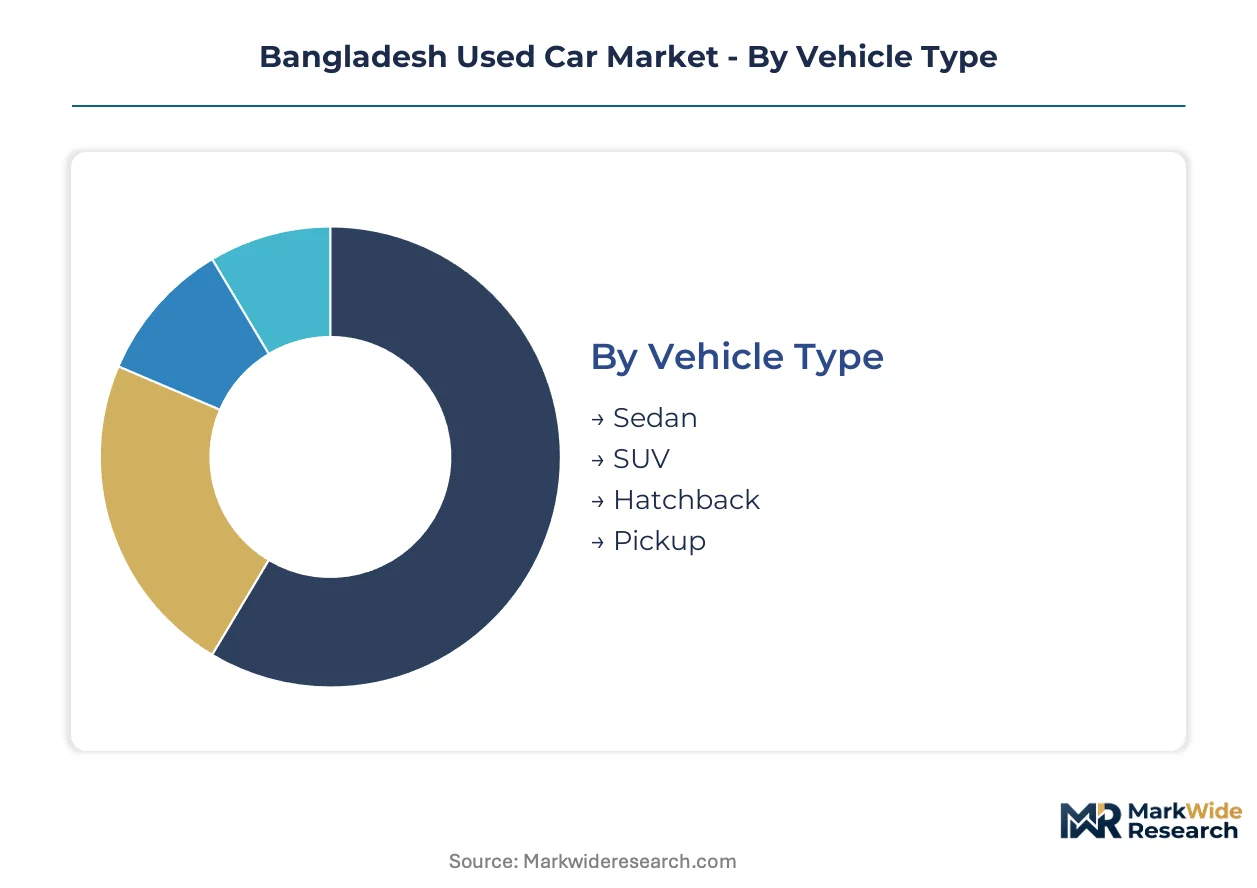
Segmentation in Bangladesh's used car market reveals how vehicle replacement cycles, fuel economics, and regulatory compliance reshape procurement priorities across buyer categories. Understanding these divides enables inventory positioning that matches Dhaka's congestion constraints against Chattogram's port-access advantages.
Vehicle Type:
Upgrade cycles from two-wheelers and aging first cars are concentrating demand in body styles that balance parking efficiency with ride-hailing revenue potential.
- Sedan:Three-box configurations dominate Dhaka Division transactions, with 1,300-1,500cc displacement brackets preferred by Uber and Pathao fleet operators seeking rear-seat comfort for airport and inter-district routes. BRTA fitness compliance rates run highest among Japanese-sourced Toyota Axio and Honda Grace units.
- Hatchback:Compact two-box designs with sub-4-meter lengths command premium pricing in Gulshan and Dhanmondi residential zones where parking bay dimensions constrain larger vehicles. Maruti Swift and Toyota Vitz variants turn inventory fastest among first-time buyers exiting motorcycle ownership.
- SUV:High-clearance unibody and ladder-frame vehicles attract Sylhet and Chattogram buyers navigating rural road degradation during monsoon seasons.
- Pickup:Cab-chassis configurations serve Narayanganj and Gazipur commercial fleets moving construction materials and garment exports.
Volume placements concentrate in Sedan; the faster expansion belongs to Hatchback.
Fuel Type:
Operating cost tiers separate owner-operators from fleet managers, with fuel arbitrage opportunities driving conversion decisions across vehicle age brackets.
- Petrol:Port-injected and direct-injection gasoline engines retain liquidity in secondary markets due to workshop familiarity and parts availability, though per-kilometer economics pressure commercial users toward alternatives. Private buyers in Dhaka's middle-class segments prioritize petrol reliability over conversion complexity.
- CNG:Factory-fitted compressed natural gas systems and aftermarket retrofits capture the steepest demand trajectory, with conversion workshops in Tongi and Fatullah running multi-week backlogs. BRTA registration data shows CNG vehicles commanding resale premiums despite cylinder-space tradeoffs.
- Diesel:Compression-ignition engines face accelerating fitness-certification disqualification under tightened particulate thresholds.
- Electric:Battery-electric vehicles remain nascent, constrained by charging infrastructure absence and import tariff treatment.
Transaction liquidity pools in Petrol; margin expansion concentrates in CNG.
Model Year:
Depreciation curves intersect with safety-feature mandates and financing eligibility windows to create distinct value bands.
- 2016-2020:This bracket balances electronic stability control and dual-airbag availability against depreciation-softened pricing that microfinance lenders will collateralize. Ride-hailing fleet buyers target this vintage for optimal capital-efficiency against remaining service life.
- 2010-2015:Pre-safety-mandate vehicles trade at steep discounts, attracting cash-constrained rural buyers in Rajshahi and Khulna divisions where BRTA enforcement remains patchy.
- 2021-2022:Near-new inventory carries factory warranty remnants but faces affordability compression from import duty structures.
- 2023:Current-year used units represent distress sales and fleet rotation, commanding minimal discount to new.
Financing penetration peaks in 2016-2020; absolute volume concentrates in 2010-2015.
Transmission:
Driver-pool composition and traffic conditions separate automatic preference zones from manual-transmission strongholds.
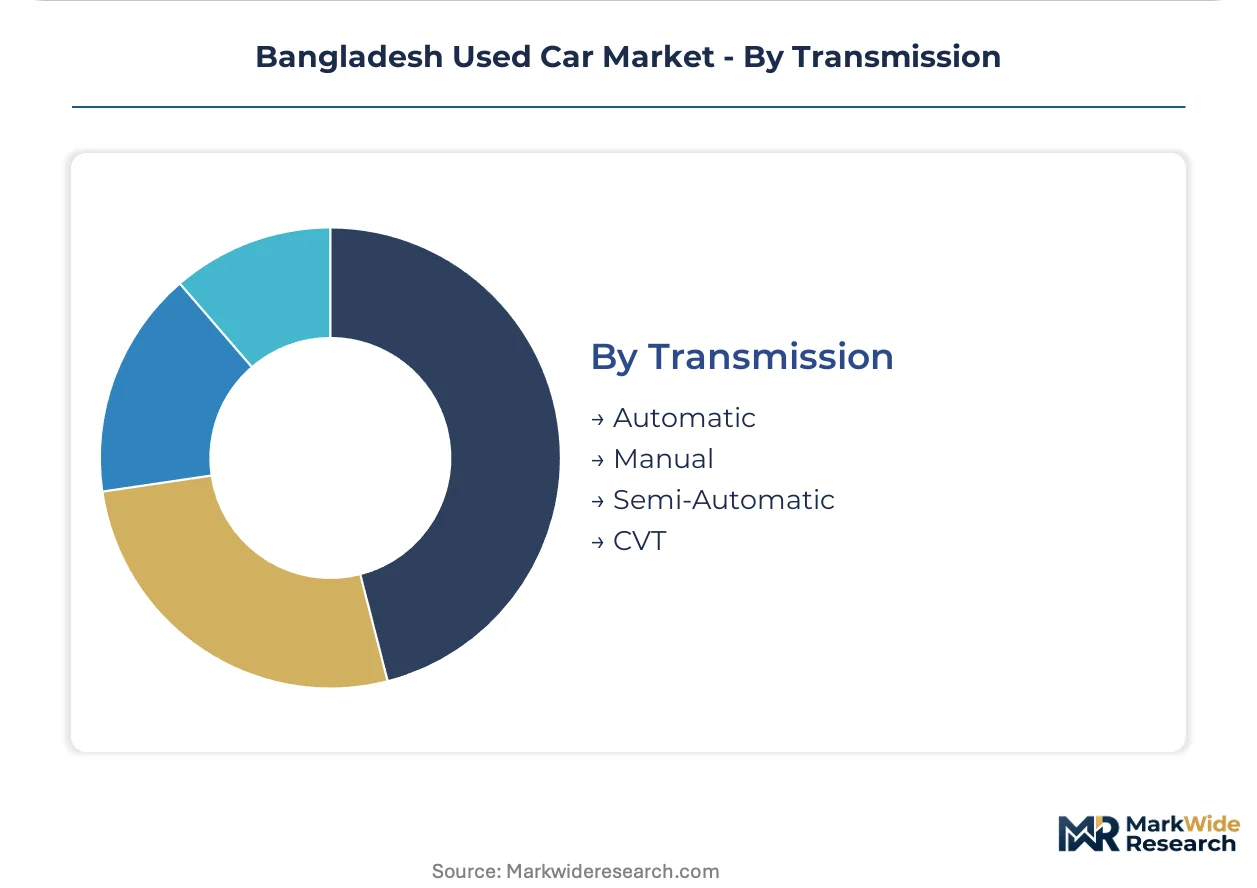
- Automatic:Torque-converter and dual-clutch systems dominate Chattogram and Dhaka urban transactions, where stop-start congestion erodes manual-clutch durability and driver fatigue concerns mount among fleet operators. Female buyer participation correlates with automatic availability in platform listings.
- Manual:Synchronized manual gearboxes retain preference in commercial and rural segments where repair accessibility and fuel-economy optimization override convenience factors.
- Semi-Automatic:Automated manual transmissions occupy a narrow niche, primarily in European-sourced grey-market units.
- CVT:Continuously variable transmissions from Japanese manufacturers dominate hybrid-sourced inventory, with belt-replacement cost anxiety tempering resale premiums.
Urban transaction share concentrates in Automatic; rural affordability anchors Manual.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chattogram port's Japanese import pipeline anchors vehicle supply flows into Bangladesh's fragmented secondary automotive market. Dhaka Division concentrates transaction liquidity through its dense ride-hailing fleet networks and digital platform penetration. Sylhet and Rajshahi divisions present underdeveloped dealer infrastructure with distinct demand profiles shaped by remittance inflows and agricultural income cycles.
Dhaka Division
Ride-hailing fleet operators in Gulshan, Dhanmondi, and Mirpur drive bulk acquisitions of 2016-2020 model-year sedans for airport route optimization. BRTA fitness certification digitization trials in Tejgaon are compressing ownership-transfer timelines from weeks to days. Mohammadpur and Jatrabari host the densest concentrations of CNG conversion workshops serving commercial owner-operators.
Chattogram Division
Port-access advantages position Chattogram as the primary entry node for Japanese auction-sourced inventory, with grey-market importers clustering around the maritime gateway. The National Board of Revenue's tariff collection infrastructure concentrates at this single point, creating customs clearance bottlenecks during monsoon shipping disruptions. Halishahar and Agrabad house the largest bonded warehouse facilities for pre-certified vehicle staging.
Sylhet Division
Remittance-funded purchasing power in northeastern districts sustains demand for premium Japanese hatchbacks despite sparse formal dealer presence. Sylhet Metropolitan Police traffic enforcement maintains patchier BRTA fitness compliance verification than Dhaka counterparts. Beanibazar and Moulvibazar sub-districts show emerging platform-adoption rates among younger buyers exiting motorcycle ownership.
Rajshahi Division
Agricultural commodity income cycles in northwestern districts generate seasonal demand spikes for utility-focused pickups and diesel variants. Pre-2015 vehicle segments trade at steep discounts here as BRTA enforcement capacity lags urban divisions. Naogaon and Chapainawabganj function as informal cross-border supply nodes for Indian-origin used vehicle flows.
Khulna Division
River-port logistics and shrimp export earnings support commercial vehicle demand across southwestern districts with distinct body-style preferences. Jashore and Kushtia sub-regions exhibit growing CNG retrofit adoption among petrol fleet operators seeking fuel-cost arbitrage. Khulna City dealer networks remain dependent on Dhaka-based diagnostic technicians for engine-computer analysis.
Bangladesh Used Car Market Competitive Landscape
Platform-based aggregation dominates the current competitive landscape as digital intermediaries displace traditional lot-based intermediation. The vendor base stratifies across three tiers: national platform aggregators with venture-scale funding, regional dealer networks with certified pre-owned programs, and port-proximate importers controlling grey-market supply chains. Strategic archetypes include digital-first marketplaces reducing information asymmetry, service-integrated dealers capturing aftermarket revenue, and auction-source specialists leveraging Chattogram customs relationships. Consolidation pressures and embedded finance partnerships represent the dominant competitive moves reshaping positioning.
Within the digital aggregation tier, Bhalogari.com and Garirbazar.com occupy positions as platform-native intermediaries connecting scattered rural sellers with urban buyer pools. Among dealer-integrated operators, Executive Motors Limited exemplifies the certified pre-owned archetype through in-house service infrastructure backing warranty programs. Carbarn Bangladesh represents the import-specialist segment with Japanese auction-source relationships and port-proximate logistics control. HNS Automobiles and Continental Motors sit within the established Dhaka-based dealer category, while Auto Museum Ltd and Car Haat occupy niche positioning in platform-verified sub-segments.
| Leading Market Players |
|---|
| HNS Automobiles |
| Bhalogari.com |
| Executive Motors Limited |
| Carbarn Bangladesh |
| Car Haat |
| Continental Motors |
| Auto Museum Ltd |
| Garirbazar.com |
| Biswas Imports |
| Others |
Pricing and Supply Chain Analysis
BRTA fitness-certification digitization is compressing ownership-transfer timelines while elevating compliance premiums for pre-certified inventory, simultaneously reshaping dealer working-capital requirements and pricing power across Dhaka-based networks.
Pricing Analysis
Warranty-backed certified pre-owned programs from Executive Motors Limited and similar dealer-integrated operators command structural premiums over platform-only transactions. Three-tier pricing structure across certified-warranty, platform-verified, and unbundled peer-to-peer segments reflects after-sales service inclusion and diagnostic transparency gradients. Pricing pressure stems from CNG conversion workshop backlogs that strand petrol-vehicle inventory capital. First-time buyers financing through microfinance channels exhibit highest price sensitivity; fleet operators prioritize total-cost-of-ownership over acquisition price.
Supply Chain Analysis
BIS brake-system and headlamp specifications gate Japanese auction-source eligibility, filtering import flows before Chattogram port arrival. Supply concentrates in Japan, Thailand, and India as primary sourcing markets, with grey-market pipelines drawing from UAE re-export hubs. Raw material dependencies span steel chassis components, catalytic converter substrates, and CNG cylinder alloys. Single-gateway vulnerability at Chattogram port creates monsoon-season logistics chokepoints. Distribution runs through bonded warehouse staging, dealer lot networks, and emerging platform-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as platform aggregators pursue backward control over inspection infrastructure and dealer networks acquire captive CNG conversion capacity.
For Market Incumbents: Extend certified pre-owned warranty programs into rural divisions where diagnostic technician scarcity creates service moats. Acquire or partner with Narayanganj and Gazipur conversion workshops to capture CNG retrofit margins. Platform-based entrants threaten dealer intermediation; fitness-certification digitization accelerates disintermediation risk.
For New Entrants and Emerging Players: Peer-to-peer transaction platforms below 500,000 Taka price points offer the most penetrable white-space entry. Sylhet Division's remittance-funded demand and sparse dealer infrastructure presents platform-first positioning opportunity. Mobile-wallet-integrated lending partnerships provide the critical go-to-market angle for first-time buyer acquisition.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-aggregator acquisitions by regional automotive groups seeking digital distribution. Long-term viability hinges on embedded finance penetration and inspection infrastructure control. Acquisition target archetype: dealer networks with Chattogram port relationships and in-house service capacity. BRTA fitness-certification queue resolution rates signal inflection timing for inventory velocity recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Fitness Pre-Certification at Source | Japanese auction-source pre-certification bypasses domestic BRTA inspection bottlenecks at Chattogram. |
| Embedded Finance Partnerships | Microfinance vehicle-secured lending aligns repayment schedules with owner-operator cash-flow patterns. |
| CNG Conversion Capacity Integration | Dealer acquisition of Tongi and Fatullah workshop capacity captures fuel-arbitrage retrofit demand. |
| Blockchain Title Verification Pilot | BRTA distributed-ledger trials eliminate duplicate-registration fraud and accelerate buyer confidence. |
| Sylhet Division Platform Expansion | Aggregator first-mover positioning in northeastern districts exploits underdeveloped dealer infrastructure. |
Research Methodology
Independent corroboration across BRTA registration databases, Chattogram customs clearance records, and platform transaction logs underwrites the qualitative findings. Primary interviews with fleet procurement managers, CNG conversion workshop operators, and dealer network principals combined with secondary validation from National Board of Revenue tariff disclosures, BIS technical standards, and ride-hailing platform operational data. Bottom-up vehicle registration analysis and top-down market sizing triangulate volume estimates.
Comparable-period anchoring to pre-digitization and post-digitization BRTA processing intervals established forecast trajectory baselines. Segmentation modeling spans vehicle type, fuel architecture, model-year vintage, transmission configuration, and regional adoption patterns across the analysis window. CAGRs derive from inventory turnover velocity, fitness-certification compliance rates, and import pipeline flow assumptions. Forecast inputs include ride-hailing fleet expansion trajectories and CNG infrastructure buildout schedules.
The model holds under stable BRTA digitization rollout and monsoon-season port operability; deviation in regulatory enforcement intensity or Chattogram logistics disruption would shift supply elasticity and pricing dynamics. Forecasts reflect documented assumptions regarding fitness-certification queue resolution and embedded finance penetration curves. A model refresh is warranted upon material change in BRTA biometric verification mandate timing or National Board of Revenue tariff restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
China Used Car Market