
 US Virtual Cards Market | 2026-2036
US Virtual Cards Market Size, Share, and Industry Trends Forecast 2026-2036
US Virtual Cards Market Analytics
Fintech infrastructure investment across the United States is broadening issuer capacity for on-demand virtual card generation. Marqeta leverages its open-API platform to sustain programmable card issuance for enterprise clients. Brex anchors its position in startup and technology company spend management with integrated virtual and physical card controls. Stripe competes through embedded finance distribution, embedding virtual card creation directly into software platforms.
US virtual cards are digitally generated payment credentials with 16-digit numbers, expiration dates, and CVV codes delivered through software interfaces rather than physical plastic, designed primarily for card-not-present transactions where merchant category codes and spend limits can be programmed at issuance. Single-use cards dominate high-security procurement workflows because each transaction employs a unique credential that expires immediately after authorization, reducing fraud exposure. Multi-use cards serve recurring vendor payments and subscription management where tokenization preserves credential continuity across billing cycles while maintaining dynamic security parameters.
The Consumer Financial Protection Bureau enforces Regulation E protections on virtual card transactions, compelling issuers to maintain dispute resolution infrastructure and liability frameworks comparable to traditional debit products. The Federal Reserve's FedNow instant payment network and Nacha's ACH operating rules create competitive pressure on virtual card pricing models as real-time alternatives mature. Stakeholders must monitor how open banking data-sharing standards under the CFPB's Section 1033 rulemaking reshape authentication requirements and platform interoperability for virtual card provisioning.
Market Dynamics
Programmable spend controls embedded at card issuance are compressing procurement approval cycles and displacing traditional purchase order workflows across US enterprise finance departments.
Growth Catalysts
- Regulation E Coverage Expansion:The Consumer Financial Protection Bureau's enforcement of dispute resolution and liability protections on virtual card transactions elevates buyer confidence in card-not-present environments.
- eCommerce Platform Integration:Online marketplaces and digital procurement channels are hardwiring virtual card APIs directly into checkout flows, embedding payment credential generation into transaction initiation.
- Merchant Category Code Programmability:Dynamic MCC restrictions at issuance enable granular spend governance that static corporate cards cannot replicate.
Market Restraints
- Interchange Cost Structure:Card network fee schedules impose per-transaction economics that disadvantage virtual cards against ACH and FedNow for high-volume, low-margin vendor payments.
- Issuer Concentration Risk:Virtual card provisioning capacity concentrates among a narrow tier of bank sponsors and BIN sponsors, creating single-point-of-failure exposure for enterprise programs.
- Tokenization Standard Fragmentation:Incompatible security token formats across card networks complicate credential portability and multi-issuer program management.
Strategic Opportunities
- Mid-Market Procurement Departments:Companies with 100-1,000 employees remain underserved by enterprise-grade virtual card platforms, presenting whitespace for tailored spend management solutions.
- Healthcare Vendor Payments:HIPAA-covered entities require auditable, single-use payment credentials for supplier transactions, aligning with virtual card security architectures.
- Real-Time Payment Convergence:Integration of virtual card issuance with FedNow instant settlement rails could compress authorization-to-funding windows from days to seconds.
Industry Challenges
- Legacy ERP Integration Complexity:Enterprise resource planning systems with rigid payment file formats require costly middleware development to ingest virtual card transaction data.
- Fraud Detection Model Retraining:Machine learning systems trained on physical card patterns generate false positives on single-use virtual credentials, degrading authorization approval rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Virtual Cards Market |
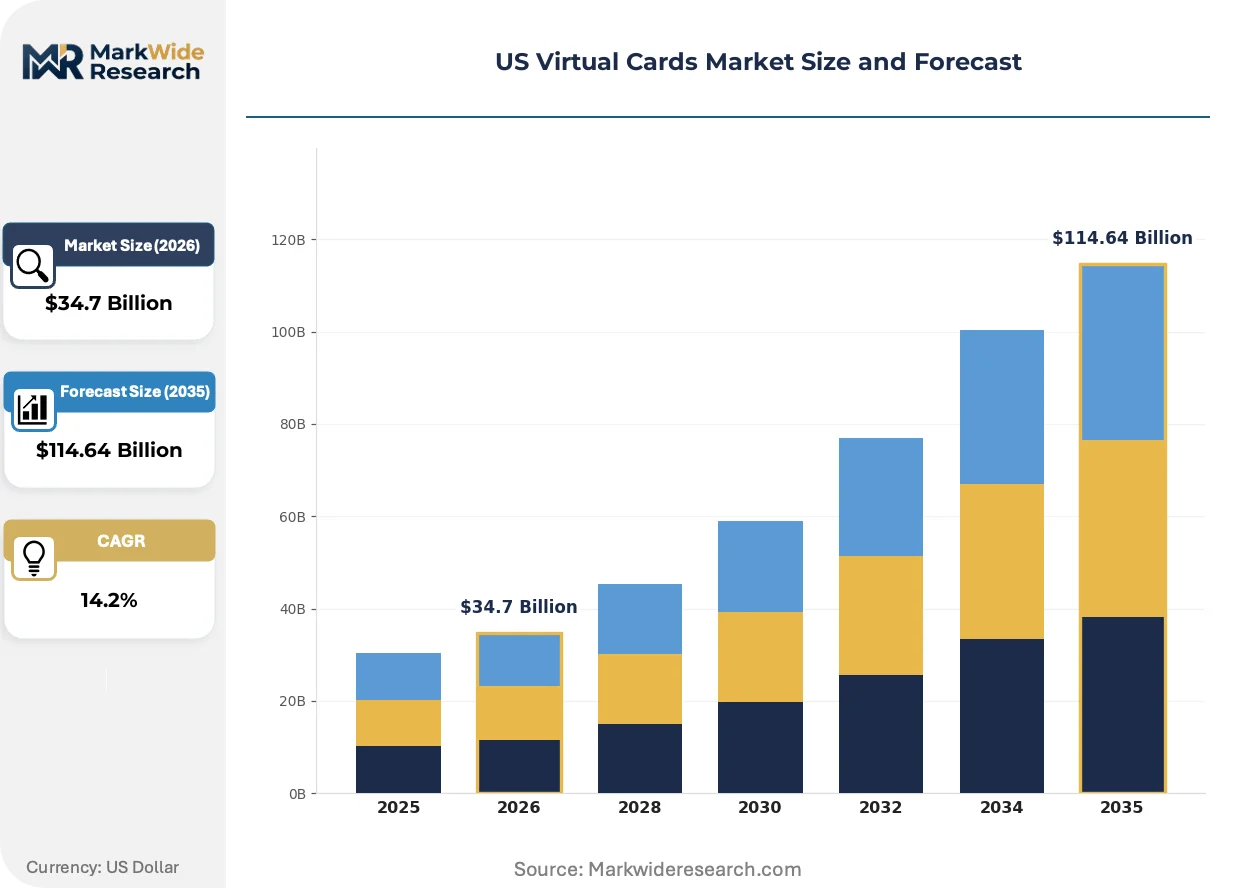
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $114.64 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use Cards, Multi-use Cards, Virtual Card Platforms, Mobile Wallet Integrations End User: Consumers, Small Businesses, Corporations, eCommerce Platforms Technology: Card-not-present Transactions, Encryption, Tokenization, Digital Identity Verification Distribution Channel: Direct Sales, Online Channels, Banking Institutions, Third-party Providers |
| Companies Covered | Visa, Mastercard, American Express, JPMorgan Chase, Marqeta, Stripe, Brex, Revolut, Airwallex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Virtual Cards Market Evolving Landscape
Distributed ledger infrastructure and open banking protocols are fragmenting credential custody models and enabling non-bank entities to originate virtual payment instruments.
Tokenized credential vaulting is decentralizing card data storage away from merchant databases and toward issuer-controlled secure elements. Large retailers and subscription platforms are adopting network tokens to reduce PCI-DSS scope and credential reissuance costs. This architecture is decentralizing fraud liability toward issuers while compressing merchant data breach exposure.
The CFPB's Section 1033 open banking rulemaking is mandating standardized data-sharing APIs between financial institutions and third-party providers. Virtual card platforms must rearchitect authentication flows to accommodate consumer-permissioned account access. Fintech infrastructure providers are responding by building OAuth-compliant consent management layers into their issuance stacks.
Procurement departments are unbundling travel and expense management from virtual card programs, selecting best-of-breed credential providers independent of legacy T&E platforms. This disintermediation is fragmenting vendor relationships that historically bundled issuance with spend analytics. Technology sector finance teams in California and New York are most visibly driving this separation, negotiating direct API contracts with card-as-a-service platforms.
US Virtual Cards Market Segmentation
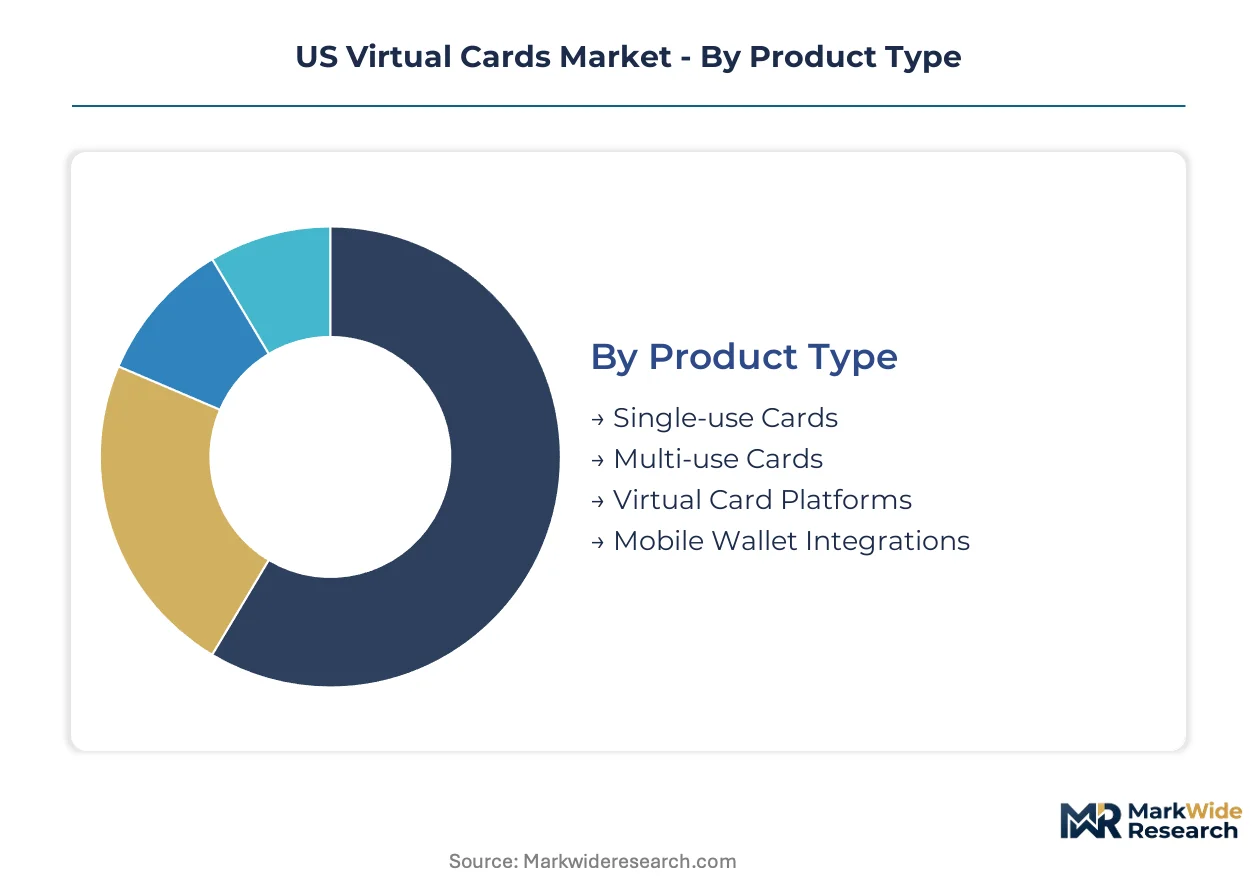
Segmentation in the US virtual cards market reveals how programmable payment credentials adapt to divergent risk profiles, transaction frequencies, and integration requirements across buyer types. Distinct technical architectures serve single procurement events versus recurring subscription flows, while distribution channel choices reflect enterprise IT sophistication and compliance burden tolerance.
Product Type:
Customization intensity spans from fully disposable credentials to persistent platform infrastructure, with standardization rising as solutions scale toward embedded finance distribution.
- Single-use Cards:Each authorization generates a unique 16-digit credential that expires immediately after transaction completion, eliminating credential reuse fraud. Demand concentrates among healthcare procurement departments and government agencies requiring HIPAA-compliant, auditable payment trails for vendor disbursements. These cards command premium per-transaction fees due to higher issuer processing overhead.
- Multi-use Cards:Tokenized credentials persist across billing cycles while maintaining dynamic security parameters adjustable at the transaction level. Corporate treasury teams in technology and professional services sectors favor these for recurring software subscriptions and managed service contracts. Programmable spend limits refresh automatically without reissuance.
- Virtual Card Platforms:API-first issuance infrastructure enables enterprise clients to generate credentials on-demand within existing ERP workflows. These systems integrate with NetSuite, SAP, and Workday environments.
- Mobile Wallet Integrations:Credentials provisioned directly into Apple Pay, Google Pay, and Samsung Pay interfaces for card-present tap transactions. Adoption tracks mobile-first small business banking penetration.
Most installed capacity flows through Multi-use Cards. Expansion is steepest in Virtual Card Platforms.
End User:
Volume concentration shifts from individual consumers toward entity-based procurement as transaction values rise and compliance requirements intensify.
- Corporations:Enterprise finance departments deploy virtual cards to displace purchase order workflows and capture early-payment discounts from suppliers. These programs integrate with Coupa, SAP Ariba, and Oracle procurement suites. The CFPB's Regulation E dispute resolution mandates apply uniformly, elevating vendor confidence in card-not-present acceptance.
- eCommerce Platforms:Online marketplaces embed virtual card generation at checkout to intermediate buyer-seller transactions without exposing primary funding credentials. Demand drivers include marketplace liability reduction and cross-border payment settlement acceleration. These platforms require BIN sponsor relationships and network token vaulting infrastructure.
- Small Businesses:Founders and finance leads at venture-backed startups use virtual cards to enforce departmental budgets without traditional corporate card approval delays. Brex and Ramp dominate this segment with integrated spend management software.
- Consumers:Individual users generate virtual credentials for one-time online purchases to limit merchant data exposure. Adoption tracks privacy concern intensity and data breach incident frequency.
Transaction value concentrates in Corporations. User count expands most quickly in Small Businesses.
Technology:
Security architecture sophistication determines issuer fraud loss ratios and merchant acceptance rates across the credential lifecycle.
- Tokenization:Network tokens replace primary account numbers in merchant systems, reducing PCI-DSS scope and enabling credential updates without reissuance. Large retailers and subscription platforms drive demand for this vaulting infrastructure. Visa and Mastercard token services dominate US deployment.
- Encryption:End-to-end credential protection during transmission and at rest satisfies FedRAMP and SOC 2 requirements for government and healthcare sector procurement. Issuers must maintain HSM-managed key infrastructure.
- Card-not-present Transactions:Virtual credentials designed exclusively for online, phone, and mail-order environments where physical card presence is impossible. These transactions carry higher interchange rates reflecting elevated fraud risk.
- Digital Identity Verification:Biometric and document-based KYC workflows authenticate cardholders before credential provisioning. The CFPB's Section 1033 open banking rulemaking is reshaping consent management for these verification flows.
Fraud loss prevention investment concentrates in Tokenization. Regulatory compliance spending is climbing fastest in Digital Identity Verification.
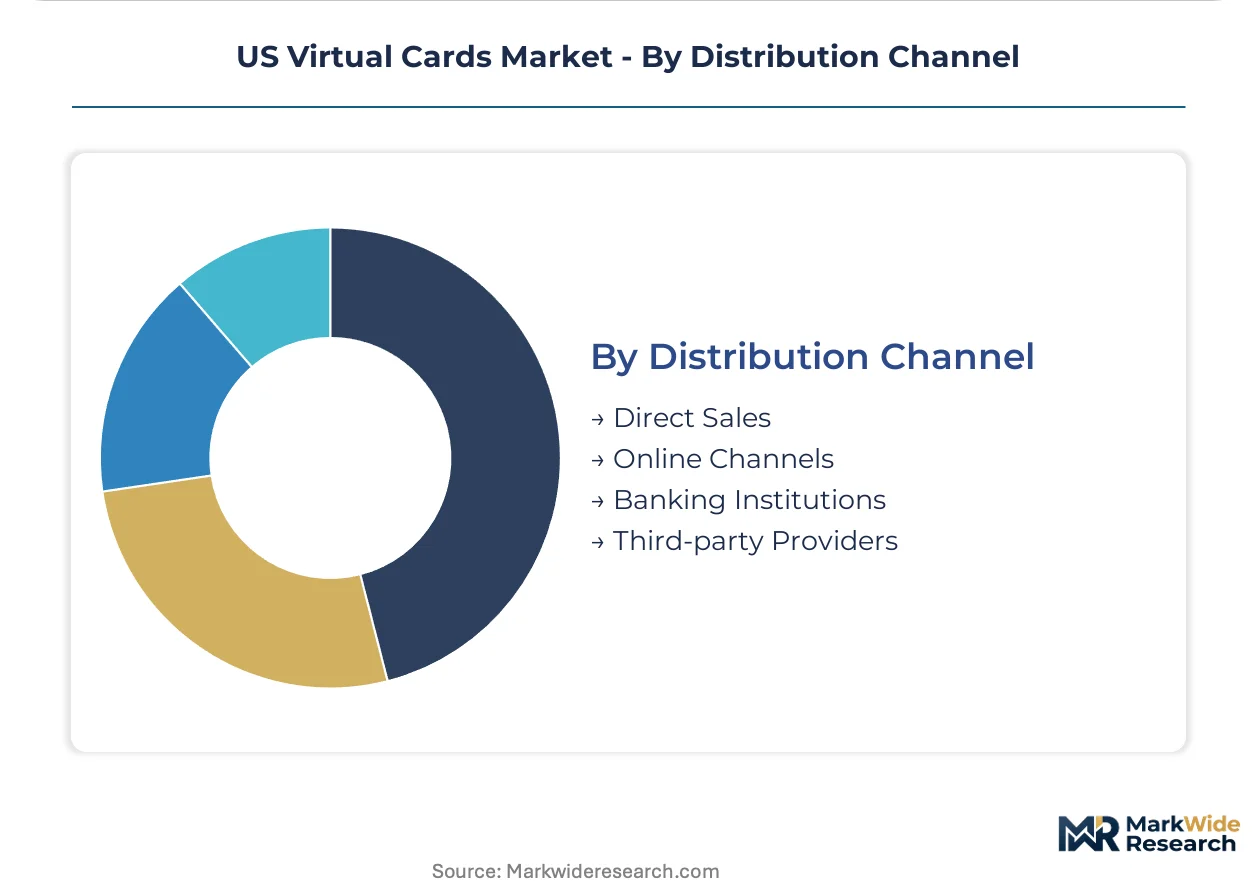
Distribution Channel:
Channel selection reflects enterprise IT maturity, with direct API relationships displacing intermediary-dependent procurement in sophisticated buyer segments.
- Third-party Providers:Fintech infrastructure platforms like Marqeta and Lithic offer card-as-a-service APIs that abstract BIN sponsor and network connectivity complexity. Technology sector finance teams in California and New York negotiate direct contracts with these providers. These arrangements enable custom spend control programming.
- Banking Institutions:Traditional commercial banks bundle virtual card issuance with treasury management and working capital products. JPMorgan Chase and Bank of America dominate corporate virtual card programs through established credit relationships.
- Direct Sales:Enterprise software vendors embed virtual card generation within procurement and expense management platforms. This channel requires dedicated sales engineering resources for ERP integration.
- Online Channels:Self-service portals enable small business and consumer credential generation without sales interaction. These platforms compete on onboarding speed and mobile application quality.
Program revenue flows predominantly through Banking Institutions. API contract volume is expanding most rapidly in Third-party Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping virtual card infrastructure deployment across the United States, with issuers gravitating toward jurisdictions offering streamlined money transmission licensing and favorable fintech charter frameworks. State-level regulatory fragmentation creates compliance cost differentials that influence BIN sponsor location decisions and program manager incorporation choices.
California
Technology sector procurement departments in San Francisco and Los Angeles drive enterprise virtual card adoption for software subscription management and cloud infrastructure payments. The California Department of Financial Protection and Innovation enforces stringent money transmitter requirements on fintech platforms operating statewide. Silicon Valley finance teams negotiate direct API contracts with card-as-a-service providers, bypassing traditional banking intermediaries for credential issuance.
New York
Financial services firms in Manhattan deploy virtual cards for vendor payments and travel expense management across global operations. The New York Department of Financial Services maintains BitLicense and virtual currency frameworks that indirectly shape digital payment infrastructure compliance expectations. Wall Street treasury departments integrate virtual card generation with legacy ERP systems through middleware development partnerships.
Texas
Energy sector procurement teams in Houston utilize single-use virtual credentials for high-value supplier transactions requiring auditable payment trails. The Texas Department of Banking offers streamlined money transmitter licensing relative to coastal jurisdictions, attracting fintech infrastructure providers to Dallas and Austin. Corporate treasury operations in the Permian Basin region are adopting programmable spend controls for field service vendor payments.
Illinois
Healthcare systems in Chicago deploy virtual cards for HIPAA-compliant supplier transactions requiring single-use credential architectures. The Illinois Department of Financial and Professional Regulation enforces consumer protection standards on prepaid and digital payment products sold to state residents. Major hospital networks in the Midwest corridor are consolidating vendor payment workflows onto tokenized virtual card platforms.
Florida
Small business formation rates in Miami and Tampa drive consumer and startup virtual card adoption for privacy-conscious online purchasing. The Florida Office of Financial Regulation maintains disclosure requirements for digital payment instruments marketed to retail users. Fintech marketing operations targeting Latin American cross-border payment corridors concentrate in South Florida metropolitan clusters.
US Virtual Cards Market Competitive Landscape
US-based payment networks and banking institutions anchor the infrastructure tier; European and Asia-Pacific fintech specialists hold challenger positions through API-first distribution models. Market structure concentrates around three strategic layers: incumbent card networks with established BIN ranges, bank-sponsored program managers with treasury relationships, and pure-play fintech issuers with embedded finance distribution. Dominant competitive moves include strategic partnerships between infrastructure platforms and ERP software vendors, plus geographic expansion of BIN sponsor capacity into secondary state markets.
Within the infrastructure-provider tier, Marqeta and Stripe exemplify API-first issuance architectures that abstract network connectivity complexity for enterprise clients. Brex occupies a position representing startup-focused spend management integration, combining virtual credential generation with expense analytics. These three entities anchor distinct competitive vectors: programmable card controls, embedded finance distribution, and vertical software integration.
| Leading Market Players |
|---|
| Visa |
| Mastercard |
| American Express |
| JPMorgan Chase |
| Marqeta |
| Stripe |
| Brex |
| Revolut |
| Airwallex |
| Others |
Value Network & Pricing Analysis
Enterprise procurement departments with 100-1,000 employees anchor pricing power in the US virtual cards market, driving subscription-based SaaS models that bundle API access with per-transaction fees rather than traditional interchange-plus structures.
Pricing Analysis
Program manager margins compress as BIN sponsor concentration intensifies pricing pressure from network fee schedules. Three-tier pricing structures across premium, standard, and economy levels segment by integration complexity and spend control programmability. Healthcare and government buyers exhibit lowest price sensitivity due to compliance requirements, while mid-market SaaS startups drive cost compression through volume-negotiated API contracts.
Supply Chain Analysis
FedRAMP and SOC 2 certifications gate access to federal and healthcare procurement channels, filtering issuer infrastructure providers. Supply concentrates in the United States for BIN sponsorship and program management, with token vaulting infrastructure drawing from Ireland and Singapore for geographic redundancy. Single-source vulnerability runs through the narrow tier of bank sponsors approved for commercial card programs. Distribution runs through direct API relationships and banking institution treasury channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US virtual cards market functions as a stable compounder, with enterprise digitization of procurement workflows delivering predictable expansion across economic cycles.
For Market Incumbents: To counter fintech API-first entrants, JPMorgan Chase and Bank of America should deepen BIN sponsor capacity in Texas and Florida while embedding virtual card generation directly into SAP Ariba and Coupa procurement suites. Channel control over ERP integration workflows remains the critical defensive lever. For New Entrants and Emerging Players: Embedded finance distribution through vertical SaaS platforms offers the most penetrable route, targeting mid-market NetSuite and QuickBooks environments with pre-built spend management modules. Healthcare vendor payments present adjacent whitespace given HIPAA-compliant credential requirements. For Investors and Strategic Acquirers: Corporate banking divisions within top-tier US financial institutions are the most active acquirers in this space, seeking card-as-a-service infrastructure to modernize treasury product suites. Acquisition targets should demonstrate established BIN sponsor relationships and FedRAMP authorization status. The signal to watch is CFPB Section 1033 implementation velocity, which will reshape authentication economics and platform interoperability requirements.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Pursuit | Unlocks federal procurement channel access requiring HSM-managed encryption infrastructure. |
| ERP Middleware Development | Reduces integration friction with Oracle and Workday environments for enterprise treasury teams. |
| Network Token Vaulting Partnership | Compresses PCI-DSS scope for merchants while decentralizing fraud liability toward issuers. |
| Real-Time Payment Convergence | Integrates virtual card issuance with FedNow rails to accelerate authorization-to-settlement windows. |
| Healthcare Compliance Specialization | Captures HIPAA-covered entity procurement through auditable single-use credential architectures. |
Research Methodology
Direct dialogue with virtual card program managers, enterprise treasury directors, BIN sponsor compliance officers, and fintech infrastructure engineers grounded this analysis, combined with secondary validation against CFPB regulatory filings, Nacha ACH operating rules, Federal Reserve payment system disclosures, and SEC 10-K filings from major card issuers. Bottom-up credential volume estimates and top-down enterprise spend penetration models were triangulated to derive market sizing.
Bottom-up analysis modeled virtual card issuance across product type, end user, technology architecture, and distribution channel dimensions, with top-down verification against aggregate corporate payment instrument displacement trends. CAGRs were derived from regression analysis of historical issuance velocity and projected enterprise procurement digitization rates. Network token adoption curves and FedNow integration timelines served as industry-specific forecast inputs across the modeling period.
The model assumes a particular technology adoption path; alternative pathways for distributed ledger credential custody would alter the outlook. Forecasts reflect assumptions regarding CFPB regulatory enforcement continuity and network interchange stability. A model refresh is warranted upon material change in open banking data-sharing rulemaking or FedNow instant payment adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Accelerator Card Market
Payments
Saudi Arabia Payment Gateway Market
Payments
United Kingdom Payment Market
Payments
Europe Payments Market
Payments
In-Vehicle Payment System Market
Payments
Convergent Billing Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Mobile Payment Transaction Market
Payments
Global Prepaid Cards Market
Payments
Biometric Payment Cards Market
Payments
Europe Mobile Payment Market
Payments
China Prepaid Cards Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Australia Payments Market
Payments
Contactless Payment Ring Market
Payments
Smart Home Payments Market