
 Accelerator Card Market | 2026-2036
Accelerator Card Market Size, Share, and Industry Trends Forecast 2026-2036
Accelerator Card Market Analysis
The migration from general-purpose CPU-centric architectures to heterogeneous computing is reshaping server design across the accelerator card industry. NVIDIA Corporation dominates GPU-based accelerator deployment through its sustained investment in CUDA ecosystem lock-in and high-bandwidth memory integration. Intel Corporation competes through its FPGA and Gaudi product lines, leveraging x86 server incumbency to bundle accelerator solutions. Advanced Micro Devices Inc. anchors its position via the Instinct portfolio, specializing in high-performance computing and AI training workloads with competitive memory bandwidth specifications.
An accelerator card is a dedicated expansion component that offloads specific computational tasks from host CPUs, typically incorporating GPU, FPGA, or ASIC silicon with high-bandwidth memory subsystems and PCIe or custom interconnect interfaces for data-intensive parallel processing. High-performance cards command the dominant share of revenue due to their deployment in training large language models where memory capacity and tensor throughput determine utility. FPGA-based accelerator cards represent a structurally distinct segment where programmability sustains premium pricing in financial modeling and low-latency trading applications despite slower volume growth compared to GPU alternatives.
The U.S. Department of Commerce export controls on advanced semiconductor manufacturing equipment constrain the availability of leading-edge accelerator cards in certain markets, reshaping procurement strategies for affected data center operators. China's MIIT domestic substitution mandates and the EU Chips Act funding framework collectively redirect supply chain investments toward regional fabrication capacity and design autonomy. Stakeholders must monitor evolving multilateral semiconductor coordination mechanisms and assess captive supply arrangements against geopolitical access risks.
Market Dynamics
The heterogeneous computing transition is compressing CPU-centric server refresh cycles as data center operators prioritize parallel processing density over single-thread performance. Cloud hyperscalers now specify accelerator-native rack architectures before CPU selection, inverting traditional procurement hierarchies.
Growth Catalysts
- Generative AI Training Clusters:Large language model deployment is pulling GPU-based accelerator procurement from hyperscalers in the United States, China, and Germany. Training workloads require memory-bandwidth-dense configurations that CPU-only servers cannot provision.
- EU Chips Act Funding:The European Union's semiconductor sovereignty program is subsidizing domestic accelerator design capacity in France and the Netherlands. Grants cover both R&D and pilot fabrication lines for AI-optimized silicon.
- MIIT Domestic Substitution Mandates:China's Ministry of Industry and Information Technology directives require state-owned data center operators to source accelerator cards from approved domestic suppliers. This policy is redirecting procurement volumes toward indigenous GPU and ASIC vendors.
Market Restraints
- High-Bandwidth Memory Supply Concentration:HBM3 and HBM3e supply concentrates among three Korean and Taiwanese suppliers. Memory wafer allocation disputes constrain accelerator card production ramps regardless of GPU die availability.
- Export Control Friction:U.S. Department of Commerce Bureau of Industry and Security restrictions on advanced accelerator shipments to specific markets are fragmenting procurement strategies. Affected operators must maintain dual supplier lists and architecture forks.
- Power Density Limitations:700W-plus accelerator cards exceed standard data center rack power and cooling specifications. Retrofit costs for liquid cooling infrastructure delay deployment timelines in legacy facilities.
Strategic Opportunities
- Edge AI Inference Deployment:Manufacturing facilities in Mexico and Vietnam are deploying low-profile accelerator cards for real-time quality inspection. These deployments favor 75W TDP cards with industrial temperature ratings over datacenter-class alternatives.
- FPGA Programmability Premium:Financial services firms in London and Singapore are paying sustained premiums for FPGA-based acceleration in options pricing and risk simulation. Reprogrammability offsets slower peak throughput versus fixed-function ASICs.
- India PLI Scheme Incentives:The Production Linked Incentive scheme for electronics manufacturing is attracting accelerator card assembly and test operations. Design-linked incentives cover domestic development of AI-optimized silicon.
Industry Challenges
- CUDA Software Stack Dependency:Accelerator card vendors outside the incumbent ecosystem face multi-year efforts to port critical workloads. Customer switching costs embed proprietary compiler and library dependencies.
- Advanced Packaging Yield Complexity:CoWoS and EMIB packaging technologies required for HBM integration exhibit yield variability that constrains volume ramps. Defect rates compound across memory die stacking and interposer fabrication steps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Accelerator Card Market |
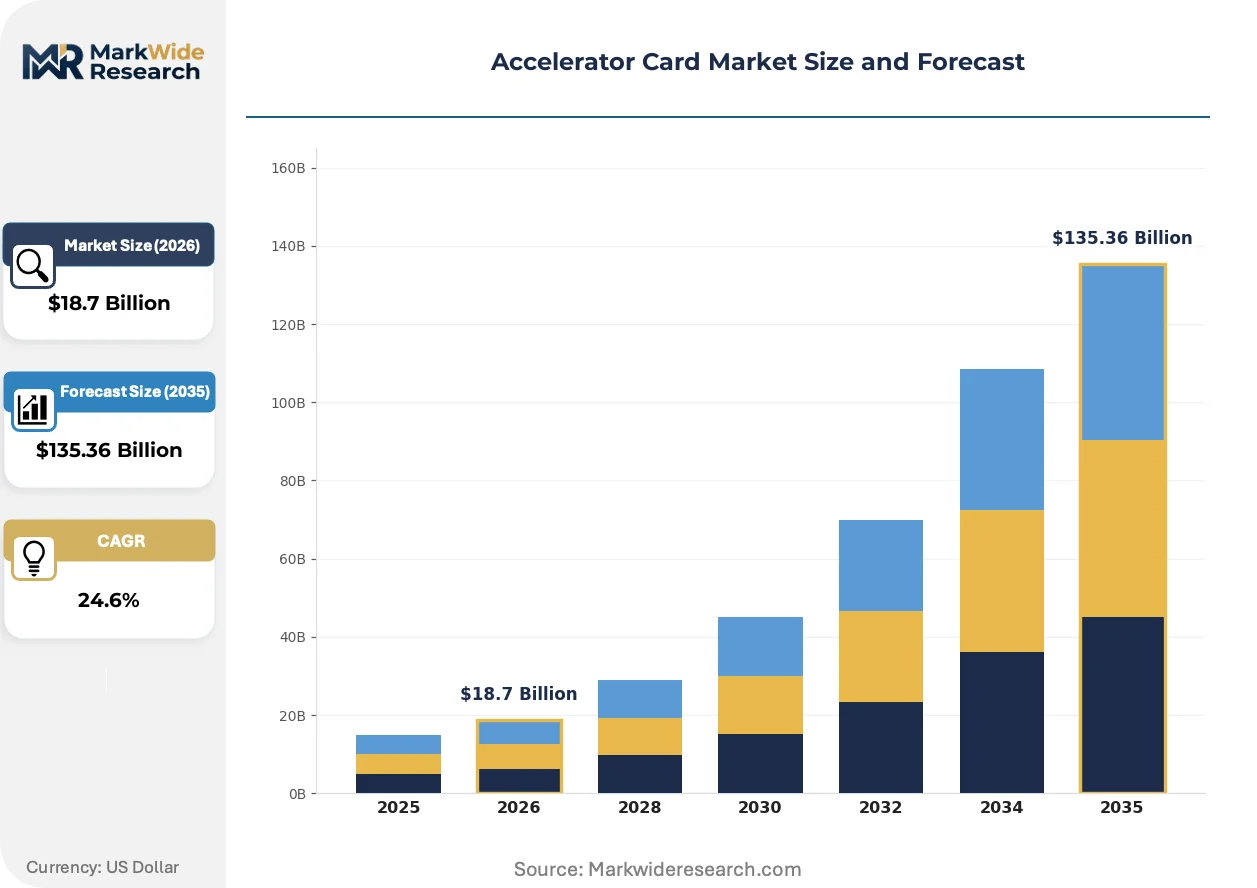
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose Cards, Specialized Cards, Low-Power Cards, High-Performance Cards Technology: FPGA, ASIC, GPU, CPU End User: Data Centers, Enterprise Users, Research Institutions, Cloud Service Providers Application: Machine Learning, Data Analytics, Financial Modeling, Scientific Computing |
| Companies Covered | Xilinx Inc., Fujitsu Ltd., NVIDIA Corporation, HP Development Company, Oracle Corporation, Intel Corporation, Cisco Systems Inc., Achronix Semiconductor Corporation, Advanced Micro Devices Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Accelerator Card Market Emerging Trajectories
Silicon photonics interconnects and CXL memory pooling are converging to reshape accelerator-to-accelerator communication topologies. These technologies are enabling disaggregated server architectures that decouple compute from memory expansion.
Chiplet-based accelerator designs are rendering obsolete monolithic GPU dies for multi-die products with specialized compute, I/O, and memory chiplets. AMD and Intel are shipping chiplet-based accelerators to cloud providers seeking modular upgrade paths. The approach is rendering obsolete single-reticle-limited performance scaling in favor of package-level integration.
The EU AI Act's risk-based classification system is imposing documentation and testing requirements on high-performance accelerators deployed in critical infrastructure applications. Hardware vendors must now provide transparency into training data provenance and model architecture for downstream compliance. Financial services and healthcare deployments in Germany and France are requiring certified accelerator configurations with audit trails.
Hyperscalers are consolidating accelerator procurement through direct silicon partnerships rather than merchant card purchases. Amazon Web Services, Microsoft Azure, and Google Cloud are negotiating custom silicon designs with foundries for exclusive deployment. This behavior is most visible in the United States, where cloud operators possess the volume and engineering resources to bypass standard accelerator card vendors entirely.
Accelerator Card Market Segmentation
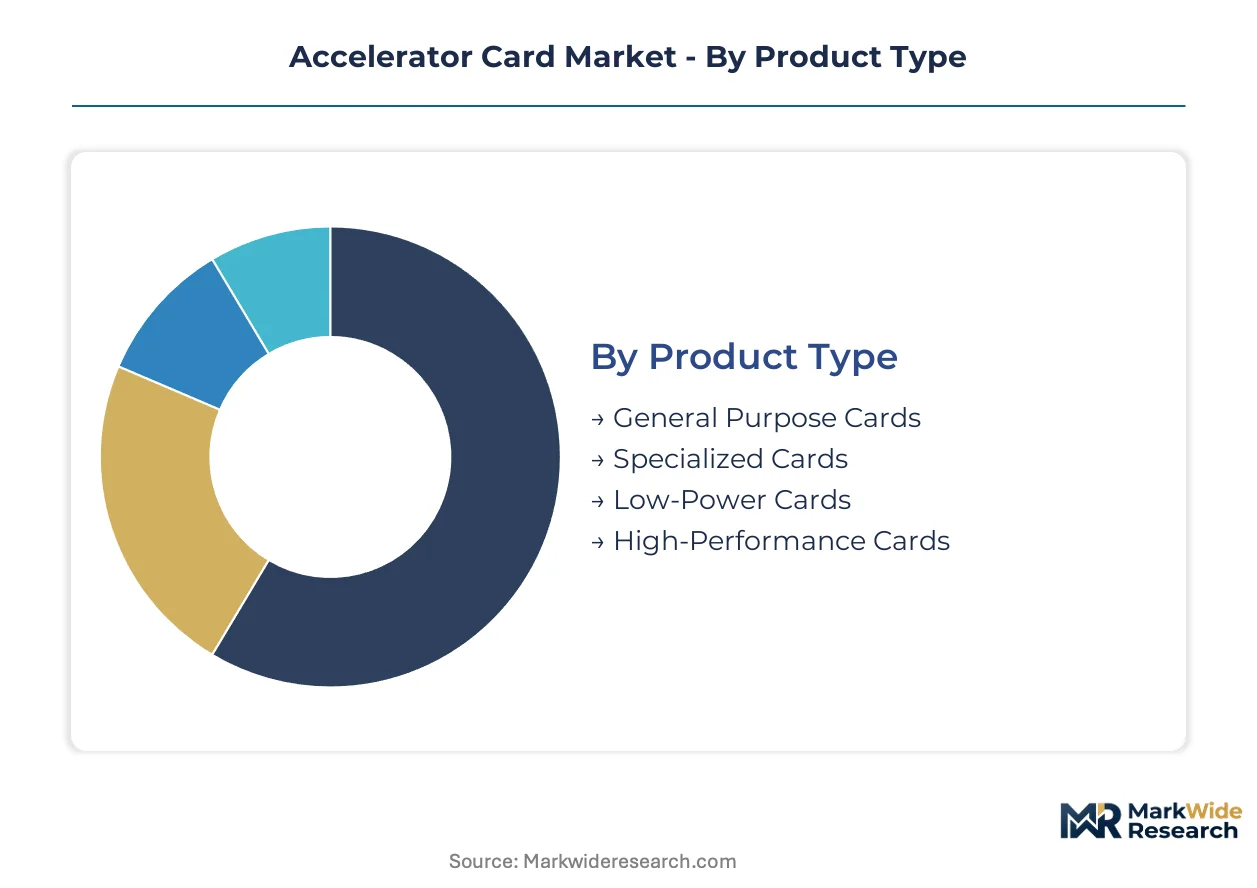
Accelerator card procurement diverges sharply across workload types and infrastructure maturity. Buyers prioritize memory bandwidth density for training clusters while favoring programmability for latency-sensitive applications.
Product Type:
Mature high-performance configurations dominate hyperscaler procurement, while emerging low-power variants capture edge deployment growth.
- High-Performance Cards:These integrate HBM3e memory subsystems and 700W-plus thermal envelopes for large language model training. Demand concentrates in China and the United States where hyperscalers build thousand-card clusters for generative AI workloads, constrained by liquid cooling retrofit requirements and memory wafer allocation bottlenecks.
- Specialized Cards:ASIC-based designs optimize specific inference pipelines through fixed-function silicon. Financial services firms in Singapore and London deploy these for risk simulation workloads where deterministic latency outweighs general-purpose flexibility, though CUDA ecosystem lock-in slows adoption outside incumbent vendor relationships.
- General Purpose Cards:Mid-range GPU configurations serve enterprise data centers with balanced compute-to-memory ratios.
- Low-Power Cards:75W TDP industrial-rated designs target manufacturing quality inspection in Mexico and Vietnam.
High-Performance Cards handle the majority of throughput; Low-Power Cards are expanding most quickly on share.
Technology:
Cost tier stratification separates premium programmable fabrics from volume GPU deployments.
- GPU:Parallel processing architectures with tensor cores and high-bandwidth memory integration anchor training workloads. Cloud service providers in Germany and the United States specify GPU-native rack architectures before CPU selection, inverting traditional procurement hierarchies despite power density limitations exceeding legacy facility specifications.
- FPGA:Reconfigurable logic arrays enable pipeline optimization without silicon respins. Investment banks in London pay sustained premiums for these in options pricing applications, where reprogrammability offsets slower peak throughput versus fixed-function alternatives and justifies higher unit economics.
- ASIC:Custom silicon delivers optimal inference efficiency for frozen model architectures at hyperscale volume.
- CPU:General-purpose acceleration through AVX-512 and AMX extensions serves legacy application compatibility.
GPU commands the dominant procurement volume; ASIC designs are climbing the fastest on deployment share.
End User:
Customer type determines specification rigor and contract structure across the procurement landscape.
- Cloud Service Providers:Hyperscalers in the United States and China negotiate direct silicon partnerships with foundries for exclusive accelerator designs. AWS, Azure, and Google Cloud are bypassing merchant card vendors entirely, consolidating procurement through custom configurations that embed proprietary interconnect topologies.
- Data Centers:Colocation operators face retrofit cost barriers for 700W-plus accelerator deployments in legacy facilities.
- Enterprise Users:Corporate IT departments favor general-purpose GPU configurations with established software stacks.
- Research Institutions:National laboratories prioritize memory bandwidth specifications for climate and materials simulation workloads.
Cloud Service Providers drive the steepest volume expansion; Research Institutions show the fastest specification escalation.
Application:
Margin structure varies by computational intensity and software stack maturity.
- Machine Learning:Training and inference pipelines demand divergent accelerator specifications—memory bandwidth for the former, latency optimization for the latter. The EU AI Act's risk-based classification system now imposes documentation requirements on high-performance accelerators deployed in German and French critical infrastructure, mandating audit trails.
- Data Analytics:Columnar query acceleration favors high memory capacity over raw compute throughput.
- Financial Modeling:Monte Carlo simulation and risk aggregation workloads in London and Singapore drive FPGA premiums.
- Scientific Computing:Weather and molecular dynamics simulations at European and American national labs stress interconnect bandwidth.
Machine Learning absorbs the dominant share of accelerator throughput; Scientific Computing is gaining share fastest on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese foundry output flows primarily to hyperscaler procurement centers in the United States and China, with assembly and test operations migrating toward Vietnam and Mexico under trade diversion pressure. This corridor shapes regional investment patterns and facility buildout timelines.
United States
Hyperscalers in Virginia and Oregon negotiate direct silicon partnerships with foundries for exclusive accelerator designs. The CHIPS and Science Act subsidizes domestic fabrication capacity in Arizona and Texas. Cloud operators in the Pacific Northwest bypass merchant card vendors entirely, consolidating procurement through custom configurations.
China
State-backed AI infrastructure programs in Beijing and Shanghai drive volume procurement of high-performance accelerator cards. MIIT domestic substitution mandates redirect procurement toward indigenous GPU and ASIC vendors. Hyperscaler buildouts in the Yangtze River Delta concentrate demand for memory-bandwidth-dense configurations.
Germany
Industrial automation clusters in Bavaria deploy edge AI inference accelerators for real-time quality inspection. The EU Chips Act funds domestic accelerator design capacity in Dresden and Munich. Research institutions in the Rhine-Ruhr region prioritize memory bandwidth specifications for climate simulation workloads.
Japan
Automotive manufacturers in Nagoya integrate low-power accelerator cards into autonomous driving validation pipelines. METI semiconductor revitalization programs support domestic packaging and test capacity expansion. Electronics assemblers in Kyushu handle chiplet-based accelerator module integration for cloud export markets.
India
Cloud service providers in Bengaluru and Hyderabad establish AI training clusters using imported high-performance accelerator configurations. The PLI scheme for electronics manufacturing attracts accelerator card assembly and test operations to Tamil Nadu. Design-linked incentives cover domestic development of AI-optimized silicon in the Delhi-NCR corridor.
Accelerator Card Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where CUDA ecosystem lock-in concentrates training workloads among incumbent GPU vendors. FPGA specialists command sustained premiums in financial modeling applications where reprogrammability offsets throughput limitations. The competitive landscape rewards backward integration into HBM supply and custom silicon partnerships with hyperscalers.
Within the semiconductor design archetype, NVIDIA Corporation and Intel Corporation exemplify divergent strategic positioning—one anchoring GPU-native parallel processing dominance, the other leveraging x86 server incumbency to bundle heterogeneous acceleration solutions. Advanced Micro Devices Inc. occupies a position between these poles through chiplet-based accelerator architectures targeting high-performance computing clusters. Xilinx Inc. represents the programmable logic specialist tier where reconfigurable silicon sustains pricing power in latency-sensitive verticals despite slower volume expansion.
| Leading Market Players |
|---|
| Xilinx Inc. |
| Fujitsu Ltd. |
| NVIDIA Corporation |
| HP Development Company |
| Oracle Corporation |
| Intel Corporation |
| Cisco Systems Inc. |
| Achronix Semiconductor Corporation |
| Advanced Micro Devices Inc. |
| Others |
Supply Flow & Price Mechanics
Taiwan-to-Arizona freight corridors carry HBM3e memory die and CoWoS-packaged GPU chiplets, with per-kilogram logistics costs feeding directly into downstream price stratification between liquid-cooled training clusters and air-cooled inference configurations. Supply concentration in Korean memory fabs and Taiwanese packaging houses concentrates pricing power among incumbent GPU vendors, while export control compliance costs fragment procurement economics across approved and restricted destination markets.
Pricing Analysis
HBM3e-equipped next-generation accelerator cards command substantial premiums over HBM3-based current-generation offerings and GDDR6-limited prior-generation inventory. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled training configurations from air-cooled inference cards and industrial-rated edge deployments. Price differentiation centers on memory bandwidth certification and liquid cooling infrastructure bundling. Cost compression in mid-range enterprise tiers is intensifying because hyperscaler direct-silicon partnerships bypass merchant card channels entirely. Enterprise IT departments show highest price sensitivity, while financial services firms in London and Singapore accept sustained FPGA premiums for reprogrammability.
Supply Chain Analysis
Extended payment terms from Korean HBM suppliers and supply-chain finance facilities from Taiwanese packaging houses shape working capital requirements for accelerator card assembly operations. Manufacturing concentrates in Taiwan for advanced packaging, South Korea for HBM memory, and Vietnam for final assembly and test. Raw material dependencies include HBM3e memory stacks, silicon interposers for CoWoS integration, and ABF substrate laminates. Single-source vulnerability in HBM wafer allocation constrains volume ramps regardless of GPU die availability. Distribution runs through direct hyperscaler procurement teams and specialized semiconductor distributors serving enterprise data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in CUDA software stack switching costs, where customer recompilation and library migration efforts embed multi-year vendor lock-in. Incumbents benefit from regulatory entrenchment through export control compliance certification requirements that new entrants cannot rapidly replicate.
For Market Incumbents: Entrench position through backward integration into HBM supply via long-term capacity reservations with Korean memory suppliers. Deepen captive packaging capabilities in Taiwan and Arizona to insulate against CoWoS yield variability. Counter emerging ASIC-based inference alternatives by accelerating chiplet-based modular upgrade paths for cloud hyperscalers.
For New Entrants and Emerging Players: Pursue white-space opportunities in industrial edge AI inference deployments across Mexican manufacturing facilities and Vietnamese electronics assembly plants. Target 75W TDP low-power configurations where CUDA ecosystem dependency weakens against deterministic latency requirements. Accelerate go-to-market through direct partnerships with industrial automation OEMs rather than hyperscaler channel competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified semiconductor parents with underutilized FPGA design teams and established financial services customer relationships. Long-term viability favors programmable logic specialists capable of sustaining premium pricing in risk simulation and options pricing verticals. Watch hyperscaler custom-silicon partnership announcements as inflection indicators for merchant card vendor displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| HBM Supply Securement | Long-term capacity contracts with Samsung and SK Hynix lock in memory wafer allocation priority. |
| Liquid Cooling Infrastructure Partnership | Collaboration with data center facility operators in Virginia and Oregon accelerates 700W-plus deployment timelines. |
| Custom Silicon Design Agreement | Direct foundry partnerships enable hyperscalers to bypass merchant accelerator card vendors entirely. |
| FPGA Financial Services Expansion | Reprogrammable logic penetration into London and Singapore investment banks sustains premium pricing power. |
| Edge AI Certification Program | Industrial temperature rating and deterministic latency validation open Mexican and Vietnamese manufacturing markets. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with semiconductor procurement executives at cloud hyperscalers, data center operators, and financial services technology leads; and secondary validation through hyperscaler capex disclosures, foundry utilization reports, and MIIT domestic substitution directive filings. Primary fieldwork captured procurement specification evolution, liquid cooling retrofit timelines, and export control compliance cost structures. Secondary sources included TSMC and Samsung technology roadmaps, U.S. Department of Commerce Bureau of Industry and Security restriction updates, and EU Chips Act funding allocation announcements. Bottom-up volume estimates triangulated against top-down market sizing from foundry capacity allocation and HBM wafer supply projections.
Forecast inputs considered technology transition velocity across GPU, FPGA, and ASIC architectures, memory bandwidth density requirements for large language model training scaling, and power density limitations in legacy data center facilities. Segmentation dimensions modeled include product type tier, technology architecture, end-user procurement structure, and application workload intensity. CAGRs derived from unit shipment trajectories and average selling price evolution across the projection horizon. Industry-specific forecast inputs encompassed hyperscaler direct-silicon partnership announcements and MIIT domestic supplier approval list expansions.
Sensitivities concentrate around multilateral semiconductor export control coordination, HBM3e yield improvement rates, and hyperscaler custom-silicon design commitment levels. Forecasts reflect assumptions regarding foundry capacity expansion timelines and memory supplier allocation discipline. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Enterprise Payment Software Market
Payments
Bitcoin Payments Market
Payments
Retail Point of Sale (POS) Market
Payments
United States Payment Gateways Market
Payments
Denmark Mobile Payments Market
Payments
Japan Mobile Payments Market
Payments
Mobile Card Reader Market
Payments
Germany Payment Gateway Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
UK Virtual Cards Market
Payments
Germany POS Terminal Market
Payments
Spain POS Terminals Market
Payments
Qatar Payments Market
Payments
South Korea Mobile Payment Market
Payments
Europe Prepaid Card Market
Payments
EMV Card Market