
 Point-To-Point Encryption (P2PE) Payment Market | 2026-2036
Point-To-Point Encryption (P2PE) Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Point-To-Point Encryption (P2PE) Payment Market Analytics
The divergence between certified hardware-based P2PE and software-only encryption is hardening as merchants weigh audit cost reduction against deployment flexibility. Bluefin Payment Systems leverages its PCI-validated solution set to anchor premium positioning in healthcare and retail verticals. MagTek Inc. competes through magnetic stripe and chip-reading hardware specialization. Verifone Systems extends its terminal installed base into encryption services across European and North American merchant acquirers.
Point-to-point encryption describes a cryptographic protocol where cardholder data enters an encrypted state at the payment terminal and remains encrypted until reaching the processor's secure decryption environment, typically employing AES-256 or equivalent symmetric algorithms within hardware security modules. Its primary commercial purpose is to render intercepted transaction data useless to attackers while narrowing merchant exposure to PCI DSS audit requirements. Software solutions lead deployment flexibility for small-to-mid retailers seeking rapid integration without terminal replacement, while integrated systems capture margin pools at large hospitality and financial institution clients demanding unified key management. Cloud-based deployment grows fastest among e-commerce platforms requiring elastic transaction volume handling.
PCI Security Standards Council validation requirements shape product development timelines and vendor eligibility for enterprise procurement. In the United States, state-level breach notification laws amplify merchant demand for encryption that excludes sensitive authentication data from internal networks. European GDPR fines for inadequate data protection push financial institutions toward validated P2PE architectures with documented key custodianship. Stakeholders must monitor whether quantum-resistant algorithm migrations disrupt current hardware certification cycles before mid-decade standards revisions.
Market Dynamics
The migration from hardware-validated to software-based encryption architectures is fragmenting procurement criteria as merchants balance PCI DSS audit reduction against terminal replacement costs and cloud-native flexibility.
Growth Catalysts
- PCI DSS compliance scope reduction:US retail merchants face state-level breach notification laws that amplify liability exposure, driving demand for validated P2PE solutions that exclude sensitive authentication data from internal networks.
- EMV chip standard integration:Tokenization convergence with chip-reading protocols is tightening end-to-end security architectures across hospitality and healthcare verticals requiring unified key management.
- Card-present transaction recovery:United States payment volumes are rebounding in physical retail environments, concentrating hardware deployment demand among merchant acquirers seeking certified terminal ecosystems.
Market Restraints
- Hardware security module costs:AES-256 encryption within certified HSMs requires specialized semiconductor components subject to foundry capacity constraints and input cost volatility.
- Validation timeline friction:PCI Security Standards Council certification cycles extend product development schedules, creating procurement eligibility gaps for vendors awaiting enterprise approval.
- Software-only substitution pressure:Non-validated encryption alternatives offer rapid deployment without terminal replacement, eroding pricing power for certified hardware providers in the small-to-mid retailer segment.
Strategic Opportunities
- GDPR-driven institutional demand:European financial institutions face fines for inadequate data protection, pushing adoption of documented key custodianship architectures with validated audit trails.
- Cloud-native e-commerce elasticity:Payment platforms requiring variable transaction volume handling are creating fastest-growing deployment channels for software-integrated encryption services.
- Quantum-resistant algorithm migration:Mid-decade standards revisions will disrupt current hardware certification cycles, opening replacement windows for vendors with next-generation cryptographic implementations.
Industry Challenges
- Cryptographic engineering talent scarcity:Specialized expertise in symmetric algorithm implementation and hardware security module architecture remains concentrated among limited qualified personnel pools.
- Legacy terminal integration complexity:Merchants with embedded magnetic stripe and early chip-reading infrastructure face friction migrating to certified P2PE without full hardware refresh cycles.
- Multi-jurisdiction compliance orchestration:Vendors must synchronize PCI validation, GDPR documentation, and US state breach laws simultaneously, stretching legal and technical certification resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-To-Point Encryption (P2PE) Payment Market |
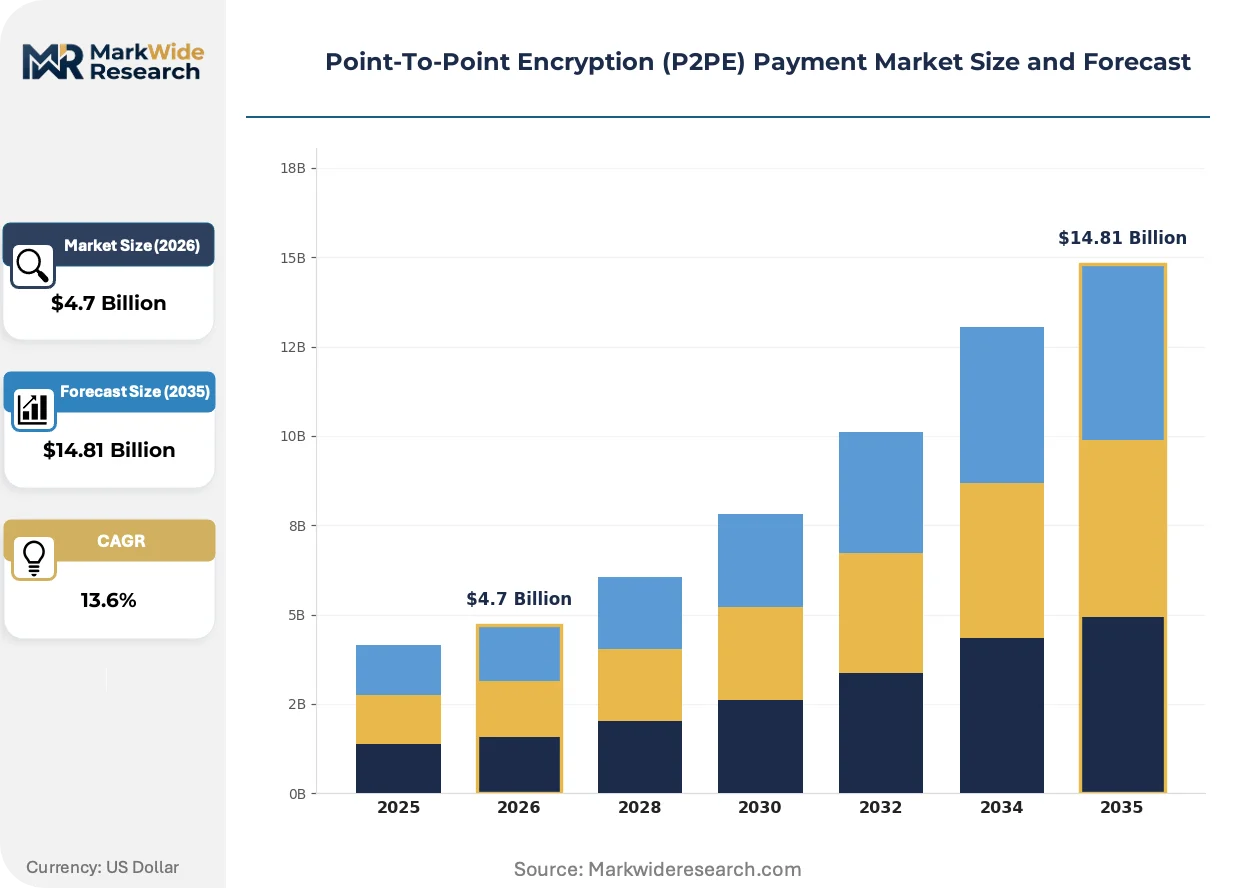
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Software, Hardware, Integrated Systems, Hybrid Solutions Deployment: On-Premises, Cloud-Based, Hosted, Hybrid Service Type: Consulting, Implementation, Support, Maintenance End User: Retailers, Financial Institutions, E-Commerce, Hospitality |
| Companies Covered | Bluefin Payment Systems, MagTek Inc., Ingenico, Verifone Systems, Shift4 Payments, PCI Proxy, ACI Worldwide, Worldpay, Access PaySuite Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-To-Point Encryption (P2PE) Payment Market Evolving Landscape
Encryption architectures are bifurcating between terminal-anchored hardware and API-integrated software layers, reshaping how merchant acquirers bundle security services with payment processing.
Tokenization protocols are consolidating transaction security by replacing primary account numbers with non-sensitive equivalents that retain processing utility without exposing raw cardholder data. Large hospitality chains and healthcare networks are adopting these systems fastest, seeking to compress breach liability exposure while maintaining interoperability with existing processor relationships. The technology is consolidating vendor positioning around unified key management platforms that span in-person and card-not-present channels.
GDPR enforcement actions by European data protection authorities are mandating documented encryption standards for financial institutions handling cross-border payment flows. The regulation's penalty structure is accelerating procurement of validated architectures with auditable key custodianship. EU-based merchant acquirers and payment processors are responding by requiring P2PE certification as a baseline eligibility criterion in vendor selection.
Merchant procurement patterns are fragmenting between terminal purchase and encryption-as-a-service models, with mid-market retailers increasingly favoring subscription-based security bundles over capital-intensive hardware ownership. ISOs and payment facilitators are displacing direct processor relationships as the primary distribution channel for encryption solutions. This shift is most visible in the United States, where independent software vendors are embedding P2PE APIs into vertical-specific point-of-sale platforms.
Point-To-Point Encryption (P2PE) Payment Market Segmentation
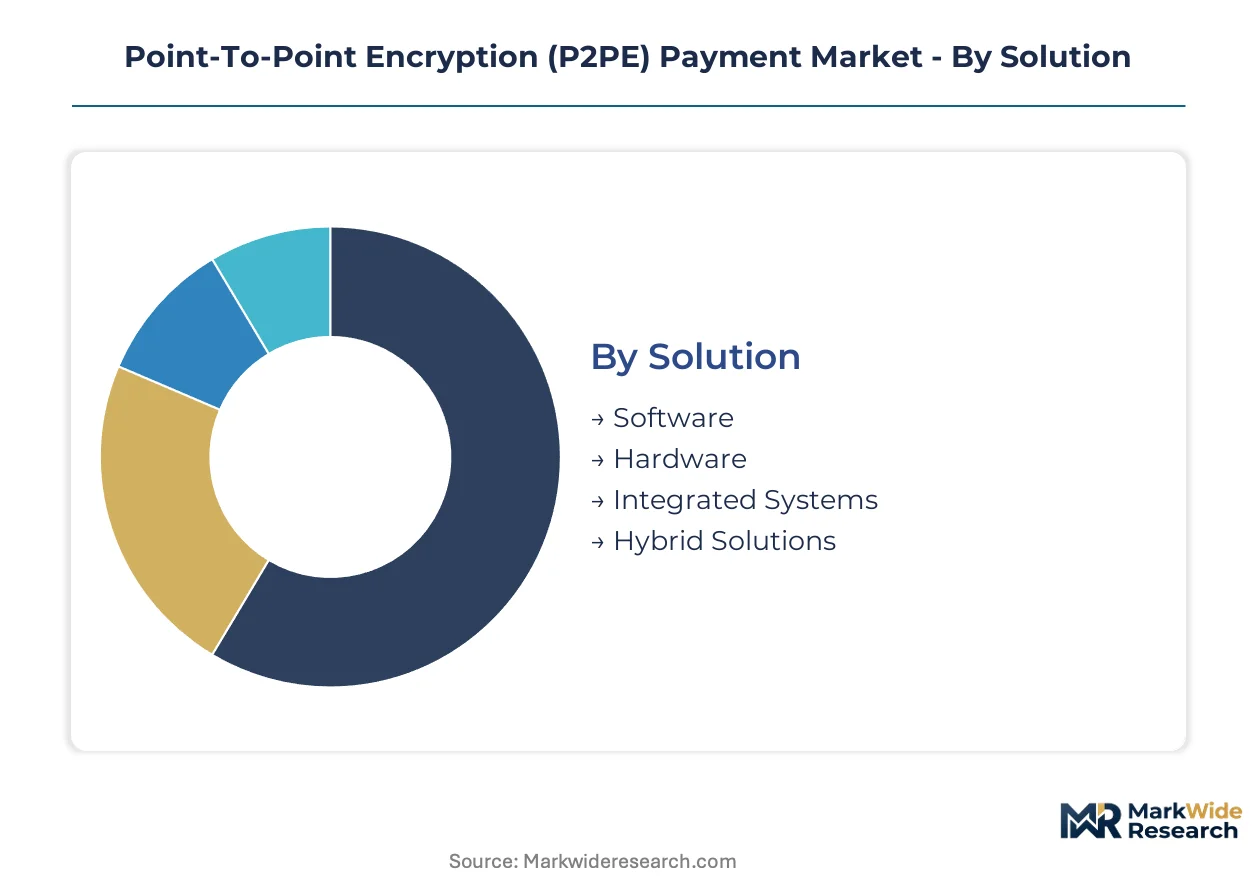
Encryption architectures fragment across hardware-software boundaries and deployment models, creating distinct procurement criteria for merchants balancing PCI DSS compliance against operational flexibility. Each segment carries divergent margin structures and certification requirements that reshape vendor positioning.
Solution:
Technical specification determines whether cardholder data receives hardware-anchored cryptographic protection or software-mediated encryption layers.
- Hardware:Dedicated encryption modules employ AES-256 within certified security enclaves, satisfying PCI-validated P2PE requirements for large retailers facing state-level breach notification laws. Demand concentrates among United States hospitality chains and healthcare networks seeking audit scope reduction through documented key custodianship.
- Software:API-integrated encryption layers deploy without terminal replacement, capturing small-to-mid retailers prioritizing speed-to-market over certification rigor. Cloud-native payment platforms drive fastest expansion as ISOs embed encryption services into vertical-specific point-of-sale platforms.
- Integrated Systems:Unified terminal-software architectures serve financial institutions requiring end-to-end key management across card-present and card-not-present channels.
- Hybrid Solutions:Modular configurations blend certified hardware at high-volume locations with software layers for remote or temporary deployment scenarios.
Hardware leads on scale; software leads on momentum.
Deployment:
Infrastructure ownership models separate capital-intensive on-site installations from subscription-based service arrangements.
- Cloud-Based:Elastic transaction volume handling attracts e-commerce platforms with variable payment flows, eliminating upfront HSM procurement while maintaining cryptographic separation. European payment processors favor this model for GDPR-compliant data residency controls.
- On-Premises:Dedicated hardware installations within merchant data centers satisfy financial institutions requiring direct key custody and air-gapped decryption environments. United States regional banks maintain preference for physical control over cryptographic material.
- Hosted:Third-party managed infrastructure splits operational burden between merchant and service provider, common among mid-market retailers lacking internal security engineering capacity.
- Hybrid:Mixed architectures position cloud layers for peak volume absorption while retaining on-premises HSMs for high-value transaction authentication.
On-premises retains the largest installed base; cloud-based deployment shows the steepest expansion trajectory.
Service Type:
Professional service intensity varies with implementation complexity and ongoing compliance maintenance requirements.
- Implementation:PCI validation pathway navigation and terminal integration demand specialized cryptographic engineering, creating concentrated revenue pools around initial deployment phases for hardware-validated solutions.
- Support:Continuous key management and incident response services generate recurring revenue from enterprise clients maintaining certified P2PE environments.
- Consulting:Compliance scope assessment and architecture design precede procurement decisions, particularly among merchants reconciling GDPR documentation with PCI validation requirements.
- Maintenance:Firmware updates and hardware lifecycle management sustain long-term vendor relationships as encryption standards evolve toward quantum-resistant algorithms.
Implementation commands the highest per-engagement value; support delivers the most predictable recurring revenue streams.
End User:
Vertical-specific transaction patterns and regulatory exposure shape encryption procurement priorities.
- Retailers:Physical storefront networks with high card-present volumes prioritize certified terminal ecosystems to compress PCI DSS audit scope, driving hardware deployment across United States merchant acquirer relationships.
- Financial Institutions:Banks and payment processors face multi-jurisdiction compliance orchestration, demanding validated architectures with auditable key custodianship for cross-border payment flows.
- E-Commerce:Digital-native merchants favor software-integrated encryption for rapid deployment without terminal infrastructure, though tokenization convergence is tightening security requirements.
- Hospitality:Hotels and restaurant chains with distributed property networks seek unified key management platforms spanning reservation systems and on-site payment terminals.
Retailers anchor current revenue concentration; financial institutions are gaining share fastest as regulatory enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryptographic engineering talent clusters in the United States anchor P2PE solution development, while European compliance enforcement and Asian transaction volume growth reshape regional deployment priorities.
United States
State-level breach notification laws in California and New York drive merchant demand for PCI-validated hardware solutions that exclude sensitive authentication data from internal networks. The FTC enforces data security standards through Section 5 authority, creating liability exposure for inadequate encryption practices. Atlanta and Boston host concentrated payment processor operations where certified terminal ecosystems dominate merchant acquirer procurement.
Germany
GDPR enforcement by the Federal Commissioner for Data Protection pushes financial institutions toward documented key custodianship architectures with auditable audit trails. The BaFin mandates encryption standards for payment service providers handling cross-border flows. Frankfurt's banking cluster demands unified key management platforms spanning card-present and digital channels.
United Kingdom
Post-Brexit regulatory divergence creates compliance complexity for payment processors operating across EU-UK boundaries. The Information Commissioner's Office applies GDPR-equivalent standards through the UK Data Protection Act. London's fintech concentration drives cloud-native encryption service adoption among e-commerce platforms.
Japan
METI guidelines on financial data protection encourage hardware-validated P2PE adoption among retail chains with high card-present volumes. The Personal Information Protection Commission enforces encryption adequacy standards for payment data handlers. Tokyo's merchant acquirer networks prioritize terminal-integrated solutions with EMV chip compatibility.
Australia
The OAIC enforces Notifiable Data Breaches scheme requirements that amplify merchant liability for unencrypted cardholder data exposure. APRA prudential standards mandate encryption controls for financial institutions processing retail payments. Sydney's hospitality and tourism sectors drive demand for unified terminal-software architectures across distributed property networks.
Point-To-Point Encryption (P2PE) Payment Market Competitive Landscape
Top-tier vendors anchor PCI-validated hardware certification, while mid-tier specialists compete on software deployment speed and vertical integration flexibility. The vendor base stratifies across three archetypes: terminal manufacturers extending into encryption services, pure-play security specialists, and payment processors bundling encryption with merchant acquiring. Consolidation pressure intensifies as acquirers seek unified key management platforms spanning in-person and digital channels. Strategic partnerships between hardware vendors and cloud platforms represent the dominant competitive move, followed by vertical specialization into healthcare and hospitality sectors.
Within the terminal-integrated tier, Bluefin Payment Systems and Verifone Systems exemplify vendors leveraging hardware certification to capture premium positioning in regulated verticals. MagTek Inc. occupies a specialist position in magnetic stripe and chip-reading hardware, anchoring a niche focused on legacy infrastructure migration. These three represent distinct competitive archetypes: the validated-solution integrator, the terminal-platform extender, and the hardware-specialist incumbent.
| Leading Market Players |
|---|
| Bluefin Payment Systems |
| MagTek Inc. |
| Ingenico |
| Verifone Systems |
| Shift4 Payments |
| PCI Proxy |
| ACI Worldwide |
| Worldpay |
| Access PaySuite Ltd. |
| Others |
Value Network & Pricing Analysis
Semiconductor foundry capacity pricing for specialized encryption chipsets cascades through hardware-validated P2PE tiers, compressing margins on entry-level terminal modules while reinforcing premium positioning for PCI-certified HSM-integrated systems among large US healthcare networks.
Pricing Analysis
The bundled-versus-unbundled service split separates terminal hardware ownership from encryption-as-a-service subscriptions, with three-tier pricing structure across premium, standard, and economy levels anchored by PCI validation grade and key management complexity. Premium tiers capture financial institutions requiring documented custodianship, while economy tiers face price erosion from software-only alternatives eroding certified hardware pricing power. Small-to-mid retailers exhibit highest price sensitivity, prioritizing rapid deployment over certification rigor.
Supply Chain Analysis
PCI Security Standards Council certification gating concentrates qualified component supply among Taiwan, South Korea, and the United States, where AES-256 semiconductor fabrication and hardware security module assembly feed from specialized foundry capacity. Cryptographic processor chips, secure element modules, and EMV-certified terminal chipsets constitute critical inputs. Single-source vulnerability around HSM semiconductor supply creates structural exposure. Distribution runs through merchant acquirer networks and ISO channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Point-To-Point Encryption market reads as a late-cycle quality story, with merchant procurement shifting decisively toward PCI-validated architectures that compress audit scope and breach liability exposure.
For Market Incumbents: Anticipate software-only substitution pressure by accelerating backward integration into cloud-native encryption layers and reinforcing certification investment ahead of quantum-resistant algorithm standards. Channel control through acquirer-exclusive partnerships represents the critical defensive lever against emerging API-first entrants. For New Entrants and Emerging Players: Launch via embedded P2PE APIs within vertical-specific point-of-sale platforms, targeting mid-market hospitality chains with distributed property networks as the most penetrable white space. ISO and payment facilitator channels offer lowest customer acquisition friction. For Investors and Strategic Acquirers: Asymmetric upside sits with software-integrated encryption specialists possessing validated key management architectures, given five-to-ten year viability windows tied to quantum-resistant migration cycles. The signal to watch is PCI Security Standards Council mid-decade standards revision timing.| Strategic Initiative | Industry Significance |
|---|---|
| PCI Validation Investment | Certification ahead of quantum-resistant standards secures enterprise procurement eligibility. |
| Cloud-Native Platform Integration | Elastic transaction handling captures e-commerce platform expansion across European GDPR jurisdictions. |
| Vertical Specialization Partnership | Healthcare network alliances leverage HIPAA breach liability exposure for validated P2PE adoption. |
| ISO Channel Embedding | Independent sales organization relationships displace direct processor sales in mid-market retail. |
| Key Management Unification | Unified terminal-software architectures span card-present and card-not-present channels for hospitality. |
Research Methodology
Bottom-up merchant-acquirer deployment modeling reconciled against top-down hardware shipment tracking forms the analytical core, combining primary interviews with payment processor executives, ISO sales directors, healthcare network procurement officers, and cryptographic engineering leads with secondary validation against PCI Security Standards Council certification databases, SEC filings from terminal manufacturers, and merchant acquirer partnership announcements.
Input-output matrix framing connects terminal hardware volumes, software licensing arrangements, and encryption-as-a-service subscriptions across deployment model, solution type, and vertical end-use dimensions. CAGRs derive from segment-level volume trajectories and value-per-transaction economics, incorporating EMV chip standard migration timelines and GDPR enforcement intensity as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced quantum-resistant algorithm standard revisions, foundry capacity disruptions affecting HSM semiconductor supply, and regulatory divergence between EU and UK data protection frameworks. A model refresh is warranted upon material change in PCI Security Standards Council certification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
US Virtual Cards Market
Payments
Payment Processing Solutions Market
Payments
United States POS Terminals Market
Payments
Egypt Mobile Payments Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Cyprus POS Terminals Market
Payments
United Kingdom Payment Gateway Market
Payments
India Gift Card and Incentive Card Market
Payments
United States Clearing Houses and Settlements Market
Payments
China Virtual Cards Market
Payments
Mpos Terminals Market
Payments
United Kingdom Mobile Payments Market
Payments
United Kingdom Payment Market
Payments
India Payment Gateway Market
Payments
UK Prepaid Cards Market
Payments
China Forex Cards Market