
 In-Vehicle Payment System Market | 2026-2036
In-Vehicle Payment System Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vehicle Payment System Market Analysis
The gap between automotive-grade hardware and fintech software stacks is narrowing as OEMs integrate payment-grade secure elements directly into vehicle ECUs. Tesla leverages its proprietary OS to anchor in-vehicle commerce within a closed ecosystem, while Mastercard competes through tokenization partnerships that extend its network into multiple OEM dashboards. Visa dominates contactless provisioning standards, positioning its token vault as the default rails for fuel, parking, and toll transactions initiated from the driver's seat.
An in-vehicle payment system constitutes an embedded transactional architecture that combines secure element hardware, near-field communication or cellular modules, and tokenized payment credentials to execute financial transactions without physical card presentation. The system typically integrates PCI-DSS compliant encryption, ISO 15118-compliant vehicle-to-grid communication protocols, and HSM-protected key storage to authenticate payments for fuel, charging, tolls, parking, and in-car commerce. Mobile wallet technology leads deployment volume due to smartphone-tethered authentication models that reduce OEM certification burdens, while embedded systems represent the fastest-growing segment as automakers pursue direct revenue streams from software-defined vehicle platforms. Cloud-based deployment models concentrate margin pools through recurring SaaS fees for transaction orchestration, though on-premises architectures persist among European luxury manufacturers prioritizing data sovereignty.
The US Federal Trade Commission scrutinizes biometric payment authentication in vehicles under Section 5 unfair practices authority, while the EU Payment Services Directive 2 mandates strong customer authentication for in-vehicle transactions exceeding contactless limits. Germany's Federal Motor Transport Authority and France's CNIL jointly shape compliance requirements for cross-border driver data flows linked to payment profiles. Stakeholders must monitor whether emerging vehicle-type approval frameworks in major automotive markets will mandate payment security as a condition of homologation, fundamentally altering R&D prioritization for connected car platforms.
Market Dynamics
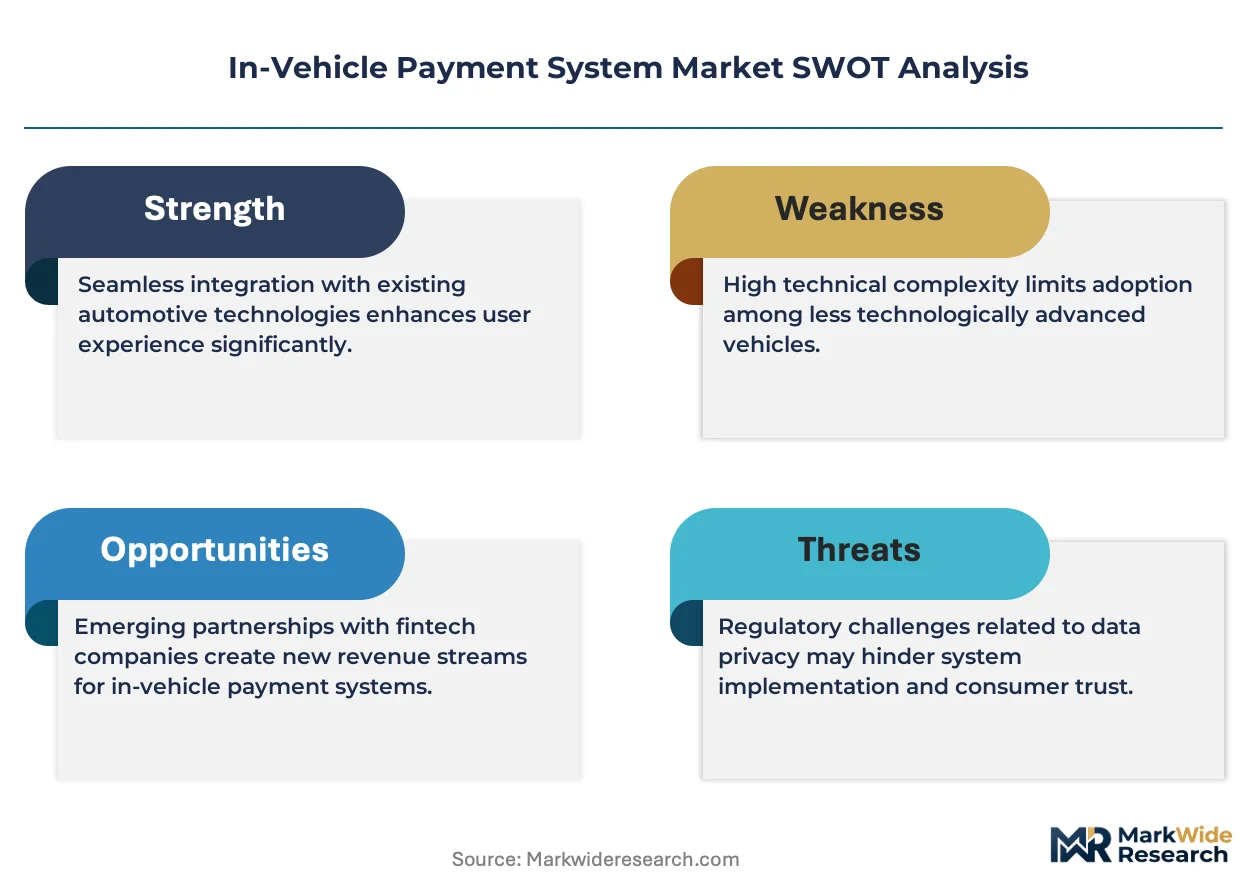
Automotive OEMs are racing to embed payment-grade secure elements directly into vehicle ECUs, collapsing the traditional separation between hardware manufacturing and financial services infrastructure. This convergence forces Tier-1 suppliers to requalify as PCI-DSS certified payment enablers while simultaneously meeting ISO 26262 functional safety standards.
Growth Catalysts
- EU AI Act certification mandates:European regulators now require algorithmic transparency for biometric authentication in vehicles, accelerating standardization of secure payment architectures across German and French automakers.
- Ride-hailing fleet digitization:Commercial fleet operators in urban mobility services demand integrated payment rails to eliminate driver-mediated transactions and capture per-trip commerce revenue.
- ISO 15118 vehicle-to-grid protocols:Bidirectional charging standards create automatic settlement requirements for energy arbitrage, embedding payment logic into power electronics.
Market Restraints
- Secure element supply concentration:Production of automotive-grade HSM chips concentrates among a handful of European semiconductor foundries, creating qualification bottlenecks for new OEM programs.
- PSD2 strong authentication friction:European open banking rules mandate multi-factor verification for transactions above contactless limits, complicating seamless in-vehicle checkout flows.
- Legacy fleet replacement cycles:Commercial vehicle operators retain assets for 7-10 years, delaying hardware refresh rates that would enable universal payment capability deployment.
Strategic Opportunities
- Subscription-based vehicle commerce:Software-defined vehicle platforms enable recurring revenue from in-car retail, parking, and charging services without hardware retrofit.
- India's digital payment infrastructure:The country's unified payments interface creates a regulatory template for real-time settlement that automakers can adapt for emerging market expansion.
- NFC-ultrawideband convergence:Combining proximity protocols enables hands-free fueling and charging authentication, differentiating premium vehicle experiences.
Industry Challenges
- Cross-functional talent scarcity:Teams must simultaneously understand automotive functional safety, PCI-DSS compliance, and embedded systems engineering—a combination rarely found in single labor pools.
- Homologation timeline compression:Vehicle-type approval frameworks in Germany and France are expanding to include payment security validation, adding certification gates to already compressed development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vehicle Payment System Market |
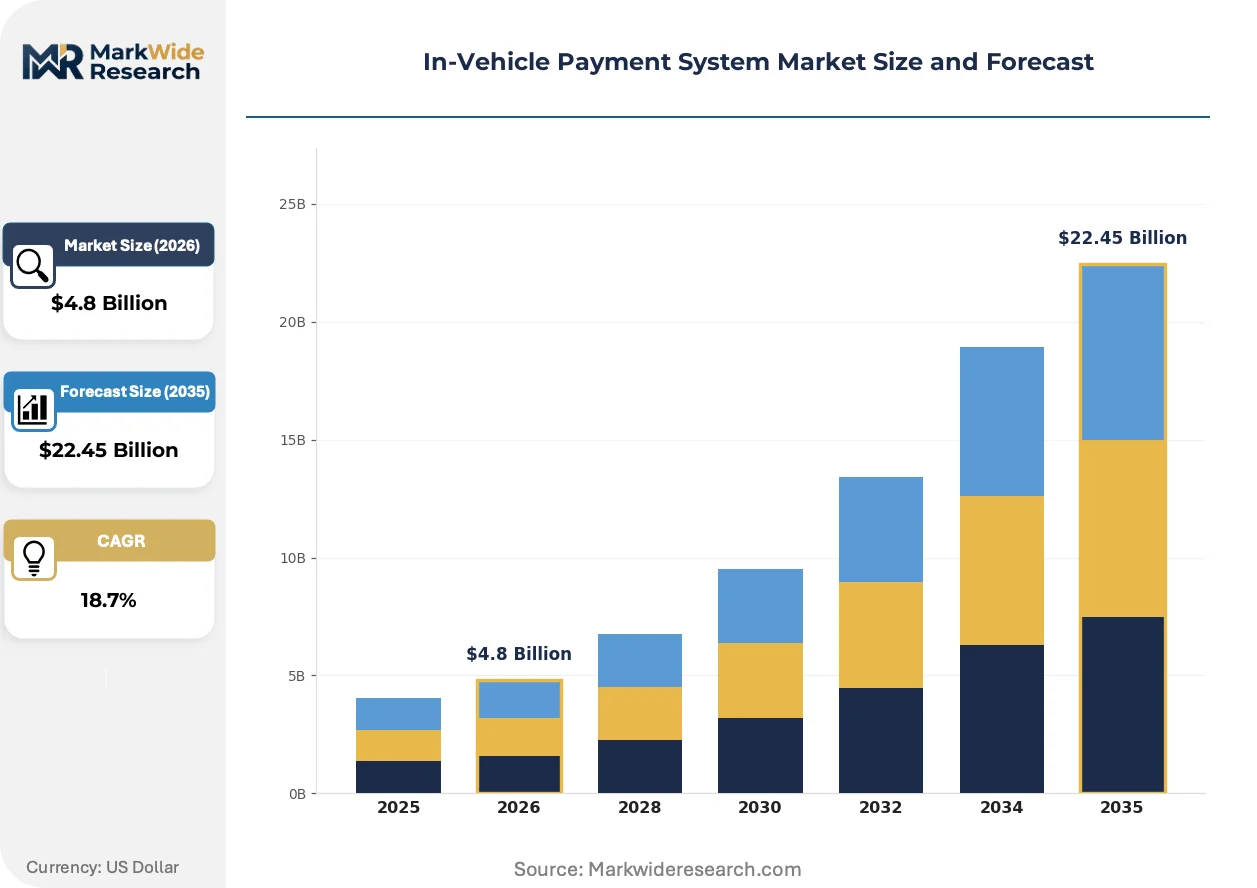
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mobile Wallet, Contactless Payment, NFC Systems, Embedded Systems End User: Automobile Manufacturers, Fleet Operators, Ride-Hailing Services, Consumers Deployment Model: On-Premises, Cloud-Based, Hybrid Solution, Mobile Integration Payment Method: Credit Card, Digital Currency, Bank Transfer, Prepaid Card |
| Companies Covered | Visa, Ford Motor Company, Tesla, Hyundai Motor Company, Mercedes-Benz Group AG, General Motors Company, Mastercard, PayPal Holdings, BMW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vehicle Payment System Market Emerging Trajectories
Payment authentication architecture is migrating from smartphone-tethered models toward embedded vehicle-native systems, driven by automaker demands for direct customer relationships and recurring software revenue streams.
Biometric driver identification is migrating from fingerprint sensors to steering wheel-integrated capacitive sensing and cabin-facing cameras. Luxury German manufacturers are adopting these systems fastest, seeking to differentiate through seamless authentication that eliminates phone dependency. The technology is migrating from aftermarket accessories into factory-installed hardware, compressing the addressable market for mobile wallet middleware providers.
The EU AI Act's risk classification framework now categorizes biometric payment authentication in vehicles as high-risk AI, mandating conformity assessment procedures before market entry. This regulatory architecture forces OEMs to maintain audit trails for algorithmic decision-making in transaction authorization. French and German type approval authorities are coordinating implementation timelines, creating a de facto European standard that Asian manufacturers must match for export competitiveness.
Fleet procurement of payment-enabled vehicles is fragmenting from centralized national leasing toward mobility-as-a-service operators running mixed-brand pools. These buyers now specify payment interoperability as a fleet management requirement, pressuring OEMs to support multi-wallet architectures rather than proprietary closed systems. This pattern is most visible in German urban ride-hailing markets, where fleet operators negotiate volume discounts based on transaction data ownership terms.
In-Vehicle Payment System Market Segmentation
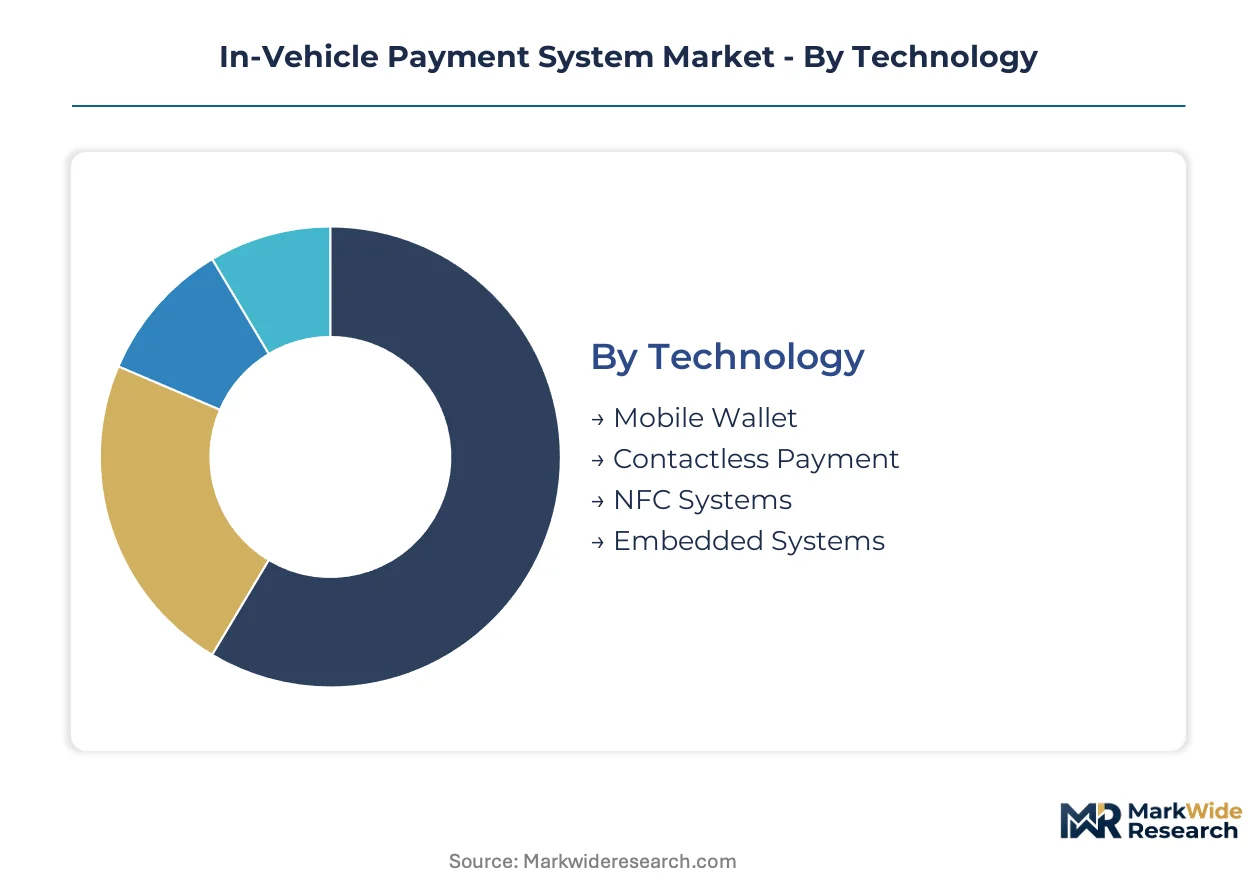
Segmentation in the in-vehicle payment system market reveals how hardware refresh cycles, regulatory mandates, and revenue model preferences create divergent growth trajectories across technology platforms and customer types. Understanding these divisions exposes where capital is concentrating and which architectures will dominate factory-installed versus retrofit deployment.
Technology:
Cycle times vary dramatically across payment technologies, with smartphone-tethered solutions refreshing annually while embedded automotive hardware locks in for 7-10 year vehicle lifespans.
- Mobile Wallet:Smartphone-dependent authentication leveraging tokenized credentials and biometric verification. Demand concentrates in aftermarket retrofit markets and entry vehicle segments where OEMs avoid hardware certification costs, though PSD2 strong authentication requirements in Europe create checkout friction above contactless limits.
- Embedded Systems:Factory-integrated secure elements within vehicle ECUs enabling phone-independent transactions. German and French automakers are adopting these fastest under EU AI Act high-risk AI mandates for biometric authentication, seeking recurring software revenue from software-defined vehicle platforms.
- NFC Systems:Near-field communication modules enabling proximity-based fueling and parking authentication. Adoption tracks contactless infrastructure density in urban centers.
- Contactless Payment:Card-not-present transaction rails adapted for in-vehicle initiation. Deployment follows Visa and Mastercard tokenization partnerships across multiple OEM dashboards.
Mobile Wallet anchors the volume base while Embedded Systems gains share at the steepest rate.
End User:
Customer type determines procurement scale and data ownership terms, with fleet operators negotiating enterprise pricing while consumers default to bundled convenience.
- Ride-Hailing Services:Fleet-scale deployment of payment-enabled vehicles to eliminate driver-mediated transactions and capture per-trip commerce revenue. Urban mobility operators in Germany specify multi-wallet interoperability as a procurement requirement, pressuring OEMs away from proprietary closed systems.
- Fleet Operators:Commercial vehicle managers with 7-10 year asset replacement cycles demanding hardware durability and centralized transaction monitoring. Legacy fleet retention delays universal payment capability deployment across commercial vehicle parc.
- Automobile Manufacturers:OEMs embedding payment architecture as a direct revenue stream through software-defined vehicle platforms. Tesla anchors closed ecosystems while others pursue tokenization partnerships.
- Consumers:Individual vehicle owners accessing in-vehicle commerce through smartphone tethering or factory-installed options. Adoption follows premium vehicle purchase patterns and charging infrastructure density.
Fleet Operators anchor the volume base while Ride-Hailing Services climbs fastest as urban mobility digitization accelerates.
Deployment Model:
Architecture choice reflects data sovereignty priorities against recurring SaaS margin capture, with European luxury manufacturers resisting cloud concentration.
- Cloud-Based:Transaction orchestration through hosted SaaS platforms enabling rapid feature updates and recurring fee structures. Margin pools concentrate here though data residency requirements complicate cross-border deployment.
- On-Premises:Localized infrastructure prioritizing data sovereignty and offline transaction capability. German luxury manufacturers favor this architecture under Federal Motor Transport Authority guidance on driver data protection.
- Hybrid Solution:Partitioned architecture with sensitive authentication local and transaction routing cloud-hosted. Emerging as compromise for multi-market OEMs navigating divergent regulatory requirements.
- Mobile Integration:Smartphone-dependent deployment minimizing vehicle hardware burden. Dominates retrofit and entry-segment factory installation.
Mobile Integration anchors the volume base while Cloud-Based expands most quickly as automakers pursue recurring revenue models.
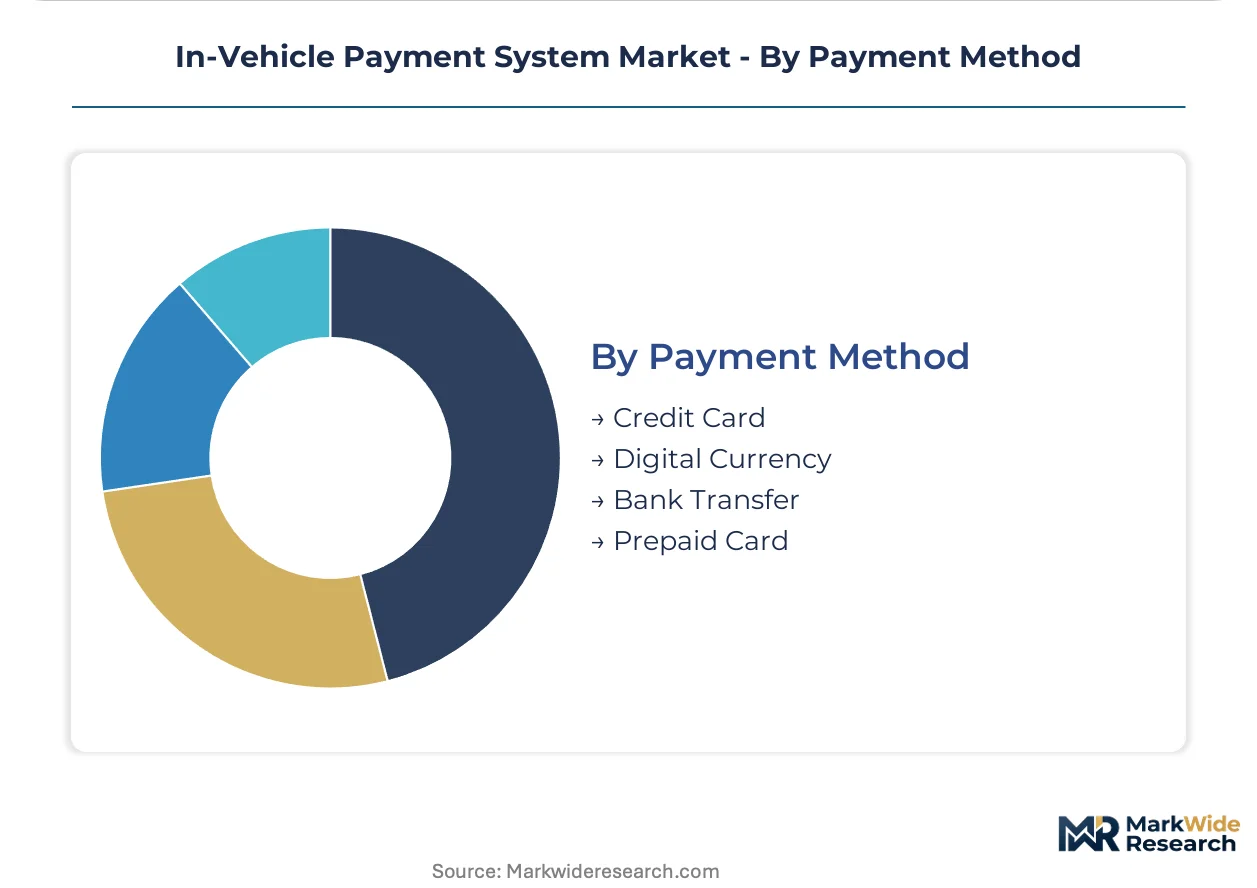
Payment Method:
Instrument selection tracks regional financial infrastructure maturity and regulatory treatment of digital assets versus traditional rails.
- Credit Card:Tokenized card credentials dominating fuel, parking, and toll transactions through Visa and Mastercard network rails. Ubiquitous acceptance drives default status.
- Digital Currency:Cryptocurrency and central bank digital currency integration for charging and commerce settlement. Pilot programs concentrate in jurisdictions with advanced CBDC frameworks.
- Bank Transfer:Account-to-account settlement leveraging open banking APIs under PSD2 frameworks. Strong customer authentication requirements create friction for seamless in-vehicle flows.
- Prepaid Card:Stored-value instruments for fleet fueling and toll management enabling spend control and simplified reconciliation. Commercial fleet procurement favors this for driver accountability.
Credit Card anchors the volume base while Bank Transfer advances fastest as open banking infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement managers and ride-hailing operators concentrate demand in jurisdictions with advanced open banking frameworks and stringent data protection mandates. Germany's Federal Motor Transport Authority shapes certification requirements that ripple across adjacent markets. Urban mobility digitization accelerates fastest where charging infrastructure density intersects with contactless payment terminal penetration.
Germany
Automakers and Tier-1 suppliers co-develop embedded NFC infrastructure in Stuttgart and Munich industrial corridors. The KBA mandates payment security validation as a condition of vehicle-type approval under evolving homologation frameworks. Bavaria's software-defined vehicle engineering clusters anchor European secure element qualification programs.
United States
The FTC scrutinizes biometric payment authentication under Section 5 unfair practices authority, creating compliance uncertainty for cabin-facing camera systems. Detroit-based OEMs leverage proprietary operating systems to anchor closed-loop commerce ecosystems. California's ride-hailing fleet operators specify multi-wallet interoperability in procurement contracts.
France
CNIL coordinates with German regulators on cross-border driver data flow requirements linked to payment profiles. Paris urban mobility operators demand centralized transaction monitoring for mixed-brand fleet pools. Île-de-France automotive clusters prototype steering wheel-integrated capacitive sensing for seamless authentication.
China
Domestic OEMs integrate payment-grade secure elements into vehicle ECUs at Shenzhen and Shanghai electronics manufacturing hubs. SAMR oversees tokenization standards for in-vehicle commerce settlement. Yangtze River Delta clusters concentrate NFC-ultrawideband convergence prototyping for hands-free fueling authentication.
India
The RBI's unified payments interface creates a regulatory template for real-time settlement that automakers adapt for emerging market expansion. Karnataka's automotive software engineering centers develop cloud-based transaction orchestration platforms. Maharashtra fleet operators pilot subscription-based vehicle commerce without hardware retrofit requirements.
In-Vehicle Payment System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Payment network incumbents leverage tokenization partnerships to extend rails into OEM dashboards, while automakers pursue vertical integration through proprietary operating systems. Strategic archetypes include closed-ecosystem orchestrators, open-architecture enablers, and fleet-scale solution providers. Dominant competitive moves center on secure element supply agreements and multi-wallet interoperability certifications.
Within the closed-ecosystem tier, Tesla exemplifies automaker-directed commerce through proprietary platform control. Mastercard and Visa anchor the open-architecture enabler archetype, representing network-driven standardization across multiple OEM partnerships. These three entities occupy positions that define the competitive fault lines between proprietary and interoperable payment architectures.
| Leading Market Players |
|---|
| Visa |
| Ford Motor Company |
| Tesla |
| Hyundai Motor Company |
| Mercedes-Benz Group AG |
| General Motors Company |
| Mastercard |
| PayPal Holdings |
| BMW Group |
| Others |
Supply Flow & Price Mechanics
Undercapacity at European automotive-grade HSM foundries is tightening supplier pricing power and compressing OEM negotiation leverage across embedded secure element procurement. German and French automakers now face extended qualification timelines that inflate unit costs for payment-grade hardware while Tier-1 suppliers pass through semiconductor scarcity premiums.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate embedded secure element procurement, insulating Tier-1 suppliers from raw material volatility while locking OEMs into volume commitments. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels reflects ISO 26262 functional safety investment differentials. Cost compression in mobile wallet middleware is intensifying because smartphone-tethered authentication eliminates hardware certification burdens. Fleet operators exhibit highest price sensitivity due to 7-10 year asset replacement cycles, while luxury OEMs prioritize data sovereignty over unit economics.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment limit HSM chip production expansion in Germany, the Netherlands, and Taiwan. Automotive-grade secure element supply concentrates in European foundries with PCI-DSS certification, drawing from silicon wafer feedstock anchored in Japanese and German chemical processing. Single-source vulnerability persists for payment-grade hardware qualified under EU AI Act high-risk AI mandates. Distribution runs through Tier-1 supplier direct contracts to OEM platform engineering teams, bypassing traditional automotive aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The in-vehicle payment system market sits in early-cycle expansion as software-defined vehicle platforms convert one-time hardware sales into recurring SaaS revenue streams. Ride-hailing fleet digitization across German urban mobility corridors provides the clearest adoption tailwind for embedded payment architecture deployment.
For Market Incumbents: Harden secure element supply agreements through captive capacity reservations at certified European foundries before EU AI Act homologation timelines compress further. Defend against Mastercard and Visa tokenization partnerships by accelerating proprietary OS development for closed-loop commerce ecosystems. Prioritize PCI-DSS certification maintenance as vehicle-type approval frameworks expand payment security validation requirements. For New Entrants and Emerging Players: Mid-market fleet operators in India and Southeast Asia represent the most penetrable entry point where unified payments interface infrastructure reduces certification complexity. Aftermarket NFC retrofit kits for legacy commercial vehicles in North America offer hardware-light deployment without OEM integration. Pursue white-label transaction orchestration partnerships with regional charging network operators to establish initial volume traction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-based SaaS transaction orchestration providers serving multi-OEM wallet architectures. Long-term viability over the next decade hinges on regulatory certification moats rather than technology differentiation alone. Monitor EU AI Act conformity assessment timeline announcements as the critical inflection signal for embedded system deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Supply Agreement | Captive HSM chip allocation from Infineon or NXP insulates against EU AI Act qualification bottlenecks. |
| Tokenization Partnership | Visa or Mastercard network integration extends payment rails into multiple OEM dashboard ecosystems simultaneously. |
| Software-Defined Vehicle Investment | Recurring SaaS revenue from in-car commerce offsets declining hardware margins for German automakers. |
| Biometric Certification Pathway | EU AI Act high-risk AI conformity assessment enables steering wheel-integrated authentication deployment. |
| Fleet-Scale Procurement Contract | Urban mobility operator volume commitments in Stuttgart and Munich anchor embedded system factory installation. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, fleet operator technology directors, and payment network tokenization specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, vehicle production databases from IHS Markit, EU regulatory filings under the AI Act and PSD2 frameworks, and customs data tracking secure element trade flows. Bottom-up segment sizing triangulated against top-down market construction across the analysis window.
Demand-supply balance modeling anchored the forecast framework, with embedded system penetration rates, mobile wallet attach rates, and cloud-based SaaS conversion tracked across technology, end-user, deployment model, and payment method dimensions. CAGRs derived from segment-level growth trajectory synthesis incorporating ISO 15118 protocol adoption curves and EU AI Act implementation timelines. Vehicle parc refresh rates and charging infrastructure density served as industry-specific demand inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect assumptions regarding homologation timeline stability and secure element foundry capacity expansion. Material shifts in export control regimes governing HSM manufacturing equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
North America POS Terminal Market
Payments
Fuel and Convenience Store POS Market
Payments
Fuel Cards Market
Payments
Malta POS Terminal Market
Payments
Egypt Mobile Payments Market
Payments
EMV Card Market
Payments
Voice-Based Payments Market
Payments
B2B Payments Platform Market
Payments
Cash Management Software Market
Payments
Payment Security Software Market
Payments
Transit Cards Market
Payments
North America Real Time Payment Market
Payments
Germany Mobile Payments Market
Payments
India Payment Gateway Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Digital Payment in Healthcare Market