
 Contactless Payment Ring Market | 2026-2036
Contactless Payment Ring Market Size, Share, and Industry Trends Forecast 2026-2036
Contactless Payment Ring Market Analysis
China is tilting toward scaled production of NFC-enabled wearables, drawing component suppliers and assembly houses into Shenzhen and Dongguan corridors. Mastercard leverages its tokenization infrastructure to anchor payment security across ring form factors. Samsung Electronics competes through backward integration into semiconductor and display supply chains for wearable devices. Oura Health differentiates by merging sleep analytics with contactless payment credentials in a single titanium enclosure.
A contactless payment ring is a finger-worn wearable device embedding near-field communication or radio-frequency identification chips, typically housed in ceramic, titanium, or resin composites, enabling tap-to-transact functionality at point-of-sale terminals without physical card or smartphone presentation. The device operates through passive or active RF coupling to payment networks, with primary commercial purpose of reducing transaction friction in transit, retail, and hospitality environments. Smart ring and NFC ring categories dominate unit shipments, while hybrid ring configurations that layer biometric authentication capture expanding margin pools. E-commerce channels sustain the fastest volume growth, though retail stores remain critical for sizing and initial consumer education.
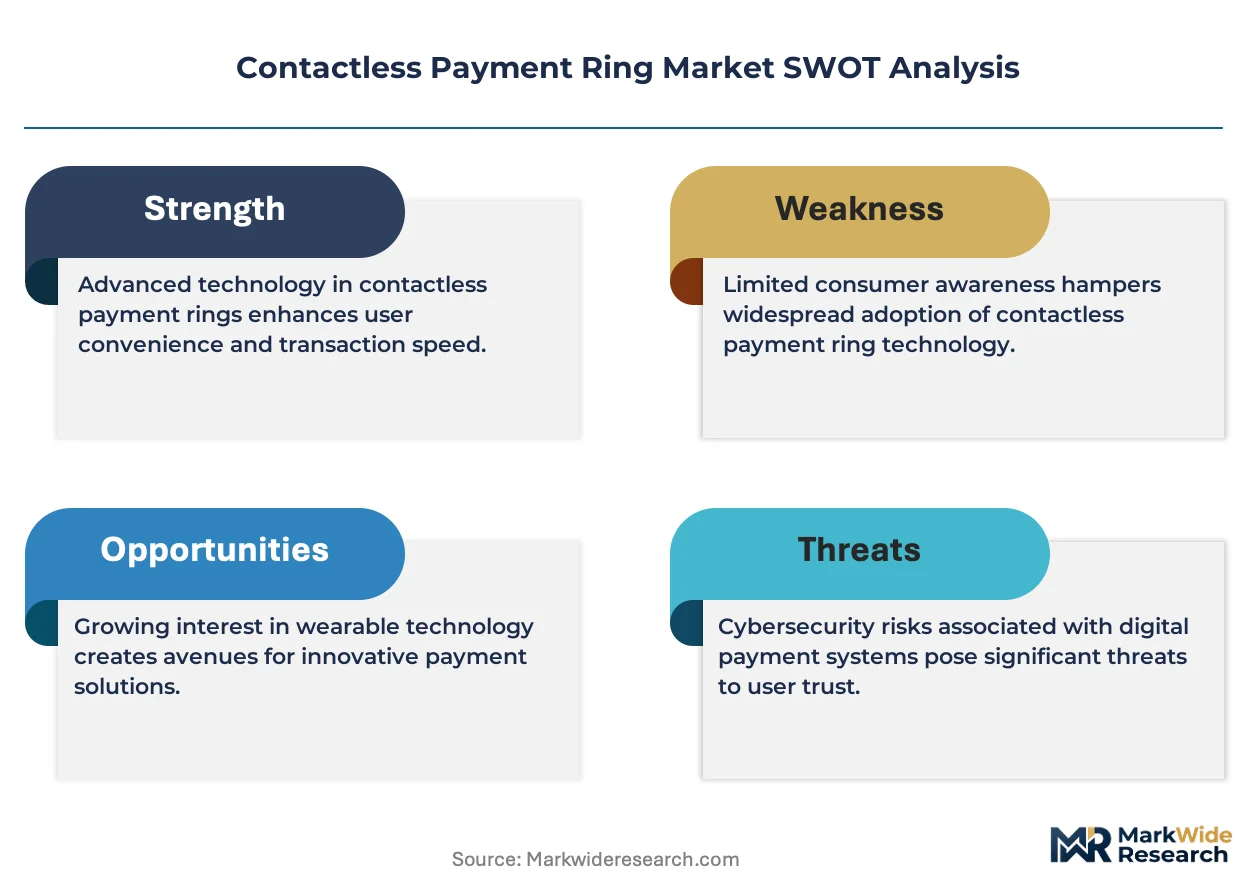
FCC certification governs radio emission thresholds in the United States, while Europe's EMD2 and GDPR frameworks shape payment authentication and biometric data handling requirements for ring devices. China's SAMR enforces national encryption standards for financial wearables, creating compliance thresholds that filter non-domestic entrants. Stakeholders must monitor how central bank digital currency integrations and evolving tokenization protocols reshape hardware security requirements.
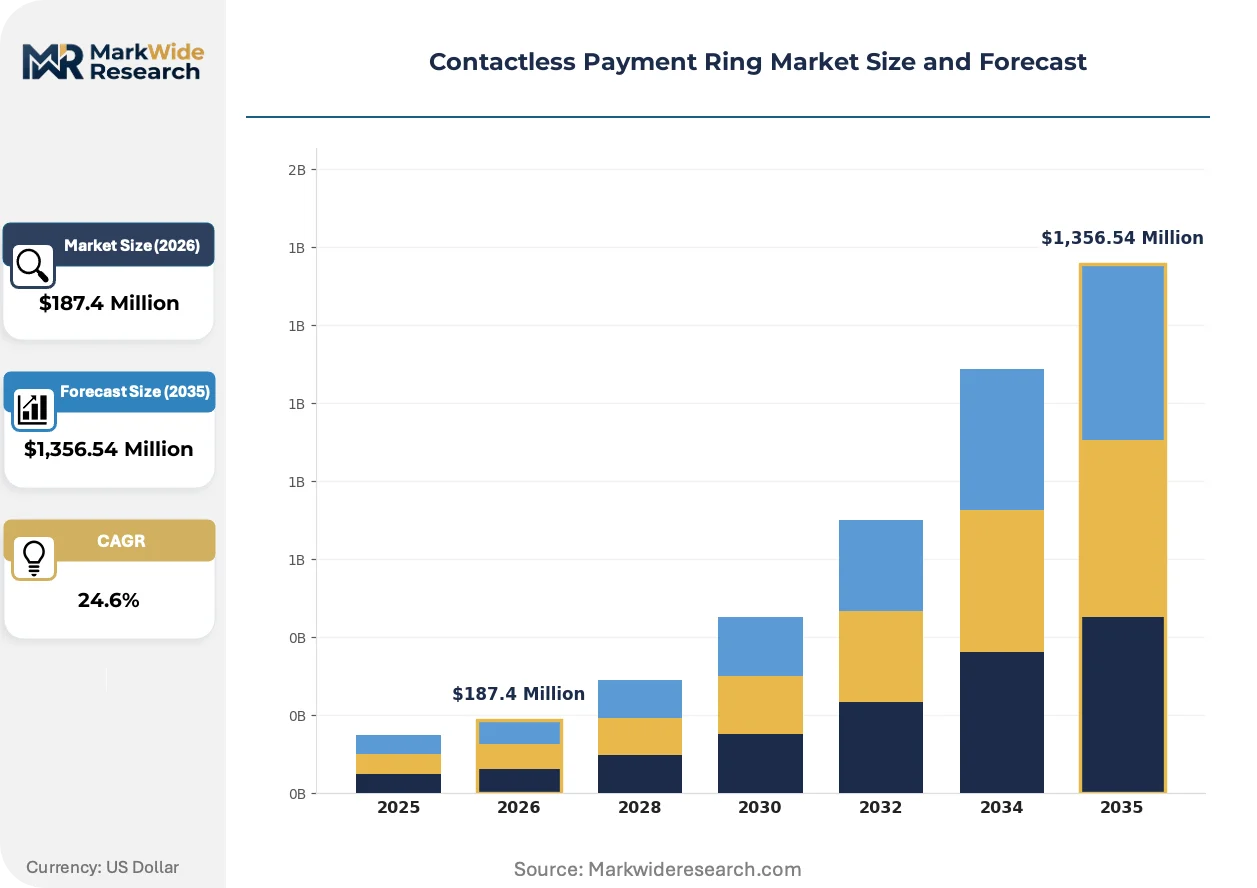
Market Dynamics
PSD2 strong customer authentication mandates and China's SAMR encryption standards are bifurcating certification pathways, forcing hardware architects to design dual-compliant RF modules and biometric token vaults from inception rather than retrofitting for regional variance.
Growth Catalysts
- EMD2 authentication frameworks:Europe's payment security directives mandate possession-and-inherence verification, creating pull for biometric-enabled ring form factors in transit and hospitality terminals.
- Shenzhen-Dongguan corridor concentration:Component suppliers and NFC antenna fabricators cluster in China's Pearl River Delta, compressing procurement lead times for ceramic and titanium enclosure manufacturers.
- Open banking APIs:Asia-Pacific regulatory frameworks enable direct credential provisioning from financial institutions to wearable devices, bypassing traditional card network tokenization bottlenecks.
Market Restraints
- Titanium feedstock volatility:Aerospace and medical device sectors compete for grade 5 titanium sponge, exposing ring manufacturers to spot price swings in Russian and Chinese metallurgical supply.
- FCC emission threshold compliance:Passive RF coupling designs must demonstrate sub-15-milliwatt power absorption at 13.56 MHz, disqualifying active-powered prototypes from US market entry.
- Smartphone wallet substitution:Apple Pay and Google Pay embedded-device penetration reduces incremental convenience value of dedicated wearable payment hardware for occasional-use consumers.
Strategic Opportunities
- Central bank digital currency integration:China's e-CNY hardware wallet specifications create first-mover positioning for domestic OEMs capable of embedding dual offline transaction capabilities in ring architectures.
- Health-monitoring convergence:Photoplethysmography sensors merged with payment NFC chips enable vital-sign tracking alongside transit authentication, opening employer wellness program procurement channels.
- Direct-to-consumer sizing platforms:At-home ring measurement kits using smartphone camera depth sensing reduce retail footprint requirements and return rates for e-commerce-only brands.
Industry Challenges
- Biometric template storage compliance:GDPR Article 9 special category data handling requires segregated secure elements with tamper-evident physical destruction circuits, extending hardware validation timelines.
- Antenna miniaturization yield rates:Ferrite core winding precision for sub-20mm diameter form factors generates 12-18% scrap rates at volume, pressuring gross margins until automated micro-coil assembly matures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactless Payment Ring Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,356.54 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Ring, Wearable Ring, NFC Ring, Hybrid Ring End User: Retail Consumers, Business Professionals, Fitness Enthusiasts, Tech Savvy Users Technology: RFID, NFC, Bluetooth, Biometric Authentication Distribution Channel: E-commerce, Retail Stores, Direct Sales, Third-Party Resellers |
| Companies Covered | Mastercard, Ultrahuman, Orukka, Circular, Amazfit, Samsung Electronics, RingConn, Renpho, Oura Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactless Payment Ring Market Emerging Trajectories
Tokenization infrastructure and biometric fusion are compressing the boundary between payment credential and identity verification, shifting competitive advantage toward semiconductor-integrated OEMs with in-house cryptographic certification capabilities.
Ultrasonic fingerprint sensing embedded beneath titanium ring surfaces is digitizing how users authenticate high-value transactions without exposing biometric data to merchant terminals. Transit authorities in Tokyo and London are piloting these modules for fare gate throughput acceleration. The technology is digitizing liability allocation by shifting fraud responsibility from issuers to hardware manufacturers with certified secure element integration.
GDPR's Article 25 data protection by design mandate is forcing wearable architects to implement biometric template anonymization before cloud synchronization. Hardware vendors must now provision on-device federated learning for behavioral pattern recognition rather than centralized AI processing. European OEMs are responding by licensing ARM TrustZone enclaves for ring-scale secure computation.
Subscription-based credential lifecycle management is displacing one-time hardware sales in enterprise deployment models. Employers provisioning rings to logistics and healthcare workers now pay per-authentication fees to platform operators rather than owning devices outright. This shift concentrates most visibly in Germany's industrial Mittelstand, where works councils negotiate wearable monitoring boundaries alongside payment utility.
Contactless Payment Ring Market Segmentation
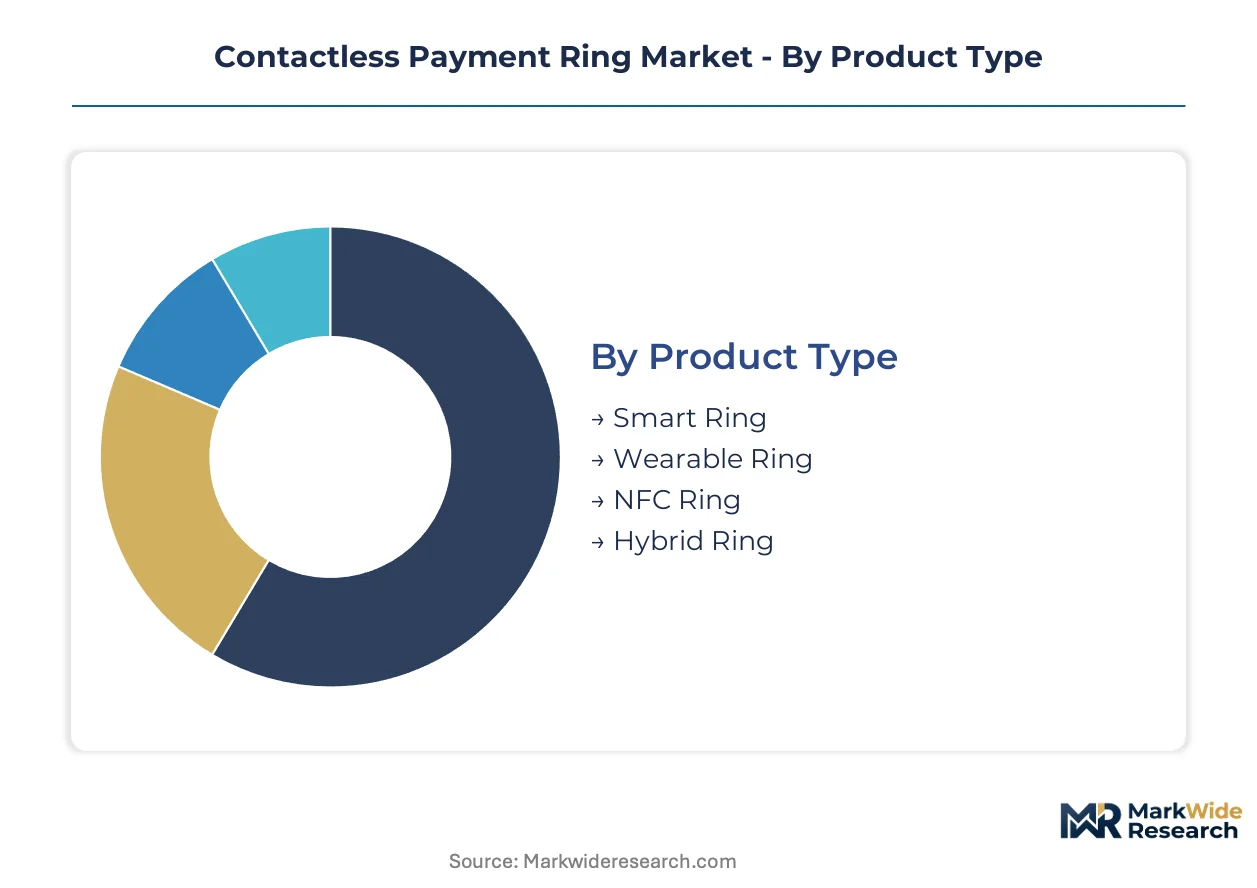
Segmentation in the contactless payment ring market reveals divergent hardware refresh cycles and credential provisioning pathways. Product type and distribution channel decisions determine whether vendors capture recurring subscription revenue or one-time hardware margins.
Product Type:
Smart rings turn over fastest at 18-24 month replacement cycles, while hybrid rings with biometric modules extend toward 36-month lifespans due to higher entry prices and enterprise provisioning contracts.
- Smart Ring:Multi-function wearables embedding NFC chips alongside basic health sensors in ceramic or resin housings. Transit authorities in London and Tokyo deploy these for fare gate throughput, though battery degradation limits active RF transmission range over time.
- Wearable Ring:Passive NFC-enabled devices without onboard power, relying on terminal-induced RF coupling for transaction authentication. Germany's industrial Mittelstand employers favor these for logistics worker provisioning due to zero charging infrastructure requirements.
- NFC Ring:Dedicated near-field communication devices optimized for 13.56 MHz ISO 14443 protocol compliance.
- Hybrid Ring:Titanium-enclosed systems combining payment credentials with photoplethysmography sensors or ultrasonic fingerprint modules.
Smart ring anchors the volume base while hybrid ring gains share at the steepest rate.
End User:
Cost tier stratification separates occasional retail purchasers from enterprise-provisioned professionals, with fitness enthusiasts occupying a mid-tier hardware-plus-subscription hybrid.
- Retail Consumers:Individual purchasers prioritizing transaction convenience in transit and hospitality environments. China's e-CNY hardware wallet specifications pull domestic OEMs toward dual offline capability in this segment.
- Business Professionals:Corporate-provisioned users receiving rings through employer wellness or access control programs. GDPR Article 9 biometric data handling requirements extend procurement validation timelines for European deployments.
- Fitness Enthusiasts:Users demanding merged payment and health monitoring functionality.
- Tech Savvy Users:Early adopters experimenting with open banking API credential provisioning outside traditional card networks.
Retail consumers anchor the volume base while business professionals expand most quickly through employer-sponsored deployment models.
Technology:
RF module certification complexity varies sharply, with passive RFID designs clearing FCC thresholds faster than biometric authentication systems requiring GDPR-compliant secure element integration.
- RFID:Legacy radio-frequency identification operating at 125 kHz or 13.56 MHz with read-only or read-write memory. Transit systems in legacy infrastructure markets retain these for backward compatibility with existing fare gate hardware.
- NFC:Near-field communication enabling two-way data exchange between ring and terminal at 13.56 MHz. Mastercard's tokenization infrastructure anchors security architectures for this dominant commercial protocol.
- Bluetooth:Active wireless connectivity extending range beyond NFC proximity constraints.
- Biometric Authentication:Ultrasonic fingerprint or capacitive sensors enabling possession-and-inherence verification under PSD2 frameworks.
NFC anchors the volume base while biometric authentication climbs the fastest on regulatory pull from European strong customer authentication mandates.
Distribution Channel:
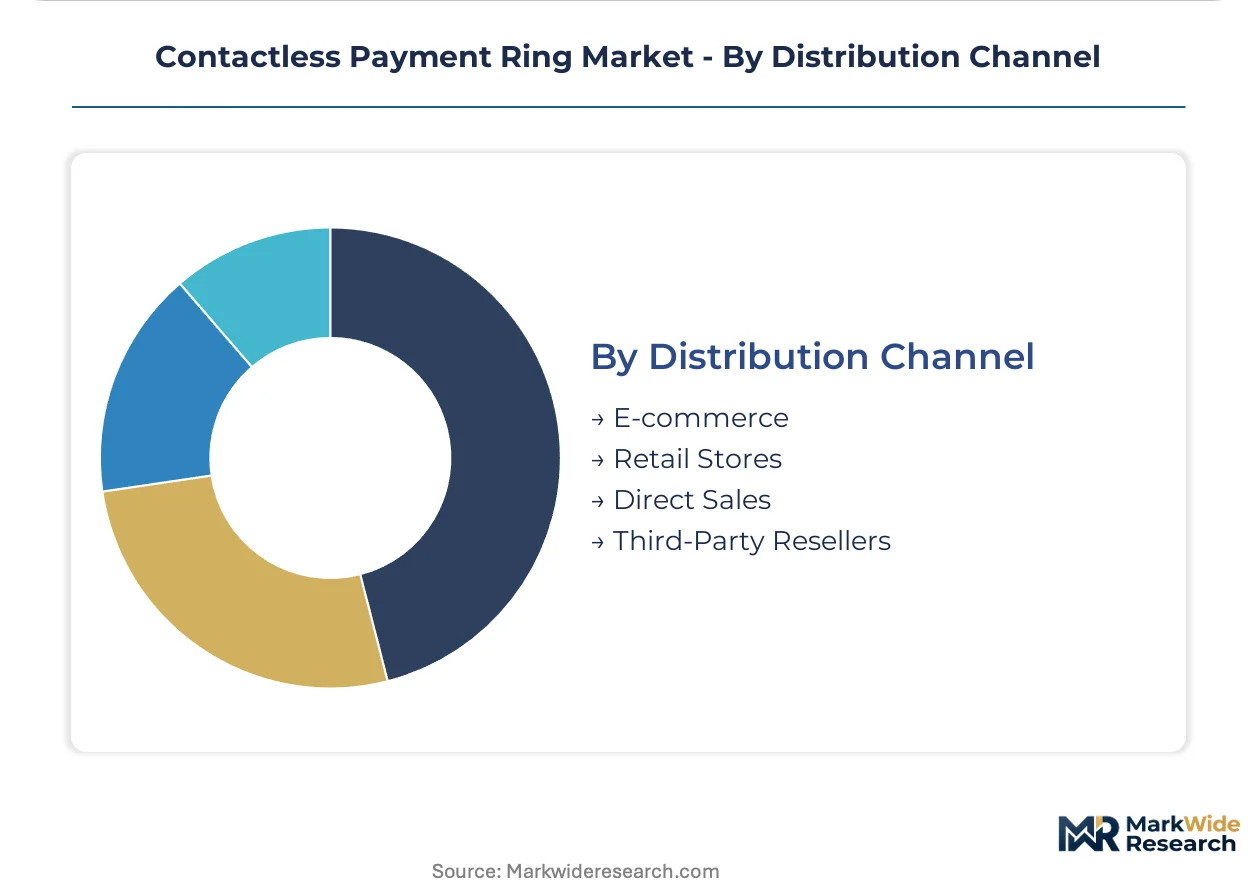
Volume concentration favors direct digital acquisition, though physical retail retains critical importance for sizing accuracy and consumer education in biometric-enabled categories.
- E-commerce:Online direct-to-consumer sales supported by at-home ring measurement kits using smartphone camera depth sensing. Return rate compression and reduced retail footprint requirements drive vendor margin expansion in this channel.
- Retail Stores:Physical outlets enabling in-person sizing, initial consumer education, and immediate credential provisioning. Critical for hybrid ring categories where titanium enclosure fit precision affects biometric sensor alignment.
- Direct Sales:Enterprise and institutional procurement through vendor field teams.
- Third-Party Resellers:Electronics retailers and mobile carrier stores extending geographic reach without captive inventory investment.
E-commerce anchors the volume base while direct sales gains share fastest through employer wellness program procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's encryption standards for financial wearables anchor China's dominance in contactless payment ring certification pathways. The country's national encryption protocols create compliance thresholds that filter non-domestic entrants while concentrating component supply in the Pearl River Delta.
China
Domestic OEMs scale production of NFC-enabled wearables for retail consumers, integrating e-CNY hardware wallet specifications with health monitoring ecosystems. SAMR enforces national encryption standards that favor local fabricators. Shenzhen and Dongguan corridors cluster component suppliers and NFC antenna fabricators, compressing procurement lead times for ceramic and titanium enclosure manufacturers.
United States
FCC emission threshold compliance governs radio emission standards, requiring passive RF coupling designs to demonstrate sub-15-milliwatt power absorption at 13.56 MHz. Transit authorities in major metropolitan areas pilot biometric-enabled rings for fare gate throughput. Mastercard leverages tokenization infrastructure to anchor payment security architectures across ring form factors.
Germany
PSD2 strong customer authentication mandates create regulatory pull for biometric-enabled ring form factors in transit and hospitality terminals. GDPR Article 9 special category data handling requirements extend procurement validation timelines for enterprise deployments. The industrial Mittelstand concentrates employer-provisioned ring deployments through works council-negotiated wellness programs.
Japan
METI frameworks shape transit authority pilot programs for ultrasonic fingerprint sensing modules in fare gate systems. Tokyo's transportation networks test biometric fusion technologies for throughput acceleration. Kanto region technology clusters support semiconductor-integrated OEMs developing in-house cryptographic certification capabilities.
United Kingdom
EMD2 authentication frameworks mandate possession-and-inherence verification for payment security. London transit systems deploy smart rings for fare gate throughput alongside existing contactless infrastructure. Fintech clusters in the Southeast concentrate open banking API development enabling direct credential provisioning to wearable devices.
Contactless Payment Ring Market Vendor Landscape
Semiconductor-integrated OEMs and specialized wearable fabricators split the market along certification capability lines. The vendor base concentrates around players with in-house cryptographic hardware validation and those dependent on licensed secure element architectures. Three archetypes dominate: payment network anchors with tokenization infrastructure, consumer electronics conglomerates with backward integration into component supply chains, and health-focused specialists merging biometric sensors with payment credentials. Competitive moves center on strategic partnerships with transit authorities and portfolio diversification into employer wellness program channels.
Among payment network anchors, Mastercard exemplifies the tokenization-centric archetype through infrastructure licensing. Samsung Electronics occupies a position within the consumer electronics conglomerate tier, leveraging captive semiconductor and display supply chain control. Oura Health represents the health-monitoring convergence specialist, merging sleep analytics with contactless payment credentials. These three anchors illustrate how competitive positioning depends on whether players control cryptographic certification in-house or rely on licensed secure elements.
| Leading Market Players |
|---|
| Mastercard |
| Ultrahuman |
| Orukka |
| Circular |
| Amazfit |
| Samsung Electronics |
| RingConn |
| Renpho |
| Oura Health |
| Others |
Supply Flow & Price Mechanics
Shenzhen-Dongguan corridor freight lanes compress logistics costs for titanium enclosure manufacturers while amplifying price differentiation between ceramic-resin economy tiers and biometric-enabled premium configurations. This logistics dynamic concentrates procurement power among domestic OEMs with captive component access, forcing international brands to absorb margin compression or cede volume in transit and hospitality deployment channels.
Pricing Analysis
Geographic price spreads separate Pearl River Delta-sourced units from European-assembled biometric variants by roughly two-to-one multiples. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with GDPR-compliant secure element integration commanding substantial premiums over passive NFC alternatives. Cost compression in the economy tier intensifies because smartphone wallet substitution erodes perceived incremental value. Retail consumers exhibit highest price sensitivity, while employer-provisioned enterprise deployments absorb premium positioning through per-authentication subscription models.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn and Luxshare-ICT facilities in Dongguan and Kunshan, supplemented by Pegatron capacity in Taiwan for secure element integration. Component sourcing draws from South Korean ferrite core suppliers, Japanese precision coil fabricators, and Chinese titanium sponge processors. Single-source vulnerability in grade 5 titanium feedstock from Russian and Chinese metallurgical supply exposes margin volatility. Distribution runs through direct-to-consumer e-commerce platforms and enterprise field sales teams, with retail stores retaining critical sizing and education functions for biometric-enabled categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contactless payment ring market expansion represents high-growth disruption anchored by PSD2 biometric authentication mandates and China's e-CNY hardware wallet specifications. These regulatory inflections compress certification timelines for prepared players while erecting barriers for retrofit-dependent competitors.
For Market Incumbents: Entrench tokenization infrastructure control by deepening partnerships with Mastercard and Visa credential vaults, while accelerating backward integration into semiconductor supply chains to offset secure element licensing costs. Samsung Electronics' captive fabrication model demonstrates defensive positioning against margin erosion from licensed cryptographic architectures.
For New Entrants and Emerging Players: Build out direct-to-consumer sizing platforms using smartphone depth sensing to bypass retail footprint requirements, targeting employer wellness program procurement in Germany's industrial Mittelstand where works council negotiations create incumbent friction. White-space concentration sits with health-monitoring convergence for fitness enthusiasts seeking merged payment and vital-sign tracking functionality.
For Investors and Strategic Acquirers: Semiconductor-integrated OEMs with in-house cryptographic certification capabilities represent the priority acquisition archetype, as tokenization infrastructure and biometric fusion compress competitive advantage toward hardware-validated players. Long-term viability hinges on central bank digital currency integration positioning; the signal to watch is pilot contract announcements with transit authorities in Tokyo, London, and Shenzhen for ultrasonic fingerprint module deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Certification Investment | In-house cryptographic validation accelerates GDPR and SAMR compliance timelines versus licensed alternatives. |
| Transit Authority Partnership | Tokyo and London pilot programs establish biometric-enabled ring standards for fare gate throughput acceleration. |
| Health Sensor Integration | Photoplethysmography merger with NFC chips opens employer wellness program procurement channels. |
| Direct-to-Consumer Sizing Platform | Smartphone camera depth sensing reduces return rates and retail footprint requirements for e-commerce brands. |
| Central Bank Digital Currency Alignment | e-CNY hardware wallet specification compliance creates first-mover positioning in China's retail consumer segment. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with payment network executives, wearable hardware architects, transit authority procurement leads, and employer wellness program administrators; and secondary validation against SAMR encryption standards documentation, FCC emission threshold filings, PSD2 regulatory guidance, and tokenization protocol specifications. Bottom-up triangulation across component supplier interviews and top-down reconciliation with payment network transaction volume disclosures anchored segmentation-level estimates.
Forecast inputs considered product type replacement cycles, credential provisioning pathway economics, and regional regulatory compliance timelines across the analysis window. Segmentation modeling incorporated technology protocol, end-user archetype, and distribution channel dimensions with industry-specific weighting for certification grade tiering. CAGRs derived from volume shipment trajectories and average selling price evolution patterns, stress-tested against smartphone wallet penetration rates and central bank digital currency pilot expansion schedules.
Stress conditions across titanium feedstock price volatility, biometric template storage compliance timeline extensions, and transit authority procurement budget cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and component supplier yield rate maturation. Quarterly review of transit authority pilot contract awards and SAMR certification issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Wearable Payments Market
Payments
Blockchain Payments Software Market
Payments
Cash Management System Market
Payments
Subscription Billing Management Market
Payments
North America Mobile Payments Market
Payments
Mobile Card Reader Market
Payments
Digital Payment Market
Payments
Digital Money Transfer Market
Payments
Vietnam E-Wallet Market
Payments
Argentina Mobile Wallet Market
Payments
France POS Terminal Market
Payments
GCC Payment Gateway Market
Payments
Belgium POS Terminals Market
Payments
Global Accounts Payable Automation Market
Payments
UK Virtual Cards Market
Payments
Canada Payments Market