
 US Data Analytics in Banking Market | 2026-2036
US Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
US Data Analytics in Banking Market Insights
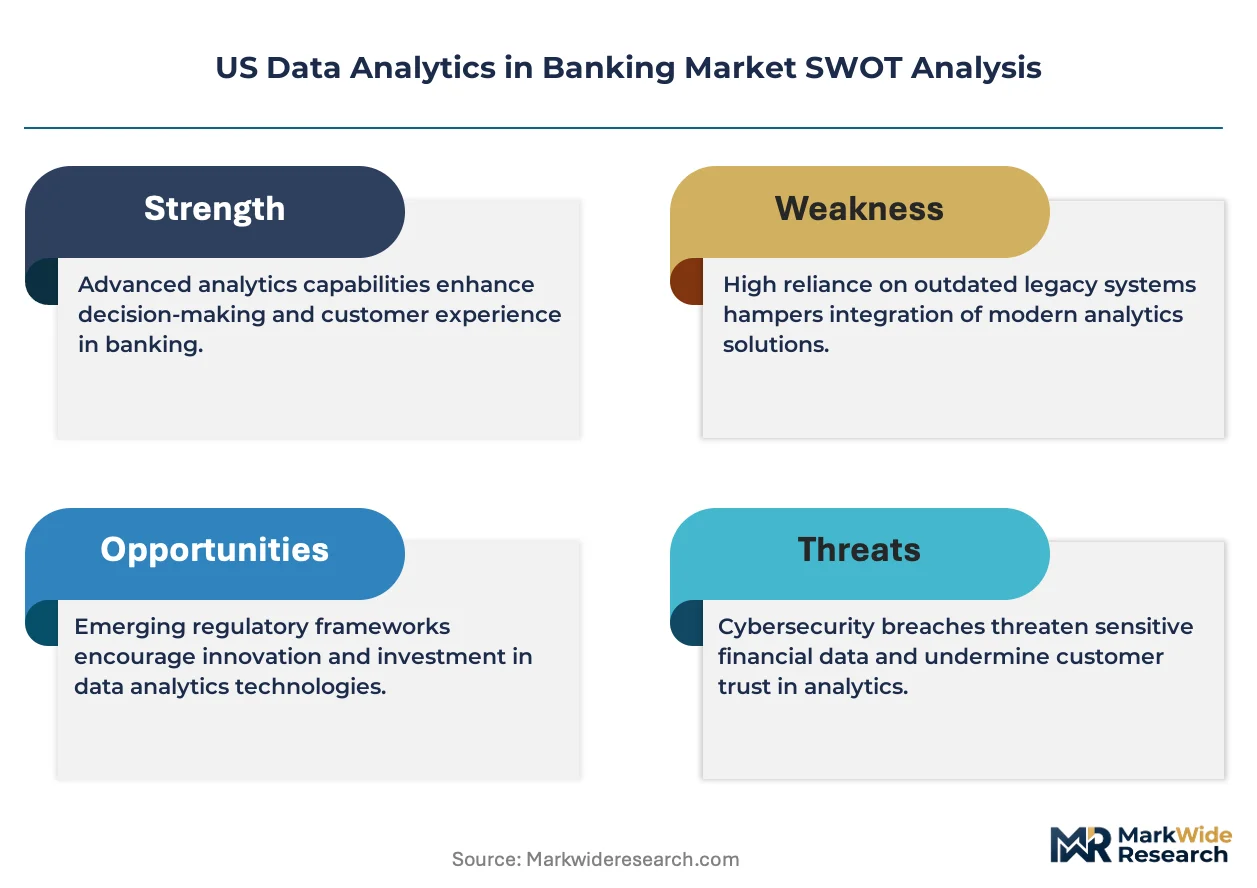
Subscription-based cloud licensing is rewriting competitive access rules for mid-tier banks that previously lacked capital for enterprise analytics infrastructure. IBM Corporation leverages its Watson platform to anchor institutional relationships with federal credit unions seeking on-premises AI governance. Microsoft Corporation extends Azure Synapse capabilities to compete directly in hybrid deployment scenarios where data residency requirements dominate procurement decisions.
US data analytics in banking encompasses statistical modeling, machine learning algorithms, and real-time data processing architectures applied to financial transaction streams, risk portfolios, and customer behavioral datasets with latency thresholds often below 50 milliseconds for fraud detection workflows. Predictive analytics and fraud detection service types now capture disproportionate R&D investment as banks automate anti-money laundering surveillance. Cloud-based and multi-cloud deployment modes are displacing legacy on-premises installations fastest among investment banks managing distributed trading desk operations across Chicago, Charlotte, and San Francisco.
The Office of the Comptroller of the Currency, Federal Reserve Board, and Consumer Financial Protection Bureau collectively shape vendor product roadmaps through mandated stress-testing data standards and fair-lending algorithmic accountability rules. The SEC's climate disclosure requirements are forcing banks to integrate alternative data sources into ESG risk scoring models. Stakeholders must monitor how state-level privacy legislation in California and New York fragments compliance architectures before selecting scalable platform investments.
Market Dynamics
Real-time fraud detection latency requirements below 50 milliseconds are forcing banks to rebuild core transaction processing architectures around edge-computing deployments and in-memory analytics fabrics.
Growth Catalysts
- Gramm-Leach-Bliley Act compliance mandates:Federal requirements for financial privacy safeguards drive automated data governance platform procurement across retail banking networks.
- Federal Reserve stress-testing protocols:Annual CCAR submissions require predictive risk models that ingest alternative credit datasets and macroeconomic scenario simulations.
- Cloud infrastructure cost curves:Subscription-based SaaS licensing removes capital barriers for mid-tier credit unions seeking enterprise-grade machine learning capabilities.
Market Restraints
- Specialized talent scarcity:Quantitative risk modelers with regulatory reporting expertise command compensation premiums that strain regional bank operating budgets.
- Data residency fragmentation:State-level privacy statutes in California and New York create incompatible compliance architectures that complicate multi-state platform deployments.
- Legacy core system entrenchment:Decades-old mainframe transaction processors resist API-based integration with modern analytics layers without expensive middleware layers.
Strategic Opportunities
- Community bank white space:Institutions below $10 billion in assets lack dedicated data science functions, creating managed analytics service opportunities.
- ESG risk scoring convergence:SEC climate disclosure rules force integration of satellite imagery and supply chain emissions data into credit underwriting models.
- Real-time payment rails:FedNow instant settlement infrastructure generates high-velocity transaction streams requiring continuous behavioral analytics.
Industry Challenges
- Model risk management talent gaps:SR 11-7 guidance demands independent validation teams that banks struggle to staff at competitive rates.
- Algorithmic fairness audit complexity:Fair lending enforcement requires explainable AI frameworks that increase computational overhead and extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Data Analytics in Banking Market |
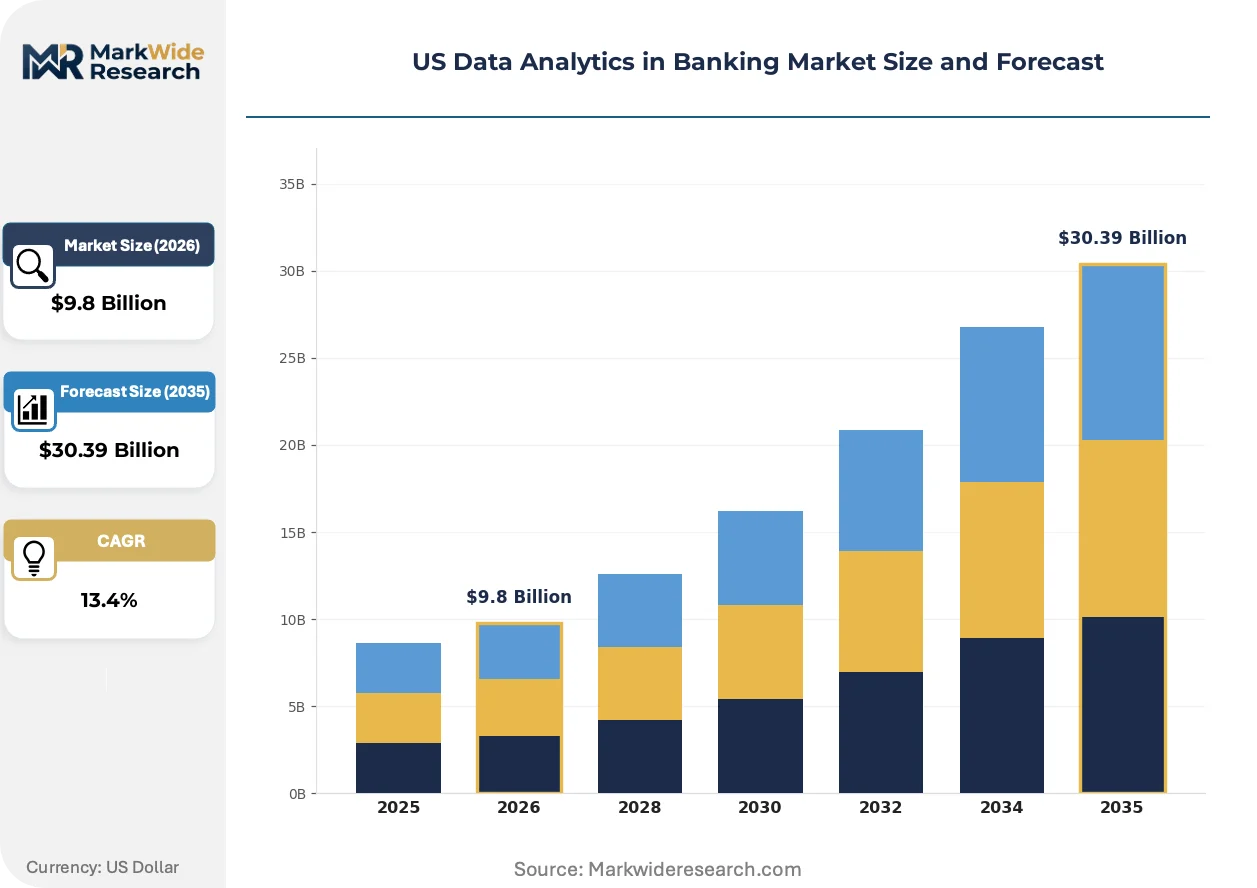
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $30.39 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Predictive Analytics, Risk Management, Customer Segmentation, Fraud Detection Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Retail Banks, Investment Banks, Credit Unions, Insurance Firms Application: Loan Underwriting, Regulatory Compliance, Marketing Optimization, Wealth Management |
| Companies Covered | IBM Corporation, Oracle Corporation, Microsoft Corporation, SAS Institute Inc., SAP SE, Amazon Web Services, Inc., Google, Fiserv, FIS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Data Analytics in Banking Market Trends and Innovations
Edge-deployed stream processing engines are collapsing the gap between transaction execution and risk scoring, eliminating batch-based overnight reconciliation cycles that previously dominated banking operations.
In-memory computing fabrics with sub-millisecond state persistence are rendering obsolete disk-based data warehouses that introduced latency penalties unacceptable for real-time payment fraud detection. Mid-tier banks in Charlotte and Chicago are migrating trading desk analytics to these platforms within 18-month procurement cycles. The compression of infrastructure refresh timelines is forcing incumbent vendors to abandon perpetual license models entirely.
The Consumer Financial Protection Bureau's circular on algorithmic bias in credit decisions requires documented adverse action explanations for automated underwriting denials. This mandate compels banks to abandon black-box ensemble models in favor of interpretable decision trees and rule-based scoring systems. Mortgage originators face the steepest compliance costs as they revalidate decades of automated appraisal and income verification workflows.
Subscription pricing for cloud analytics platforms is displacing capital-intensive on-premises deployments among credit unions with constrained IT budgets. Managed service providers now capture multi-year contracts that bundle infrastructure, model development, and regulatory reporting submission. This shift concentrates most visible in federal credit union segments across the Southeast and Pacific Northwest where internal data science capabilities remain underdeveloped.
US Data Analytics in Banking Market Segmentation
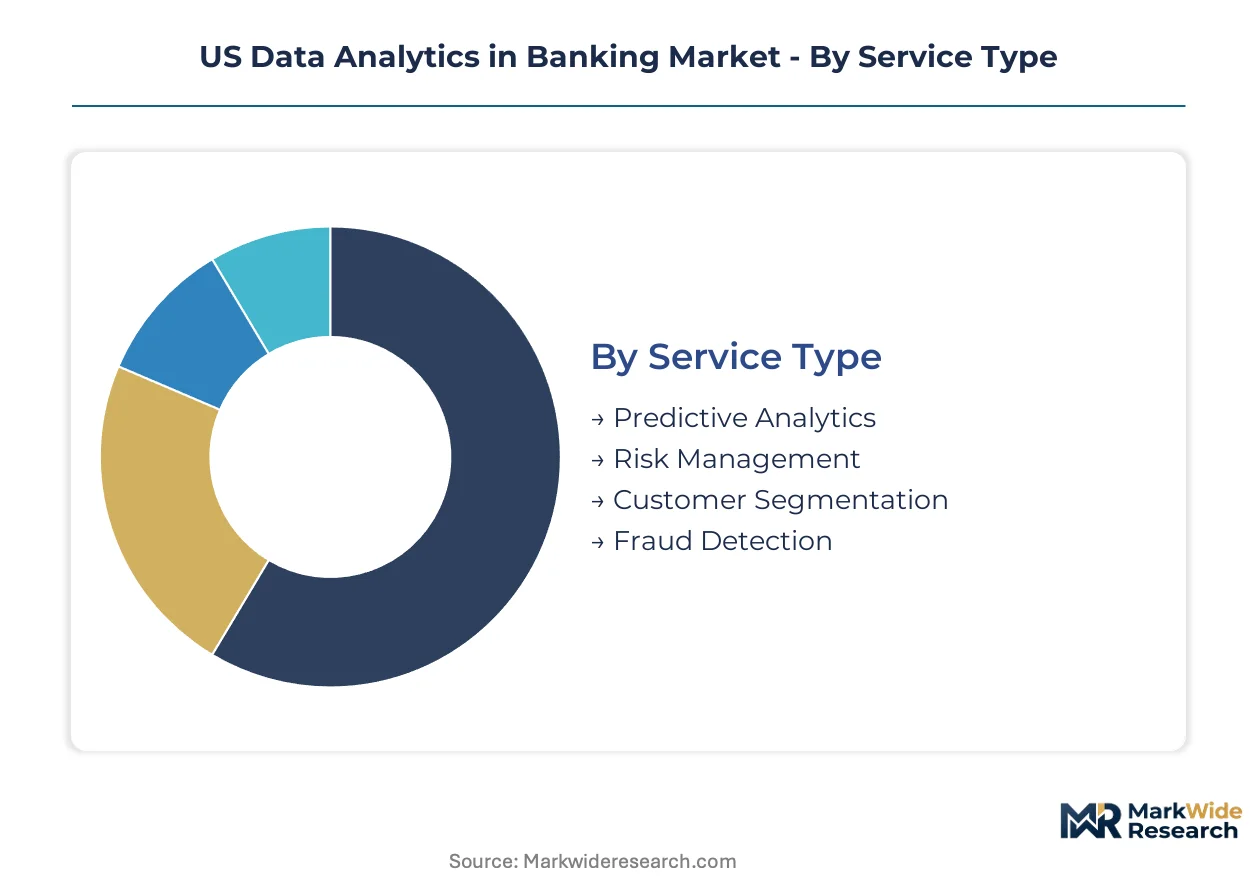
Banks select analytics platforms through four distinct lenses: service capability, infrastructure control, user sophistication, and workflow integration. Each dimension carries procurement weight that shifts with regulatory pressure and capital availability.
Service Type:
Application focus determines which service tier commands budget priority across retail and institutional banking networks.
- Predictive Analytics:Machine learning models forecast portfolio default probabilities and deposit attrition rates using macroeconomic scenario inputs. Demand concentrates among investment banks in New York running CCAR stress-test submissions where model explainability faces Federal Reserve scrutiny.
- Fraud Detection:Real-time stream processing architectures score transactions against behavioral baselines with sub-50-millisecond latency requirements. Regional banks in Charlotte and Chicago are rebuilding core systems around these capabilities as FedNow instant payment rails expand transaction velocity.
- Risk Management:Integrated credit, market, and operational risk dashboards aggregate regulatory capital calculations.
- Customer Segmentation:Micro-clustering algorithms parse transaction histories for targeted product recommendations.
Predictive Analytics holds installed capacity. Fraud Detection is rotating up the share rankings.
Deployment:
Infrastructure control preferences split across data residency mandates, latency tolerance, and IT capital constraints.
- Cloud-Based:Subscription SaaS licensing removes upfront capital barriers for credit unions under $10 billion in assets. Southeast and Pacific Northwest federal credit unions are signing multi-year managed service contracts bundling infrastructure, model development, and regulatory reporting submission.
- Hybrid:Split architectures keep sensitive customer data on-premises while pushing compute-intensive model training to public cloud resources. Microsoft Azure Synapse deployments dominate procurement decisions where state-level privacy statutes in California and New York create fragmented compliance requirements.
- On-Premises:Legacy mainframe-anchored installations persist where API integration costs exceed cloud migration budgets.
- Multi-Cloud:Distributed trading desk operations across Chicago, Charlotte, and San Francisco drive vendor diversification strategies to avoid single-provider lock-in.
Cloud-Based deployment is climbing the fastest. Hybrid architectures are gaining share among mid-tier institutions.
End User:
User sophistication and regulatory burden shape platform complexity requirements and implementation timelines.
- Investment Banks:Distributed trading operations demand sub-millisecond analytics fabrics for real-time position risk calculations. IBM Watson platform relationships anchor institutional procurement where on-premises AI governance satisfies federal credit union examiner requirements.
- Retail Banks:Branch networks and digital channels generate high-velocity transaction streams requiring continuous behavioral monitoring. Gramm-Leach-Bliley Act compliance mandates drive automated data governance platform procurement across these networks.
- Credit Unions:Constrained IT budgets favor managed analytics services over internal data science functions.
- Insurance Firms:Property-casualty and life underwriting workflows require integrated alternative data ingestion for climate risk scoring.
Investment Banks hold installed capacity. Retail Banks are expanding procurement fastest.
Application:
Workflow integration depth determines whether analytics platforms replace legacy point solutions or augment existing infrastructure.
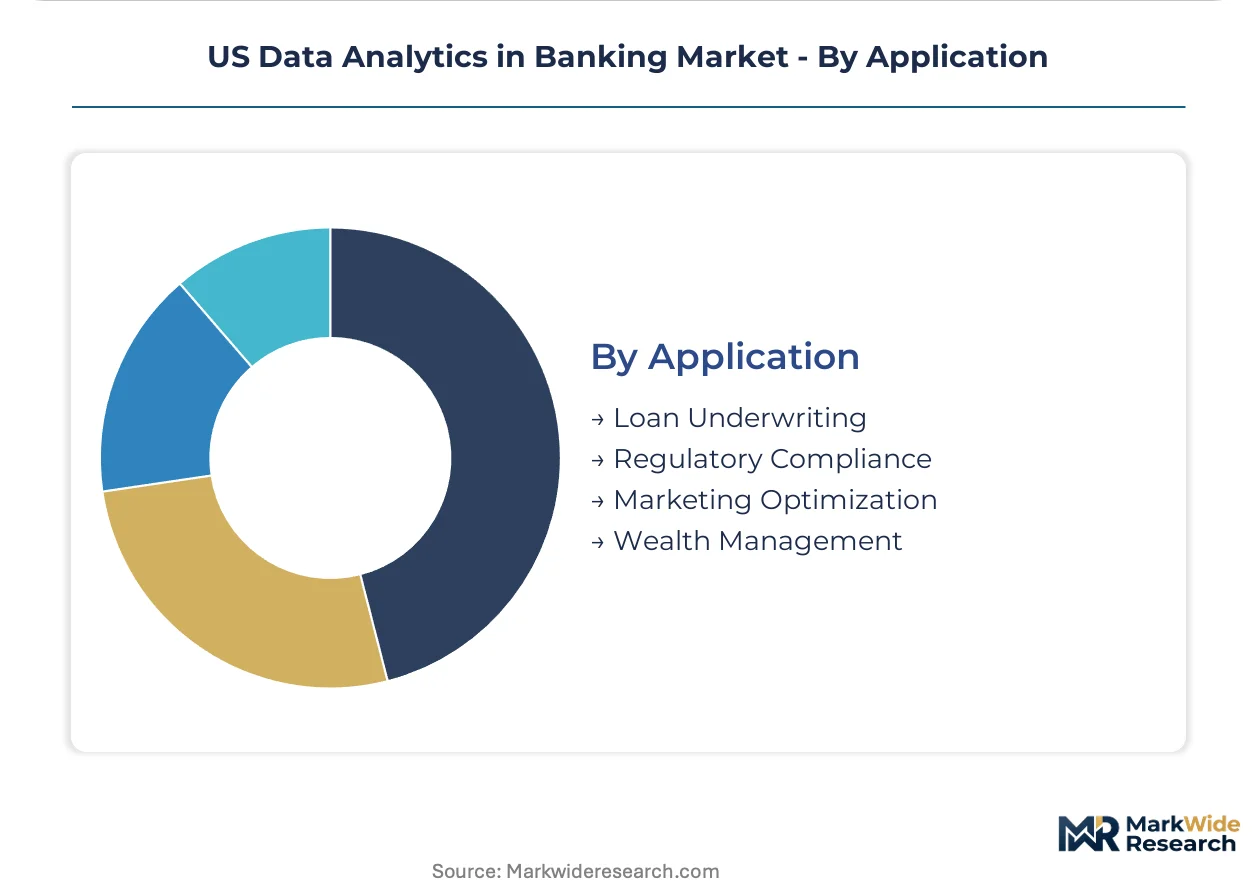
- Regulatory Compliance:Automated reporting infrastructure ingests Dodd-Frank Act and SEC climate disclosure datasets for submission-ready formatting. The Office of the Comptroller of the Currency and Consumer Financial Protection Bureau mandate stress-testing data standards that shape vendor product roadmaps.
- Loan Underwriting:Alternative credit datasets and cash-flow analytics replace traditional FICO-centric models for thin-file borrowers. CFPB circulars on algorithmic bias force abandonment of black-box ensemble models in favor of interpretable decision trees.
- Marketing Optimization:Next-best-action engines orchestrate cross-sell campaigns across digital and branch channels.
- Wealth Management:Portfolio construction algorithms integrate ESG risk scores from satellite imagery and supply chain emissions data.
Regulatory Compliance holds installed capacity. Loan Underwriting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Investment banks and federal credit unions concentrate procurement decisions in distinct geographic clusters shaped by regulatory proximity and talent density.
New York Metro
Major financial institutions headquartered in Manhattan drive enterprise analytics platform procurement for CCAR stress-testing and real-time trading risk calculations. The Federal Reserve Bank of New York shapes vendor roadmaps through supervisory guidance on model risk management. Innovation labs in Hudson Yards and the Financial District pilot edge-computing deployments for sub-millisecond fraud detection latency.
Charlotte
Regional banks rebuilding core transaction systems around FedNow instant payment rails generate demand for stream processing architectures with behavioral analytics integration. The Office of the Comptroller of the Currency's southern regional office influences compliance platform specifications for institutions across the Carolinas. Trading desk operations in Uptown Charlotte are migrating analytics workloads to multi-cloud configurations to avoid vendor lock-in.
Chicago
Commodity derivatives exchanges and commercial banking headquarters sustain demand for predictive risk models ingesting alternative macroeconomic datasets. Illinois state privacy legislation interacts with federal Gramm-Leach-Bliley Act requirements to complicate data governance architecture decisions. The Loop and West Loop financial corridors host concentrated procurement activity for hybrid cloud deployments balancing latency and residency mandates.
San Francisco
Technology-forward credit unions and venture-backed fintech partnerships accelerate adoption of subscription-based SaaS analytics licensing. The California Consumer Privacy Act fragments compliance architectures for multi-state institutions, privileging hybrid deployment modes that keep sensitive data on-premises. SoMa and Mission Bay clusters concentrate vendor sales engineering resources targeting mid-tier institutions with constrained internal data science functions.
Pacific Northwest
Federal credit unions across Oregon and Washington sign multi-year managed service contracts bundling infrastructure, model development, and regulatory reporting submission. State-level privacy statutes in Washington complement federal fair lending enforcement to demand explainable AI frameworks for automated underwriting decisions. Seattle and Portland metropolitan areas exhibit fastest growth in cloud-native analytics adoption among institutions below ten billion dollars in assets.
US Data Analytics in Banking Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Enterprise technology conglomerates anchor institutional relationships through platform breadth and regulatory compliance certification. Pure-play analytics specialists capture premium pricing in fraud detection and predictive modeling niches. Cloud infrastructure providers displace legacy on-premises vendors through consumption-based economics. Dominant competitive moves include strategic partnerships between core banking system vendors and AI platform providers, plus vertical integration into managed regulatory reporting services.
Within the enterprise platform tier, IBM Corporation, Microsoft Corporation, and Oracle Corporation exemplify divergent strategic positioning. IBM Corporation anchors relationships with federal credit unions seeking on-premises AI governance and Watson-based risk modeling. Microsoft Corporation extends Azure Synapse capabilities to capture hybrid deployment scenarios where data residency requirements dominate procurement decisions. Oracle Corporation leverages database-installed bases to embed analytics layers within existing core banking infrastructure relationships.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| SAS Institute Inc. |
| SAP SE |
| Amazon Web Services, Inc. |
| Fiserv |
| FIS |
| Others |
Pricing and Supply Chain Analysis
Manhattan's concentration of enterprise analytics vendors and federal credit union procurement headquarters concentrates pricing power among platform providers serving CCAR stress-testing and real-time fraud detection workloads. Subscription SaaS licensing from cloud infrastructure providers draws from this geographic clustering to compress margins for legacy on-premises vendors while expanding access for mid-tier institutions previously locked out of enterprise-grade capabilities.
Pricing Analysis
Cost-plus contracts with consumer price indexation anchor enterprise platform licensing agreements between major financial institutions and incumbent technology conglomerates. Three-tier pricing structure across premium, standard, and economy levels separates dedicated infrastructure deployments from shared-tenant SaaS offerings and managed analytics services for credit unions below ten billion dollars in assets. Pricing pressure stems from hyperscaler consumption-based economics displacing perpetual license models. Regional banks exhibit highest price sensitivity due to constrained IT budgets, while investment banks prioritize latency performance over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from cloud infrastructure providers ease capital constraints for credit unions migrating from legacy mainframe environments. Hardware component sourcing concentrates in Taiwan, South Korea, and the United States for GPU accelerators and in-memory computing fabrics. Raw material dependencies span advanced semiconductors, high-bandwidth memory modules, and specialized networking equipment. Single-source vulnerability in GPU supply chains creates procurement risk for real-time analytics deployments. Distribution runs through direct enterprise sales teams and managed service provider partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FedNow instant payment rail integration is reshaping competitive positioning around platform economics, as interoperability requirements force consolidation of fragmented point solutions into unified analytics fabrics.
For Market Incumbents: Pre-empt displacement by hyperscalers through embedding analytics layers within core banking system relationships and certifying platforms for Federal Reserve stress-testing data standards. Backward integration into regulatory reporting submission services defends against pure-play managed service entrants. Channel control through federal credit union examiner relationships anchors institutional retention.
For New Entrants and Emerging Players: Southeast federal credit union networks present the most penetrable white space, where internal data science capabilities remain underdeveloped and subscription SaaS economics remove capital barriers. Target loan underwriting automation for thin-file borrowers using alternative credit datasets and cash-flow analytics. Partner with core banking system vendors for distribution leverage.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because Gramm-Leach-Bliley Act and Dodd-Frank Act compliance mandates create durable demand for automated governance platforms regardless of interest rate cycles. Acquisition target archetype: managed analytics specialists with existing federal credit union contracts and CFPB algorithmic bias audit capabilities. Monitor SEC climate disclosure rule enforcement intensity as ESG risk scoring integration inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented fraud detection and stress-testing point solutions into single vendor relationships. |
| Strategic Partnership | Core banking system alliances accelerate procurement cycles for mid-tier institutions with legacy entrenchment. |
| Acquisition of Specialist Firm | Managed analytics services capture credit union white space with bundled infrastructure and regulatory submission. |
| Geographic Expansion | Pacific Northwest federal credit union concentration offers fastest cloud-native adoption among sub-ten-billion-dollar assets. |
| Product Launch | Explainable AI frameworks satisfy CFPB circular requirements for automated underwriting adverse action documentation. |
Research Methodology
Operator-level perspectives from chief data officers, federal credit union IT directors, regulatory compliance leads, and platform engineering heads anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from SEC filings, Federal Reserve supervisory guidance documents, CFPB circulars, and cloud hyperscaler capex disclosures. Bottom-up segmentation modeling and top-down macroeconomic scenario triangulation ensured cross-verification of demand estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing around FedNow adoption velocity and state-level privacy statute fragmentation. Segmentation dimensions modeled encompassed deployment mode, institution asset tier, service capability type, and regulatory compliance application. CAGRs derived from installed base growth rates and replacement cycle compression. Forecast inputs included CCAR submission volumes and real-time payment transaction velocity projections.
Practitioners should monitor Federal Reserve interest rate policy shifts and CFPB algorithmic enforcement intensity for early signals of platform procurement timing. Forecasts reflect assumptions around cloud infrastructure cost curve trajectories and legacy mainframe replacement urgency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Embedded Banking Market
Banking
Banking Software Market
Banking
Latin America Banking As a Service Market
Banking
Italy Data Analytics in Banking Market
Banking
Digital Banking Market
Banking
Retail Banking IT Spending Market
Banking
North America Data Analytics in Banking Market
Banking
China Bank Kiosk Market
Banking
Investment Banking Market
Banking
Automated Teller Machine (ATM) Market
Banking
Global AI in Banking Market
Banking
GCC Mobile Banking Market
Banking
Banking-As-A-Service (Baas) Platform Market
Banking
Corporate Banking Market
Banking
Smart Banking Solutions Market
Banking
Banking Maintenance Support and Services Market