
 Europe Payments Market | 2026-2036
Europe Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Payments Market Foresight
A shortage of qualified payment security engineers is reorganizing how European processors staff their technical operations. Adyen sustains its edge through unified platform architecture spanning acquiring and issuing. Worldline anchors its position via deep banking relationships across France and the Benelux. Mastercard Incorporated competes aggressively on tokenization standards for card-not-present environments.
Europe payments encompass digital fund transfer mechanisms enabling commercial transactions between consumers, merchants, and financial institutions through encrypted authorization protocols and settlement networks. These systems process authorization, clearing, and settlement in milliseconds while maintaining PCI DSS compliance and SCA authentication thresholds under PSD2. Mobile payment methods are capturing the fastest growth as NFC-enabled smartphones displace physical card presentment at point-of-sale terminals. Bank transfer volumes are expanding through open banking APIs that bypass traditional card network rails. Contactless technology dominates in-store transaction throughput across Nordic and Western European retail corridors.
PSD2 mandates from the European Banking Authority enforce strong customer authentication and open API access, reshaping how payment service providers onboard merchants and route transactions. EBA guidelines on interchange fee caps limit card scheme revenue pools while GDPR constraints from EU data protection authorities govern how transaction data flows across borders. Stakeholders must monitor how the EU AI Act classifies automated fraud detection algorithms and whether the European Commission advances a unified digital euro framework that could reretailize payment infrastructure.
Market Dynamics
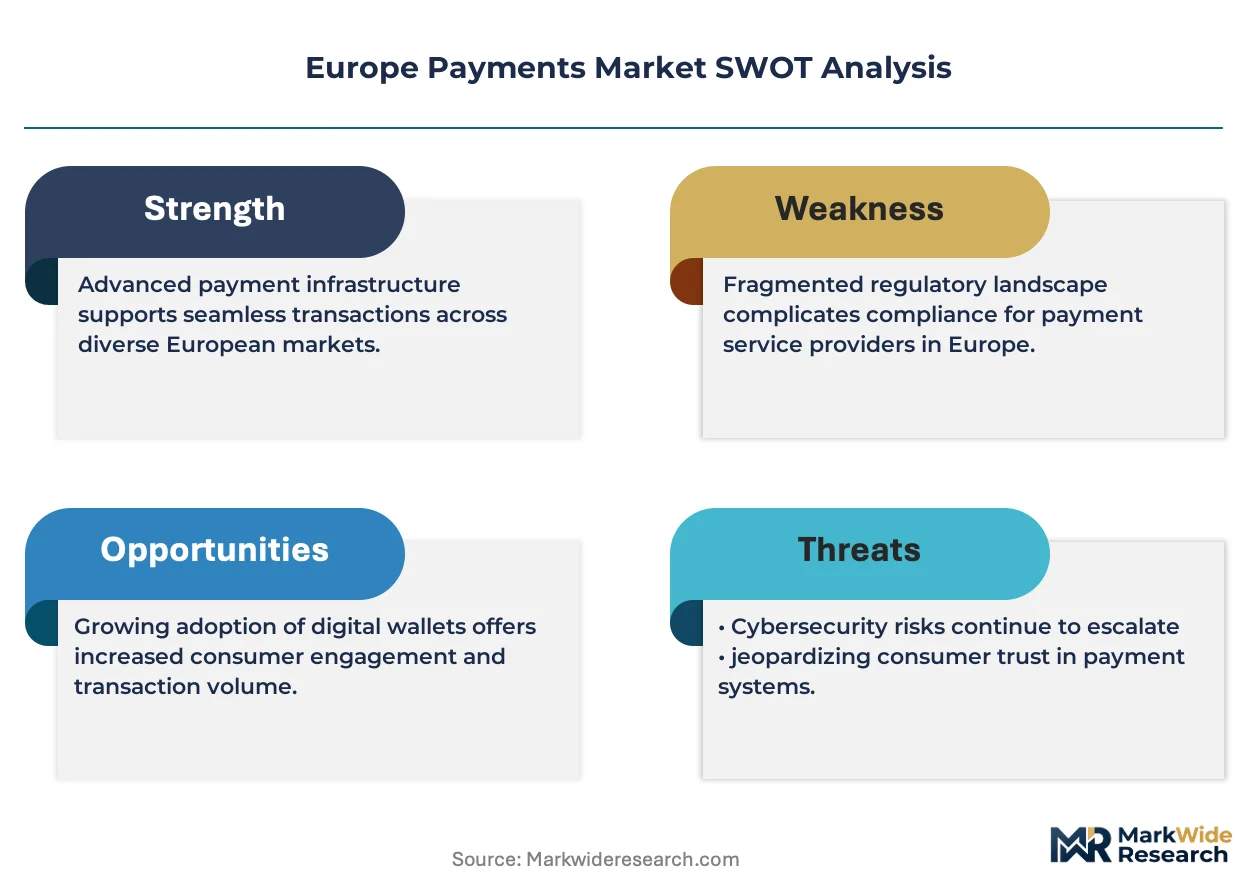
PSD2 mandates from the European Banking Authority are forcing payment service providers to rebuild authentication stacks and open API access, compressing margins for traditional acquirers while enabling new market entrants.
Growth Catalysts
- Real-time payment rails:SEPA Instant Credit Transfer expansion across Germany, France, and the Netherlands is displacing legacy batch settlement cycles for e-commerce merchants.
- Open banking APIs:PSD2-mandated account access interfaces are enabling account-to-account payment flows that bypass interchange fee structures entirely.
- NFC smartphone penetration:Contactless-enabled device saturation above 85% in Nordic corridors is accelerating mobile wallet adoption at physical point-of-sale terminals.
Market Restraints
- Interchange fee caps:EBA regulations limit card scheme revenue pools to 0.2% for debit and 0.3% for credit transactions, constraining processor profitability.
- Qualified security engineer shortage:PCI DSS compliance and SCA implementation requirements exceed available talent supply across Frankfurt, London, and Amsterdam tech clusters.
- GDPR data localization:Cross-border transaction data flows face jurisdictional friction, increasing infrastructure redundancy costs for multi-country processors.
Strategic Opportunities
- Digital euro framework:European Commission central bank digital currency pilots could reretailize payment infrastructure and create new settlement layer opportunities.
- Embedded finance convergence:Banking-as-a-Service APIs combined with checkout orchestration platforms enable non-financial merchants to capture payment float.
- Automated fraud detection:EU AI Act classification of risk-scoring algorithms creates compliance service opportunities for specialized regtech vendors.
Industry Challenges
- Legacy core banking integration:SCA implementation requires real-time authentication handshakes with decades-old batch-oriented bank systems, creating latency failures.
- Certification timeline compression:PSD2 and GDPR compliance audits must complete within 90-day merchant onboarding windows, straining quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Payments Market |
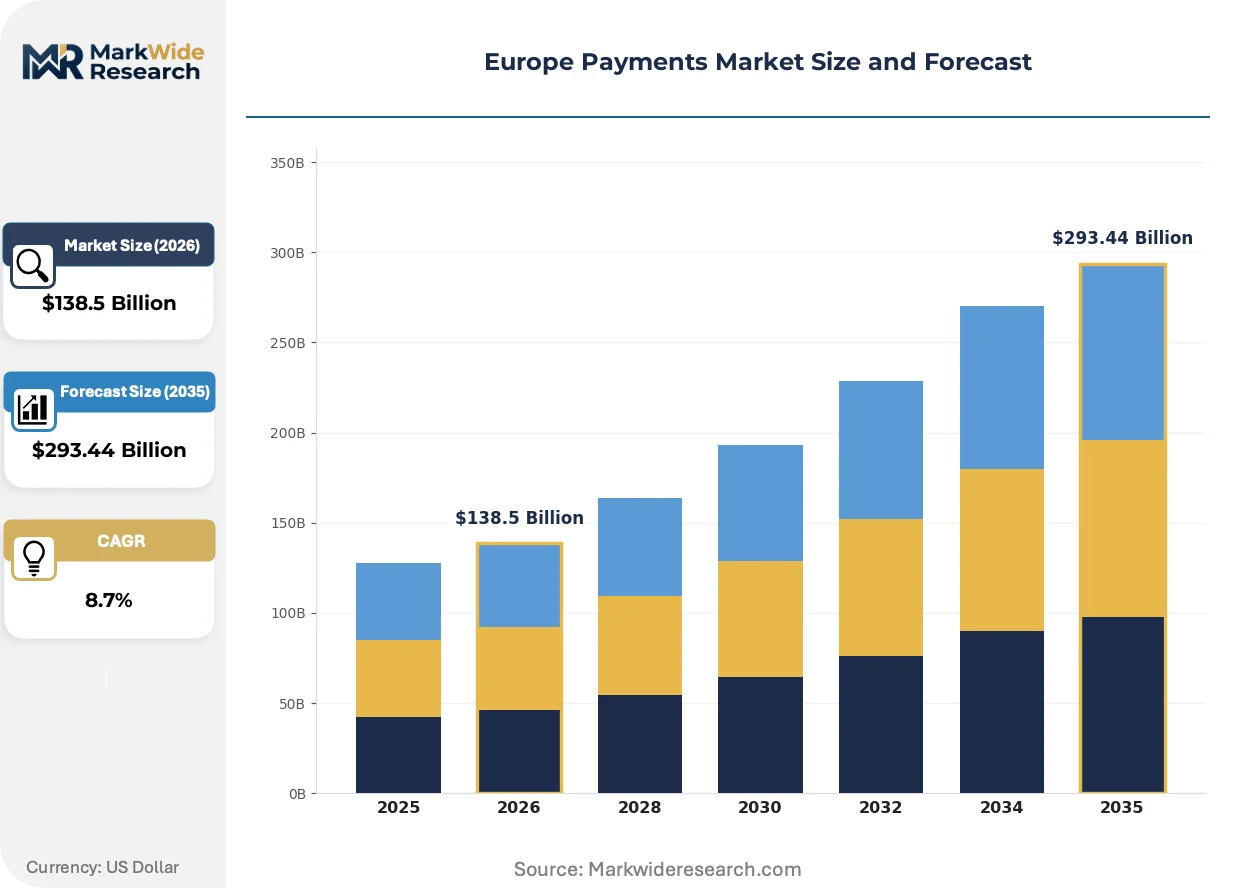
| Market Size in 2026 | $138.5 Billion |
| Market Size in 2035 | $293.44 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Payment, Bank Transfer Transaction Type: E-commerce, In-store, Peer-to-Peer, Subscription Consumer Segment: Millennials, Generation X, Seniors, Small Businesses Technology: Contactless, NFC, Blockchain, QR Code |
| Companies Covered | Visa Inc., Checkout.com, Adyen, Nexi S.p.A., Mollie, Stripe, Worldline, SumUp Inc, Mastercard Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Payments Market Shifts & Advancements
Payment infrastructure is fragmenting across specialized layers as merchants demand composable checkout experiences and regulators enforce open access mandates.
Tokenization technology is decomposing card-not-present security architectures by replacing primary account numbers with cryptographically secure surrogates. E-commerce merchants in fashion and digital services are adopting network tokens at accelerated rates to reduce fraud liability exposure. This shift is decomposing the traditional acquiring value chain by separating authentication from settlement functions.
GDPR enforcement actions from EU data protection authorities are reshaping how transaction data flows across borders and how long processors may retain behavioral analytics. The industrial consequence is mandatory data residency investments and explicit consent management layers for every checkout interaction. German and French retail banking corridors are responding by localizing analytics infrastructure and truncating retention periods.
Merchant procurement of payment services is consolidating toward unified platforms that bundle acquiring, issuing, and risk management under single API contracts. Independent software vendors and marketplace operators are displacing standalone gateway relationships with embedded finance partnerships. This pattern is most visible in Benelux e-commerce clusters where platform economics favor integrated orchestration over best-of-breed point solutions.
Europe Payments Market Segmentation
Payment infrastructure across Europe fragments along four critical dimensions that determine routing economics, authentication requirements, and settlement velocity. Each segmentation axis carries distinct regulatory obligations under PSD2 and diverging technical standards across SEPA jurisdictions.
Payment Method:
Domestic payment preferences vary sharply across European corridors, with northern markets favoring account-to-account rails while southern economies retain card dominance.
- Credit Card:Premium revolving credit instruments carry higher interchange ceilings under EBA caps. French and Italian e-commerce merchants rely heavily on co-branded products for cross-border conversion.
- Debit Card:Immediate funds settlement through SEPA networks dominates German and Dutch retail corridors. PSD2 SCA requirements apply to every transaction above low-value exemption thresholds.
- Mobile Payment:NFC-enabled wallet applications from Apple and Google capture Nordic in-store volume. Berlin and Amsterdam transit authorities have accelerated adoption through closed-loop municipal integrations.
- Bank Transfer:SEPA Instant Credit Transfer rails displace cards for high-value B2B settlements. Open banking APIs from Tink and TrueLayer enable merchant-initiated account-to-account flows.
Debit instruments hold the largest share; momentum sits with bank transfer rails.
Transaction Type:
Volume concentration tilts toward digital commerce, though physical retail retains substantial throughput in cash-preferred southern economies.
- E-commerce:Remote card-not-present transactions require 3D Secure authentication under PSD2 mandates. Fashion and digital services merchants in Benelux corridors drive tokenization adoption for fraud liability reduction.
- In-store:Contactless terminal penetration exceeds 90% in Sweden and Denmark. Legacy POS hardware in Spanish and Portuguese retail creates EMV migration bottlenecks.
- Peer-to-Peer:Mobile number-linked transfers through Bizum and MobilePay capture domestic person-to-person volume. Settlement finality varies across national real-time payment schemes.
- Subscription:Recurring billing models trigger SCA exemptions for merchant-initiated transactions. SaaS and streaming providers optimize for frictionless credential-on-file authentication.
E-commerce commands the dominant position; subscription billing climbs fastest on recurring revenue economics.
Consumer Segment:
Generational payment behavior splits between digital-native cohorts and security-conscious older consumers requiring assisted onboarding.
- Millennials:Mobile-first transaction habits favor biometric authentication and in-app checkout. Amsterdam and Copenhagen fintech penetration rates exceed regional averages for this cohort.
- Generation X:Hybrid channel usage spans desktop e-commerce and contactless physical retail. French and German Gen X consumers show highest adoption of buy-now-pay-later products.
- Seniors:Branch-assisted onboarding and voice-authenticated telephone banking retain importance. Italian and Greek senior populations lag in SCA-compliant mobile enrollment.
- Small Businesses:Integrated receivables and payables through banking APIs reduce manual reconciliation. German Mittelstand firms drive demand for multi-bank cash management platforms.
Millennials represent the most active transactors; small business adoption expands most quickly on embedded finance integration.
Technology:
Hardware and protocol standards determine authentication latency, merchant acceptance costs, and cross-border interoperability.
- Contactless:EMV tap-to-pay at point-of-sale terminals processes under 500 milliseconds. Terminal hardware deployment concentrates in Nordic and British retail corridors.
- NFC:Near-field communication protocols enable smartphone-based card emulation for in-store presentment. Host card emulation versus secure element architectures create Android-iOS fragmentation.
- Blockchain:Distributed ledger settlement for cross-border remittances remains experimental under ECB scrutiny. Stablecoin payment pilots face MiCA regulatory uncertainty.
- QR Code:Static and dynamic quick-response payments gain traction in hospitality and transit verticals. Dutch and Belgian merchant acquirers promote QR as low-cost card alternative.
Contactless infrastructure holds the largest share; QR code deployment gains fastest on minimal hardware requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Banking Authority anchors payment infrastructure governance across the continent, with national implementations of PSD2 and SCA creating divergent compliance environments. SEPA Instant Credit Transfer rails and open banking APIs are reshaping settlement velocity in core economies. GDPR data localization requirements and interchange fee caps under EBA rules compress processor margins while enabling new market entrants.
Germany
SEPA Instant Credit Transfer volumes through Deutsche Bundesbank rails are displacing card networks for B2B settlements. BaFin supervision enforces strict SCA implementation timelines for payment service providers. Berlin and Frankfurt fintech clusters concentrate engineering talent for open banking API development.
United Kingdom
Faster Payments Scheme expansion supports real-time retail settlement independent of EU SEPA infrastructure. Financial Conduct Authority open banking mandates drive account-to-account payment innovation. London's Square Mile hosts dense concentrations of payment processors navigating post-Brexit regulatory divergence.
France
Cartes Bancaires domestic scheme retains substantial volume alongside international card networks in retail corridors. ACPR prudential supervision governs payment institution licensing and SCA compliance. Paris fintech incubators in Station F cluster specialize in embedded finance orchestration platforms.
Netherlands
iDEAL bank transfer dominance in e-commerce creates account-to-account payment preference distinct from card-centric southern markets. De Nederlandsche Bank oversees instant payment scheme participation and PSD2 compliance. Amsterdam's Zuidas financial district anchors acquiring technology development for Benelux merchants.
Sweden
Swish mobile payment saturation above 80% of adult population demonstrates contactless infrastructure maturity. Finansinspektionen supervision enforces strong customer authentication for digital wallet transactions. Stockholm's Kista Science City clusters NFC technology engineering and tokenization protocol development.
Europe Payments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive structure. Consolidated platforms spanning acquiring, issuing, and risk management command premium merchant relationships. Specialists in checkout orchestration and embedded finance carve defensible positions through API differentiation. Geographic expansion through banking partnerships and vertical integration into core banking systems represent the dominant competitive vectors.
Within the integrated platform tier, Adyen and Worldline exemplify full-stack architecture approaches that bundle merchant services under unified contracts. Stripe occupies a position bridging developer-centric tooling with enterprise scale, representing the archetype of API-first expansion into European corridors. These anchors demonstrate how technology licensing and strategic banking relationships reshape competitive positioning without requiring proprietary scheme infrastructure.
| Leading Market Players |
|---|
| Visa Inc. |
| Checkout.com |
| Adyen |
| Nexi S.p.A. |
| Mollie |
| Stripe |
| Worldline |
| SumUp Inc |
| Mastercard Incorporated |
| Others |
Supply & Pricing Matrix
Ninety-day merchant onboarding windows compress both supply chain responsiveness and pricing flexibility for European payment processors navigating PSD2 compliance deadlines. This lead-time constraint concentrates pricing power with integrated platform providers while squeezing standalone gateway margins across Frankfurt and Amsterdam tech clusters.
Pricing Analysis
Geographic price spreads of 40-60 basis points separate Nordic corridor rates from southern European interchange benchmarks. Transactional per-unit pricing dominates, with volume scale and SCA compliance certification tier as primary differentiation drivers. Pricing pressure stems from EBA interchange fee caps constraining processor profitability. Small merchants exhibit highest price sensitivity; enterprise retailers negotiate through unified platform bundling.
Supply Chain Analysis
Certification bottlenecks at PCI DSS audit facilities in London and Frankfurt throttle supply chain velocity for new market entrants. Engineering talent concentrates in Germany, the Netherlands, and the United Kingdom; data center infrastructure draws from Ireland, France, and Sweden. Single-source vulnerability sits with qualified security engineer availability. Distribution runs through banking partnership channels and API marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe payments market is recovering from cyclical margin compression as SEPA Instant Credit Transfer volumes displace legacy batch settlement economics and restore processor yield structures.
For Market Incumbents: Consolidate authentication stack investments against open banking API entrants eroding interchange-dependent revenue pools. Deepen banking relationships across Benelux corridors to lock in merchant switching costs. Prioritize embedded finance orchestration capabilities as the defensive lever against platform unification trends.
For New Entrants and Emerging Players: Anchor in German Mittelstand B2B payment corridors where multi-bank cash management platform demand outpaces incumbent coverage. Target subscription billing SaaS providers seeking frictionless credential-on-file authentication. Pursue regtech partnerships as the go-to-market angle for EU AI Act compliance services.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across checkout orchestration software layers as cloud infrastructure commoditizes compute costs. Long-term viability favors specialists with proprietary tokenization protocols and deep banking API integrations. Watch SEPA Instant Credit Transfer adoption curves as the inflection signal for account-to-account payment infrastructure valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Banking API Integration | Deepens merchant switching costs through Deutsche Bundesbank and Banque de France rail connectivity. |
| Tokenization Protocol Development | Reduces fraud liability exposure for fashion and digital services merchants in Benelux corridors. |
| SCA Compliance Automation | Compresses 90-day merchant onboarding timelines through automated PSD2 authentication stack certification. |
| Embedded Finance Partnership | Enables non-financial merchants to capture payment float via Banking-as-a-Service API convergence. |
| Regulatory Technology Investment | Positions vendors for EU AI Act risk-scoring algorithm classification compliance service opportunities. |
Research Methodology
Initial hypotheses were tested against primary input from payment service provider executives, merchant acquiring directors, open banking API engineers, and regulatory compliance officers and refined through secondary validation against ECB payment statistics, EBA PSD2 implementation reports, SEPA Instant Credit Transfer volume disclosures, and national central bank settlement data. Bottom-up transaction volume modeling triangulated with top-down market sizing across payment method, transaction type, consumer segment, and technology dimensions.
Variance decomposition across the projection horizon isolates growth contributions from real-time payment rail expansion, NFC smartphone penetration curves, and open banking API adoption rates. Segmentation modeling captured payment method, transaction type, consumer segment, and technology dimensions alongside regional regulatory cluster differentiation. CAGRs derived from historical SEPA volume trajectories and merchant digital checkout adoption elasticities, with forecast inputs including Deutsche Bundesbank instant payment participation rates and GDPR enforcement action frequency.
Material uncertainties — EBA interchange fee regulation revisions, EU digital euro framework advancement, and qualified security engineer supply constraints — sit outside the modeled envelope. Forecasts reflect assumptions about PSD2 SCA implementation timelines and open banking API standardization velocity. Practitioners should keep alternative scenarios live as MiCA stablecoin provisions and EU AI Act enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Bill Splitting Apps Market
Payments
Payment Security Software Market
Payments
Wearable Payments Market
Payments
Blockchain Payments Software Market
Payments
Global Wearable Payment Device Market
Payments
Consumer Mobile Payment Market
Payments
Thailand Mobile Payments Market
Payments
Australia Payments Market
Payments
Electronic Payment System for Transportation Market
Payments
Digital Money Transfer Market
Payments
Hong Kong Credit Cards Market
Payments
Norway POS Terminals Market
Payments
Smart Bands Payments Market
Payments
Latin America Mobile Payment Market
Payments
Transit Cards Market
Payments
Mobile Payment Market