
 Virtual Currency Market | 2026-2036
Virtual Currency Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Currency Market Analysis
Retail investor fragmentation is expanding across mobile-native trading platforms and neobank integrations. Bitcoin leverages its first-mover position and fixed supply cap to sustain store-of-value positioning among institutional treasuries. Ethereum anchors smart-contract utility through its proof-of-stake validation layer, while Solana competes on transaction throughput for decentralized application developers.
Virtual currency comprises cryptographically secured digital tokens operating on distributed ledger networks, with Bitcoin using SHA-256 proof-of-work consensus and Ethereum employing proof-of-stake validation with finality thresholds under fifteen minutes. The primary commercial purpose spans peer-to-peer value transfer, programmable financial contracts, and tokenized asset settlement without intermediary clearing. Exchange platforms dominate transaction fee revenue pools, while institutional custody and staking-as-a-service segments capture expanding margin accretion from regulated asset managers. Developer tooling and smart-contract infrastructure represent the fastest-growing technology layer as enterprises pilot tokenized treasury and supply-chain applications.
The SEC enforces securities classification tests for token issuances, while the EU MiCA framework establishes reserve-backing requirements for stablecoin issuers and exchange licensing standards. Singapore's MAS and Switzerland's FINMA shape demand through graduated authorization tiers that separate retail-accessible tokens from restricted professional instruments. Stakeholders must monitor how jurisdictional arbitrage between these frameworks affects liquidity fragmentation and compliance cost allocation across trading venues.
Market Dynamics
Regulatory fragmentation across major financial centers is forcing issuers and exchanges to maintain parallel compliance architectures, driving operational complexity while creating jurisdictional arbitrage opportunities for nimble operators.
Growth Catalysts
- MiCA framework implementation:The EU's Markets in Crypto-Assets regulation establishes clear licensing pathways for stablecoin issuers and exchanges, reducing legal uncertainty for institutional entrants across the 27-member bloc.
- Proof-of-stake validation migration:Ethereum's consensus layer shift reduced energy consumption by over 99%, enabling ESG-constrained asset managers to allocate to staking yields without sustainability conflicts.
- Singapore custody specialization:MAS graduated authorization tiers separate retail-accessible tokens from professional instruments, concentrating licensed custody providers in the city-state.
Market Restraints
- SEC securities classification uncertainty:The Howey test application to token issuances creates enforcement risk that chills primary market activity and raises legal defense costs for US-domiciled projects.
- Stablecoin reserve concentration:Dollar-denominated reserves concentrate in short-term Treasury instruments, exposing issuers to interest rate volatility and rollover risk during monetary tightening cycles.
- Cross-chain interoperability gaps:Bridge protocols remain vulnerable to exploits, limiting composability between Layer-1 networks and fragmenting liquidity across isolated execution environments.
Strategic Opportunities
- Tokenized real-world assets:Private credit, real estate, and commodity instruments on public blockchains unlock fractional ownership for retail investors previously excluded from illiquid alternative markets.
- Layer-2 settlement integration:Rollup architectures compress transaction costs below one cent, enabling micropayment use cases in gaming and content monetization that Layer-1 fees previously priced out.
- UAE regulatory sandbox expansion:Dubai's VARA framework permits controlled experimentation with novel custody and trading structures, attracting hedge funds seeking operational flexibility.
Industry Challenges
- Smart-contract auditing capacity constraints:Formal verification expertise remains scarce relative to deployment velocity, leaving DeFi protocols exposed to exploits that drain nine-figure treasuries.
- Institutional onboarding friction:Sub-custody arrangements, insurance coverage gaps, and board-level risk appetite limitations slow treasury allocation decisions despite yield advantages over money market instruments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Currency Market |
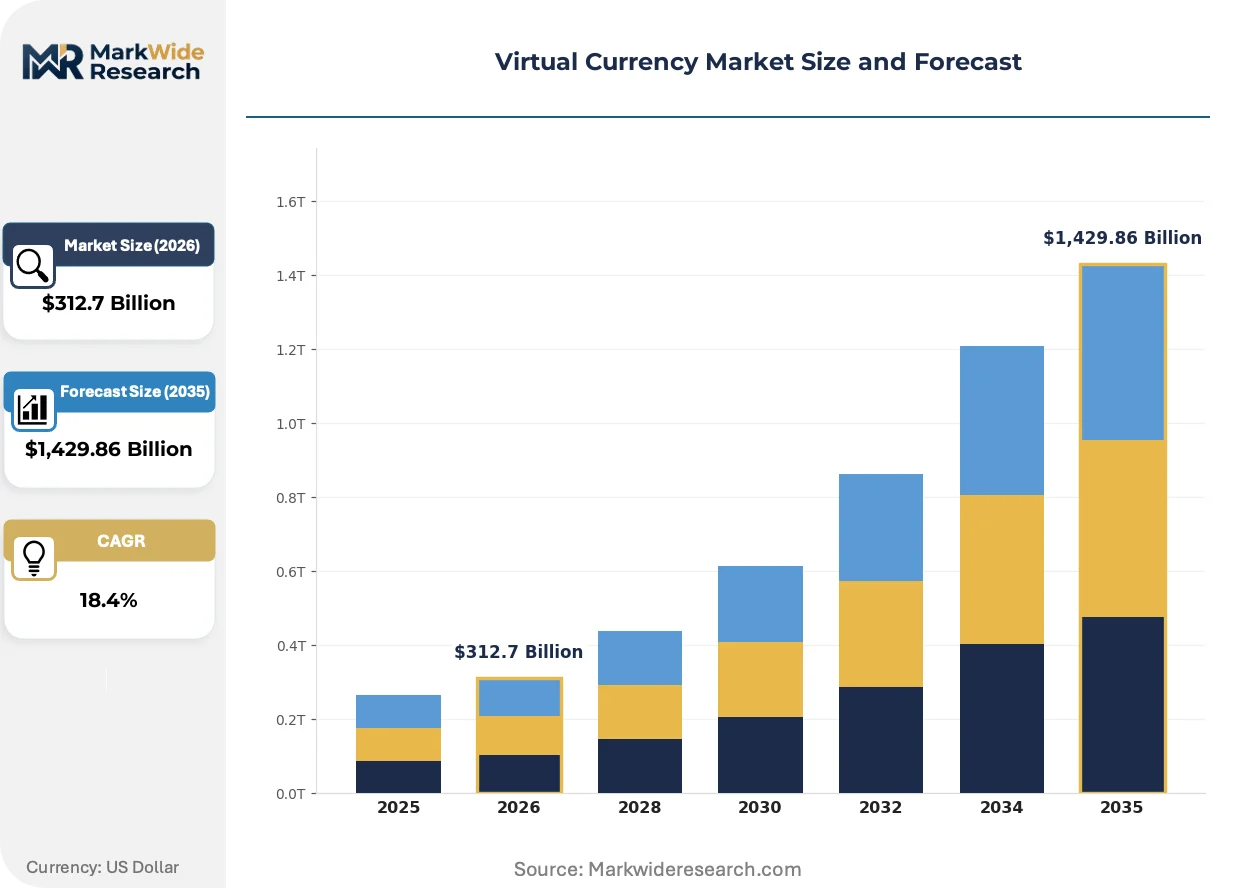
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $1,429.86 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Currency Type: Bitcoin, Ethereum, Litecoin, Ripple Platform Type: Exchange, Wallet, Mining, Payment Gateway End User Type: Retail Investor, Institutional Investor, Merchant, Developer Technology: Blockchain, Smart Contract, Tokenization, Cryptography |
| Companies Covered | Bitcoin, Ethereum, Tether, BNB, XRP, USD Coin, Solana, TRON, Dogecoin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Currency Market Emerging Trajectories
Artificial intelligence agents are beginning to execute on-chain transactions autonomously, compressing the latency between signal generation and settlement while raising new questions about liability and control.
Programmable smart contracts are automating collateral management, liquidation sequencing, and yield optimization across DeFi protocols. Institutional treasuries at hedge funds and family offices are deploying capital through these systems to capture basis trades and staking spreads. This automation is compressing the operational headcount required to manage complex multi-protocol positions.
EU MiCA reserve-backing requirements for stablecoin issuers are reshaping commercial paper and Treasury bill demand patterns. Issuers must hold liquid assets in segregated accounts, disqualifying opaque reserve compositions. Circle and Tether issuance strategies are diverging as they adapt to Brussels-mandated disclosure and redemption standards.
Neobank distribution partnerships are displacing standalone exchange applications for retail onboarding. Revolut, N26, and Cash App users now access Bitcoin and Ethereum through embedded interfaces without separate KYC flows. European and Latin American markets show the highest penetration of this consolidated financial super-app model.
Virtual Currency Market Segmentation
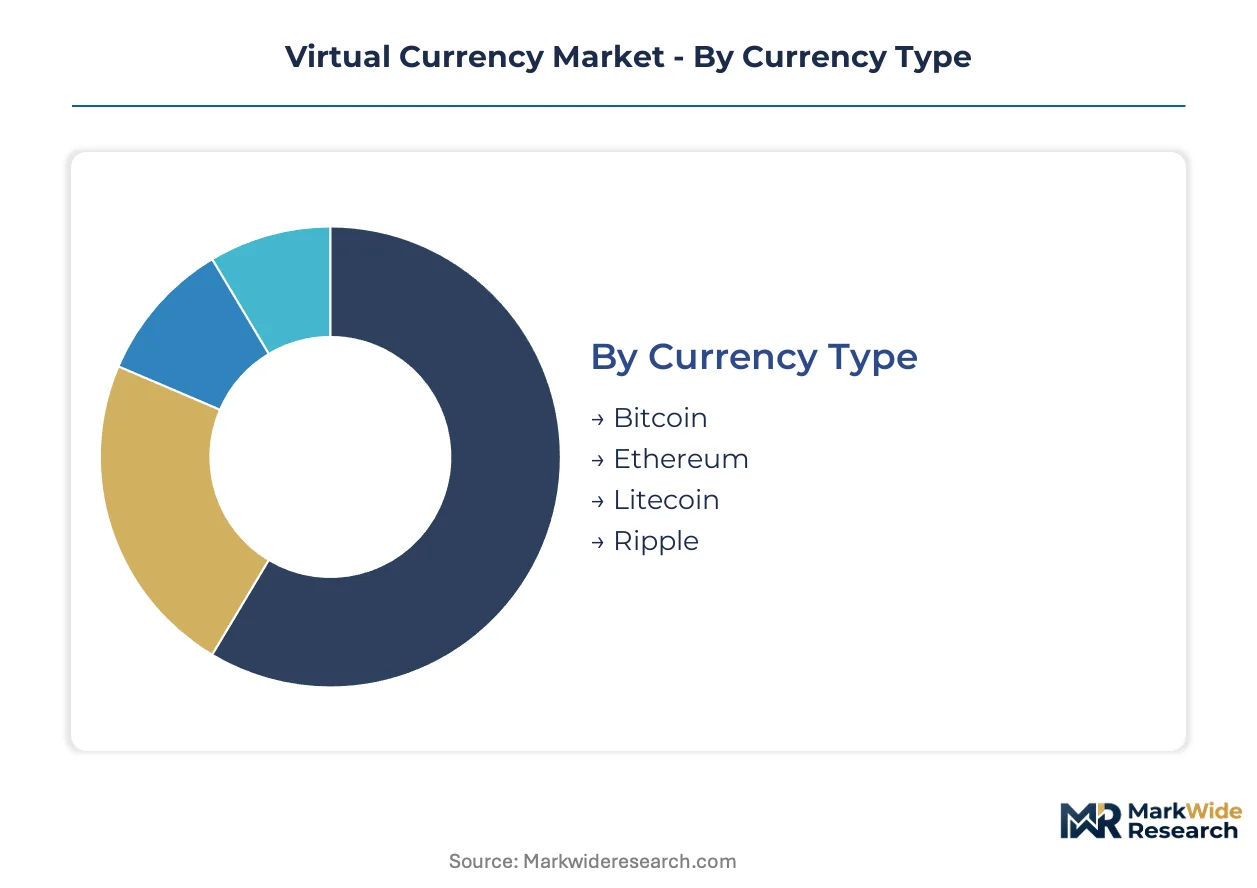
Virtual currency market segmentation reveals how value capture concentrates across infrastructure layers and participant types. Distinct compliance requirements and technical specifications fragment the addressable opportunity across trading venues, custody solutions, and development environments.
Currency Type:
Supply concentration among proof-of-work and proof-of-stake networks creates divergent operational economics for miners, validators, and stakers.
- Bitcoin:SHA-256 proof-of-work consensus enforces a fixed supply cap of 21 million units. Institutional treasuries in the United States and Switzerland allocate to Bitcoin for non-correlated store-of-value exposure, though energy intensity constrains ESG-mandated capital.
- Ethereum:Proof-of-stake validation with sub-fifteen-minute finality anchors smart-contract utility. Developer demand concentrates in Singapore and the United Arab Emirates, where MAS and VARA frameworks provide regulatory clarity for staking-as-a-service providers.
- Litecoin:Scrypt-based hashing delivers faster block confirmation than Bitcoin. Retail payment processors in Europe integrate Litecoin for point-of-sale velocity.
- Ripple:Federated consensus protocol targets cross-border remittance corridors. Banking partnerships in Asia-Pacific leverage XRP for nostro-vostro liquidity optimization.
Bitcoin absorbs the bulk of institutional treasury allocation; Ethereum is expanding most quickly through Layer-2 scaling deployments.
Platform Type:
Revenue pools concentrate at the exchange layer, though margin compression from zero-fee trading is pushing providers toward custody and staking verticals.
- Exchange:Centralized order-matching engines dominate spot and derivatives volume. MiCA licensing requirements in Europe are consolidating authorization-holding venues while fragmenting liquidity across compliant and non-compliant operators.
- Wallet:Self-custody solutions span hot software interfaces and cold hardware devices. Regulatory mandates in Singapore require segregated key management for retail-facing custody providers.
- Mining:Proof-of-work hashing infrastructure concentrates in jurisdictions with stranded energy assets. Kazakhstan and Texas attract compute migration following China's extraction ban.
- Payment Gateway:Merchant acceptance rails bridge fiat settlement with on-chain finality. Latin American neobanks embed Bitcoin payment functionality for remittance-receiving households.
Exchange platforms capture the dominant share of transaction fee revenue; Wallet infrastructure is climbing the fastest as self-custody mandates proliferate.
End User Type:
Participation thresholds vary sharply across KYC intensity, minimum ticket sizes, and technical sophistication requirements.
- Retail Investor:Mobile-native onboarding through neobank integrations displaces standalone exchange applications. European markets show the highest penetration of consolidated financial super-app access.
- Institutional Investor:Hedge funds and family offices deploy capital through sub-custody arrangements with regulated banking partners. Insurance coverage gaps and board-level risk appetite limitations slow allocation velocity.
- Merchant:Point-of-sale acceptance remains concentrated in cross-border e-commerce and remittance corridors. Settlement finality latency constrains brick-and-mortar adoption.
- Developer:Smart-contract engineers build decentralized applications on Layer-1 and Layer-2 networks. Tooling demand concentrates in ecosystems with grant programs and hackathon infrastructure.
Retail investors account for the largest participant base by headcount; Institutional investors are gaining share fastest as compliance frameworks mature.
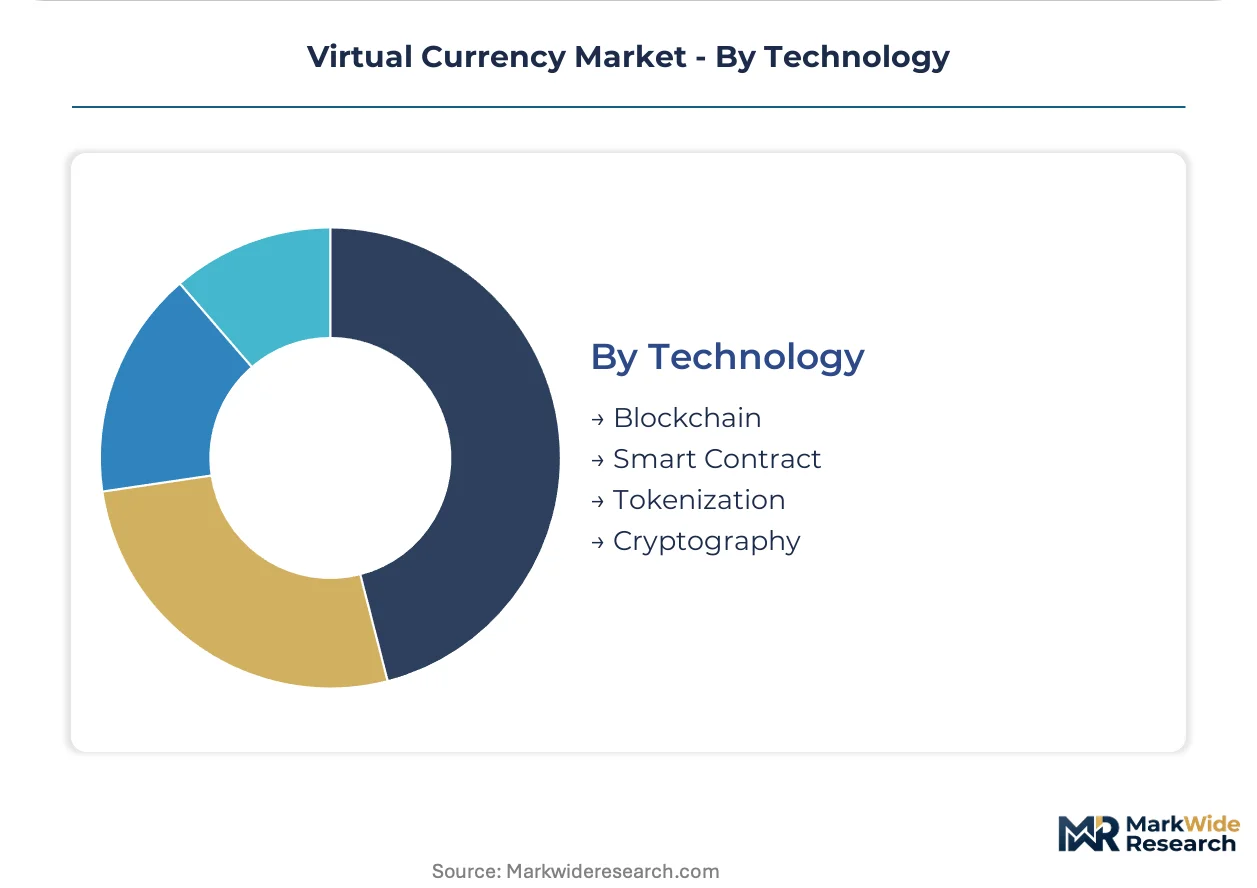
Technology:
Stack abstraction is compressing the specialized expertise required to deploy on-chain applications, though security vulnerabilities persist at the protocol and contract layers.
- Blockchain:Distributed ledger consensus mechanisms span proof-of-work, proof-of-stake, and delegated validation architectures. Energy consumption tradeoffs drive network selection for enterprise pilots.
- Smart Contract:Programmable execution automates collateral management, liquidation sequencing, and yield optimization. Formal verification expertise scarcity leaves DeFi protocols exposed to exploit risk.
- Tokenization:Real-world asset representation on public chains unlocks fractional ownership for previously illiquid instruments. Private credit and real estate pilots are advancing in the United Arab Emirates regulatory sandbox.
- Cryptography:Zero-knowledge proofs and multi-party computation enable privacy-preserving transaction validation. Institutional custody providers deploy threshold signature schemes for key management.
Blockchain infrastructure underpins all commercial activity; Smart Contract automation is expanding most quickly through DeFi protocol composability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in jurisdictions that balance regulatory clarity with operational flexibility. Singapore, Switzerland, and the United Arab Emirates have captured disproportionate institutional custody and trading infrastructure as issuers flee enforcement-heavy regimes.
United States
Institutional treasuries at technology and financial services firms allocate to Bitcoin for non-correlated store-of-value exposure. The SEC applies the Howey test to token issuances, creating enforcement risk that chills primary market activity. Texas attracts proof-of-work mining migration with stranded energy assets and permissive state-level frameworks.
Switzerland
FINMA graduated authorization tiers separate retail-accessible tokens from restricted professional instruments, concentrating licensed custody providers in Zug and Zurich. The Crypto Valley cluster anchors Ethereum staking-as-a-service operations for European asset managers. Swiss banks now offer sub-custody arrangements that satisfy board-level risk requirements for hedge fund allocations.
Singapore
MAS regulatory clarity for digital asset custody and trading has concentrated licensed infrastructure providers in the city-state. Institutional demand for Ethereum staking yields flows through Singapore-domiciled service providers. The jurisdiction's segregated key management mandates for retail-facing custody have spawned specialized hardware security module vendors.
United Arab Emirates
Dubai's VARA framework permits controlled experimentation with novel custody structures, attracting hedge funds seeking operational flexibility. Tokenized real estate and private credit pilots advance in the regulatory sandbox. Abu Dhabi complements Dubai with banking-grade custody licensing for sovereign wealth fund allocations.
Germany
MiCA implementation positions German banks to offer compliant custody and exchange services across the 27-member bloc. BaFin early licensing for crypto custody has given domestic institutions first-mover advantage in institutional onboarding. Frankfurt's banking infrastructure now supports euro-denominated stablecoin redemption rails.
Virtual Currency Market Vendor Landscape
Established protocols occupy the store-of-value and smart-contract utility tiers; emerging entrants pursue transaction throughput specialization and Layer-2 scaling solutions. Market structure fragments across consensus mechanisms, with proof-of-work networks commanding institutional treasury allocation while proof-of-stake ecosystems capture developer tooling demand. Three archetypes dominate: fixed-supply monetary assets, programmable settlement layers, and fiat-backed stablecoins. Competitive moves concentrate on Layer-2 integration partnerships and regulatory licensing across multiple jurisdictions.
Within the monetary asset tier, Bitcoin and Ethereum anchor institutional positioning through divergent value propositions. Tether and USD Coin exemplify the reserve-backed stablecoin archetype, with issuance strategies diverging under Brussels-mandated disclosure standards. Solana occupies a position among throughput-optimized alternatives targeting decentralized application developers.
| Leading Market Players |
|---|
| Bitcoin |
| Ethereum |
| Tether |
| BNB |
| XRP |
| USD Coin |
| Solana |
| TRON |
| Dogecoin |
| Others |
Supply Flow & Price Mechanics
Proof-of-stake validation migration across Ethereum and competing Layer-1 networks compresses energy costs below one percent of prior proof-of-work baselines while redistributing supply concentration toward jurisdictions with favorable staking tax treatment and regulatory clarity.
Pricing Analysis
Transaction fee revenue pools split between high-volume retail exchanges and low-margin institutional over-the-counter desks. Pricing stratifies across premium custody tiers with insurance-backed segregation, standard exchange-traded spot rates, and economy-grade self-custody solutions with hardware wallet acquisition costs. Cost compression in retail onboarding channels intensifies because neobank distribution partnerships eliminate standalone KYC overhead. Retail investors through mobile-native platforms exhibit highest price sensitivity; sovereign wealth funds and hedge fund treasuries show least sensitivity due to yield-focused allocation mandates.
Supply Chain Analysis
Cross-border settlement latency and custody hardware logistics tether operational costs to Singapore, Switzerland, and the United Arab Emirates as primary concentration points for institutional-grade infrastructure. Mining equipment and validator node hardware draw from Taiwan semiconductor foundries, Chinese ASIC manufacturers, and South Korean memory suppliers. Single-source vulnerability concentrates in specialized hardware security module production for institutional key management. Distribution runs through licensed exchange venues, regulated custody providers, and embedded neobank interfaces for retail access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Institutional staking capacity scarcity props fee-based pricing power as validator node deployment lags demand from ESG-constrained asset managers.
For Market Incumbents: Hedge against regulatory fragmentation by maintaining parallel compliance architectures across MiCA, SEC, and MAS frameworks simultaneously. Vertical integration into custody hardware manufacturing mitigates supply bottlenecks from Taiwan and South Korean component vendors. Capacity addition in Dubai's VARA sandbox captures hedge fund demand for operational flexibility. For New Entrants and Emerging Players: MiCA in Europe opens a window for compliant stablecoin issuance with Brussels-mandated reserve transparency. Tokenized real-world assets in the United Arab Emirates regulatory sandbox represent the most penetrable white-space target. Go-to-market through neobank API partnerships bypasses standalone application customer acquisition costs. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by regulated banking groups seeking digital asset custody capabilities. Long-term viability hinges on jurisdictional licensing breadth rather than single-market dominance. The signal to watch is institutional treasury allocation velocity from technology sector balance sheets.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Licensing Expansion | Multi-jurisdictional authorization from MAS, FINMA, and VARA unlocks institutional capital pools. |
| Staking Infrastructure Buildout | Validator node deployment in Singapore and Switzerland captures ESG-mandated yield demand. |
| Neobank Distribution Partnership | Embedded interfaces through Revolut and N26 displace standalone exchange customer acquisition. |
| Tokenized Asset Platform Launch | Private credit and real estate pilots in Dubai's VARA sandbox unlock fractional ownership markets. |
| Layer-2 Settlement Integration | Rollup architectures below one-cent fees enable gaming and content micropayment use cases. |
Methodological Framework
Multi-period observation of staking yield spreads, regulatory authorization timelines, and institutional allocation flows anchored the trend analysis, supplemented by interviews with exchange compliance officers, custody infrastructure engineers, neobank product managers, and asset manager digital asset strategists. Secondary validation drew from SEC enforcement actions, MAS licensing disclosures, EU MiCA regulatory texts, and validator network participation data. Bottom-up transaction volume modeling and top-down macro allocation sizing were triangulated against exchange-reported fee revenue and custody provider asset under management disclosures.
Input-output matrices mapped currency type, platform category, and end-user archetype against jurisdictional regulatory frameworks across the projection horizon. Segmentation dimensions modeled encompassed proof-of-work versus proof-of-stake consensus mechanisms, centralized versus self-custody infrastructure, and retail versus institutional participation tiers. CAGRs were derived from network participation growth rates and fee pool expansion trajectories. Forecast inputs incorporated Ethereum staking participation ratios and MiCA implementation compliance cost estimates.
The model assumes a particular technology adoption path; alternative pathways for zero-knowledge proof scaling solutions would alter the outlook for Layer-2 fee compression and validator economics. Forecasts reflect assumptions regarding regulatory enforcement continuity and institutional risk appetite normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
NFT Art Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
Digital Asset Transaction Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Germany Online Trading Platform Market