
 Smart Home Payments Market | 2026-2036
Smart Home Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Payments Market Outlook
Property managers and utility service providers is bifurcating the Smart Home Payments landscape away from individual consumer bill-pay. Samsung Electronics leverages its smart appliance installed base to embed payment credentials directly into refrigerator and television interfaces. Visa anchors the credential layer by tokenizing card data for IoT endpoints with minimal user interaction. Mastercard differentiates through biometric authentication protocols that reduce friction in high-frequency micro transactions.
Smart Home Payments denote financial transaction execution through internet-connected residential devices using near-field communication, voice recognition, or automated scheduling protocols to transfer value without direct mobile phone or physical card presentation. The primary commercial purpose centers on reducing purchase friction for recurring household expenditures such as energy refills, grocery replenishment, and subscription services. Digital Wallet and Mobile Payment methods are capturing the fastest growth as consumers abandon card-on-file setups in favor of device-native credential storage. Smart Speakers dominate transaction origination volume, though Security Systems are emerging as a higher-margin segment due to integrated insurance and monitoring payment bundles.
The Federal Trade Commission scrutinizes data collection practices in voice commerce, while the Payment Card Industry Security Standards Council mandates tokenized credential isolation for IoT endpoints. The European Banking Authority's strong customer authentication rules under PSD2 create compliance thresholds that favor established token vault providers over emerging hardware entrants. Stakeholders must weigh the pace of biometric standardization against regulator appetite for algorithmic transparency in automated purchasing decisions.
Market Dynamics
Voice commerce is pulling transaction origination out of banking applications and into ambient home environments, fundamentally restructuring how payment credentials are stored, authenticated, and monetized across connected residential ecosystems.
Growth Catalysts
- PSD2 Strong Customer Authentication:The European Banking Authority's mandate for multi-factor verification is accelerating token vault adoption among IoT endpoint manufacturers seeking compliant credential isolation.
- Utility service provider consolidation:Property managers are aggregating tenant payment flows through integrated smart home platforms, creating embedded finance opportunities at the building infrastructure level.
- Biometric standardization:Fingerprint and voiceprint protocols are reducing authentication friction for refrigerator and television-initiated replenishment transactions.
Market Restraints
- PCI DSS compliance costs:Tokenization architecture requirements for connected devices impose significant certification overhead on hardware manufacturers with limited security expertise.
- Cloud infrastructure concentration:Payment processing for IoT endpoints depends on hyperscale providers with pricing power over transaction routing economics.
- Voice spoofing vulnerabilities:Synthetic audio attacks against speaker-based commerce create liability exposure that insurers are pricing aggressively.
Strategic Opportunities
- Germany's smart building retrofit mandates:Federal energy efficiency regulations are driving connected HVAC and appliance replacements with embedded payment capability.
- Security system bundling:Integrated insurance and monitoring payment packages attached to residential surveillance hardware generate recurring revenue at premium margins.
- Edge computing convergence:Local transaction processing on home gateways reduces latency and cloud dependency for time-sensitive replenishment triggers.
Industry Challenges
- Embedded systems security talent scarcity:Firmware engineers with payment security expertise command compensation premiums that strain mid-tier device manufacturer staffing.
- Multi-jurisdiction certification timelines:Simultaneous FDA, FCC, and GDPR compliance for health-monitoring payment devices extends product launch cycles substantially.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Payments Market |
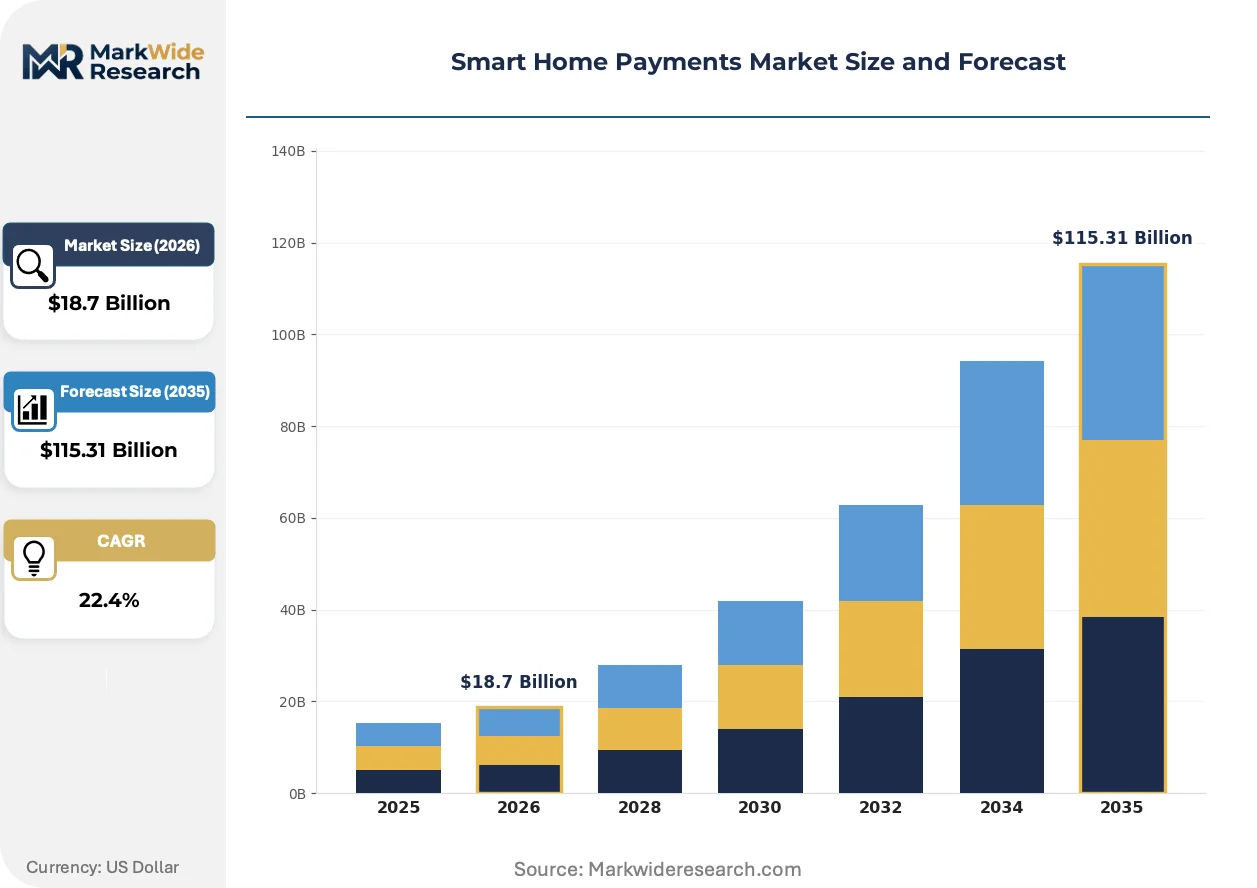
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Digital Wallet, Bank Transfer, Mobile Payment Device Type: Smart Speakers, Smart Thermostats, Smart Lights, Security Systems Transaction Size: Micro transactions, Small transactions, Medium transactions, Large transactions User Demographics: Millennials, Families, Retirees, Tech Enthusiasts |
| Companies Covered | Samsung Electronics, Visa, Amazon, Alibaba Group, Mastercard, Google, PayPal, Tencent Holdings, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Payments Market Strategic Shifts
Payment credential storage is migrating from cloud vaults to device-secure elements, compressing attack surfaces while complicating key rotation and revocation workflows across fragmented hardware ecosystems.
Tokenization hardware is miniaturizing to fit within constrained IoT form factors without sacrificing cryptographic strength. Smart appliance manufacturers are embedding these modules directly into refrigerator control boards and television chipsets. This compression is miniaturizing the distinction between payment terminal and everyday household object, enabling grocery replenishment and subscription management without phone or card presentation.
The FTC's scrutiny of voice commerce data collection is forcing explicit consent architectures for transaction audio recording and biometric retention. Device manufacturers must now implement granular permission layers that separate payment authentication from marketing data harvesting. Smart speaker platforms in the United States are responding with isolated processing enclaves that limit data egress to tokenized transaction confirmations only.
Consumers are abandoning card-on-file setups in favor of device-native credential storage that eliminates recurring re-authentication. Digital wallet providers are disintermediating traditional banking applications by pre-positioning payment authority at the point of household need. This behavioral pivot is most pronounced in China, where super-app payment habits are translating directly to appliance-embedded transaction initiation.
Smart Home Payments Market Segmentation
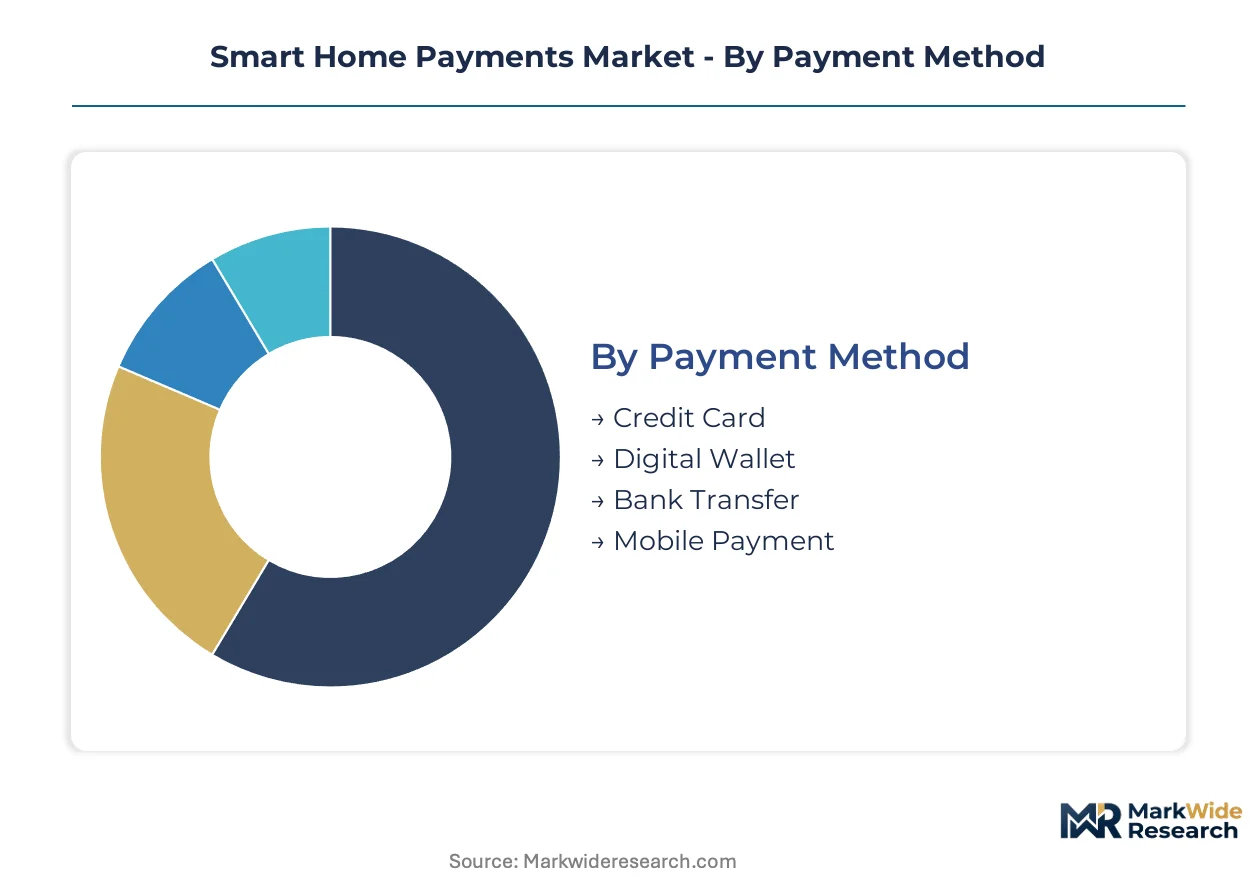
Segmentation in smart home payments reveals how transaction value pools shift across authentication methods, device interfaces, and household purchasing patterns. Understanding these divisions exposes where hardware manufacturers, payment networks, and platform operators compete for credential placement and recurring revenue capture.
Payment Method:
Margin concentration flows toward methods that minimize authentication friction while maintaining tokenization security compliance.
- Digital Wallet:Credentials reside in device-secure elements rather than cloud vaults, enabling one-tap replenishment on Samsung refrigerators and LG televisions. Demand clusters in China where super-app payment habits translate directly to appliance-embedded initiation, driven by consumer abandonment of card-on-file re-authentication.
- Mobile Payment:NFC-enabled smartphone proximity triggers dominate grocery restocking and energy refill scenarios in the United States. High-frequency household expenditure automation favors this method where biometric phone unlock substitutes for repeated password entry.
- Credit Card:Tokenized PAN data flows through Visa's credential layer for IoT endpoints with minimal user interaction.
- Bank Transfer:Direct account debits support utility bill aggregation by property managers in Germany's smart building retrofit wave.
The dominant share belongs to Digital Wallet, while Mobile Payment is closing the gap fastest.
Device Type:
Volume origination skews toward ambient interfaces that eliminate screen-based authentication steps entirely.
- Smart Speakers:Voice commerce pulls transaction origination out of banking applications into ambient home environments. Alexa and Google Home platforms process the highest transaction counts in the United States, constrained by FTC scrutiny forcing explicit consent architectures for biometric audio retention.
- Security Systems:Integrated insurance and monitoring payment bundles attach to residential surveillance hardware, generating recurring revenue at premium margins. Demand concentrates in Germany where federal energy efficiency regulations drive connected HVAC replacements with embedded financial capability.
- Smart Thermostats:Automated energy refill triggers execute when usage thresholds breach pre-set balances.
- Smart Lights:Subscription management for bulb replacement and scene service tiers operates on minimal transaction values.
Smart Speakers command transaction volume leadership, though Security Systems are climbing the fastest on margin expansion.
Transaction Size:
Authentication protocol costs and fraud liability scale inversely with transaction value, compressing margins on the smallest transfers.
- Micro transactions:Sub-dollar replenishment for detergent pods, coffee capsules, and printer ink operates on biometric voiceprint protocols with minimal friction. Mastercard's authentication standards reduce step count for these high-frequency triggers in connected appliance scenarios.
- Small transactions:Grocery restocking and energy refills between $10-50 dominate smart refrigerator and thermostat use cases. Demand concentrates in United States suburban households where automated scheduling protocols reduce purchase decision fatigue.
- Medium transactions:Appliance service subscriptions and insurance bundling span $50-200 authorization thresholds.
- Large transactions:HVAC replacement and major home upgrade financing require stepped-up authentication beyond ambient device capability.
Micro transactions hold the dominant share, with Small transactions gaining ground fastest on replenishment automation adoption.
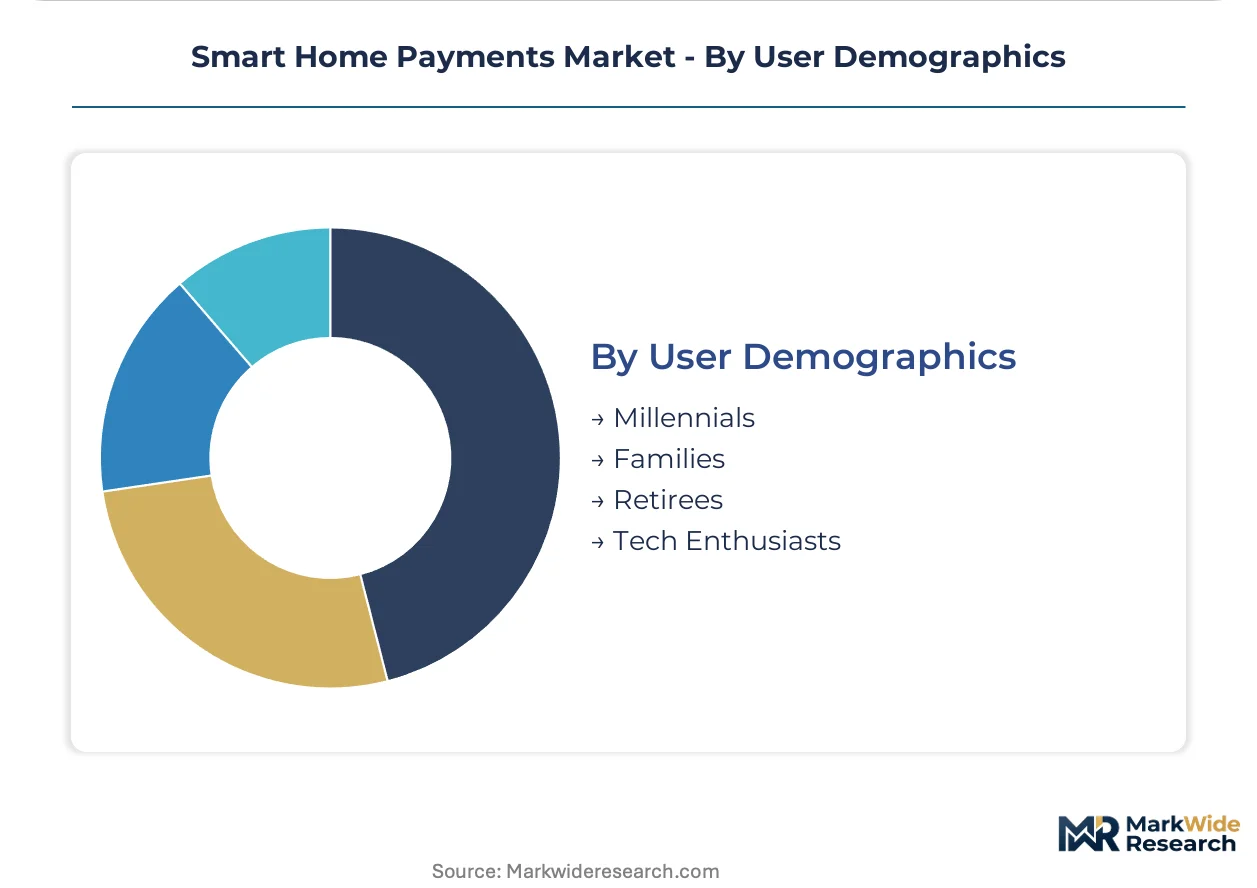
User Demographics:
Technology comfort and household expenditure automation willingness segment the addressable market by age and family structure.
- Families:Multi-person households with predictable consumption patterns drive refrigerator-initiated grocery replenishment and subscription management. Demand concentrates in United States and China where integrated smart home ecosystems embed financial infrastructure across appliance categories.
- Tech Enthusiasts:Early adopters tolerate beta authentication flows and edge computing gateway configurations for latency reduction. This cohort pilots device-native credential storage before mass-market rollout.
- Millennials:First-time homeownership correlates with smart device installation and payment method experimentation.
- Retirees:Voice-first interfaces reduce screen navigation burden, though fraud vulnerability concerns limit transaction size comfort.
Families represent the dominant share, while Tech Enthusiasts are expanding most quickly as authentication friction diminishes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains the densest fiber-optic backbone infrastructure supporting smart home device connectivity, enabling real-time payment processing across 90 million connected households. China's national broadband strategy underwrites the largest single-country deployment of IoT payment endpoints. Germany's district heating network interconnections create embedded finance opportunities at the building infrastructure level.
United States
Suburban household automation drives refrigerator-initiated grocery replenishment and thermostat-triggered energy refills. The FTC scrutinizes voice commerce data collection practices, forcing explicit consent architectures for biometric audio retention. Seattle and San Francisco anchor smart speaker platform development, with payment credential storage migrating to device-secure elements.
China
Super-app payment habits translate directly to appliance-embedded transaction initiation across 400 million connected homes. The MIIT mandates IoT security certification for networked payment devices, accelerating token vault adoption among hardware manufacturers. Shenzhen's electronics manufacturing clusters produce miniaturized secure elements for television and refrigerator control boards.
Germany
Federal energy efficiency regulations drive connected HVAC replacements with embedded financial capability in 12 million residential units. The EBA's PSD2 strong customer authentication rules create compliance thresholds favoring established token vault providers. Munich and Stuttgart concentrate smart building retrofit activity, with property managers aggregating tenant payment flows through integrated platforms.
United Kingdom
Voice-first interfaces reduce screen navigation burden for aging demographics adopting smart home payment systems. The FCA enforces open banking standards that facilitate third-party payment initiation through connected devices. London's fintech corridor hosts tokenization service providers serving European IoT endpoint manufacturers.
Japan
Appliance manufacturers embed payment modules into toilet and bathing systems for automated supply replenishment. METI promotes interoperability standards for home gateway transaction processing. Osaka's industrial electronics sector supplies cryptographic hardware for constrained IoT form factors.
Smart Home Payments Market Competitive Environment
Concentration sits with technology conglomerates and payment networks that control credential tokenization and device-secure element standards. The market structure divides between hardware-integrated platform operators and financial infrastructure providers. Three archetypes dominate: consumer electronics manufacturers embedding payment capability into appliance installed bases, payment networks anchoring token vault and authentication protocols, and voice platform operators originating transaction volume through ambient interfaces. Competitive moves center on strategic partnerships between device manufacturers and payment networks, plus geographic expansion of appliance-embedded payment certification programs.
Within the payment network tier, Visa and Mastercard occupy positions defining tokenization architecture for IoT endpoints with minimal user interaction. Samsung Electronics exemplifies the hardware-integrated archetype, leveraging smart appliance installed bases to embed payment credentials directly into refrigerator and television interfaces. Amazon represents the voice platform operator archetype, with Alexa processing the highest transaction counts in ambient home environments.
| Leading Market Players |
|---|
| Samsung Electronics |
| Visa |
| Amazon |
| Alibaba Group |
| Mastercard |
| PayPal |
| Tencent Holdings |
| Apple |
| Others |
Value Chain & Pricing Dynamics
Long-term token vault service contracts lock in both secure element supply access and authentication pricing visibility for smart appliance manufacturers navigating PCI DSS certification cycles. These multi-year agreements tether hardware vendors to established payment networks while insulating transaction processing costs from spot-market volatility in cryptographic chip supply.
Pricing Analysis
Volume-discount tiering structures separate enterprise appliance OEMs with million-unit annual shipments from mid-tier device manufacturers and niche gateway producers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and embedded security module performance tiers. Pricing pressure stems from hyperscale cloud providers exercising routing economics leverage over IoT transaction processing. Mid-tier manufacturers exhibit highest price sensitivity due to limited security expertise and certification overhead absorption capacity.
Supply Chain Analysis
Inventory lead times for FIPS-certified secure elements extend substantially when demand spikes coincide with smart building retrofit waves in Germany and federal energy efficiency mandates. Taiwan, South Korea, and China concentrate semiconductor fabrication for constrained IoT form factors. Raw material dependencies center on silicon wafers, cryptographic coprocessors, and NFC antenna substrates. Single-source vulnerability concentrates in advanced node secure element foundry capacity. Distribution runs through tier-one electronics manufacturing services aggregating component procurement for appliance OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward property managers and utility service providers consolidating tenant payment flows, fragmenting individual consumer bill-pay influence over platform economics.
For Market Incumbents: Consolidate token vault partnerships with payment networks to defend credential placement against emerging biometric authentication entrants. Deepen backward integration into secure element design to reduce hyperscale cloud dependency for transaction routing. Lock in long-term appliance OEM certification programs before PSD2 compliance thresholds favor established providers.
For New Entrants and Emerging Players: Edge computing gateway configuration services present an underserved layer where incumbents under-serve mid-tier device manufacturers lacking firmware security expertise. Germany's smart building retrofit wave offers the most penetrable geography for localized transaction processing solutions. Pursue channel partnerships with property management platforms aggregating embedded finance opportunities at building infrastructure level.
For Investors and Strategic Acquirers: Capital is best deployed toward biometric authentication protocol specialists with algorithmic transparency architectures satisfying regulator scrutiny. Long-term viability hinges on compliance automation capabilities spanning multi-jurisdiction certification timelines. Watch FTC consent decree patterns as inflection indicators for voice commerce data collection liability exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Token Vault Partnership Expansion | Visa and Mastercard credential layer anchoring secures IoT endpoint placement for appliance OEMs. |
| Secure Element Miniaturization R&D | Samsung and LG refrigerator control board integration demands constrained form factor cryptographic modules. |
| Biometric Authentication Protocol Development | Mastercard's voiceprint standards reduce friction for high-frequency micro transactions in connected homes. |
| Edge Computing Gateway Deployment | Local transaction processing reduces latency and cloud dependency for time-sensitive replenishment triggers. |
| Property Management Platform Integration | Utility service provider consolidation creates embedded finance opportunities at building infrastructure level. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across smart appliance manufacturers, payment network tokenization specialists, property management platform operators, and voice commerce platform engineers. Primary fieldwork combined with secondary validation from PCI Security Standards Council compliance documentation, Federal Trade Commission consent decree records, European Banking Authority PSD2 implementation reports, and smart home device certification databases. Bottom-up shipment modeling and top-down payment volume triangulation anchored market sizing.
Across the analysis window, forecasts derived from segment-level authentication protocol adoption curves, device shipment projections by OEM, and transaction frequency assumptions by household type. Segmentation dimensions modeled include payment method credential storage architecture, device type interface category, transaction size tier, and regional regulatory cluster. CAGRs computed from year-over-year payment volume expansion rates adjusted for authentication friction reduction coefficients and smart home penetration trajectories.
Underlying assumptions cover PSD2 strong customer authentication enforcement continuity and biometric standardization timeline convergence, with deviation risk concentrated in FTC algorithmic transparency rulemaking and voice spoofing liability insurance pricing volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India POS Terminals Market
Payments
E-Wallet Market
Payments
India Gift Card and Incentive Card Market
Payments
Japan Mobile Payments Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
Global Real-Time Payments Market
Payments
Digital Transaction Management Market
Payments
Digital Payment Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
United States Clearing Houses and Settlements Market
Payments
Saudi Arabia Payments Market
Payments
Canada Payment Gateway Market
Payments
Spain Mobile Payment Market
Payments
Malta POS Terminal Market
Payments
Spain POS Terminals Market
Payments
Instant Payments Market