
 Europe Virtual Cards Market | 2026-2036
Europe Virtual Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Virtual Cards Market Foresight
Corporate procurement and travel expense management is shifting toward single-use and subscription-locked virtual card products across Europe. Revolut Limited leverages its multi-currency infrastructure to anchor corporate card issuance in the United Kingdom and Ireland. Marqeta Inc. competes through API-first card program management that lets European fintechs customize spend controls. Adyen N.V. dominates unified payment acceptance, extending virtual issuance capabilities to enterprise merchants operating across eurozone markets.
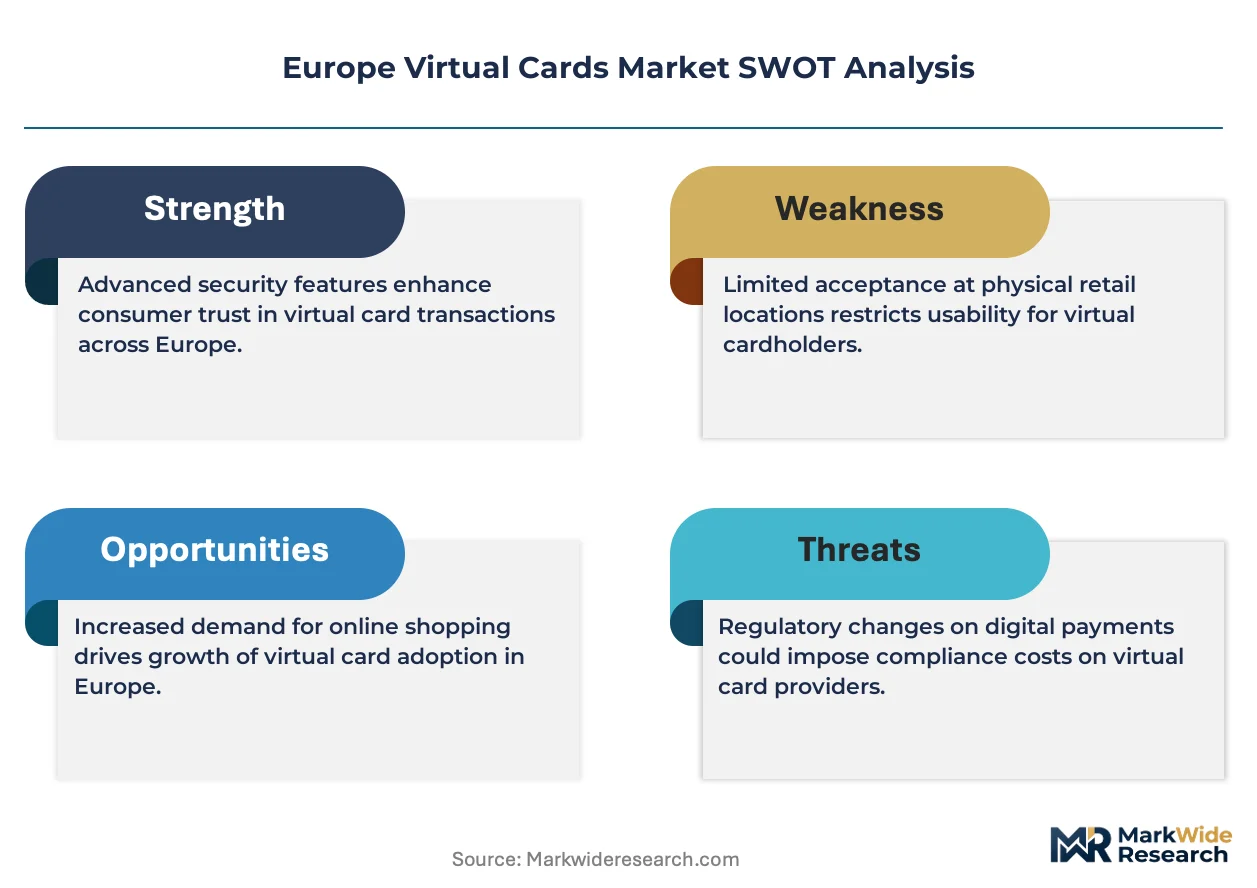
Europe virtual cards are digitally generated payment credentials with unique sixteen-digit numbers, expiration dates, and CVV codes, typically issued via tokenized APIs with real-time authorization limits and merchant category restrictions. They serve primarily to reduce fraud exposure in online transactions and enable granular spend governance for corporate treasuries. Credit cards and prepaid cards lead transaction volume, though corporate cards represent the fastest-expanding margin pool as enterprises replace traditional purchasing cards with API-managed virtual alternatives. B2B platforms and mobile apps are displacing retail distribution for new account origination, while fraud detection and two-factor authentication have become baseline security requirements rather than differentiators.
PSD2 strong customer authentication mandates from the European Banking Authority, GDPR data residency rules, and the EU AI Act's risk classification framework collectively shape product architecture and cross-border data handling for issuers. The European Central Bank's digital euro exploration adds uncertainty to long-term virtual card utility in retail payments. Stakeholders must monitor regulatory divergence between EU member states on open banking implementation timelines and decide whether to centralize issuance licenses or maintain fragmented national programs.
Market Dynamics
PSD2 strong customer authentication mandates from the European Banking Authority are compressing transaction authorization windows while simultaneously expanding tokenized credential issuance volumes across the continent.
Growth Catalysts
- GDPR data residency frameworks:Tokenization architectures that localize cardholder data within EU borders satisfy cross-border data handling requirements while enabling seamless multi-country program deployment.
- Corporate travel management:Enterprise procurement teams are replacing physical purchasing cards with API-managed virtual alternatives that enforce merchant category codes and real-time spend ceilings.
- Germany:The country's dense concentration of automotive and industrial exporters generates sustained demand for multi-currency virtual card infrastructure supporting supplier payments across eurozone and non-eurozone markets.
Market Restraints
- Issuance license fragmentation:National banking regulators in France, Italy, and Spain maintain divergent capital reserve requirements for electronic money institutions, forcing program managers to maintain multiple legal entities.
- Interchange fee compression:The EU Interchange Fee Regulation caps debit transaction revenue at 0.20 percent, constraining margin expansion for virtual card products positioned as low-cost alternatives.
- Central bank digital currency substitution:The European Central Bank's digital euro exploration introduces long-term utility uncertainty for retail-facing virtual card products.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated SME segments in these markets present first-mover advantages for fintechs offering embedded virtual card issuance through accounting software integrations.
- Subscription-locked credentials:Recurring payment authorization tools that auto-generate single-use numbers for each billing cycle address merchant data breach anxiety in streaming and SaaS verticals.
- CSRD sustainability reporting:The Corporate Sustainability Reporting Directive creates procurement transparency mandates that virtual card transaction data satisfies through automated carbon footprint allocation.
Industry Challenges
- SCA implementation complexity:PSD2-compliant two-factor authentication flows introduce checkout friction that merchants address through exemption routing strategies requiring sophisticated risk engine calibration.
- Legacy core banking integration:Established financial institutions struggle to retrofit mainframe-based card management systems with real-time API credential generation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Virtual Cards Market |
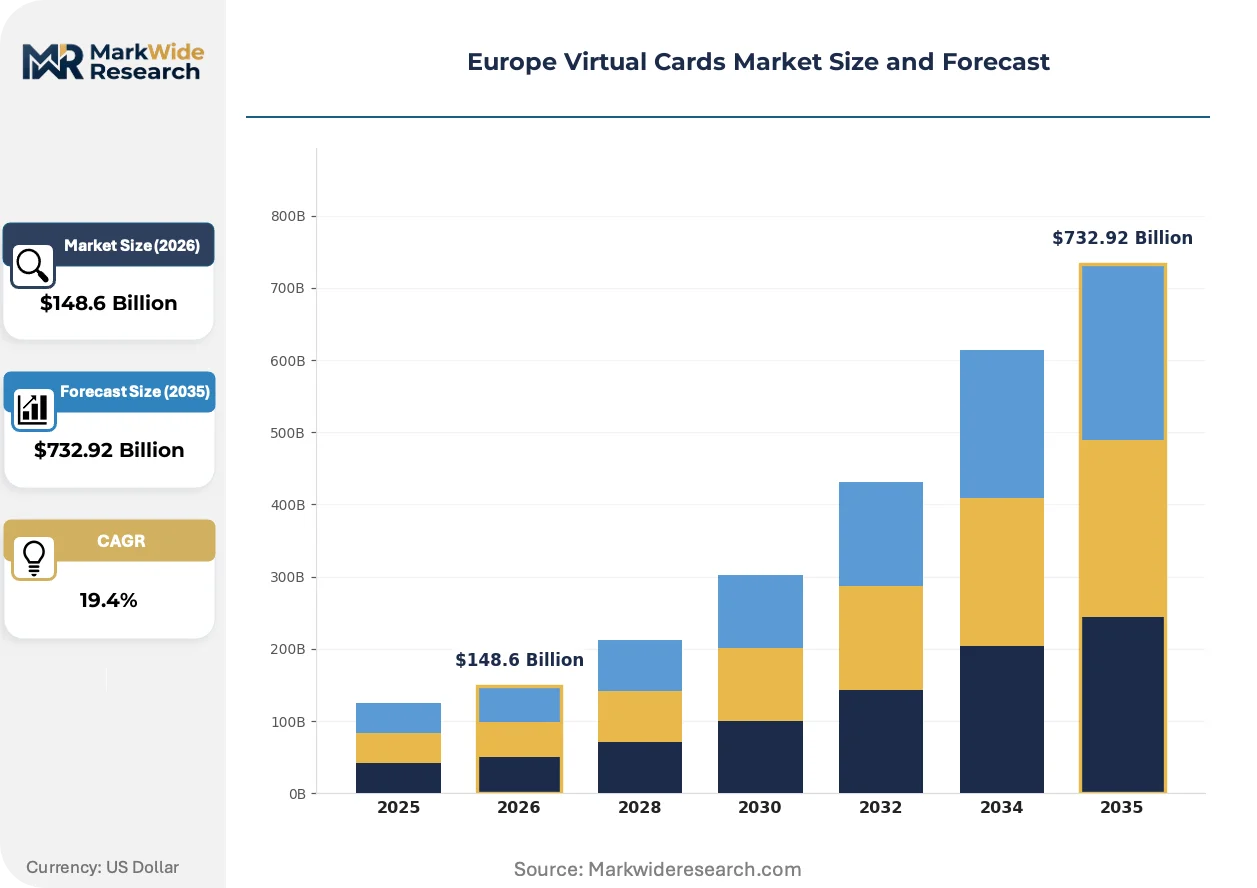
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $732.92 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Debit Cards, Prepaid Cards, Corporate Cards Industry Type: E-commerce, Travel, Food Services, Gaming Distribution Channel: Online, Mobile Apps, Retail, B2B Platforms Security Features: Fraud Detection, Two-Factor Authentication, Encryption, Virtual Account Numbers |
| Companies Covered | Revolut Limited, Klarna Holding AB, Marqeta Inc., Adyen N.V., bunq B.V., Monese Limited, WEX Inc., Qonto, N26 GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Virtual Cards Market Shifts & Advancements
Machine learning risk scoring is compressing authorization latency while expanding the transaction types eligible for virtual card coverage across European payment networks.
Dynamic CVV2 generation technology refreshes security codes at 30-minute intervals for high-value transactions. E-commerce merchants in the United Kingdom and Netherlands are adopting this capability fastest, with fashion retail and electronics verticals leading integration. Real-time credential rotation is automating fraud exposure reduction without requiring customer device changes.
The EU AI Act's risk classification framework subjects high-volume virtual card authorization engines to conformity assessment requirements. Issuers must document algorithmic decision-making transparency for credit-limit adjustments and transaction blocking. Automated underwriting systems serving cross-border B2B programs face the steepest compliance burden.
Enterprise treasury teams are consolidating supplier payment instruments onto platform-issued virtual cards with embedded spend analytics. Procurement departments in Germany and France are displacing traditional purchasing card programs with API-managed alternatives that feed directly into ERP reconciliation workflows. This instrument consolidation is most visible among mid-market manufacturing exporters with 500-plus supplier relationships.
Europe Virtual Cards Market Segmentation
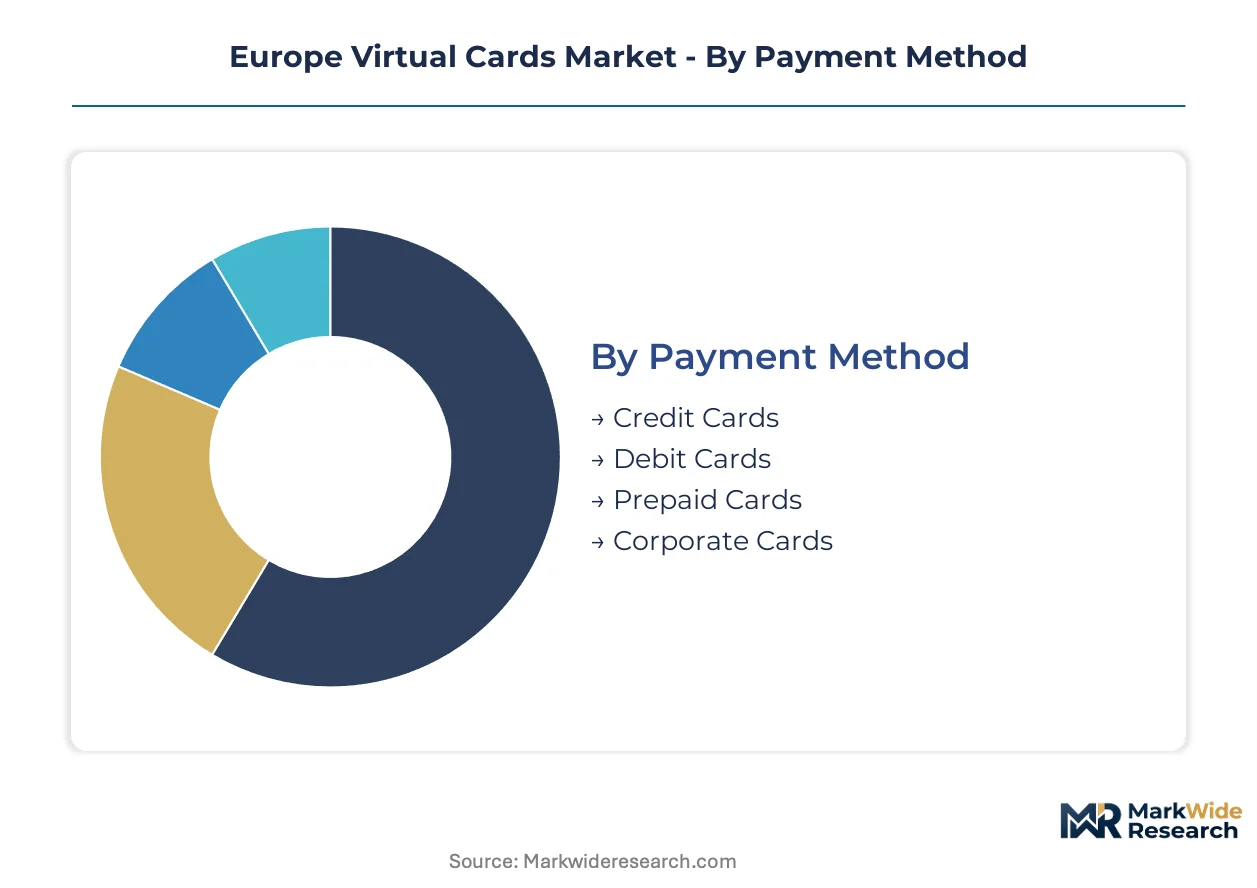
Virtual card architectures diverge sharply across payment rails, end-use contexts, and security postures. Issuers configure credential generation parameters, authorization logic, and data handling protocols differently for each segment combination.
Payment Method:
Card type determines liability frameworks, interchange economics, and API integration complexity for European issuers.
- Credit Cards:Revolving credit lines with 30-45 day billing cycles dominate high-value B2B procurement in Germany and France. Corporate treasuries exploit grace period float while enforcing merchant category restrictions through programmable spend controls.
- Corporate Cards:API-managed credentials with embedded ERP reconciliation are displacing traditional purchasing card programs among mid-market exporters. Real-time spend ceilings and supplier-specific virtual numbers reduce fraud exposure in multi-entity supply chains.
- Debit Cards:Direct account linkage with immediate settlement suits consumer subscription management and low-value digital goods purchases.
- Prepaid Cards:Fixed-balance credentials serve gift card distribution and temporary worker expense allowances without credit risk exposure.
Credit cards lead on scale; corporate cards lead on momentum.
Industry Type:
Vertical-specific transaction patterns dictate authorization velocity requirements and fraud model calibration.
- E-commerce:High-velocity checkout environments in the United Kingdom and Netherlands demand sub-200ms authorization latency. Dynamic CVV2 rotation at 30-minute intervals reduces card-not-present fraud without device dependency.
- Travel:Multi-currency supplier payments across eurozone and non-eurozone markets require automated FX hedging embedded in virtual issuance APIs. German automotive and industrial exporters generate sustained demand for cross-border credential programs.
- Food Services:Low-margin, high-frequency delivery app transactions prioritize interchange cost minimization over feature depth.
- Gaming:Micropayment aggregation and parental spend controls drive prepaid virtual credential adoption.
E-commerce captures transaction volume concentration; travel commands premium pricing power.
Distribution Channel:
Customer acquisition economics shift dramatically across origination pathways, with platform embedding displacing direct distribution.
- B2B Platforms:Accounting software and procurement system integrations in Poland and the Czech Republic enable embedded issuance with zero marginal customer acquisition cost.
- Mobile Apps:Neobank interfaces with biometric authentication dominate consumer virtual card origination in Ireland and the United Kingdom.
- Online:Traditional web-based onboarding retains relevance for corporate treasury platforms requiring multi-user approval workflows.
- Retail:Physical distribution of prepaid virtual credentials persists in Southern European markets with lower smartphone penetration.
B2B platforms gain share fastest; mobile apps retain volume leadership.
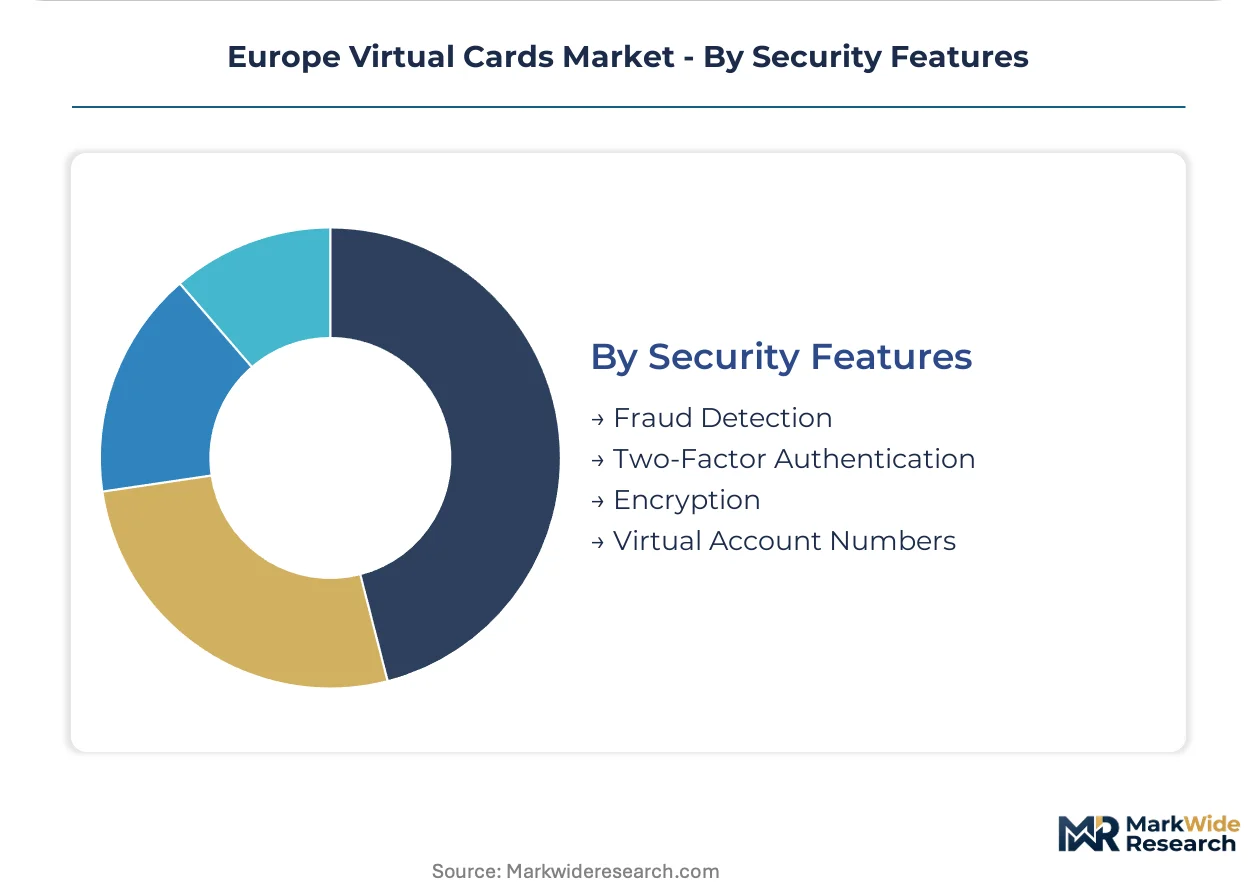
Security Features:
Regulatory mandates from the European Banking Authority and the EU AI Act stratify compliance investment across authentication architectures.
- Two-Factor Authentication:PSD2 strong customer authentication mandates compress transaction authorization windows while expanding tokenized credential issuance. Exemption routing strategies require sophisticated risk engine calibration to minimize checkout friction.
- Fraud Detection:Machine learning risk scoring compresses authorization latency while expanding eligible transaction types. The EU AI Act subjects high-volume authorization engines to conformity assessment requirements for algorithmic transparency.
- Encryption:Tokenized data residency within EU borders satisfies GDPR cross-border handling requirements.
- Virtual Account Numbers:Single-use credential generation for specific merchants or transaction amounts limits breach exposure.
Two-factor authentication is mandatory baseline; fraud detection commands R&D investment priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's financial technology corridor anchors European virtual card issuance volume, drawing API-first program managers and neobank infrastructure into concentrated regulatory sandbox environments. Continental demand fragments across national banking licenses and divergent open banking maturity curves.
Germany
Automotive supplier networks and industrial exporters in Baden-Württemberg and Bavaria drive multi-currency virtual card adoption for cross-border procurement. The Federal Financial Supervisory Authority enforces strict electronic money institution capital requirements that favor established banking groups over fintech entrants. Frankfurt's concentration of treasury management platforms accelerates ERP-embedded virtual issuance among mid-market manufacturers.
United Kingdom
Neobank consumer onboarding and corporate expense management tools dominate issuance growth in Greater London and the South East. The Financial Conduct Authority's open banking implementation timeline exceeds EU PSD2 standards, creating regulatory arbitrage for UK-domiciled program managers. Revolut Limited leverages its multi-currency infrastructure to anchor corporate card distribution across British and Irish enterprise segments.
France
Luxury goods exporters and aerospace subcontractors in Île-de-France generate demand for supplier-locked virtual credentials with automated FX hedging. The Autorité de Contrôle Prudentiel et de Résolution maintains conservative licensing timelines that slow fintech market entry relative to neighboring jurisdictions. Paris-based procurement platforms are displacing traditional purchasing card programs with API-managed alternatives.
Netherlands
E-commerce merchants in Amsterdam and Rotterdam adopt dynamic CVV2 rotation fastest among European markets, prioritizing sub-200ms authorization latency. The Dutch Central Bank's early PSD2 enforcement created mature tokenization infrastructure that supports seamless cross-border program deployment. Eindhoven's electronics retail verticals lead merchant integration of real-time credential refresh capabilities.
Poland
Underpenetrated SME segments in Warsaw and Kraków present embedded issuance opportunities through accounting software integrations. The Polish Financial Supervision Authority's alignment with EU electronic money directives enables passportable licensing for regional program expansion. Local fintechs exploit lower customer acquisition costs via platform-embedded virtual card origination.
Europe Virtual Cards Market Competitive Landscape
Strategic partnership formation dominates the current landscape as program managers seek banking license coverage across fragmented national regulatory regimes. The vendor base stratifies into three tiers: full-stack neobanks with proprietary issuance infrastructure, API-first platform providers enabling white-label deployment, and legacy processors retrofitting core systems for real-time credential generation. Competitive positioning depends on open banking integration depth and multi-currency settlement velocity. M&A activity concentrates on electronic money institution license acquisition, while technology licensing agreements accelerate time-to-market for regional entrants.
Within the neobank tier, Revolut Limited and N26 GmbH exemplify vertically integrated issuance models that control customer acquisition and credential generation within unified technology stacks. Marqeta Inc. and Adyen N.V. occupy distinct positions as infrastructure enablers, supplying API-first card program management to European fintechs and enterprise merchants respectively. These four entities represent divergent strategic archetypes: consumer-facing digital banking, B2B platform embedding, developer-centric infrastructure provision, and unified payment acceptance extension.
| Leading Market Players |
|---|
| Revolut Limited |
| Klarna Holding AB |
| Marqeta Inc. |
| Adyen N.V. |
| bunq B.V. |
| Monese Limited |
| WEX Inc. |
| Qonto |
| N26 GmbH |
| Others |
Supply & Pricing Matrix
Interchange fee benchmarks set by the EU Interchange Fee Regulation cascade through European virtual card issuance, compressing debit transaction economics to 0.20 percent and forcing program managers to differentiate through API value-adds rather than transaction spreads. This regulatory price ceiling reshapes tier structures across the continent, pushing revenue models toward subscription SaaS tiers and embedded platform fees.
Pricing Analysis
Input-cost pass-through from tokenization infrastructure and PSD2 compliance investments flows into three-tier pricing structures across premium, standard, and economy levels. Price differentiation hinges on API call volume thresholds and real-time FX hedging inclusion, with German automotive exporters showing lowest price sensitivity due to embedded treasury cost absorption. Pricing pressure stems from neobank zero-fee positioning in consumer segments, while corporate procurement teams in France and the Netherlands negotiate platform-embedded issuance at volume-scaled rates.
Supply Chain Analysis
Warehouse-distribution layer concentration in Frankfurt, London, and Amsterdam anchors European virtual card program deployment, with regional data centers satisfying GDPR residency requirements. Token generation infrastructure draws from cloud compute providers, banking-as-a-service licensure, and specialized fraud detection APIs. Single-source vulnerability concentrates in core banking processor relationships, particularly for legacy institutions retrofitting mainframe systems. Distribution runs through B2B platform integrations and neobank mobile apps, displacing traditional retail origination channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's virtual card market functions as a geographic-arbitrage play where the United Kingdom's accelerated open banking timeline creates regulatory cost advantages against continental PSD2 implementation lags, enabling UK-domiciled program managers to capture cross-border issuance volume.
For Market Incumbents: Anticipate central bank digital currency displacement by deepening API platform moats around ERP reconciliation workflows. Defensive consolidation should prioritize electronic money institution license acquisition in Poland and the Czech Republic to preempt fintech platform embedding. Vertical integration into tokenization infrastructure reduces third-party processor dependency.
For New Entrants and Emerging Players: Capture underpenetrated SME segments in Warsaw and Kraków through accounting software integrations that eliminate customer acquisition costs. White-space concentration sits with subscription-locked credential products for streaming and SaaS verticals. Go-to-market execution should anchor in embedded issuance partnerships with procurement platforms serving mid-market manufacturing exporters.
For Investors and Strategic Acquirers: Asymmetric upside sits with API-first infrastructure providers holding multi-country banking license coverage. Long-term viability favors firms with demonstrated PSD2 compliance automation and machine learning authorization engines subject to EU AI Act conformity pathways. Watch ECB digital euro pilot announcements as inflection signals for retail virtual card utility compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Money Institution License Acquisition | Multi-country regulatory coverage reduces fragmentation costs for cross-border program deployment. |
| API-First Platform Integration | Embedded issuance through accounting software displaces direct customer acquisition in underpenetrated markets. |
| Dynamic CVV2 Technology Deployment | Real-time credential rotation addresses merchant fraud anxiety in UK and Netherlands e-commerce verticals. |
| ERP Reconciliation Workflow Embedding | Treasury platform consolidation among German manufacturers drives corporate card program displacement. |
| GDPR-Compliant Data Residency Architecture | Tokenized EU-border localization satisfies cross-border handling requirements for multi-country issuance. |
Research Methodology
Coverage spans Western Europe, Central Europe, and the British Isles, with primary inputs from each regional cluster combined with secondary validation. Primary research incorporated program managers at neobanks and API-first infrastructure providers, corporate treasury directors at mid-market exporters, regulatory affairs leads at electronic money institutions, and procurement platform engineers. Secondary sources included ECB payment statistics, BaFin electronic money licensing disclosures, FCA open banking implementation reports, and EU AI Act conformity assessment documentation. Bottom-up transaction volume modeling triangulated against top-down market sizing from banking association aggregates.
Granularity-level modeling deployed payment method, industry vertical, distribution channel, and security feature dimensions at country-level resolution across the analysis window. CAGRs derived from regression analysis of historical issuance volume against corporate travel recovery trajectories and B2B platform adoption curves. Forecast inputs incorporated PSD2 strong customer authentication implementation timelines and GDPR enforcement patterns by national regulator.
ECB digital euro policy shifts, divergent national open banking maturity curves, and EU AI Act algorithmic transparency enforcement are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
United Arab Emirates Payment Market
Payments
Canada POS Terminal Market
Payments
North America Payment Analytics Software Market
Payments
Netherlands Mobile Payments Market
Payments
United Kingdom Mobile Payments Market
Payments
Direct Carrier Billing Platform Market
Payments
Outdoor Payment Terminal Market
Payments
Australia Mobile Payment Market
Payments
Smart Home Payments Market
Payments
Argentina Mobile Wallet Market
Payments
South Korea Real Time Payments Market
Payments
China Virtual Cards Market
Payments
Romania POS Terminals Market
Payments
Gift Card and Incentive Card Market
Payments
Consumer Mobile Payment Market
Payments
Fuel Cards Market