
 Biometric Payment Cards Market | 2026-2036
Biometric Payment Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Payment Cards Market Intelligence
France is rewriting the competitive map for biometric card manufacturing through Thales Group's advanced semiconductor packaging operations. Thales leverages its chip integration expertise to dominate European supply chains. Zwipe sustains technology leadership through its proprietary biometric sensor-on-card platform. Fingerprint Cards AB anchors Nordic R&D intensity with its capacitive fingerprint sensor designs.
Biometric payment cards embed fingerprint sensors directly into the card body, enabling cardholder-authenticated transactions without PIN entry or terminal contact. The primary commercial purpose is to eliminate fraud in card-present environments while preserving the familiar plastic form factor. Dual interface cards are capturing the fastest expansion as they bridge legacy chip infrastructure with contactless acceptance growth. Fingerprint recognition technology leads deployment volumes due to mature sensor miniaturization and proven liveness detection algorithms.
EMVCo, ISO/IEC, and the EU Payment Services Directive shape product certification pathways and market access conditions across issuing jurisdictions. France's CNIL enforces biometric data governance rules that directly affect card enrollment procedures and template storage architectures. Stakeholders must monitor how central bank digital currency pilots intersect with physical card authentication requirements in major issuing economies.
Market Dynamics
Dual-interface biometric cards are compressing the transition timeline from contact chip to contactless authentication across European and Asian issuing banks.
Growth Catalysts
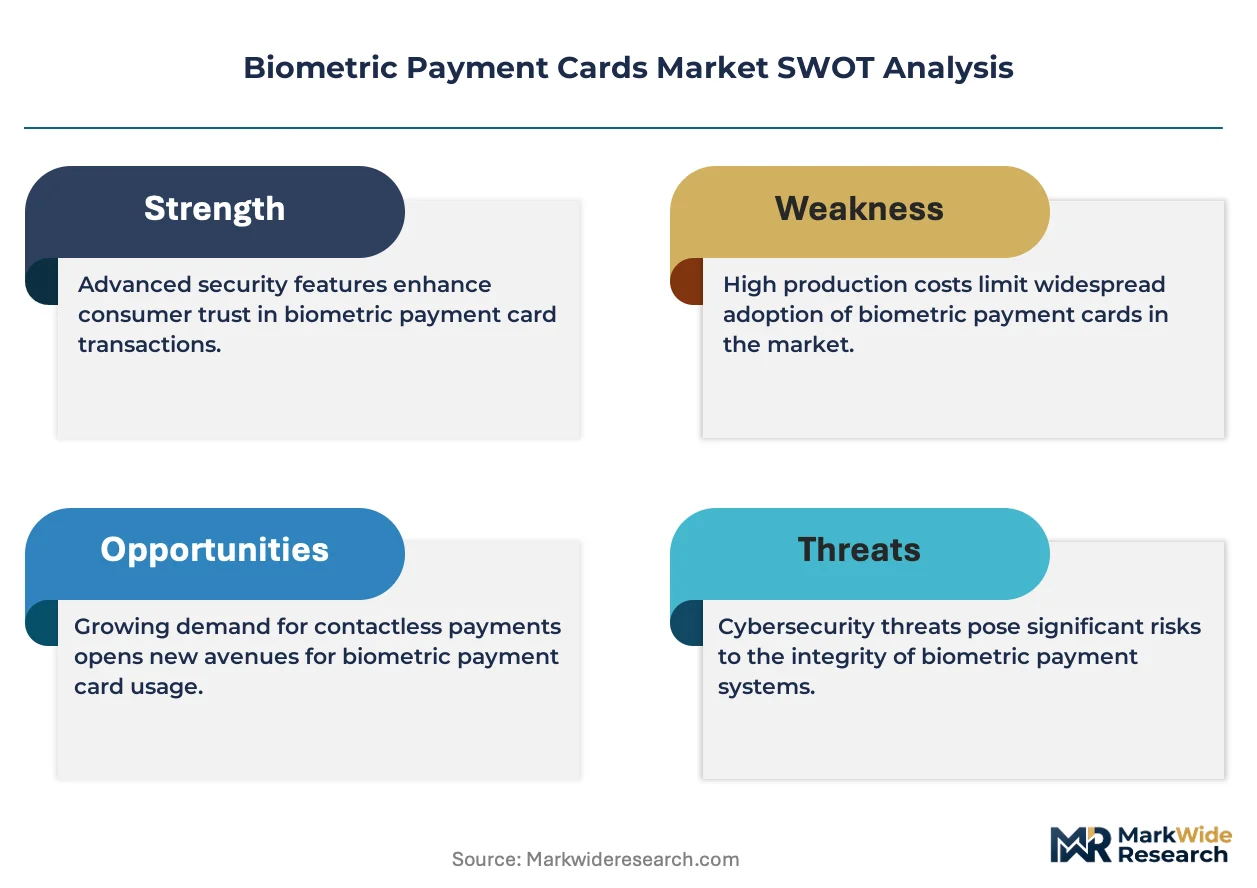
- EMVCo compliance mandates:Certification requirements for biometric card security are accelerating issuer procurement cycles in France and South Korea.
- Contactless transaction volumes:Retail payment infrastructure upgrades in India are creating immediate demand for fingerprint-authenticated cards.
- CNIL biometric governance framework:France's data protection authority is standardizing enrollment procedures that reduce implementation friction for card programs.
Market Restraints
- Semiconductor packaging costs:Fingerprint sensor integration into ISO-compliant card bodies requires specialized die-bonding equipment concentrated in German and French facilities.
- Template storage architecture:On-card biometric template storage demands secure element capacity that increases unit manufacturing complexity.
- Mobile payment substitution:Smartphone-based authentication applications are capturing transaction volume in urban Chinese and Nordic markets.
Strategic Opportunities
- Rural Indian banking penetration:Jan Dhan Yojana financial inclusion programs are converting unbanked populations into biometric card recipients.
- Central bank digital currency convergence:Physical card authentication requirements in European CBDC pilots are creating hybrid product specifications.
- ISO/IEC 15408 certification pathways:Common Criteria evaluation facilities are expanding capacity to reduce time-to-market for new card platforms.
Industry Challenges
- Secure element firmware integration:Biometric sensor communication protocols require specialized embedded systems engineering scarce in traditional card manufacturing.
- Enrollment infrastructure deployment:Bank branch and ATM biometric capture equipment necessitates coordinated hardware and software rollout investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Payment Cards Market |
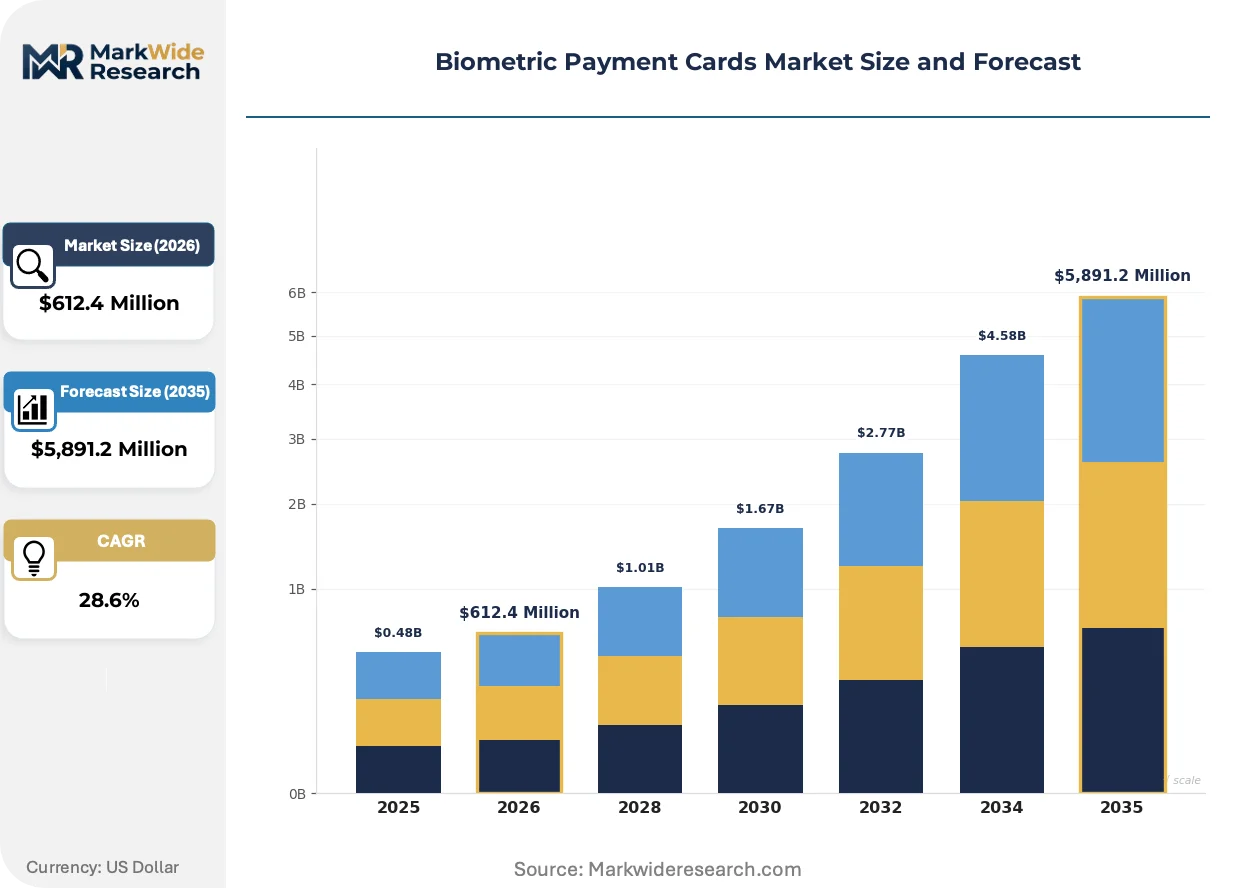
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $5,891.2 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless Cards, Smart Cards, Dual Interface Cards, Chip Cards Technology: Fingerprint Recognition, Facial Recognition, Iris Scanning, Card Authentication Use Case: Retail Payments, Online Transactions, ATM Withdrawals, Access Control End User: Consumers, Financial Institutions, Retailers, Technology Providers |
| Companies Covered | IDEX Biometrics ASA, Zwipe, Thales Group, Visa Inc., Mastercard, Fingerprint Cards AB, Infineon Technologies AG, NXP Semiconductors, IDEMIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Payment Cards Market Strategic Shifts & Innovations
Sensor miniaturization and power harvesting from payment terminals are collapsing the technical barriers that previously constrained biometric card commercialization.
Capacitive fingerprint sensing arrays are digitizing cardholder identity verification by embedding liveness detection directly into the plastic substrate. Tier-one issuers in France and South Korea are deploying these sensors in dual-interface cards at commercial scale. This hardware integration is digitizing the authentication step that previously required PIN entry or signature verification.
GDPR Article 9 biometric data processing rules are tightening consent and storage requirements for European card programs. Issuers must now implement template deletion protocols and purpose limitation documentation. French banks are responding by deploying branch-based enrollment with explicit consent capture rather than remote onboarding.
Merchant acquiring banks are bundling biometric card acceptance certification into terminal upgrade programs. Small-format retail chains in India are replacing magnetic stripe readers with contactless-biometric capable devices. This infrastructure refresh is most visible in Mumbai and Delhi metropolitan payment corridors.
Biometric Payment Cards Market Segmentation
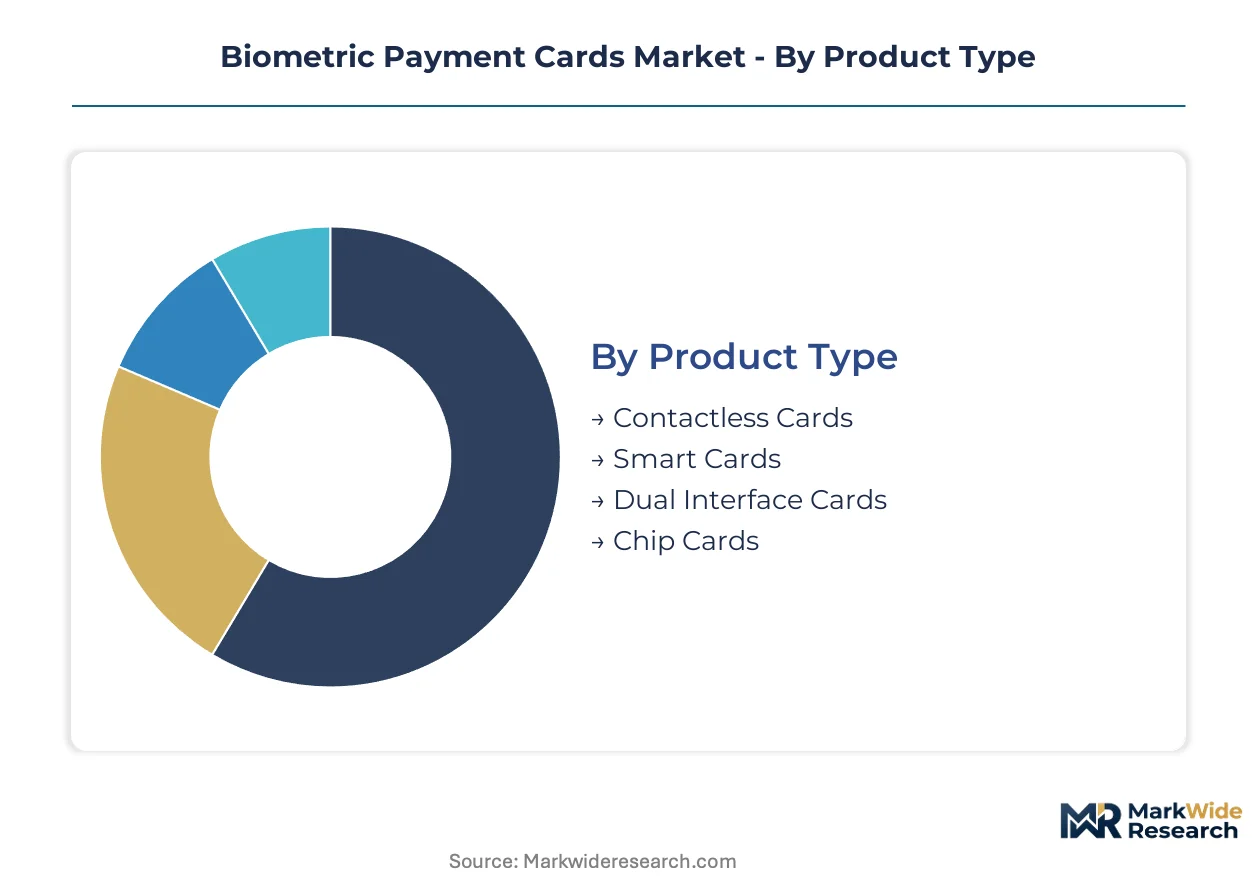
Biometric payment card segmentation reveals how hardware form factors, biometric modalities, transaction environments, and stakeholder economics intersect to shape procurement patterns. Understanding these dimensions exposes where technology investments concentrate and which use cases justify premium unit costs.
Product Type:
The use-case spectrum spans legacy chip infrastructure through fully contactless authentication, with each form factor carrying distinct manufacturing complexity and terminal compatibility requirements.
- Dual Interface Cards:These cards integrate both contact chip and contactless antenna architectures, enabling fallback authentication at legacy terminals while supporting tap-to-pay at modern readers. French and South Korean banks are standardizing on this format for mass issuance programs, as it bridges infrastructure transition periods without forcing merchant hardware upgrades.
- Contactless Cards:Pure contactless biometric cards eliminate physical card insertion entirely, relying on NFC communication with payment terminals and embedded fingerprint sensors for cardholder verification. Indian financial inclusion initiatives are driving volume here, where rural branch networks prioritize speed over backward compatibility.
- Smart Cards:These embed microprocessor chips with secure elements capable of storing biometric templates and executing cryptographic protocols, forming the foundational architecture for all biometric card variants.
- Chip Cards:Traditional EMV chip cards without biometric layers serve as the baseline comparison point and remain relevant in cost-sensitive issuance markets.
The dominant share belongs to Dual Interface Cards, while Contactless Cards are closing the gap fastest.
Technology:
Cost tier differentiation separates mature capacitive fingerprint solutions from emerging optical and multimodal alternatives still seeking manufacturing scale.
- Fingerprint Recognition:Capacitive fingerprint sensors dominate commercial deployments due to proven liveness detection algorithms and established semiconductor packaging supply chains. Thales Group and Fingerprint Cards AB have refined die-bonding processes that integrate these sensors into ISO-compliant card bodies at yields supporting million-unit issuance programs.
- Card Authentication:Template matching algorithms running on secure elements verify cardholder identity without transmitting biometric data off-card, satisfying GDPR Article 9 and CNIL storage requirements for European programs.
- Facial Recognition:Miniaturized camera modules and infrared dot projectors are emerging for high-value transaction scenarios, though power consumption and form factor constraints limit current plastic card integration.
- Iris Scanning:Near-infrared imaging systems remain confined to pilot programs and premium corporate card segments due to component costs and enrollment complexity.
Fingerprint Recognition commands the installed base, though Card Authentication capabilities are expanding most quickly as regulatory compliance hardens.
Use Case:
Application intensity varies sharply across transaction environments, with card-present retail dominating volume while access control commands premium pricing.
- Retail Payments:Point-of-sale biometric authentication eliminates PIN entry friction and reduces terminal contact, driving merchant acquiring banks in India and France to bundle biometric-capable terminal upgrades. Small-format retail chains in Mumbai and Delhi metropolitan corridors are replacing magnetic stripe readers with contactless-biometric devices.
- ATM Withdrawals:Biometric card authentication at cash machines addresses card trapping and shoulder-surfing fraud vectors, with South Korean banks deploying fingerprint-enabled cards across urban ATM networks to reduce cash-out fraud rates.
- Online Transactions:Card-not-present biometric verification requires companion mobile applications or USB readers, creating hybrid authentication workflows that extend card utility into e-commerce.
- Access Control:Corporate and government facilities are adopting biometric payment cards for physical building entry, merging financial and security credentials into single form factors at premium unit economics.
Retail Payments absorbs the highest transaction volume, yet Access Control is climbing the fastest as convergence credentials gain enterprise traction.
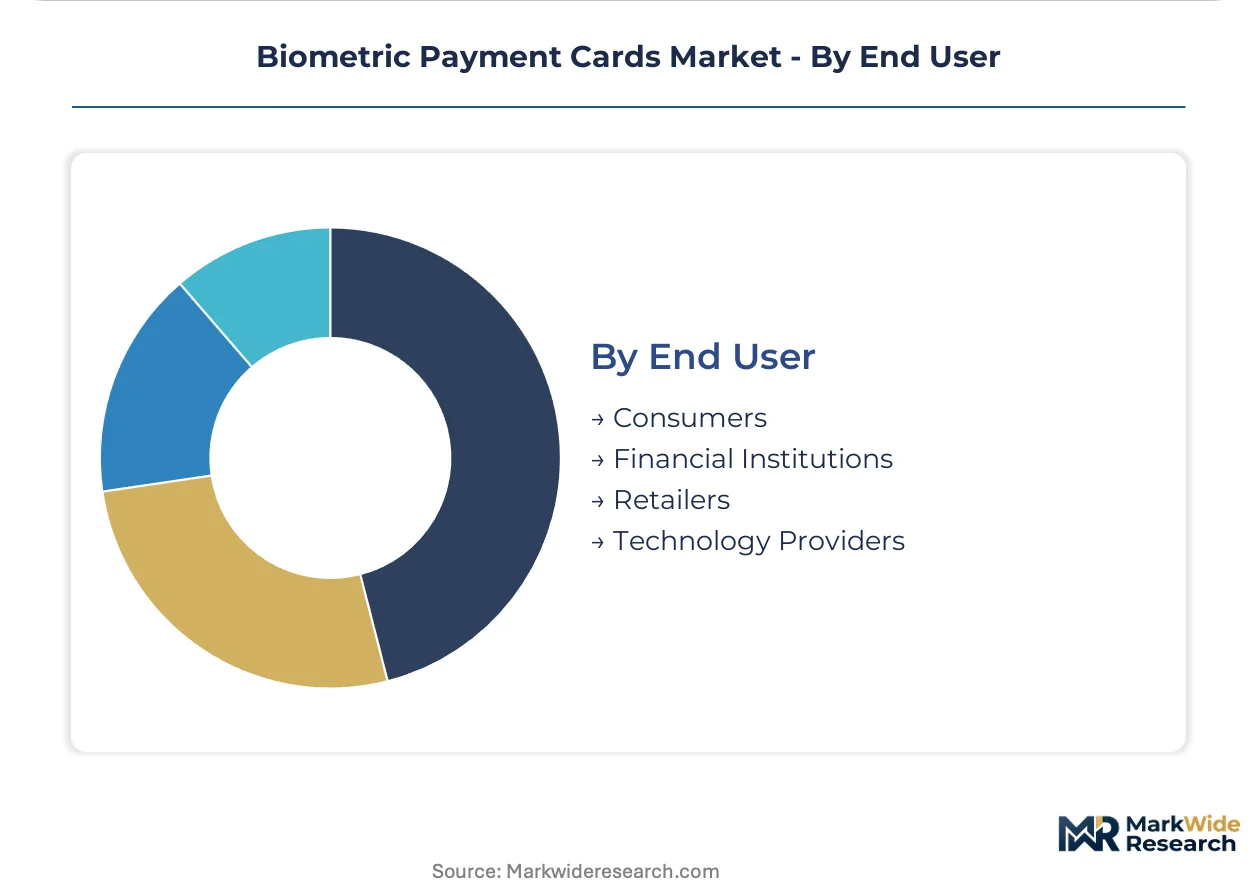
End User:
Customer type determines procurement scale and technical specification rigor, from individual consumers through institutional technology integrators.
- Financial Institutions:Banks and payment networks define product specifications, certification requirements, and issuance volumes. France's CNIL enrollment protocols and EMVCo security mandates directly shape their vendor selection criteria and rollout timelines.
- Consumers:Individual cardholders experience biometric authentication as reduced transaction friction and elimination of PIN memorization, with adoption sensitivity varying by age demographics and technology comfort.
- Retailers:Merchant acquiring banks and retail chains drive terminal infrastructure investment, with acceptance certification bundling into hardware upgrade programs.
- Technology Providers:Semiconductor foundries, secure element firmware developers, and biometric algorithm licensors occupy upstream positions in the value chain, capturing margin from specialized engineering scarcity.
Financial Institutions control specification authority, while Technology Providers are gaining share fastest as component integration complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biometric card manufacturing clusters in France and Germany supply European and Asian issuers. France's semiconductor packaging facilities anchor sensor integration capacity. South Korean and Indian banks drive commercial issuance velocity through regulatory-aligned procurement.
France
Thales Group's advanced packaging operations in Île-de-France dominate European sensor integration. CNIL biometric governance frameworks standardize enrollment procedures for card programs. Paris-based engineering clusters refine die-bonding processes for million-unit issuance scales.
South Korea
Urban ATM networks deploy fingerprint-enabled cards to reduce cash-out fraud. MFDS cybersecurity guidelines align with EMVCo certification pathways for domestic issuers. Seoul Capital Area banks convert pilot programs into commercial rollouts at accelerating velocity.
India
Jan Dhan Yojana financial inclusion programs convert unbanked populations into biometric card recipients. RBI payment security mandates tighten secure element requirements for domestic issuance. Mumbai and Delhi metropolitan corridors replace magnetic stripe readers with contactless-biometric terminals.
Germany
Specialized die-bonding equipment manufacturers concentrate in Bavaria and Baden-Württemberg. GDPR Article 9 compliance drives template storage architecture investments. Munich and Stuttgart engineering centers supply ISO/IEC 15408 evaluation capacity for Common Criteria certification.
United States
Payment networks shape global biometric card standards through EMVCo participation. FTC consumer protection oversight influences data handling disclosures for cross-border programs. Silicon Valley and Boston fintech clusters pilot hybrid CBDC-physical card authentication specifications.
Biometric Payment Cards Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in sensor and secure element supply. The market structures around three tiers: full-stack card manufacturers, biometric sensor providers, and semiconductor foundries. Two strategic archetypes dominate—European industrial conglomerates with defense-electronics heritage, and Nordic fabless semiconductor designers. Competitive moves concentrate on EMVCo certification pre-emption and enrollment infrastructure partnerships with tier-one issuers.
Within the Nordic specialist tier, IDEX Biometrics ASA and Zwipe occupy positions as sensor-on-card platform architects. Thales Group anchors the European industrial tier through semiconductor packaging integration. Fingerprint Cards AB exemplifies the component-focused archetype with capacitive sensor designs. These three represent divergent paths to market—platform licensing, vertical manufacturing control, and discrete component supply—each capturing margin from distinct value chain positions.
| Leading Market Players |
|---|
| IDEX Biometrics ASA |
| Zwipe |
| Thales Group |
| Visa Inc. |
| Mastercard |
| Fingerprint Cards AB |
| Infineon Technologies AG |
| NXP Semiconductors |
| IDEMIA |
| Others |
Cost & Logistics Intelligence
Undercapacity in French semiconductor packaging facilities is tightening sensor integration availability and pushing tier-one issuers toward long-term offtake commitments. This utilization squeeze simultaneously elevates pricing power for die-bonding specialists and compresses margins for card manufacturers caught between fixed-price bank contracts and rising input costs.
Pricing Analysis
EMVCo certification requirements dictate the pricing tier structure across biometric card procurement, separating Common Criteria-certified platforms from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO/IEC 15408 evaluation grade, volume scale, and after-sales enrollment support bundling. Cost compression in economy-tier contactless cards is intensifying because Indian financial inclusion programs prioritize unit cost over feature depth. Small-format retail chains in Mumbai exhibit the highest price sensitivity, while South Korean urban banks accept premium positioning for fraud reduction guarantees.
Supply Chain Analysis
Tariff exposure between German die-bonding equipment manufacturers and Asian card assembly plants dominates supply chain risk planning for tier-one issuers. Component sourcing concentrates in France for sensor integration, Germany for specialized packaging machinery, and South Korea for secure element fabrication. Raw material dependencies include silicon wafers for capacitive sensors, polyimide substrates for flexible antennae, and epoxy molding compounds for card body lamination. Single-source vulnerability around Thales Group's Île-de-France packaging capacity threatens million-unit issuance timelines. Distribution runs through bank procurement consortia and payment network certification programs rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric payment cards face substitution pressure from smartphone-based authentication applications, particularly in urban Chinese and Nordic markets where mobile wallet penetration has achieved critical mass. Incumbents must architect defensive positioning that preserves physical card relevance against digital displacement.
For Market Incumbents: Build certification moats through preemptive EMVCo and CNIL compliance investments that raise rival entry costs. Secure enrollment infrastructure partnerships with France's major banking groups to lock in branch-based biometric capture networks. Counter mobile payment substitution by emphasizing offline transaction capability in rural Indian corridors where connectivity gaps persist. Deepen backward integration into secure element firmware development to capture margin from scarce embedded systems engineering talent. For New Entrants and Emerging Players: Rural Indian banking penetration represents the most penetrable white-space target, where Jan Dhan Yojana programs convert unbanked populations without entrenched incumbent relationships. CBDC-physical card hybrid specifications in European pilot programs offer second-mover entry points as standards crystallize. Target municipal payment system tenders in secondary South Korean cities where Seoul Capital Area banks have not yet consolidated supply relationships. Pursue platform licensing arrangements with Nordic sensor-on-card specialists rather than competing for vertical manufacturing scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among secure element firmware developers and biometric algorithm licensors with per-unit royalty structures. Long-term viability over the coming decade hinges on positioning upstream of commoditizing card assembly operations. Acquisition candidates with ISO/IEC 15408 evaluation facility relationships and EMVCo pre-certification track records command structural scarcity premiums. Monitor central bank digital currency pilot announcements as the critical inflection signal for hybrid product specification demand.| Strategic Initiative | Industry Significance |
|---|---|
| EMVCo Certification Pre-emption | Early certification completion locks in tier-one issuer procurement cycles before rivals reach compliance. |
| Enrollment Infrastructure Partnership | Branch-based biometric capture networks with French banks create switching costs for card program migration. |
| Secure Element Firmware Acquisition | Embedded systems engineering scarcity makes firmware capabilities the binding constraint on card platform launches. |
| CBDC Hybrid Specification Development | European central bank pilot participation shapes physical card authentication requirements for digital currency convergence. |
| Rural Distribution Channel Buildout | Jan Dhan Yojana program access in India converts financial inclusion mandates into volume procurement relationships. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with biometric card program directors, secure element firmware engineers, payment network certification leads, and merchant acquiring bank procurement officers; alongside secondary validation through EMVCo specification documents, CNIL biometric governance filings, RBI payment security circulars, and SEC disclosures from listed semiconductor suppliers. Bottom-up unit economics modeling triangulated against top-down issuer procurement forecasts anchored the market sizing.
Forecast inputs included dual-interface versus contactless card adoption curves, fingerprint sensor miniaturization cost trajectories, and regulatory compliance timeline variations across French, South Korean, and Indian jurisdictions. Segmentation dimensions spanned product form factor, biometric modality, transaction environment, and end-user archetype. CAGRs derived from issuer rollout velocity assumptions and terminal infrastructure refresh cycles. Industry-specific inputs incorporated EMVCo certification queue lengths and Common Criteria evaluation facility capacity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by German die-bonding equipment manufacturers or accelerated mobile payment substitution in Nordic markets would shift outcomes. Forecasts reflect assumptions about regulatory alignment continuity and semiconductor packaging yield improvements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Payments Market
Payments
Mobile Payment Security Market
Payments
Global Payment Processor Market
Payments
China POS Terminals Market
Payments
Saudi Arabia Payments Market
Payments
Poland POS Terminal Market
Payments
Norway POS Terminals Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Digital Payment in Healthcare Market
Payments
France Virtual Cards Market
Payments
Japan Virtual Cards Market
Payments
Italy Payments Market
Payments
Italy Gift Cards Market
Payments
Proximity Payment Market
Payments
Mobile Wallet Market