
 South Korea Analog Integrated Circuits Market | 2026-2036
South Korea Analog Integrated Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Analog Integrated Circuits Market Insights
Market Context
Silicon-on-insulator substrates is shifting wafer economics for precision analog designs as foundries migrate from bulk CMOS to reduce parasitic capacitance. Samsung Electronics leverages captive fab capacity to anchor power management IC supply for domestic smartphone OEMs. MagnaChip Semiconductor specializes in display driver integration, occupying a defensible niche in OLED panel architectures. SK hynix competes through advanced packaging know-how, extending its memory-centric expertise into analog-digital hybrid modules.
Technical Definition and Segment Structure
Analog integrated circuits process continuous voltage and current signals through operational amplifiers, voltage regulators, and comparators fabricated in BiCMOS, CMOS, or Bipolar processes, typically operating across temperature ranges from minus forty to one hundred twenty-five degrees Celsius for industrial reliability. The primary commercial purpose centers on power management and signal conditioning in systems where digital precision proves insufficient or power efficiency demands granular analog control. Voltage regulators capture the dominant margin pool as automotive and telecommunications infrastructure demand tighter load regulation across wider input ranges. Operational amplifiers represent the fastest-growing product category, propelled by sensor interface proliferation in industrial automation and electric vehicle battery management systems. GaN technology segments remain nascent in South Korea but attract R&D allocation due to superior switching efficiency in high-frequency power conversion applications.
Regulatory Framework and Outlook
MFDS equipment safety standards and KTL certification requirements shape product qualification timelines for medical and automotive analog IC deployments in South Korea. The Ministry of Trade, Industry and Energy enforces local content ratios through the National Strategic Technology designation, steering procurement toward domestic suppliers for designated critical components. Stakeholders must monitor how forthcoming amendments to the Electrical Appliances Safety Control Act expand scope to cover battery management analog subsystems previously exempt from mandatory testing.
Market Dynamics
Samsung's 3nm analog-compatible node migration is compressing die geometries while forcing domestic competitors to accelerate BiCMOS process roadmaps or cede power management socket share to captive foundry output.
Growth Catalysts
- Automotive electrification mandates:Hyundai-Kia supply chain qualification requirements for battery management ICs are pulling precision voltage regulator volumes upward. Tier-1 module suppliers must dual-source from domestic analog houses under Ministry of Trade, Industry and Energy local content ratios.
- Silicon-on-insulator substrate transition:Foundry migration from bulk CMOS to SOI wafers reduces parasitic capacitance in radio-frequency signal paths. RF front-end module integrators in Gyeonggi Province are qualifying SOI-based LNAs for 5G infrastructure deployments.
- Gyeonggi cluster infrastructure:Co-located packaging and test facilities with design houses compress NPI timelines. Analog fabless houses leverage proximity to OSATs for rapid iteration on custom power management specifications.
Market Restraints
- 300mm SOI wafer supply concentration:Substrate fabrication capacity concentrates among two global suppliers, exposing Korean analog designers to allocation risk during semiconductor upcycles.
- MFDS equipment safety certification timelines:Medical device analog subsystem approvals require twelve-to-eighteen month qualification windows, freezing design revisions post-submission.
- GaN process substitution threat:Gallium nitride power devices achieve superior switching efficiency above one megahertz, threatening silicon-based voltage regulator sockets in high-frequency conversion applications.
Strategic Opportunities
- Busan-Jinhae industrial zone underpenetration:Shipbuilding and marine electronics clusters lack localized analog design support, creating white space for power management IC houses to establish application engineering presence.
- National Strategic Technology procurement incentives:Designated critical component status unlocks preferential R&D tax treatment and public procurement preference for domestic battery management analog suppliers.
- Advanced packaging convergence:SK hynix memory-centric expertise in hybrid bonding enables analog-digital module integration for sensor fusion applications, compressing form factors in autonomous vehicle compute stacks.
Industry Challenges
- Analog-mixed signal design talent scarcity:BiCMOS process expertise concentrates among engineers with ten-plus years of foundry interface experience, constraining fabless house expansion.
- KTL certification test capacity bottlenecks:Automotive analog qualification queues extend six months at peak demand periods, delaying production ramps for new power management device introductions.
- Legacy 8-inch equipment obsolescence:Maintenance parts availability for established analog process nodes is degrading, forcing premature migration to higher-cost 12-inch flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Analog Integrated Circuits Market |
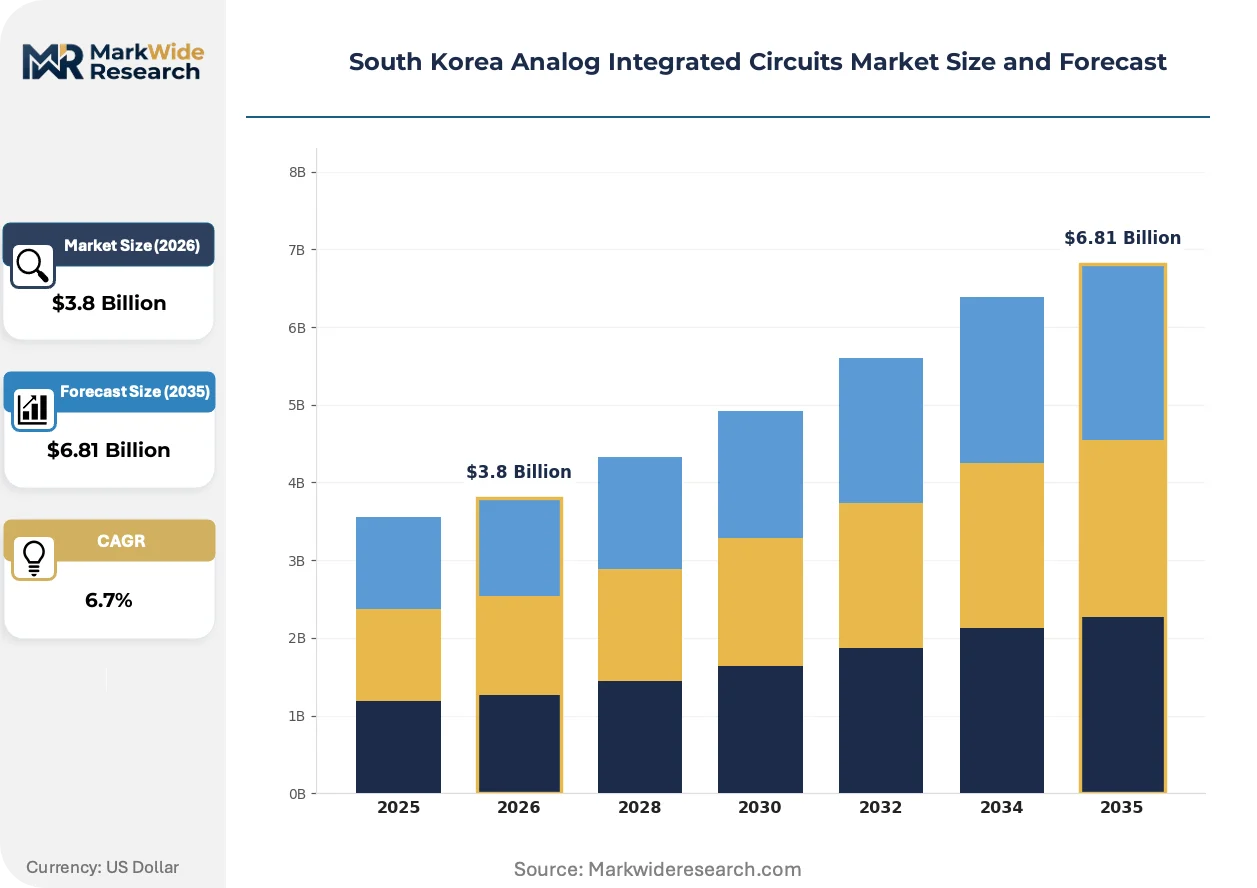
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Voltage Regulators, Comparators, Amplifiers End User: Consumer Electronics, Automotive, Telecommunications, Industrial Automation Technology: BiCMOS, CMOS, Bipolar, GaN Application: Signal Processing, Power Management, Sensing, Audio Processing |
| Companies Covered | Samsung Electronics, SK hynix, MagnaChip Semiconductor, DB HiTek, Silicon Works, Texas Instruments Inc, Analog Devices Inc, STMicroelectronics NV, Infineon Technologies AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Analog Integrated Circuits Market Trends and Innovations
Process-material co-optimization is displacing pure geometry scaling as the primary vector for analog performance improvement, with substrate engineering and packaging innovation now outpacing lithographic advancement in signal fidelity gains.
Silicon-on-insulator substrates are absorbing the parasitic reduction burden previously addressed through node migration, enabling bulk CMOS analog designs to achieve RF performance without full process redeployment. 5G infrastructure OEMs in Suwon and Pangyo are qualifying SOI-based variable gain amplifiers for massive MIMO arrays. The technology is absorbing margin pressure from foundry cost escalation by extending depreciated equipment utilization.
MFDS amendments to the Electrical Appliances Safety Control Act are expanding mandatory testing scope to cover battery management analog subsystems previously exempt from certification. Medical device OEMs must now submit power management IC documentation for pre-market safety review. Portable diagnostic equipment manufacturers in Osong Biovalley are restructuring supply chains to source pre-qualified domestic analog components.
Consolidated procurement by smartphone OEMs is compressing analog supplier qualification cycles and forcing specification standardization across power management device families. Samsung Electronics mobile division now mandates unified voltage regulator footprints across flagship and mid-tier platforms. Domestic analog houses report average socket retention periods shortening from thirty-six to eighteen months.
South Korea Analog Integrated Circuits Market Segmentation
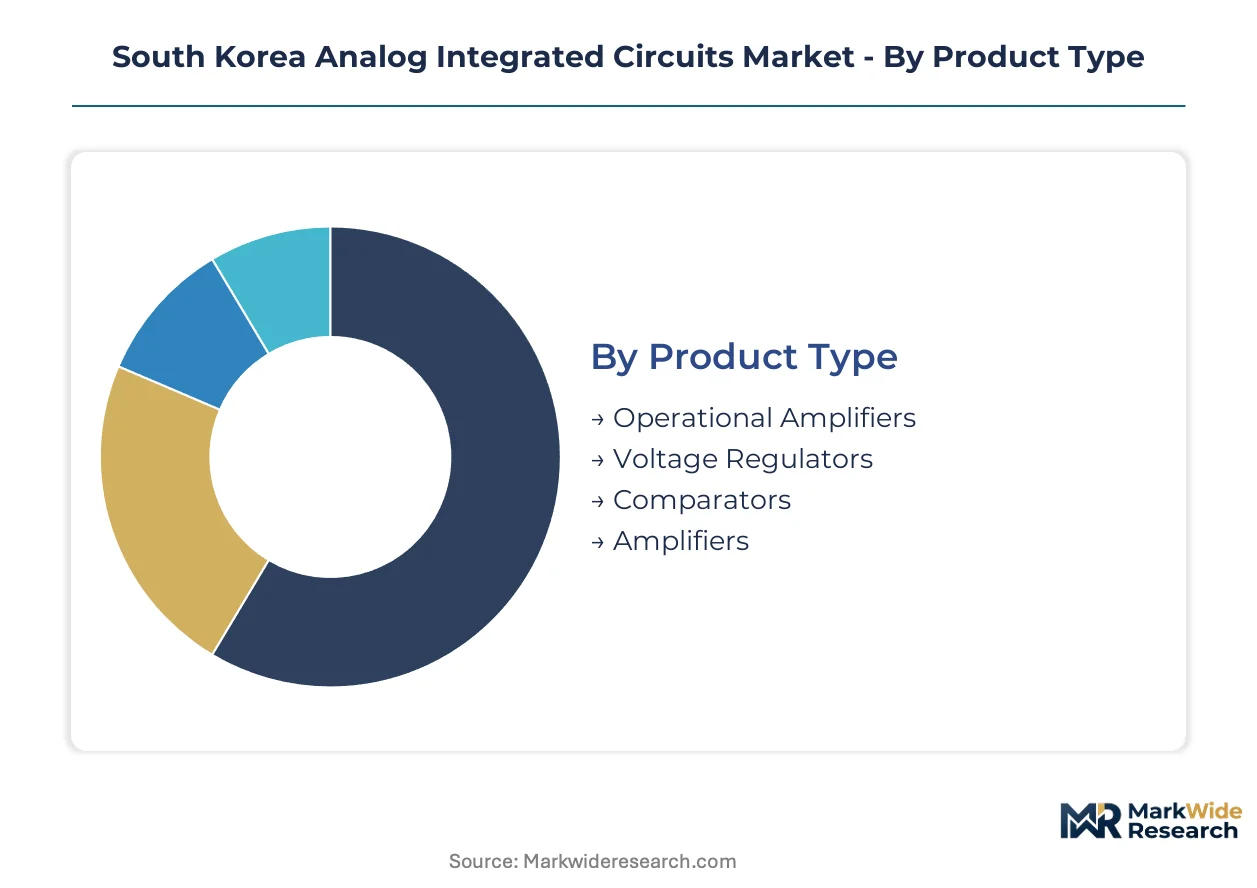
Segmentation reveals how capital deployment and process specialization fragment South Korea's analog IC landscape. Foundry capacity allocation, automotive qualification requirements, and substrate technology choices reshape competitive positioning across each dimension.
Product Type:
Capital intensity varies sharply across product categories, with precision voltage regulation demanding the most extensive characterization infrastructure and longest qualification cycles.
- Voltage Regulators:These devices maintain stable output voltage across fluctuating load conditions and input ranges through linear or switching topologies. Hyundai-Kia battery management systems consume the dominant share of precision LDO and DC-DC volumes, with local content mandates forcing dual-source qualification timelines. Automotive-grade specifications require minus forty to one hundred fifty degree Celsius operation, extending test infrastructure investment cycles.
- Operational Amplifiers:High-gain differential amplifiers with near-infinite input impedance serve sensor signal conditioning and active filter applications. Industrial automation OEMs in Gyeonggi Province are qualifying rail-to-rail CMOS op-amps for motor control interfaces, driven by smart factory sensor proliferation.
- Comparators:High-speed voltage level detectors trigger digital logic transitions in power-on reset and window detection circuits. Samsung smartphone platforms standardize comparator footprints across tiered product lines.
- Amplifiers:General-purpose gain stages span audio, RF, and instrumentation domains with varying bandwidth and noise specifications. 5G infrastructure deployments in Suwon absorb RF amplifier volumes for massive MIMO implementations.
Most installed capacity flows through Voltage Regulators. Expansion is steepest in Operational Amplifiers.
End User:
Application maturity and certification burden create divergent margin structures across customer verticals.
- Automotive:Battery management, LED driver, and infotainment subsystems require AEC-Q100 qualification and MFDS safety documentation. Tier-1 module suppliers face twelve-to-eighteen month approval windows for new power management introductions.
- Consumer Electronics:Smartphone and wearable OEMs drive the highest volume consumption through consolidated procurement. Samsung Electronics mobile division compresses supplier qualification cycles to eighteen-month socket retention periods.
- Telecommunications:Base station and optical transport equipment demand wide-temperature-range operation for outdoor deployment. 5G infrastructure OEMs in Pangyo qualify SOI-based RF front-ends for massive MIMO arrays.
- Industrial Automation:Motor drives, programmable logic controllers, and sensor interfaces require extended temperature operation and galvanic isolation. Smart factory deployments in Gyeonggi Province accelerate precision analog consumption for process control.
Automotive commands the highest average selling prices. Consumer Electronics delivers the steepest volume expansion trajectory.
Technology:
Process node selection determines parasitic performance, integration density, and foundry access economics.
- BiCMOS:Bipolar-CMOS integration combines high-speed bipolar transistors with dense CMOS logic for mixed-signal precision. Analog houses with ten-plus years of foundry interface experience concentrate expertise here, constraining fabless expansion.
- CMOS:Pure CMOS implementations achieve lowest cost at the expense of analog performance, dominating consumer price-sensitive sockets. Samsung's 3nm analog-compatible node migration enables die size compression for power management integration.
- Bipolar:Discrete bipolar processes deliver superior transconductance and noise performance for precision instrumentation. Legacy 8-inch equipment obsolescence forces premature migration to higher-cost 12-inch flows.
- GaN:Gallium nitride power devices achieve switching efficiencies above one megahertz, threatening silicon-based voltage regulator sockets in high-frequency conversion. R&D allocation remains nascent in South Korea despite superior performance characteristics.
CMOS holds the dominant installed base. BiCMOS delivers the fastest margin expansion.
Application:
Functional purpose determines specification stringency and customer integration depth.
- Power Management:Voltage regulation, battery charging, and power distribution subsystems dominate analog IC consumption by value. Automotive electrification mandates pull precision power management volumes upward across Hyundai-Kia supply chains.
- Signal Processing:Amplification, filtering, and analog-to-digital interface conditioning enable sensor and communication front-ends. 5G infrastructure deployments absorb variable gain amplifiers for beamforming applications.
- Sensing:Temperature, current, and voltage sensing circuits provide system monitoring and protection functions. Electric vehicle battery management systems require multi-channel precision sensing for cell balancing.
- Audio Processing:Microphone preamplification, DAC output stages, and headphone drivers serve consumer electronics platforms. Smartphone OEMs mandate specification standardization across flagship and mid-tier audio subsystems.
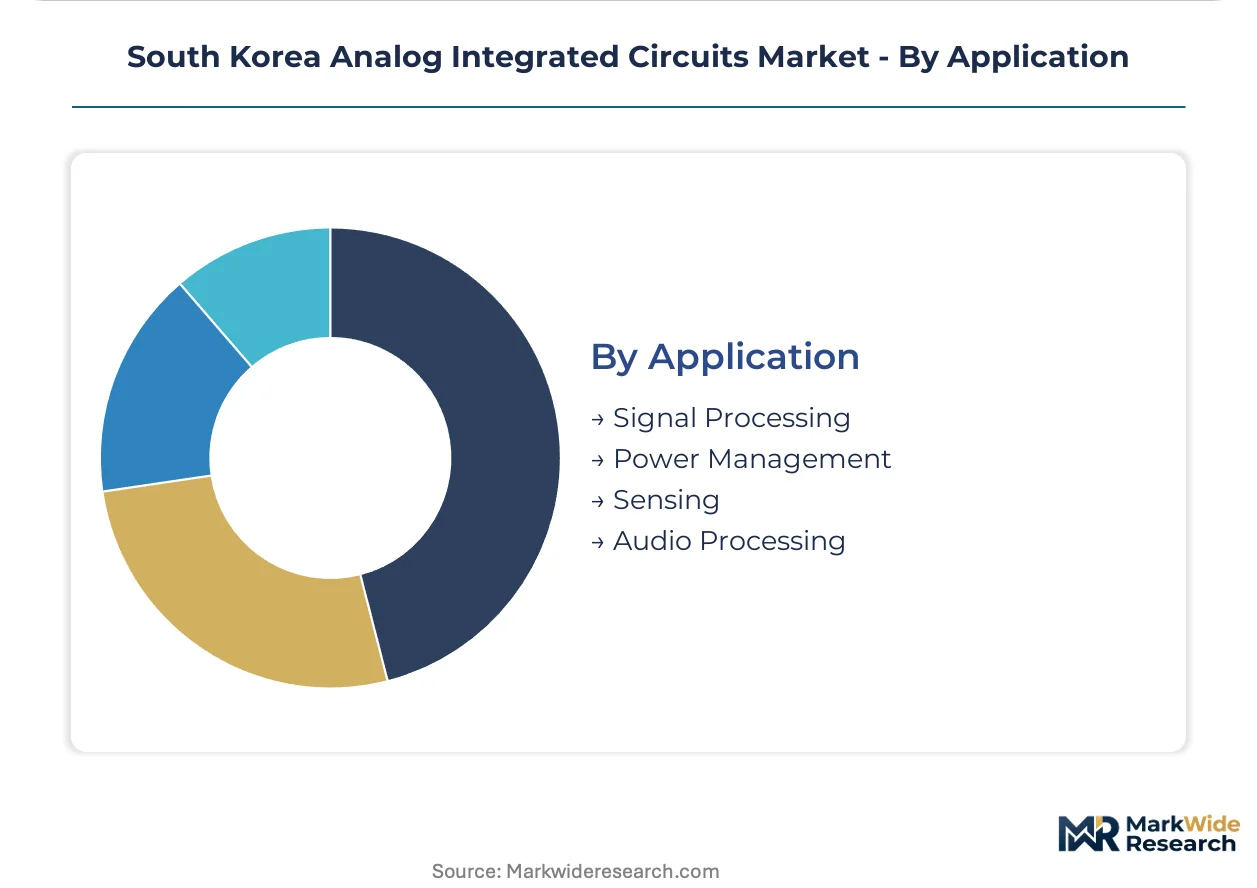
Power Management captures the dominant revenue share. Sensing applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gyeonggi Province anchors South Korea's analog IC production, hosting the densest concentration of foundry capacity, packaging infrastructure, and fabless design houses. Geographic specialization across five sub-regions creates distinct competitive ecosystems.
Seoul Capital Area
Hyundai Motor Group's battery management procurement drives precision voltage regulator demand through Seongnam and Suwon design centers. MFDS equipment safety standards enforce twelve-month qualification windows for automotive analog deployments. Pangyo Techno Valley hosts RF front-end module integrators qualifying SOI-based LNAs for 5G infrastructure.
Busan-Ulsan
Shipbuilding and marine electronics clusters generate underserved demand for industrial-grade power management ICs. The Ministry of Trade, Industry and Energy's National Strategic Technology designation steers procurement toward domestic suppliers for critical marine propulsion subsystems. Busan-Jinhae industrial zone lacks localized analog design support, creating white space for application engineering expansion.
Daegu-Gyeongbuk
Smart factory sensor proliferation accelerates operational amplifier consumption for motor control interfaces. KTL certification requirements shape product qualification timelines for industrial automation deployments. Gumi electronics complex concentrates precision analog test infrastructure for automotive-tier suppliers.
Daejeon-Sejong
Government research institutes drive advanced packaging R&D for analog-digital hybrid modules. Public procurement incentives under the National Strategic Technology program unlock preferential tax treatment for designated critical component developers. Sejong administrative city coordinates regulatory alignment between MFDS and automotive safety standards.
Gwangju-Honam
Portable diagnostic equipment manufacturers restructure supply chains around pre-qualified domestic analog components. Amendments to the Electrical Appliances Safety Control Act expand mandatory testing scope to battery management subsystems. Osong Biovalley medical device OEMs source power management ICs from Gyeonggi-based qualified suppliers.
South Korea Analog Integrated Circuits Market Competitive Landscape
Global majors compete with regional champions across process technology and automotive qualification depth. The vendor base separates into captive foundry operators, specialized fabless houses, and diversified memory players extending into analog-digital integration. Three archetypes dominate: integrated device manufacturers with captive fab capacity, analog pure-plays with decade-long foundry relationships, and memory-centric fabricators leveraging advanced packaging expertise. Competitive moves concentrate on SOI substrate qualification partnerships and BiCMOS process roadmap acceleration.
Within the integrated device manufacturer tier, Samsung Electronics anchors power management supply for domestic smartphone OEMs through captive 3nm analog-compatible node output. SK hynix exemplifies the memory-to-analog extension archetype, applying hybrid bonding expertise to sensor fusion modules for autonomous vehicle compute stacks. MagnaChip Semiconductor occupies a defensible niche among specialized fabless houses, concentrating display driver integration expertise for OLED panel architectures.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK hynix |
| MagnaChip Semiconductor |
| DB HiTek |
| Silicon Works |
| Texas Instruments Inc |
| Analog Devices Inc |
| STMicroelectronics NV |
| Infineon Technologies AG |
| Others |
Pricing and Supply Chain Analysis
Hyundai-Kia battery management procurement concentration enforces contract-based long-term offtake pricing for automotive-grade voltage regulators, compressing spot-market premiums for unqualified suppliers. Samsung Electronics mobile division's consolidated power management IC sourcing extracts volume-scale discounts that propagate through Gyeonggi Province fabless houses.
Pricing Analysis
300mm SOI wafer cost pass-through dominates input-cost dynamics, with substrate allocation surcharges feeding directly into voltage regulator unit economics. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels segments buyer willingness-to-pay. Cost compression in consumer CMOS implementations is intensifying because Samsung's 3nm node migration enables die-size reduction without performance penalty. Smartphone OEMs exhibit highest price sensitivity, while medical device manufacturers under MFDS compliance timelines accept premium positioning for pre-qualified domestic supply.
Supply Chain Analysis
BiCMOS process engineer scarcity in Gyeonggi Province and Seongnam design centers constrains foundry interface capacity expansion for precision analog houses. Raw material flows draw from Japan and Taiwan for 300mm SOI substrates, while specialty gases and sputtering targets source from Germany and the United States. Single-source vulnerability concentrates in SOI wafer fabrication, where two global suppliers control substrate availability during semiconductor upcycles. Distribution runs through co-located OSATs in Suwon and Pangyo for rapid NPI iteration on custom power management specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with MFDS amendments to the Electrical Appliances Safety Control Act expanding mandatory testing scope and locking in domestic supplier preference for battery management subsystems.
For Market Incumbents: Deploy BiCMOS process roadmap acceleration to defend automotive socket share against Samsung's captive 3nm analog-compatible node output. Secure KTL certification test capacity reservations six months ahead of production ramps to avoid qualification queue bottlenecks. Extend backward integration into 300mm SOI substrate partnerships to mitigate allocation risk from concentrated global supply. For New Entrants and Emerging Players: Begin with Busan-Jinhae industrial zone application engineering presence to capture underserved shipbuilding and marine electronics power management demand. Target industrial automation sensor interface sockets in Daegu-Gyeongbuk smart factory clusters where analog-mixed signal design talent scarcity constrains incumbent expansion. Pursue National Strategic Technology designation for battery management components to unlock preferential public procurement access. For Investors and Strategic Acquirers: Memory-centric fabricators extending into analog-digital hybrid modules are the most active acquirer in this space, seeking advanced packaging expertise for autonomous vehicle compute stack integration. Five-to-ten year viability hinges on SOI substrate qualification partnerships and automotive AEC-Q100 certification depth. Monitor GaN power device R&D allocation rates as inflection indicator for silicon-based voltage regulator substitution threat.| Strategic Initiative | Industry Significance |
|---|---|
| SOI Substrate Qualification Partnership | Secures 300mm wafer allocation priority from Japanese and Taiwanese suppliers during supply upcycles. |
| KTL Certification Pre-Investment | Compresses automotive analog qualification timelines from eighteen months to twelve months for battery management ICs. |
| BiCMOS Process Roadmap Acceleration | Defends power management socket retention against Samsung's captive 3nm foundry output for domestic smartphone OEMs. |
| Busan-Jinhae Application Engineering Expansion | Captures white-space demand from marine electronics and shipbuilding clusters lacking localized analog design support. |
| Advanced Packaging Hybrid Bonding Investment | Enables analog-digital module integration for sensor fusion in Hyundai-Kia autonomous vehicle compute stacks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foundry process engineers, Tier 1 automotive supplier procurement leads, OSAT operations managers, and medical device OEM regulatory affairs directors with secondary validation against SEC 10-K filings, MFDS equipment safety registration databases, KTL certification records, and Korea Customs Service trade data. Bottom-up voltage regulator and operational amplifier volume estimates triangulated against top-down foundry capacity allocation disclosures.
Historical reference periods anchored the projection horizon to observed capacity expansion cycles, qualification timeline distributions, and substrate price volatility patterns across prior semiconductor upcycles. Segmentation dimensions modeled include product type, end-user vertical, process technology node, and application function, with CAGRs derived from regression analysis of foundry utilization rates and automotive electrification mandate implementation schedules. Forecast inputs incorporated Hyundai-Kia battery management IC procurement volumes and 5G infrastructure deployment trajectories in Suwon and Pangyo.
Several conditions sit outside the modeled scope, including unforeseen GaN power device process breakthroughs, SOI wafer supply disruption beyond historical allocation patterns, and regulatory acceleration or delay in MFDS electrical safety standard amendments. Forecasts reflect assumptions about continued local content ratio enforcement and Samsung foundry capacity prioritization for captive analog output. Material deviation in GaN substitution rates, substrate supply concentration, or automotive qualification timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market