
 US Sterilization Services Market | 2026-2036
US Sterilization Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Sterilization Services Market Intelligence
Contract sterilization revenue is fragmenting across modality-specific providers and full-service platforms. STERIS anchors the high-volume ethylene oxide segment through its nationwide facility network. Sotera Health competes on integrated irradiation and electron-beam capacity for pharmaceutical packaging. E-BEAM Services, Inc specializes in electron-beam sterilization for temperature-sensitive polymers, occupying a defensible niche in medical device materials.
US sterilization services encompass validated microbial elimination processes applied to medical instruments, devices, and packaging materials using steam, ethylene oxide, gamma radiation, or vaporized hydrogen peroxide at specified sterility assurance levels, primarily ensuring patient safety and regulatory compliance in healthcare delivery. Ethylene oxide sterilization retains dominant share due to its compatibility with heat- and moisture-sensitive medical devices, though gamma irradiation is capturing faster growth in pharmaceutical packaging applications. Low temperature sterilization technologies command premium pricing in hospital central sterile processing departments where instrument turnover speed determines operating room throughput.
FDA medical device reprocessing regulations and AAMI ST79 steam sterilization standards shape validation requirements and facility qualification burdens for service providers. OSHA ethylene oxide exposure limits and EPA emissions oversight constrain facility siting and operational economics for chemical sterilization operators. Stakeholders must monitor emerging vaporized hydrogen peroxide validation protocols and state-level environmental permitting shifts that could redistribute capacity across the US sterilization landscape.
Market Dynamics
Hospital consolidation and ambulatory surgical center expansion are compressing sterilization procurement cycles, forcing contract providers to reconfigure capacity networks around regional surgical volume clusters rather than legacy metropolitan hub models.
Growth Catalysts
- Ethylene oxide compatibility:Heat- and moisture-sensitive polymer devices from cardiovascular and orthopedic manufacturers require validated EtO cycles that third-party specialists alone can certify under FDA reprocessing guidelines.
- Texas and Florida construction:Sun Belt ambulatory surgical center buildouts concentrate sterilization demand near medical device manufacturing corridors, reducing logistics costs for contract providers.
- OSHA exposure rule enforcement:Tighter workplace EtO monitoring is pushing hospital systems toward outsourced sterilization with dedicated emissions control infrastructure.
Market Restraints
- Ethylene oxide feedstock volatility:Petrochemical supply disruptions and EPA emissions permitting delays constrain facility siting economics for chemical sterilization operators.
- Gamma irradiation source concentration:Cobalt-60 supply chains concentrate in Canadian and Russian processing facilities, creating cross-border dependency risk for US pharmaceutical packaging sterilizers.
- Electron-beam penetration limits:High-density medical device loads and thick polymer packaging materials exceed effective electron-beam dose penetration, restricting modality substitution.
Strategic Opportunities
- Vaporized hydrogen peroxide validation:Emerging VHP protocols for temperature-sensitive endoscopes and robotic surgical instruments open premium service tiers in hospital central sterile processing departments.
- Arizona and Nevada ASC corridors:Underpenetrated desert-state surgical markets lack proximate sterilization capacity, rewarding early-mover facility investments along Interstate corridors.
- FDA 510(k) sterilization validation bundling:Device manufacturers seek sterilization partners capable of integrated biocompatibility and sterility assurance documentation, consolidating vendor relationships.
Industry Challenges
- Certified sterile processing technician scarcity:Hospital and contract facility expansion outpaces credentialed central sterile supply workforce development, compressing staffing ratios.
- Legacy steam autoclave infrastructure:In-house hospital sterilization departments face multi-million dollar capital refresh cycles for ASME pressure vessel compliance and AAMI ST79 validation updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sterilization Services Market |
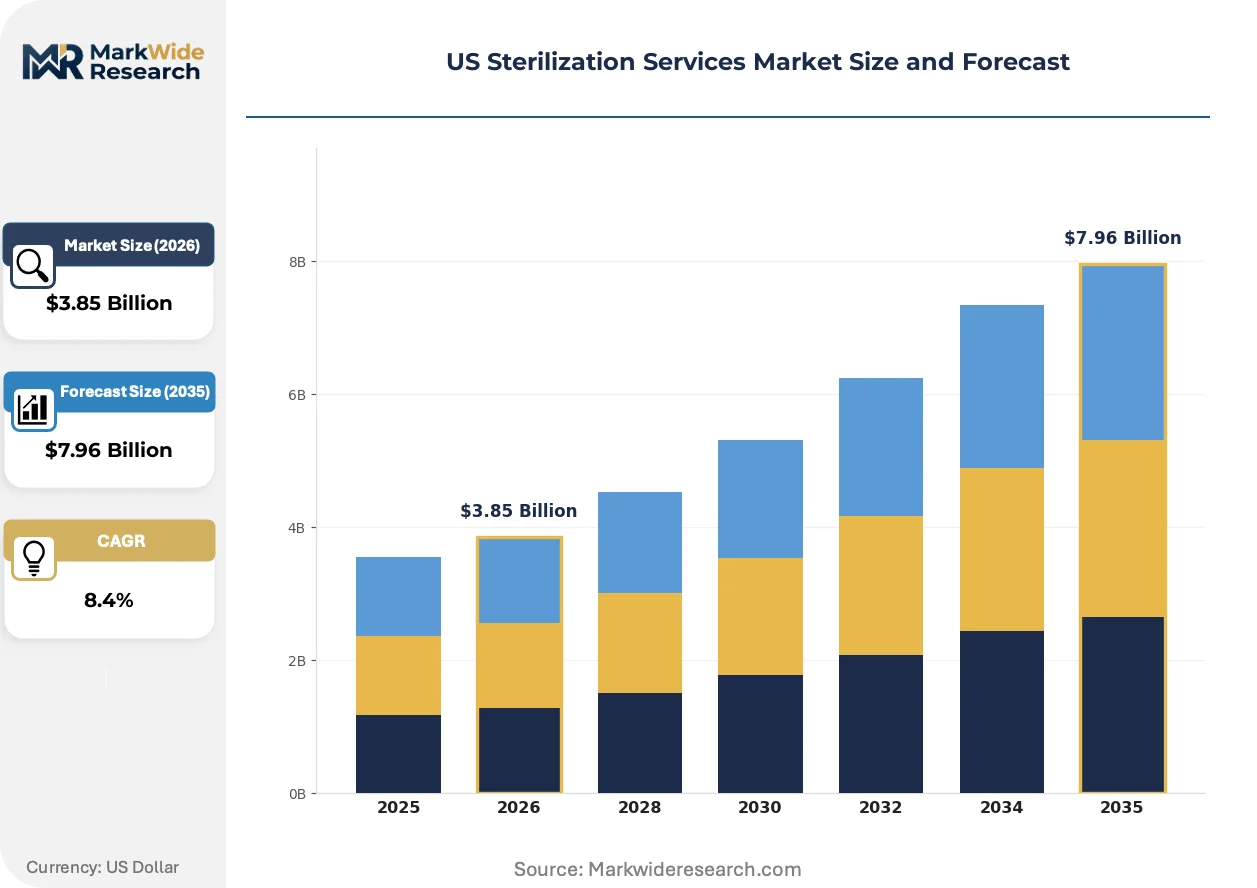
| Market Size in 2026 | $3.85 Billion |
| Market Size in 2035 | $7.96 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Sterilization by Steam, Ethylene Oxide, Gamma Radiation, Vaporized Hydrogen Peroxide End User: Hospitals, Dental Clinics, Pharmaceutical Companies, Medical Device Manufacturers Technology: Conventional Sterilization, Low Temperature Sterilization, Irradiation, Chemical Sterilization Application: Instruments, Packaging, Medical Equipment, Laboratory Supplies |
| Companies Covered | Andersen Sterilizers, Prince Sterilization Services, LLC, STERIS, Ecolab Inc., Midwest Sterilization Corporation, Sotera Health, E-BEAM Services, Inc, Cretex Companies, ASP (Fortive), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sterilization Services Market Strategic Shifts & Innovations
Sterilization modality selection is pivoting from historical ethylene oxide dominance toward radiation-based alternatives, driven by regulatory pressure on chemical emissions and device material evolution.
X-ray sterilization systems are penetrating pharmaceutical packaging and medical device sterilization with penetration depths exceeding electron-beam limits without radioactive source management. Midwest contract sterilizers are piloting X-ray units for high-volume polymer syringe and vial applications. The technology is rendering obsolete cobalt-60 gamma irradiation for mid-density medical packaging loads.
EPA ethylene oxide emissions oversight is tightening facility siting requirements and stack monitoring protocols for chemical sterilization operators. Industrial consequence includes extended permitting timelines and defensive facility relocation toward rural industrial zones. Texas and Louisiana chemical corridor sterilizers face the most intensive state-level air quality enforcement.
Consolidated procurement by multi-hospital health systems is compressing sterilization vendor panels from modality-specific contracts toward integrated full-service platforms. Hospital supply chain executives are bundling EtO, gamma, and low-temperature sterilization under single-source agreements with penalty clauses for modality failure. This pattern concentrates most visibly in Florida and California health system networks.
US Sterilization Services Market Segmentation
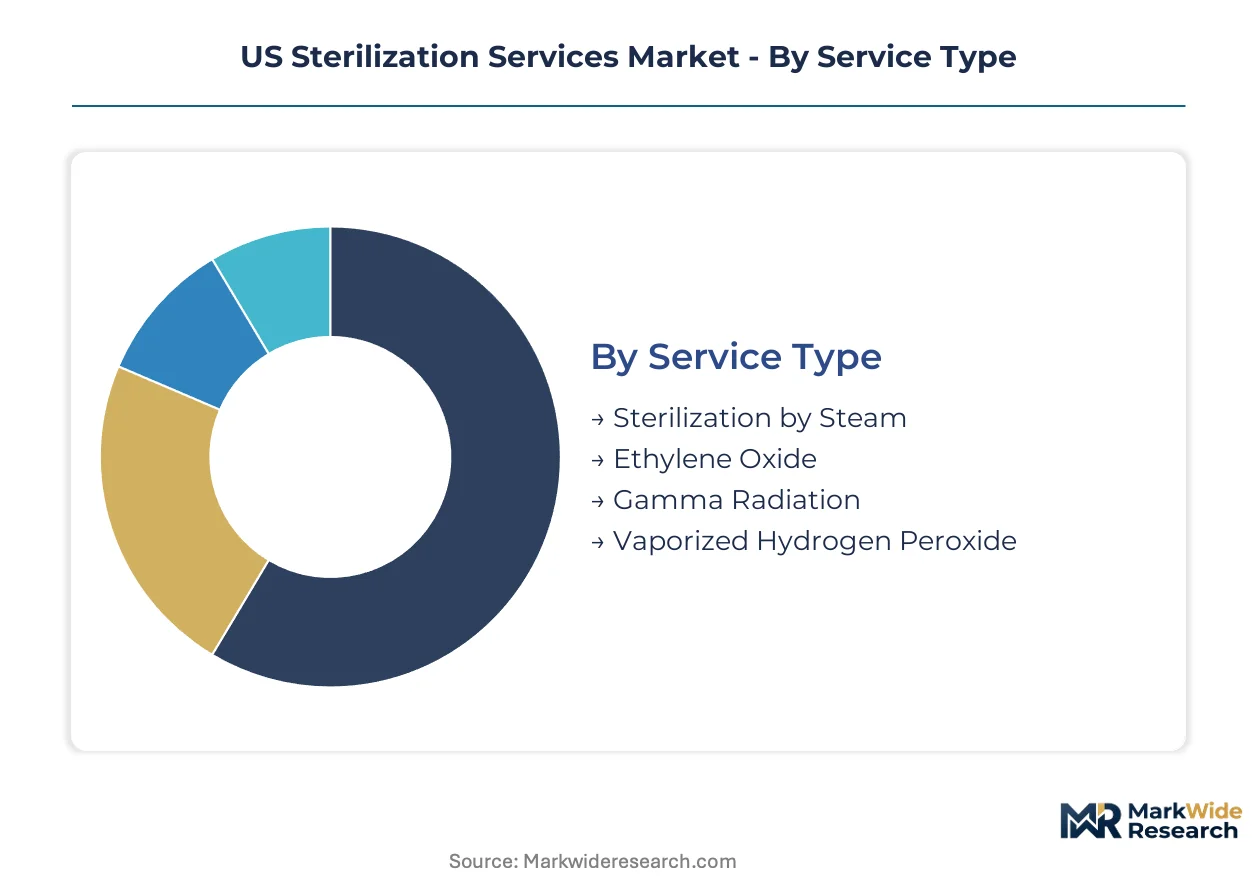
Sterilization modality selection determines capital intensity, regulatory burden, and geographic service radius for contract providers. End-user procurement patterns fragment the market between high-volume hospital outsourcing and precision-driven pharmaceutical validation requirements.
Service Type:
Steam sterilization anchors high-throughput surgical instrument processing, while chemical and radiation modalities address material compatibility constraints across device portfolios.
- Sterilization by Steam:Saturated steam under pressure achieves rapid microbial elimination for heat-stable surgical instruments and metal device trays. Demand concentrates in hospital central sterile processing departments across Texas and Florida surgical corridors, where instrument turnover speed determines operating room throughput.
- Ethylene Oxide:Low-temperature gas penetration sterilizes heat- and moisture-sensitive polymers used in cardiovascular catheters and orthopedic implants. FDA reprocessing validation requirements and OSHA exposure monitoring push device manufacturers toward third-party EtO specialists with dedicated emissions control infrastructure.
- Gamma Radiation:Cobalt-60 isotope emission delivers deep penetration for pharmaceutical packaging and bulk medical device loads. Cobalt-60 supply concentration in Canadian processing facilities creates cross-border dependency risk for US pharmaceutical sterilizers.
- Vaporized Hydrogen Peroxide:Low-temperature oxidative process targets temperature-sensitive endoscopes and robotic surgical instruments with rapid cycle times. Emerging VHP protocols open premium service tiers in hospital central sterile processing departments.
Established volume favors steam sterilization; emerging adoption favors vaporized hydrogen peroxide.
End User:
Procurement scale and validation complexity create distinct service tiers across healthcare delivery and manufacturing segments.
- Hospitals:Multi-facility health systems consolidate sterilization vendor panels under single-source agreements bundling EtO, gamma, and low-temperature modalities. Consolidated procurement concentrates visibly in Florida and California health system networks.
- Medical Device Manufacturers:Cardiovascular and orthopedic polymer device producers require validated EtO cycles under FDA 510(k) sterilization validation bundling. Device manufacturers seek integrated biocompatibility and sterility assurance documentation from contract partners.
- Pharmaceutical Companies:Sterile injectable packaging and vial sterilization demand gamma irradiation or emerging X-ray alternatives for high-density polymer syringe applications.
- Dental Clinics:Smaller-scale instrument sterilization requirements favor regional steam autoclave service networks or in-house processing equipment.
Hospital outsourcing is accelerating fastest; pharmaceutical validation commands premium pricing tiers.
Technology:
Capital deployment and workforce certification requirements differentiate conventional infrastructure from emerging low-temperature platforms.
- Conventional Sterilization:Steam autoclave and EtO chamber infrastructure dominates installed base across contract sterilization networks. Legacy hospital in-house departments face multi-million dollar capital refresh cycles for ASME pressure vessel compliance.
- Irradiation:Gamma and electron-beam systems serve pharmaceutical packaging and temperature-sensitive polymer medical devices. Midwest contract sterilizers pilot X-ray units rendering cobalt-60 gamma irradiation obsolete for mid-density packaging loads.
- Low Temperature Sterilization:Vaporized hydrogen peroxide and hydrogen peroxide gas plasma systems command premium pricing where instrument turnover speed determines surgical throughput.
- Chemical Sterilization:Liquid chemical and EtO gas processes remain essential for heat-sensitive device materials despite EPA emissions oversight tightening facility siting requirements.
Conventional infrastructure retains volume dominance; irradiation technology is climbing the fastest.
Application:
Load density and material composition dictate modality compatibility across sterilization service portfolios.
- Instruments:Surgical tool trays and endoscopes require validated steam or low-temperature cycles with bioburden documentation for FDA compliance.
- Packaging:Pharmaceutical vials, syringes, and sterile barrier systems drive gamma and electron-beam irradiation demand with penetration depth requirements.
- Medical Equipment:Implantable devices and robotic surgical systems combine polymer and electronic components demanding material-specific sterilization protocols.
- Laboratory Supplies:Cell culture media and diagnostic consumables require sterile assurance levels distinct from surgical instrument processing.
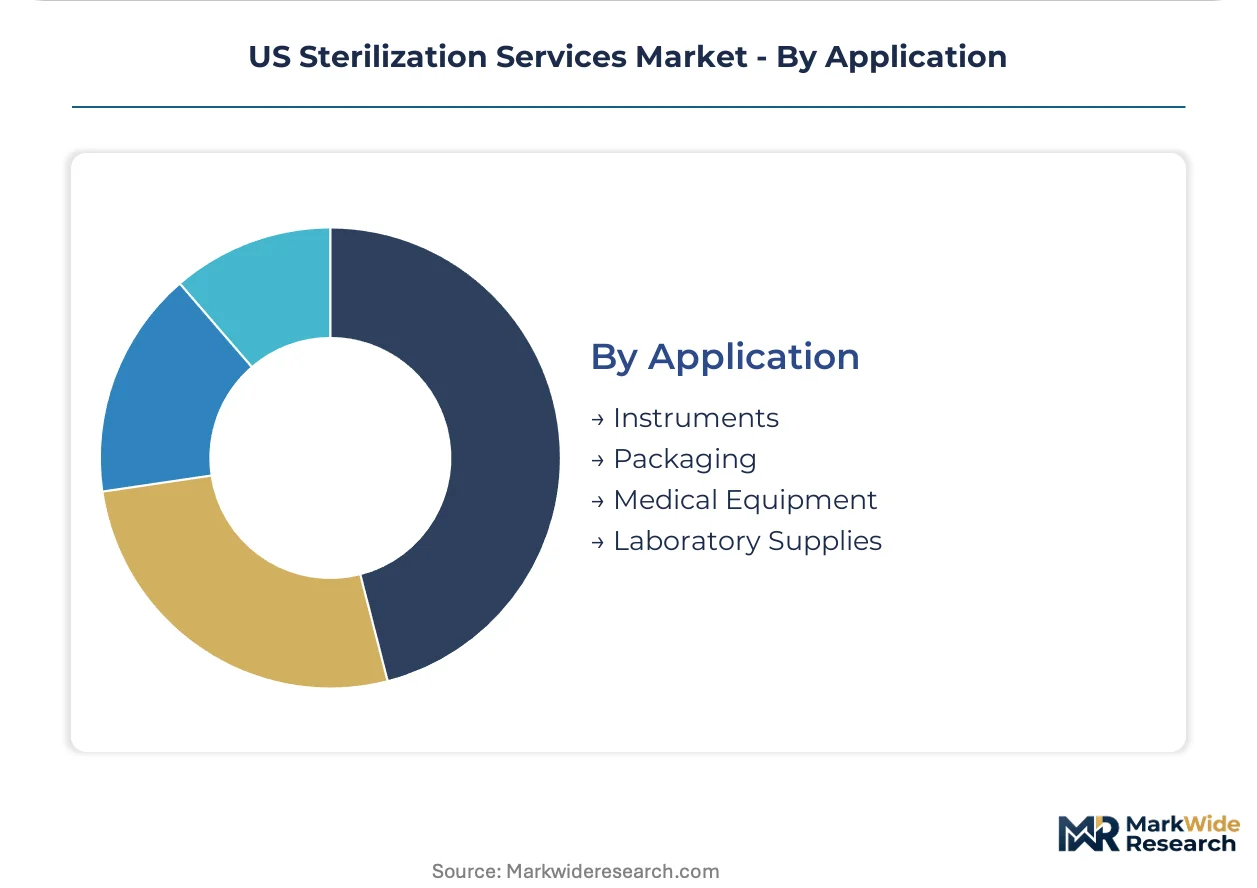
Instrument sterilization anchors revenue scale; packaging applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across US sterilization demand. Hospital systems in saturated Northeast markets negotiate aggressively on contract terms, while Sun Belt ASC clusters absorb premium pricing for proximity advantages.
Texas
Medical device manufacturing corridors in Dallas-Fort Worth and Houston generate concentrated EtO sterilization demand from cardiovascular and orthopedic polymer producers. TCEQ air quality permitting creates extended timelines for new chemical sterilization facility siting. San Antonio's ambulatory surgical center buildouts pull contract sterilization capacity southward along Interstate 35.
Florida
Multi-facility health system consolidation in Miami, Tampa, and Orlando drives single-source vendor agreements bundling multiple sterilization modalities. EPA Region 4 emissions oversight shapes stack monitoring protocols for chemical sterilization operators. Jacksonville's port logistics support pharmaceutical packaging sterilization serving Caribbean and Latin American distribution networks.
California
Bay Area biopharma clusters demand validated gamma and electron-beam sterilization for sterile injectable packaging. CARB emissions regulations impose stricter facility siting constraints than federal EPA baselines. Los Angeles County hospital networks outsource central sterile processing to avoid multi-million dollar ASME pressure vessel compliance upgrades.
Arizona
Phoenix-Tucson ASC corridors lack proximate sterilization capacity, creating logistics premiums for device manufacturers and surgical networks. State environmental permitting moves faster than coastal jurisdictions, attracting defensive facility relocation from Texas and Louisiana chemical corridor operators. Flagstaff and Prescott surgical markets remain underserved by validated third-party sterilization infrastructure.
Ohio
Cleveland and Cincinnati hospital systems anchor Midwest sterilization demand for steam and low-temperature modalities. OSHA Region 5 enforcement of EtO workplace exposure limits pushes remaining in-house chemical sterilization toward outsourced partners. Midwest contract sterilizers pilot X-ray sterilization units for pharmaceutical packaging, displacing cobalt-60 gamma irradiation dependency.
US Sterilization Services Market Key Industry Players
Capability concentration sits with modality-specific specialists; scale advantage sits with integrated full-service platforms. The vendor base splits between ethylene oxide chamber networks, irradiation infrastructure operators, and emerging low-temperature technology providers. Three archetypes dominate: nationwide EtO facility networks, pharmaceutical-focused radiation sterilizers, and electron-beam niche specialists. Competitive moves center on geographic capacity repositioning toward Sun Belt surgical corridors and integrated FDA 510(k) validation bundling for device manufacturers.
Within the full-service platform tier, STERIS anchors nationwide ethylene oxide capacity through multi-state facility networks. Sotera Health exemplifies integrated irradiation and electron-beam positioning for pharmaceutical packaging validation. E-BEAM Services, Inc occupies the electron-beam specialist archetype, serving temperature-sensitive polymer medical device applications where penetration depth constraints exclude gamma alternatives.
| Leading Market Players |
|---|
| Andersen Sterilizers |
| Prince Sterilization Services, LLC |
| STERIS |
| Ecolab Inc. |
| Midwest Sterilization Corporation |
| Sotera Health |
| E-BEAM Services, Inc |
| Cretex Companies |
| ASP (Fortive) |
| Others |
Cost & Logistics Intelligence
Overcapacity in Northeast steam sterilization infrastructure compresses contract pricing for hospital systems while tightening margins for operators, yet Sun Belt undercapacity supports rate premiums as providers absorb logistics savings from proximate facility networks.
Pricing Analysis
Long-term offtake agreements dominate hospital system procurement, with multi-year bundled contracts spanning EtO, gamma, and low-temperature modalities commanding standard rates while spot procurement for surge capacity extracts premium pricing. Price differentiation rests on FDA validation tier and geographic delivery cost, with validated 510(k) bundling for device manufacturers attracting premium positioning against commodity steam sterilization. Cost compression in Northeast hospital outsourcing intensifies as consolidated health systems leverage volume scale against vendor panels. ASC networks in Arizona and Nevada corridors exhibit lowest price sensitivity due to absence of proximate alternatives.
Supply Chain Analysis
Extended payment terms from multi-facility health systems strain working capital for contract sterilizers, accelerating supply-chain finance facility adoption among mid-cap operators. Cobalt-60 isotope supply concentrates in Canada and Russia, while electron-beam accelerator manufacturing anchors in Germany and the United States. Raw material dependencies span petrochemical EtO feedstock, cobalt-60 radioisotope, and hydrogen peroxide reagent supply. Single-source vulnerability in Canadian cobalt-60 processing creates cross-border dependency risk. Distribution runs through regional sterilization hubs serving 150-mile surgical catchment zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US sterilization services market tracks a cyclical recovery pattern as hospital capital expenditure cycles refresh deferred autoclave infrastructure investments and ASC construction absorbs excess capacity from prior expansion waves.
For Market Incumbents: Insulate core EtO capacity through emissions control infrastructure upgrades ahead of EPA permitting tightening, while consolidating vendor relationships with Florida and California health systems through integrated modality bundling. Defensive positioning against X-ray sterilization substitution demands pilot investments in electron-beam penetration limits. Backward integration into cobalt-60 logistics or hydrogen peroxide reagent supply secures input cost control. For New Entrants and Emerging Players: Pursue Arizona and Nevada ASC corridor penetration where sterilization capacity scarcity supports rate premiums and faster state environmental permitting reduces facility siting timelines. Target vaporized hydrogen peroxide validation services for temperature-sensitive robotic surgical instruments as the most penetrable premium tier. Go-to-market positioning through FDA 510(k) documentation bundling for mid-cap orthopedic device manufacturers bypasses incumbent relationship lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electron-beam and X-ray sterilization sub-segments as accelerator manufacturing scales and cobalt-60 dependency diminishes. Long-term viability favors integrated full-service platforms over modality-specific specialists. Acquisition target archetype: regional EtO operators with EPA-compliant emissions infrastructure in Sun Belt growth corridors. Signal to watch: FDA validation protocol shifts favoring radiation-based alternatives over chemical sterilization.| Strategic Initiative | Industry Significance |
|---|---|
| Vaporized Hydrogen Peroxide Validation Investment | FDA protocol development for robotic surgical instruments opens premium service tiers in hospital central sterile processing. |
| Sun Belt Capacity Expansion | Texas and Florida facility investments capture ambulatory surgical center construction and medical device manufacturing corridor demand. |
| X-ray Sterilization Pilot Deployment | Midwest pharmaceutical packaging applications displace cobalt-60 gamma irradiation for mid-density polymer loads. |
| Integrated FDA 510(k) Bundling | Device manufacturers consolidate vendor relationships for combined biocompatibility and sterility assurance documentation. |
| Emissions Control Infrastructure Upgrade | EPA and TCEQ compliance positioning defends EtO facility operating permits in Texas and Louisiana chemical corridors. |
Research Approach
A spread of perspectives from hospital supply chain executives, contract sterilization operations directors, FDA regulatory affairs specialists, and biomedical engineering consultants converged on the working assumptions underpinning demand projections. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) submission databases, EPA emissions compliance records, hospital procurement databases, and GPO contract filings. Bottom-up facility capacity modeling and top-down health system expenditure analysis were triangulated against AAMI ST79 standard implementation timelines.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with sterilization modality segmentation, end-user procurement scale, and geographic surgical volume clusters as core dimensions. CAGRs were derived from facility utilization trajectories, ASC construction permitting data, and device manufacturer sterilization outsourcing rates. Industry-specific forecast inputs incorporated OSHA EtO exposure enforcement patterns and state-level environmental permitting velocity differentials.
Sensitivities concentrate around EPA emissions rulemaking, cobalt-60 supply disruption scenarios, and hospital capital expenditure cycle timing. Forecasts reflect documented assumptions regarding regulatory trajectory and surgical volume migration patterns. Macroeconomic recession, accelerated FDA validation protocol shifts, or breakthrough low-temperature sterilization technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Canada Senior Living Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Tissue Banking Market
Healthcare Services
Medical Billing Outsourcing Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Global Offsite Medical Case Management Market
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
US Healthcare Third-Party Logistics Market
Healthcare Services
Retail Clinics Market