
 Sterilization Technologies Market | 2026-2036
Sterilization Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Technologies Market Outlook
ISO 13485 certification cycles for sterilization service providers is collapsing from twenty-four months to under fourteen months as notified bodies clear pandemic-era backlogs. STERIS leverages its installed base of V-PRO hydrogen peroxide systems to sustain recurring consumables revenue across North American hospital networks. Getinge Group anchors European market presence through centralized sterile supply department automation that integrates sterilization equipment with logistics software.
Sterilization technologies encompass physical and chemical processes that eliminate or deactivate all forms of microbial life, including bacterial endospores, through controlled application of heat, radiation, gas, or plasma at specified parameters such as temperature, pressure, concentration, and exposure duration. These processes serve as critical quality control steps in manufacturing and patient care environments where microbial contamination compromises product safety or clinical outcomes. Steam sterilization dominates equipment-installed base metrics due to decades of operational familiarity and lower capital requirements, while hydrogen peroxide plasma is displacing ethylene oxide in temperature-sensitive medical device applications as residual toxicity scrutiny intensifies. Gamma radiation occupies distinct margin pools in single-use pharmaceutical packaging and implantable device sterilization where penetration depth and dose uniformity requirements exclude thermal or chemical alternatives.
The FDA enforces ethylene oxide emission limits and residual testing protocols under 21 CFR Part 820 quality system regulations, compelling sterilization providers to invest in abatement technology or transition to alternative modalities. EPA oversight of commercial sterilization facility air emissions under the National Emission Standards for Hazardous Air Pollutants shapes site selection and capacity expansion decisions. Stakeholders must monitor regulatory divergence between FDA residual limits and evolving EPA facility permitting to avoid stranded capacity in ethylene oxide-dependent infrastructure.
Market Dynamics
Ethylene oxide residual toxicity scrutiny is compressing validation timelines and forcing modality switches across contract sterilization infrastructure, with FDA emission limits and EPA facility permitting creating divergent compliance burdens that reshape capacity allocation decisions.
Growth Catalysts
- Biologics pipeline expansion:Pharmaceutical manufacturers are scaling sterile processing capacity to accommodate cell and gene therapy manufacturing requirements, driving capital deployment into aseptic fill-finish and terminal sterilization infrastructure.
- 21 CFR Part 820 enforcement:FDA quality system regulations mandate enhanced residual testing protocols that accelerate validation service demand and equipment upgrade cycles across contract sterilization providers.
- German industrial cluster concentration:Central European medical device supply chains anchor sterile processing demand in specialized service hubs that serve cross-border manufacturing networks.
Market Restraints
- Ethylene oxide abatement capex:Catalytic oxidation and thermal scrubber installations impose seven-figure capital burdens per facility, straining mid-tier contract sterilizers with concentrated EtO dependencies.
- Gamma irradiator cobalt-60 supply concentration:Radioisotope sourcing depends on a limited reactor base with geopolitical exposure, creating dose availability risk for pharmaceutical packaging sterilization.
- Hydrogen peroxide material compatibility constraints:Cellulosic and absorbent polymers suffer degradation at plasma process parameters, excluding substantial medical device categories from V-PRO and similar platform adoption.
Strategic Opportunities
- X-ray sterilization modality emergence:High-energy electron beam alternatives to gamma radiation penetrate dense pharmaceutical packaging without isotope dependencies, opening capacity expansion paths for sterilization service providers.
- ISO 13485 certification acceleration:Notified body backlog clearance collapses quality management system approval cycles from twenty-four to fourteen months, enabling faster market entry for sterilization equipment and service vendors.
- Central sterile supply department automation:Hospital networks integrate sterilization equipment with logistics software platforms, creating recurring revenue attachment points for equipment vendors with installed base leverage.
Industry Challenges
- Validation engineering talent scarcity:Sterilization process development and regulatory submission expertise concentrates among experienced practitioners, constraining expansion velocity for emerging service providers.
- Legacy EtO facility reconfiguration timelines:Existing ethylene oxide-dependent infrastructure faces stranded asset risk as EPA National Emission Standards for Hazardous Air Pollutants enforcement tightens, forcing complex site remediation or modality migration decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Technologies Market |
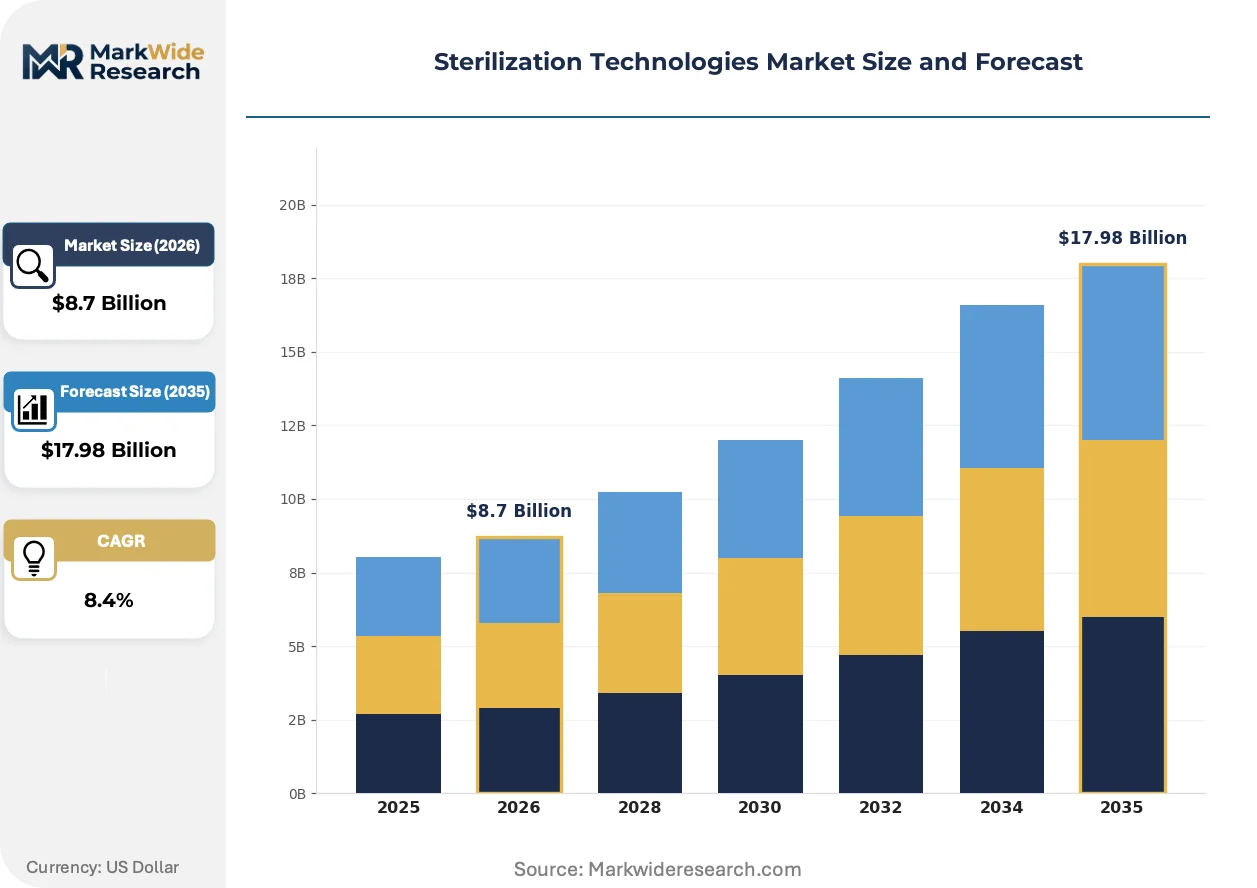
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Steam, Ethylene Oxide, Hydrogen Peroxide, Gamma Radiation Application: Healthcare, Pharmaceuticals, Food Processing, Laboratory End User: Hospitals, Clinics, Manufacturers, Research Institutions Product Type: Equipments, Consumables, Services, Software |
| Companies Covered | STERIS, Sotera Health, Getinge Group, 3M Company, Belimed AG, Advanced Sterilization Products, Ecolab, Nordion Inc., Tuttnauer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Technologies Market Strategic Shifts
Plasma-based modalities and regulatory divergence are actively restructuring competitive positioning across sterilization technology providers, with residual toxicity limits and automation integration defining capability differentiation.
Vaporized hydrogen peroxide sterilization is displacing ethylene oxide in temperature-sensitive medical device applications where polymer compatibility and residual toxicity constraints dominate selection criteria. Cardiovascular implant and drug-eluting stent manufacturers are accelerating platform qualification timelines from thirty-six to eighteen months. This modality shift compresses contract sterilizer margins on legacy EtO-dependent assets while elevating consumables revenue for hydrogen peroxide system vendors with installed base density.
EPA National Emission Standards for Hazardous Air Pollutants oversight of commercial sterilization facility air emissions is tightening facility permitting requirements and abatement technology mandates. Industrial sterilization providers face capital allocation decisions between catalytic oxidation retrofits and site relocation to jurisdictions with divergent enforcement intensity. Contract sterilizers with concentrated ethylene oxide infrastructure in high-enforcement US states are experiencing capacity reallocation toward lower-regulatory-friction geographies or modality transition investments.
Centralized sterile supply department automation is consolidating equipment procurement decisions within integrated health system capital committees. Hospital networks are unbundling sterilization equipment from legacy service contracts and consolidating vendor relationships around platform-agnostic logistics software compatibility. North American acute care networks with multi-facility footprints are driving this procurement pattern shift, prioritizing interoperability and remote monitoring integration over standalone equipment specifications.
Sterilization Technologies Market Segmentation
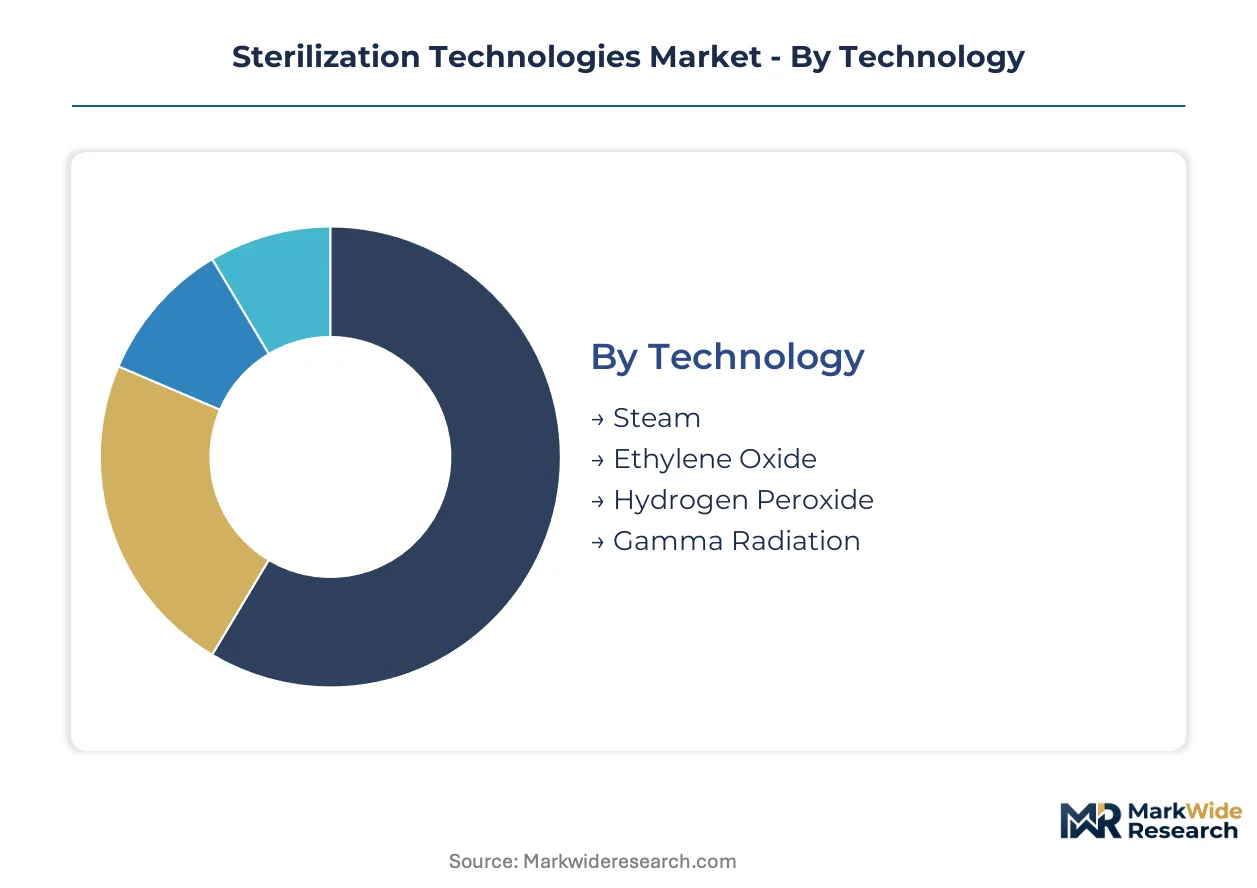
Sterilization technology selection hinges on material compatibility, regulatory load, and throughput economics. Each segmentation dimension reveals distinct procurement patterns and margin structures across healthcare, pharmaceutical, and industrial end uses.
Technology:
FDA residual limits and EPA emission standards create divergent compliance economics across modalities, forcing capital allocation toward lower-regulatory-friction alternatives.
- Steam:Saturated steam under pressure of 15-30 psi achieves 121-134°C temperatures for 15-60 minutes, destroying microbial life through protein denaturation. German industrial sterilization clusters deploy steam systems for Central European medical device supply chains where polymer compatibility constraints exclude alternatives. Steam handles the majority of throughput; hydrogen peroxide is the fastest mover on share.
- Ethylene Oxide:Alkylation chemistry at 30-60°C penetrates complex device geometries and porous packaging, though residual toxicity scrutiny under 21 CFR Part 820 compels abatement investment. Contract sterilizers face stranded asset risk as EPA National Emission Standards enforcement tightens.
- Hydrogen Peroxide:Low-temperature plasma at 45-50°C decomposes into water and oxygen, eliminating residual toxicity concerns for temperature-sensitive cardiovascular implants.
- Gamma Radiation:Cobalt-60 emits 1.17-1.33 MeV photons penetrating dense pharmaceutical packaging with dose uniformity unattainable by surface-dependent methods.
Steam dominates installed base metrics; hydrogen peroxide gains share fastest as EtO regulatory pressure intensifies.
Application:
End-use environments dictate validation complexity and recurring revenue attachment points.
- Healthcare:Acute care networks prioritize central sterile supply department automation integrating sterilization equipment with logistics platforms for multi-facility interoperability.
- Pharmaceuticals:Aseptic fill-finish and terminal sterilization infrastructure scales to accommodate cell and gene therapy manufacturing requirements in US and European biologics corridors.
- Food Processing:Irradiation and thermal methods eliminate pathogens in packaged goods where thermal tolerance permits.
- Laboratory:Research institutions demand flexible sterilization capacity for diverse media and equipment with rapid cycle turnaround.
Healthcare absorbs the largest equipment procurement volume; pharmaceuticals shows the steepest expansion trajectory.
End User:
Customer scale determines capital commitment depth and service contract structure.
- Hospitals:Integrated health system capital committees consolidate vendor relationships around platform-agnostic software compatibility, unbundling equipment from legacy service contracts.
- Clinics:Ambulatory surgical centers favor tabletop sterilizers with minimal facility infrastructure requirements and compressed validation protocols.
- Manufacturers:Medical device and pharmaceutical producers operate captive sterilization capacity or contract with specialized service providers for terminal processing.
- Research Institutions:Academic and government laboratories prioritize cycle flexibility over throughput, accepting higher per-cycle costs for protocol diversity.
Manufacturers command the largest project scale; clinics are expanding capacity most rapidly.
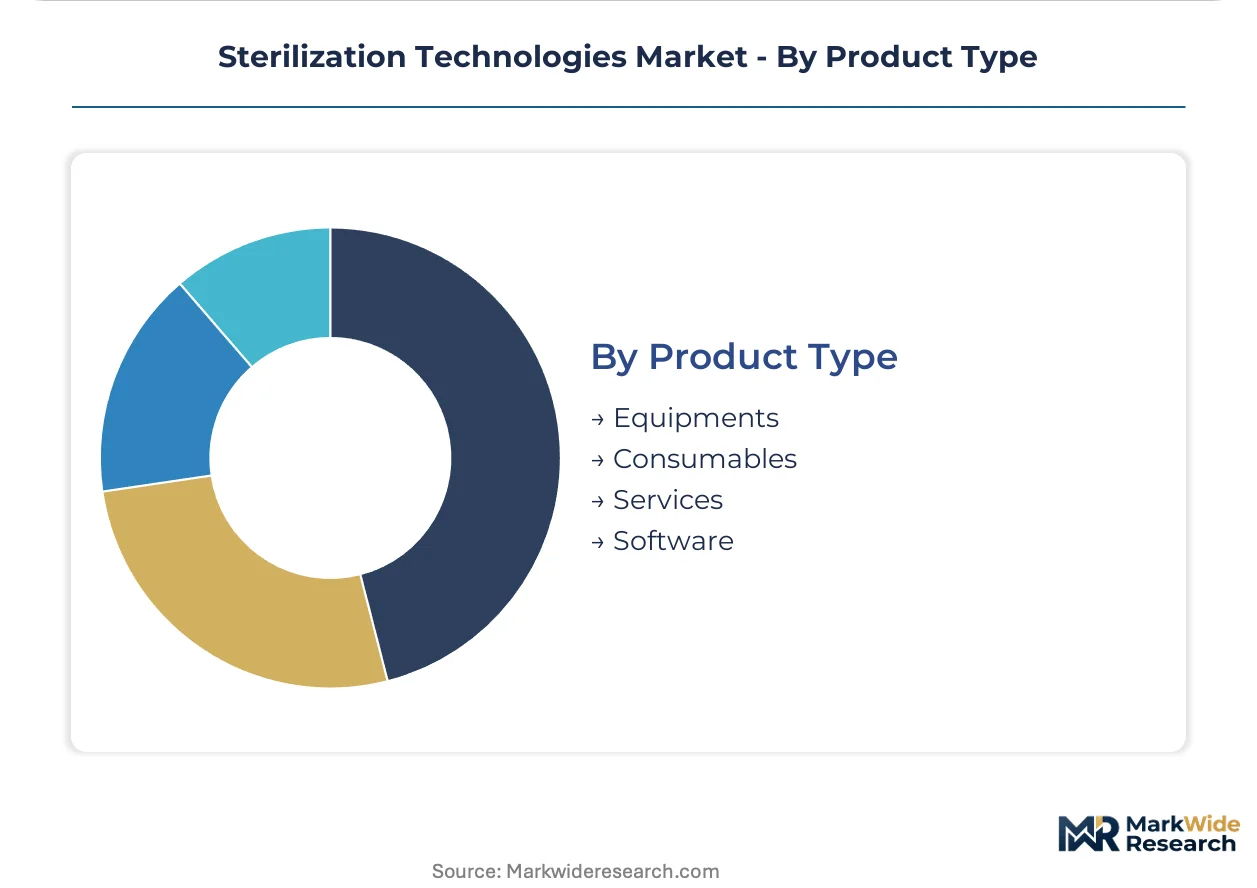
Product Type:
Revenue model differentiation separates capital equipment vendors from recurring revenue platforms.
- Equipments:Autoclaves, sterilizers, and irradiators represent front-loaded capital deployment with 10-15 year replacement cycles, though automation integration is shortening effective economic life.
- Consumables:Hydrogen peroxide cartridges, biological indicators, and chemical integrators generate recurring revenue attachment for vendors with installed base density.
- Services:Contract sterilization providers face margin compression on legacy EtO assets while validation engineering talent scarcity constrains expansion velocity.
- Software:Logistics platforms for sterile supply tracking and remote equipment monitoring create vendor stickiness through interoperability requirements.
Consumables deliver the most predictable revenue streams; software is climbing fastest on share as hospital networks digitize supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers and medical device sterilization service providers concentrate procurement decisions in jurisdictions with aligned FDA and EPA enforcement frameworks. German industrial clusters anchor European demand for validated sterile processing capacity.
United States
Biologics manufacturers in Massachusetts and North Carolina are expanding aseptic fill-finish facilities to accommodate cell therapy production. FDA enforcement of 21 CFR Part 820 quality system regulations compels contract sterilizers to accelerate validation protocol revisions. EtO-dependent facilities in Illinois and California face stranded asset risk as EPA National Emission Standards for Hazardous Air Pollutants enforcement tightens permitting requirements.
Germany
Central European medical device supply chains drive sterile processing demand through specialized industrial service hubs in Baden-Württemberg and Bavaria. EU Medical Device Regulation (MDR) transition deadlines compress notified body certification cycles for sterilization service providers. The Rhine-Main cluster around Frankfurt anchors contract sterilization capacity serving cross-border pharmaceutical packaging networks.
Switzerland
Swissmedic oversight of implantable device sterilization creates premium-tier validation requirements for cardiovascular and orthopedic manufacturers in the Basel-Zurich corridor. REACH chemical safety protocols constrain ethylene oxide residual limits below FDA thresholds. The Lake Geneva region concentrates gamma irradiation capacity for pharmaceutical primary packaging serving EU export markets.
Japan
PMDA quality management system inspections drive sterilization equipment upgrade cycles among domestic pharmaceutical manufacturers. METI industrial standards for hydrogen peroxide plasma systems accelerate modality transitions away from ethylene oxide in temperature-sensitive applications. The Kansai region around Osaka maintains dense concentrations of contract sterilization providers serving medical device exporters.
India
CDSCO medical device rules implementation is expanding formal sterilization service requirements for domestic manufacturers previously reliant on unvalidated processing. PLI scheme incentives for pharmaceutical manufacturing are scaling sterile infrastructure investment in Gujarat and Maharashtra. The Hyderabad-Bangalore corridor anchors emerging contract sterilization capacity serving biosimilar and vaccine producers.
Sterilization Technologies Market Competitive Environment
Player mix skews toward integrated sterilization equipment vendors with recurring consumables revenue streams and specialized contract service providers with concentrated modality dependencies. Market structure exhibits tiered consolidation with premium-tier vendors commanding hospital automation integration contracts and mid-tier operators competing on validation speed and geographic proximity. Two strategic archetypes dominate: hydrogen peroxide platform vendors leveraging installed base density for cartridge revenue, and gamma irradiation specialists managing cobalt-60 supply security. Competitive moves center on modality transition investments and ISO 13485 certification acceleration to capture biologics manufacturing expansion.
Within the integrated equipment tier, STERIS and Getinge Group exemplify platform vendors with hospital network penetration and sterile supply department automation capabilities. Among contract sterilization specialists, Sotera Health occupies a position representing scaled EtO-dependent infrastructure facing regulatory transition pressure. These three anchors illustrate divergent strategic positioning across equipment-versus-service revenue models and legacy-versus-alternative modality exposure.
| Leading Market Players |
|---|
| STERIS |
| Sotera Health |
| Getinge Group |
| 3M Company |
| Belimed AG |
| Advanced Sterilization Products |
| Ecolab |
| Nordion Inc. |
| Tuttnauer |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates above 85% at German industrial sterilization clusters create scale economies that compress per-cycle costs by 20-30% versus fragmented operators, anchoring price floors across Central European contract sterilization markets while forcing smaller competitors toward modality specialization or geographic retreat.
Pricing Analysis
Cost-plus contracts with cobalt-60 price indexation dominate gamma irradiation services, while hydrogen peroxide platform vendors deploy three-tier pricing structure across premium, standard, and economy levels tied to ISO 13485 certification grade and consumables bundling. Price differentiation separates FDA-validated terminal sterilization from basic hospital autoclave cycles, with contract sterilizers in high-EPA-enforcement US states absorbing abatement capex that compresses margins. Cost compression in ethylene oxide-dependent tiers is intensifying because catalytic oxidation retrofits impose seven-figure capital burdens. Ambulatory surgical centers exhibit highest price sensitivity, seeking tabletop systems with minimal validation overhead; pharmaceutical manufacturers show lowest sensitivity, prioritizing regulatory defensibility over unit economics.
Supply Chain Analysis
Strategic stockpiling of cobalt-60 radioisotopes supersedes just-in-time preferences among gamma irradiation operators, with 18-24 month sourcing lead times compelling inventory buffers against reactor maintenance shutdowns. Supply concentrates in Canada, Russia, and South Africa for cobalt-60; Germany, Switzerland, and the United States for precision sterilization equipment; China and India for commodity autoclave components. Raw material dependencies encompass stainless steel pressure vessels, hydrogen peroxide cartridges, biological indicator media, and cobalt-60 sealed sources. Single-source vulnerability in radioisotope supply creates dose availability risk for pharmaceutical packaging sterilization. Distribution runs through specialized logistics networks for sterile goods, with validated cold-chain requirements for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterilization technology markets operate as a defensive-moat industry where regulatory entrenchment creates substantial switching costs: FDA 21 CFR Part 820 validation histories and ISO 13485 certification cycles lock customers into incumbent relationships that extend 10-15 year equipment replacement horizons.
For Market Incumbents: Compound installed base density into recurring consumables revenue by expanding hydrogen peroxide cartridge fulfillment networks across North American hospital systems. Add captive sterilization capacity in low-EPA-enforcement US states or German industrial clusters to escape stranded asset risk from tightening National Emission Standards for Hazardous Air Pollutants enforcement. Acquire validation engineering talent pools to accelerate ISO 13485 certification throughput for biologics manufacturing customers.
For New Entrants and Emerging Players: Differentiate on X-ray sterilization modality qualification to capture gamma irradiation customers seeking cobalt-60 independence. Target Indian CDSCO-regulated domestic manufacturers and contract sterilization providers in the Hyderabad-Bangalore corridor where formal validation requirements are expanding fastest. Deploy equipment-as-a-service models with embedded logistics software to bypass capital committee procurement friction in mid-tier hospital networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hydrogen peroxide platform vendors with hospital network penetration and consumables attachment rates above 60%. Long-term viability favors equipment-software integrated players over pure-service contract sterilizers facing modality transition capex. Watch EPA permitting velocity in Illinois and California as the inflection signal: accelerated enforcement triggers stranded asset revaluations across EtO-dependent infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Modality Transition Investment | Shifts capacity from EtO to hydrogen peroxide or X-ray to escape EPA emission limits. |
| ISO 13485 Certification Acceleration | Collapses quality system approval cycles from twenty-four to fourteen months for faster market entry. |
| Central Sterile Supply Automation | Integrates STERIS or Getinge equipment with hospital logistics platforms for recurring revenue. |
| Cobalt-60 Supply Security Program | Secures radioisotope sourcing contracts with Canadian or Russian reactor operators. |
| Biologics Corridor Capacity Expansion | Builds terminal sterilization infrastructure in Massachusetts or North Carolina cell therapy clusters. |
Study Parameters
Operator-level perspectives from sterilization service directors, biomedical engineers at hospital purchasing committees, GPO contracts managers, and regulatory affairs leads at pharmaceutical manufacturers anchored the qualitative base. Primary interview findings triangulated against FDA 510(k) filings, EPA enforcement action databases, ISO certification registries, and hospital procurement contract disclosures. Secondary validation drew from SEC 10-K equipment vendor disclosures, notified body certification timelines, and trade data on cobalt-60 imports. Bottom-up capacity modeling across 12 countries converged with top-down spend analysis by end-use sector.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity scenarios and modality transition speed assumptions throughout the projection horizon. The analytical framework modeled technology, application, end user, and product type segmentation alongside regulatory jurisdiction clusters. CAGRs derived from installed base replacement cycles, biologics pipeline expansion rates, and EPA permitting velocity assumptions. Industry-specific inputs encompassed hydrogen peroxide material compatibility constraints and gamma irradiator dose uniformity requirements for dense pharmaceutical packaging.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820 enforcement and EPA National Emission Standards frameworks; material policy shifts would require re-modeling capacity allocation and modality transition timelines. Revision becomes warranted when EPA permitting denial rates in high-enforcement states cross thresholds that trigger accelerated EtO facility closures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Global Viral Clearance Services Market
Infection Control
Antimicrobial Suture Market
Infection Control
Hospital Acquired Infections Therapeutic Market
Infection Control
Infection Control Market
Infection Control
Disinfection Cupboard Market
Infection Control
Hand Hygiene Products Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Ear Infection Treatment Market
Infection Control
Sanitizers Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Denture Disinfectants Market
Infection Control
Medical Activated Carbon Dressing Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Intra-Abdominal Infection Treatment Market