
 Medical Billing Outsourcing Market | 2026-2036
Medical Billing Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Billing Outsourcing Market Analysis
Indian revenue cycle management talent pools are decoupling from domestic healthcare infrastructure and serving North American providers at scale. Access Healthcare anchors large-scale operations across multiple delivery centers in South Asia. Athenahealth competes through cloud-native platforms that integrate eligibility verification with real-time claim scrubbing. CareCloud differentiates by targeting ambulatory practices with modular service tiers.
Medical billing outsourcing encompasses the delegation of revenue cycle functions—including patient registration, charge capture, claim submission, payment posting, and denial management—to third-party specialists operating under defined service-level agreements. These arrangements typically leverage HIPAA-compliant data transmission protocols and ICD-10 coding standards to ensure regulatory adherence while reducing days in accounts receivable. Claims management services command the deepest expertise premiums due to payer-specific adjudication complexity and escalating denial rates. Cloud-based technology deployments are expanding fastest among mid-sized physician groups seeking to avoid capital-intensive infrastructure investments. Hybrid solutions retain relevance for large health systems managing legacy electronic health record architectures alongside modern platforms.
HIPAA privacy and security rules govern all protected health information exchanges between covered entities and business associates, mandating encrypted transmission channels and breach notification protocols. CMS reimbursement policies, including the No Surprises Act implementation, reshape claim accuracy requirements and patient financial responsibility workflows. The FDA maintains indirect oversight through software-as-a-medical-device guidance that affects clinical decision support embedded within billing platforms. Stakeholders must monitor evolving state-level balance billing prohibitions and their downstream effects on collections strategy and vendor accountability frameworks.
Market Dynamics
Payer contract complexity under CMS value-based care mandates is fragmenting revenue cycle expertise across hospital systems, forcing specialization into external vendors who can absorb denial management volatility and ICD-10 coding density at scale.
Growth Catalysts
- No Surprises Act enforcement:CMS patient financial responsibility rules are expanding the need for specialized vendor networks that can reconcile out-of-network billing prohibitions with accurate cost estimation workflows.
- Cloud-native platform adoption:Mid-sized physician groups are abandoning capital-intensive server infrastructure for subscription-based eligibility verification and real-time claim scrubbing architectures.
- India-based talent arbitrage:South Asian delivery centers are decoupling from domestic healthcare infrastructure to serve North American providers with HIPAA-compliant coding operations at scale.
Market Restraints
- Data sovereignty requirements:State-level patient data residency laws in the United States are constraining cross-border workflow distribution and inflating compliance architecture costs.
- Cyber insurance premium spikes:Breach notification mandates under HIPAA security rules are driving up operational overhead for business associates managing PHI transmission channels.
- Legacy EHR integration friction:Hybrid environments combining modern cloud platforms with aging hospital information systems are extending implementation timelines and inflating customization costs.
Strategic Opportunities
- Specialty practice penetration:Ambulatory surgery centers and independent diagnostic facilities remain underserved by modular service tiers designed for high-volume hospital systems.
- AI-augmented denial prediction:Machine learning models trained on payer-specific adjudication patterns are converging with robotic process automation to compress days in accounts receivable.
- Rural health system consolidation:Critical access hospitals facing administrative burden concentration are prime targets for turnkey revenue cycle partnerships with guaranteed collection rate floors.
Industry Challenges
- Coding certification scarcity:AIC and CPC credential pipelines are failing to match demand for specialized oncology and surgical procedure coders, inflating wage premiums.
- Interoperability standard fragmentation:FHIR implementation gaps between vendor platforms are forcing expensive middleware development for health systems running multiple EHR architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Billing Outsourcing Market |
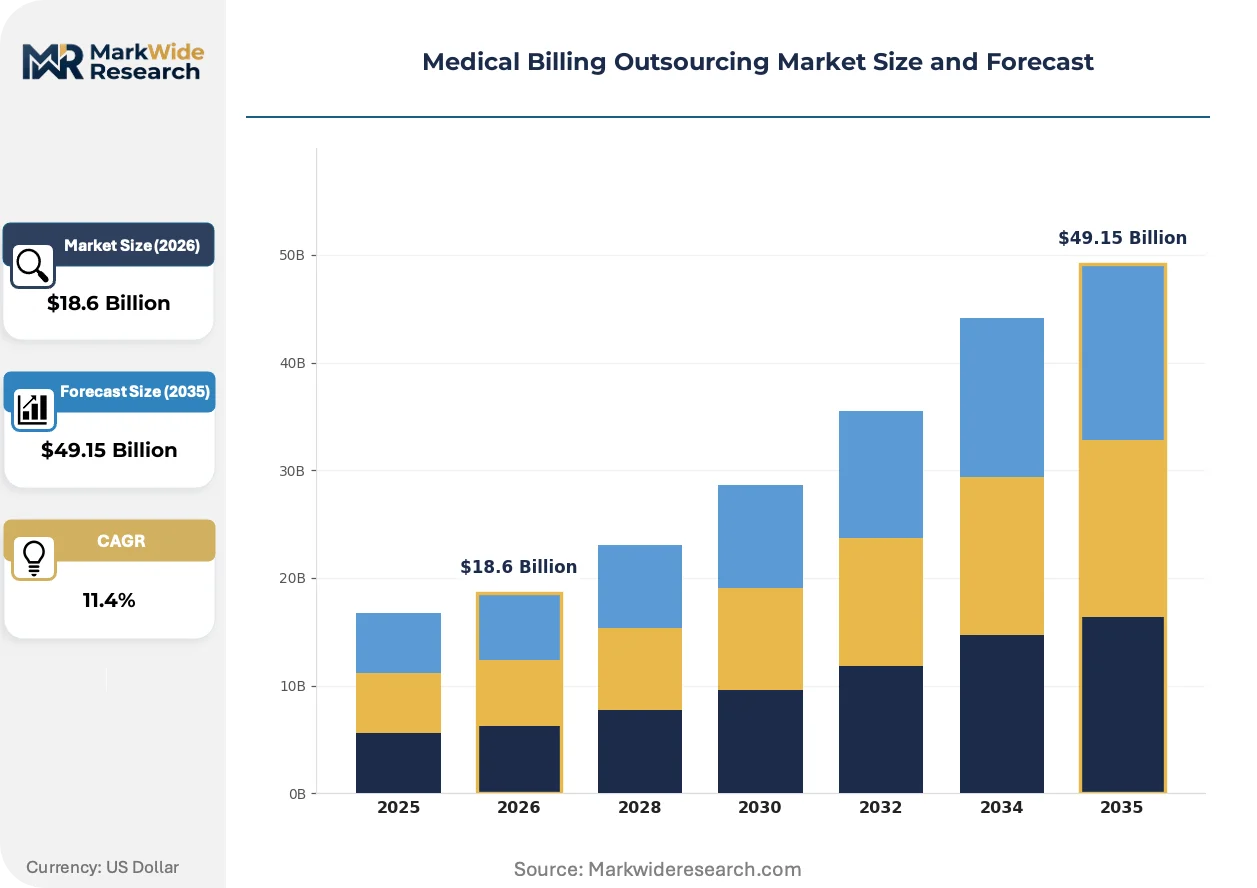
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $49.15 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Patient Billing, Charge Entry, Payment Posting, Claims Management End User: Hospitals, Clinics, Physician Groups, Diagnostic Labs Technology: Cloud-Based, On-Premises, Hybrid Solutions, Electronic Health Records Client Type: Small Practices, Large Practices, Integrated Health Systems, Third-Party Administrators |
| Companies Covered | CareCloud, Access Healthcare, Transcure, CureMD, Promantra, ChartLogic, AdvancedMD, Practolytics, Athenahealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Billing Outsourcing Market Emerging Trajectories
Revenue cycle automation is compressing the boundary between clinical documentation and financial capture, embedding coding intelligence directly into provider workflows rather than treating billing as a downstream administrative function.
Natural language processing engines trained on clinical notes are converging with automated code suggestion algorithms to reduce manual abstraction labor. Large health systems with integrated EHR deployments are piloting these tools in emergency departments where documentation speed directly affects claim completeness. The technology is converging with existing charge capture workflows to eliminate revenue leakage from missed procedure documentation.
CMS price transparency mandates are forcing hospitals to publish machine-readable files of payer-negotiated rates, exposing reimbursement variation that vendors must now model in patient cost estimation tools. The regulation is reshaping how outsourcing contracts structure performance guarantees around point-of-service collections. Ambulatory practices in competitive metropolitan markets are responding fastest by embedding real-time eligibility verification into scheduling workflows.
Subscription pricing for revenue cycle software is displacing traditional percentage-of-collections fee structures among independent physician associations. Buyers are demanding fixed-cost predictability as denial rates fluctuate under evolving payer policies. This procurement recalibration is most visible in the southeastern United States where private equity-backed practice rollups are standardizing vendor selection across multi-state networks.
Medical Billing Outsourcing Market Segmentation
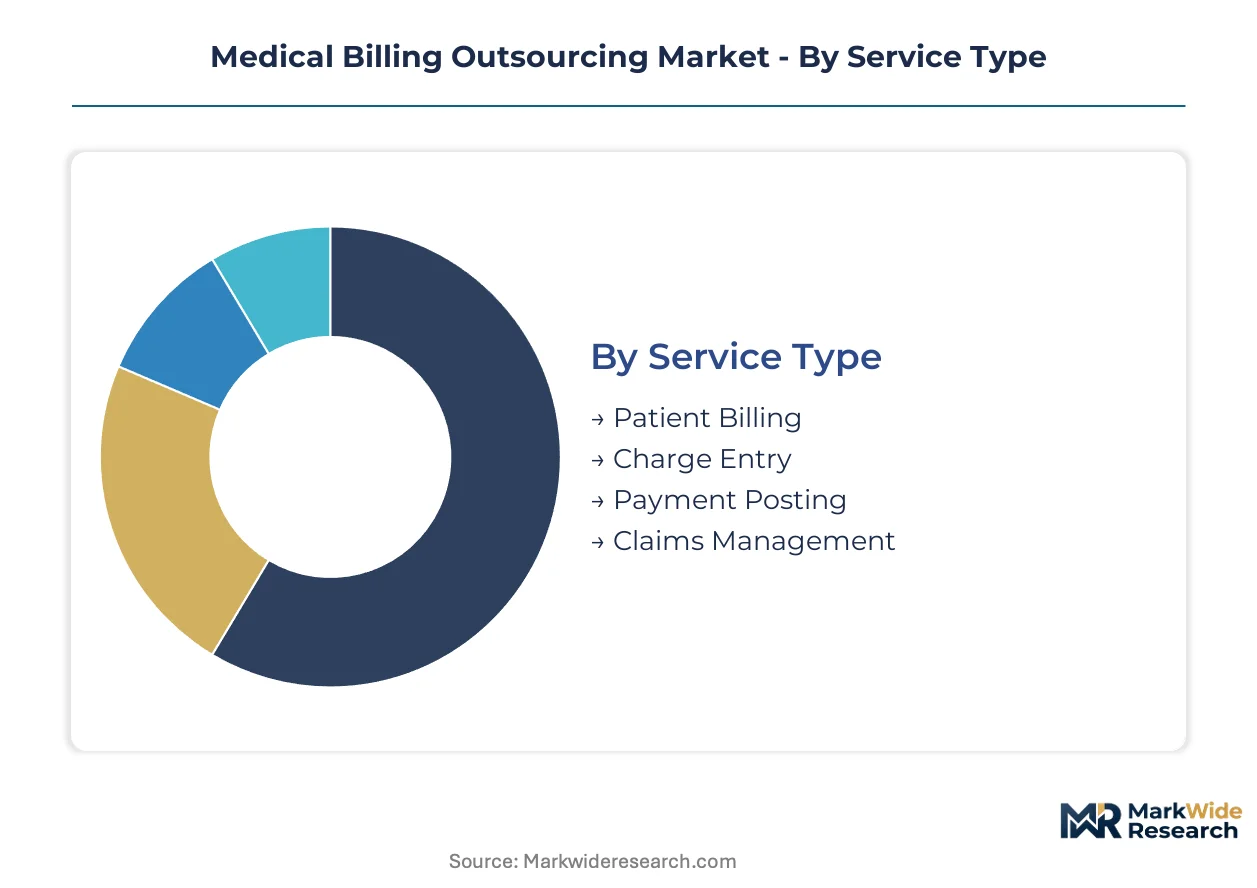
Revenue cycle outsourcing vendors configure service architectures around four distinct axes: technical delivery mode, institutional scale, clinical setting, and payer interaction complexity. Each segmentation dimension shapes pricing mechanics, compliance architecture, and talent deployment geography.
Service Type:
Complexity of payer adjudication pathways determines which functions health systems retain versus delegate.
- Claims Management:Payer-specific denial pattern analysis and appeal workflows demand specialized coders with AAPC credentials. United States hospitals facing CMS value-based care mandates concentrate procurement here due to escalating denial rates under ICD-10-CM specificity requirements.
- Patient Billing:Cost estimation and financial counseling workflows integrate with hospital information systems to reduce bad debt exposure. Demand concentrates in metropolitan markets where the No Surprises Act compliance burden heaviest.
- Charge Entry:Procedure-to-code mapping with modifier application for surgical encounters.
- Payment Posting:ERA/EFT reconciliation and contractual allowance calculation.
Volume sits with Claims Management; growth tilts toward Patient Billing.
End User:
Capital intensity and EHR maturity separate buyers with in-house capability from those requiring full outsourcing.
- Hospitals:Enterprise revenue cycle operations spanning inpatient, outpatient, and emergency department encounters. These institutions leverage India-based delivery centers for overnight coding throughput while retaining domestic staff for patient-facing financial counseling.
- Physician Groups:Ambulatory practices with 10-50 providers seek modular service tiers avoiding percentage-of-collections fees. Subscription pricing models are displacing traditional arrangements fastest in private equity-backed rollups across the southeastern United States.
- Clinics:Federally qualified health centers and urgent care chains with limited IT infrastructure.
- Diagnostic Labs:High-volume, low-complexity coding environments with molecular pathology exceptions.
Procurement concentration favors Hospitals; Physician Groups are expanding most quickly.
Technology:
Infrastructure ownership preferences split buyers between capital avoidance and data sovereignty requirements.
- Cloud-Based:Subscription architectures with API-first eligibility verification and real-time claim scrubbing. Mid-sized practices in competitive metropolitan markets adopt fastest to avoid server maintenance overhead.
- Hybrid Solutions:Combinations of cloud-native platforms with legacy hospital information system bridges. Large health systems with Epic or Cerner deployments spanning decades use these to phase migration without operational disruption.
- On-Premises:Dedicated server installations for critical access hospitals with unreliable broadband infrastructure.
- Electronic Health Records:Native billing modules within integrated EHR deployments.
Deployment volume clusters with Hybrid Solutions; Cloud-Based adoption is climbing the fastest.
Client Type:
Organizational scale and payer contract complexity dictate service-level agreement structures.
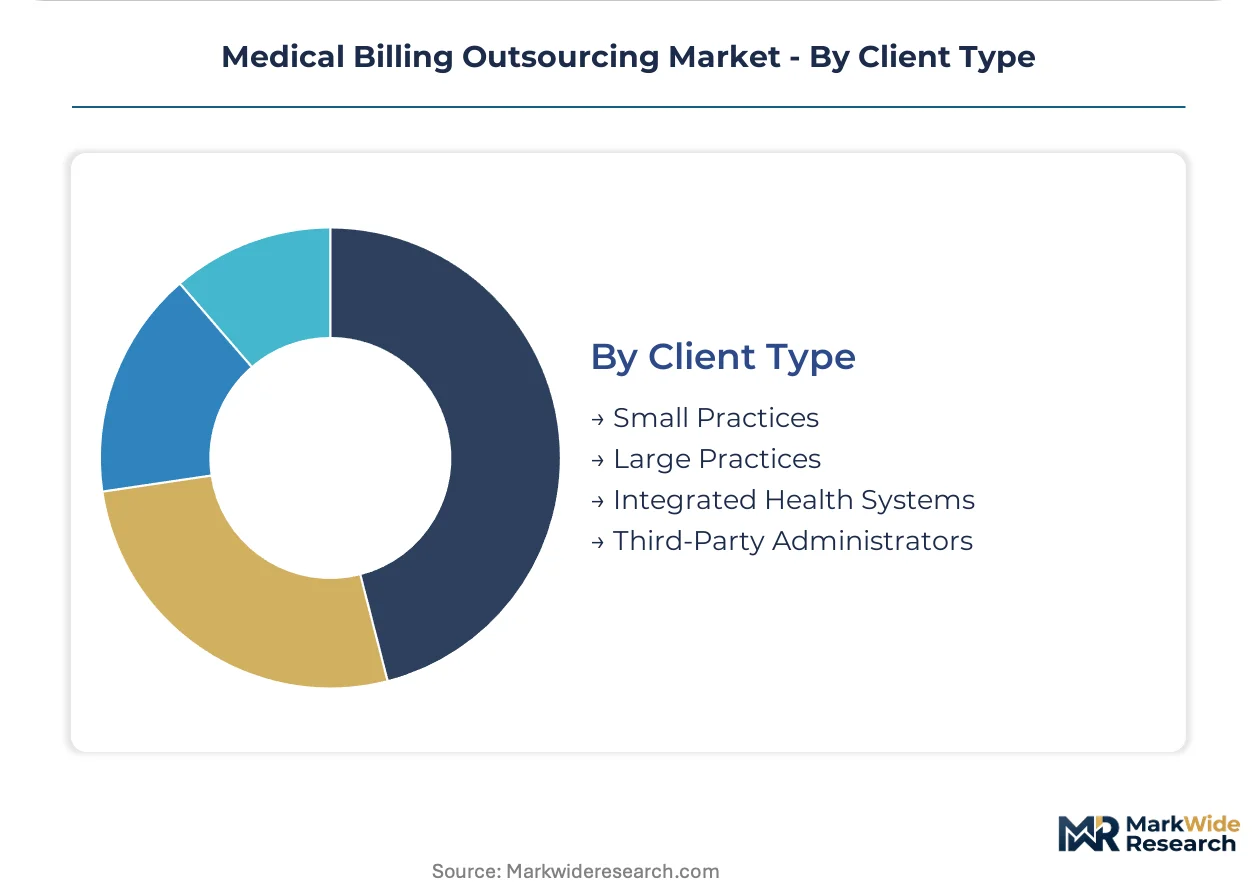
- Integrated Health Systems:Multi-hospital networks with centralized revenue cycle operations spanning multiple states. These buyers demand guaranteed collection rate floors and dedicated account management teams.
- Third-Party Administrators:Self-funded employer health plan administrators requiring out-of-network negotiation and balance billing compliance expertise under the No Surprises Act.
- Large Practices:Single-specialty groups with 50+ providers and complex surgical coding needs.
- Small Practices:Solo and small-group primary care with standardized CPT code patterns.
Contract value concentrates with Integrated Health Systems; Third-Party Administrators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized labor pools in South Asia and cloud infrastructure investments in North American metropolitan hubs anchor geographic deployment patterns for revenue cycle services.
United States
Administrative burden concentration and payer contract fragmentation drive outsourcing intensity. HIPAA security rules and CMS value-based care mandates reshape vendor accountability frameworks. Delivery centers in Dallas-Fort Worth and Phoenix host domestic coding operations for large health systems seeking overnight turnaround.
India
AIC and CPC credential pipelines supply specialized coders for North American claims adjudication. The country's IT services regulatory environment accommodates HIPAA-compliant data transmission protocols. Chennai and Hyderabad delivery centers process high-volume hospital billing for US integrated health systems.
Philippines
English-language proficiency and US-aligned healthcare education support patient-facing financial counseling operations. Data privacy regulations under the National Privacy Commission govern cross-border PHI handling. Metro Manila clusters concentrate payment posting and eligibility verification workflows for mid-sized physician groups.
Canada
Provincial health system structures limit domestic outsourcing scope while generating specialized cross-border expertise. Health Canada oversight of medical device billing intersects with US reimbursement workflows. Toronto-area vendors serve American ambulatory surgery centers seeking bilingual patient communication capabilities.
Ireland
EU data residency requirements and GDPR compliance architecture attract hybrid delivery models serving European and North American clients. The country's pharmaceutical regulatory alignment with FDA standards supports clinical trial billing specialization. Dublin hosts European headquarters for US-based revenue cycle platforms managing multi-jurisdictional deployments.
Medical Billing Outsourcing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-augmented denial prediction and specialty practice penetration. The vendor base stratifies across three tiers: large-scale India-based delivery networks, cloud-native platform specialists, and modular service providers targeting ambulatory segments. Competitive positioning hardens around M&A consolidation of regional coding boutiques and strategic partnerships embedding billing intelligence into EHR workflows.
Among cloud-native platform specialists, Athenahealth exemplifies subscription-based eligibility verification architectures. Access Healthcare anchors large-scale delivery center operations across South Asia. CareCloud occupies a position within the modular service tier targeting private equity-backed physician rollups. These three represent distinct strategic archetypes: platform-centric automation, labor arbitrage at scale, and segmented service modularity.
| Leading Market Players |
|---|
| CareCloud |
| Access Healthcare |
| Transcure |
| CureMD |
| Promantra |
| ChartLogic |
| AdvancedMD |
| Practolytics |
| Athenahealth |
| Others |
Supply Flow & Price Mechanics
CPC-credentialed labor arbitrage from South Asian delivery centers feeds directly into tiered service pricing, with HIPAA-compliant coding throughput commanding premium rates against domestic-only alternatives while mid-sized physician groups absorb subscription SaaS tiers to avoid capital deployment.
Pricing Analysis
Service bundling separates claims management with denial appeal warranties from unbundled charge entry modules, with the former capturing recurring subscription commitments. Three-tier pricing structure across premium, standard, and economy levels differentiates by AAPC certification density and after-hours coverage scope. Pricing pressure stems from private equity-backed practice rollups demanding fixed-cost predictability over percentage-of-collections models. Ambulatory surgery centers exhibit highest price sensitivity; integrated health systems with guaranteed collection rate floors show lowest.
Supply Chain Analysis
Domestic-content mandates for patient-facing financial counseling constrain cross-border workflow distribution, reshaping vendor geographic deployment. Supply concentrates in India for overnight coding throughput, the Philippines for English-language patient communication, and domestic delivery centers in Dallas-Fort Worth and Phoenix for same-day turnaround. Raw material dependencies center on AAPC-certified talent pipelines, encrypted PHI transmission infrastructure, and API-first EHR integration middleware. Single-source vulnerability sits with concentrated South Asian credential supply. Distribution runs through direct enterprise sales to health systems alongside channel partnerships with EHR platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as cyber insurance premium spikes and data sovereignty compliance costs force sub-scale regional coding boutiques toward acquisition.
For Market Incumbents: Acquire specialty-specific coding boutiques with oncology and surgical procedure expertise to absorb denial management volatility. Consolidate India-based delivery center networks to achieve HIPAA-compliant scale economies against emerging AI-augmented entrants. Channel control through embedded EHR partnerships offers defensive leverage against platform-native competitors. For New Entrants and Emerging Players: Capture rural critical access hospitals facing administrative burden concentration without existing vendor relationships. Target ambulatory surgery centers and independent diagnostic facilities underserved by modular service tiers designed for high-volume hospital systems. Lead with AI-augmented denial prediction as a differentiated go-to-market wedge against legacy labor-arbitrage models. For Investors and Strategic Acquirers: Accelerating M&A consolidation of regional coding boutiques is the leading indicator that vendor accountability frameworks are hardening around guaranteed collection rate floors. Long-term viability favors platforms with hybrid cloud-native and legacy EHR integration capabilities spanning the full provider spectrum. Watch for inflection when AI-augmented denial prediction compresses days in accounts receivable below human-only benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Regional Coding Boutiques | Consolidates specialized oncology and surgical procedure expertise under unified HIPAA-compliant delivery architectures. |
| AI-Augmented Denial Prediction Deployment | Machine learning models trained on payer-specific adjudication patterns compress days in accounts receivable. |
| EHR Platform Integration Partnership | Embedding billing intelligence directly into Epic and Cerner workflows eliminates revenue leakage from documentation gaps. |
| India Delivery Center Expansion | Chennai and Hyderabad operations absorb overnight coding throughput for US integrated health systems at scale. |
| Rural Health System Turnkey Partnership | Critical access hospitals receive guaranteed collection rate floors addressing administrative burden concentration. |
Methodological Framework
CMS Medicare cost reports, hospital procurement databases, and GPO contracts formed the secondary backbone for market sizing and validation. Primary interviews with revenue cycle directors, HIPAA compliance officers, AAPC-certified coding managers, and health system CFOs combined with secondary triangulation to establish operational benchmarks. Bottom-up segmentation modeling across service type, end user, technology deployment, and client scale converged with top-down macro validation.
Historical trendline analysis of revenue cycle outsourcing penetration rates informed projection mechanics across the analysis window. Segmentation dimensions modeled include service complexity tier, institutional scale, EHR integration architecture, and geographic delivery concentration. CAGRs derive from fitted growth curves adjusted for payer policy volatility and technology adoption S-cycles. Forecast inputs incorporate denial rate trajectories under ICD-10-CM specificity requirements and cloud-native platform subscription conversion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS value-based care mandate acceleration and state-level data sovereignty law proliferation. Analytical boundaries exclude clinical trial billing and pharmaceutical revenue cycle operations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Long Term Care Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
US Medical Billing Outsourcing Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
Medical Transcription Services Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Sterilization Services Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
Global Ambulatory Services Market