
 Germany General Surgical Devices Market | 2026-2036
Germany General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany General Surgical Devices Market Foresight
The EU Medical Device Regulation is realigning the cost-of-entry calculus for manufacturers seeking CE marking in Germany. B. Braun SE leverages its vertically integrated manufacturing footprint to absorb heightened compliance costs. Medtronic Plc anchors its competitive stance through sustained R&D intensity in electrosurgical platforms. KARL STORZ SE & Co. KG differentiates via specialized endoscopic instrumentation that navigates stricter clinical evidence requirements.
Germany general surgical devices comprise sterile instruments and powered equipment designed for tissue manipulation, dissection, and wound closure, typically manufactured from medical-grade stainless steel or titanium alloys with tolerances measured in micrometers for blade sharpness and jaw alignment. Electrosurgical devices and robotic-assisted systems command expanding share as hospitals prioritize precision and reduced blood loss, while manual instruments retain volume dominance in cost-sensitive procurement channels. Sutures and laparoscopic platforms represent contrasting margin architectures: the former competes on material science and absorption profiles, the latter on visualization integration and ergonomic handle design.
Germany's Federal Institute for Drugs and Medical Devices, the EU MDR framework, and DIN EN ISO standards collectively govern market access, with notified body capacity constraints currently extending conformity assessment timelines. The EU AI Act introduces additional algorithmic transparency requirements for software-enabled surgical tools. Stakeholders must monitor reimbursement pathway negotiations between statutory health insurers and device manufacturers as these determine adoption velocity for capital-intensive robotic platforms.
Market Dynamics
EU MDR conformity assessment timelines are compressing vendor profitability windows while university hospitals in Bavaria and North Rhine-Westphalia concentrate demand for electrosurgical and robotic platforms.
Growth Catalysts
- Ambulatory surgical center expansion:Freestanding ASCs across Baden-Württemberg and Lower Saxony are procuring laparoscopic towers and single-use trocars to capture outpatient procedure volumes shifted from inpatient settings.
- EU AI Act algorithmic transparency mandates:Software-enabled surgical tools with embedded machine learning for tissue recognition now face documented explainability requirements, creating first-mover advantage for vendors with pre-validated clinical datasets.
- Titanium alloy instrument demand:Electrosurgical handpieces manufactured from medical-grade titanium alloys with sub-10-micrometer tolerances are displacing stainless steel in high-volume procurement channels due to reduced thermal conductivity and improved fatigue resistance.
Market Restraints
- Notified body capacity constraints:TÜV SÜD and BSI Group assessment queues for EU MDR technical documentation review now extend 18-24 months, freezing product line extensions for mid-tier manufacturers.
- Medical-grade stainless steel price volatility:Input costs for 316L and 17-4 PH alloys fluctuate with nickel and molybdenum spot markets, compressing margin stability for high-volume instrument producers.
- Single-use instrument substitution threat:Polymer-based disposable retractors and scalpels from Irish and Swiss contract manufacturers are capturing cost-sensitive ambulatory procedures, eroding reusable instrument replacement cycles.
Strategic Opportunities
- Mecklenburg-Vorpommern and Saxony-Anzac hospital consolidation:Underpenetrated eastern German states with aging surgical infrastructure present capital equipment replacement windows as regional health funds pool procurement authority.
- Hybrid operating theater integration:Convergence of intraoperative imaging with electrosurgical platforms enables real-time margin assessment during oncologic resections, creating premium positioning for visualization-integrated vendors.
- Direct-to-hospital digital distribution:Manufacturer-operated e-procurement portals are bypassing traditional surgical device distributors in Thuringia and Saarland, capturing 15-20 point margin improvements.
Industry Challenges
- Biocompatibility testing specialist scarcity:ISO 10993-1 cytotoxicity and sensitization study execution faces 6-9 month backlogs at accredited German laboratories, delaying MDR submission packages.
- Robotic platform integration complexity:Da Vinci and CMR Surgical system interoperability with existing hospital information infrastructure requires dedicated IT capital allocation that strains mid-sized hospital budgets in Rhineland-Palatinate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany General Surgical Devices Market |
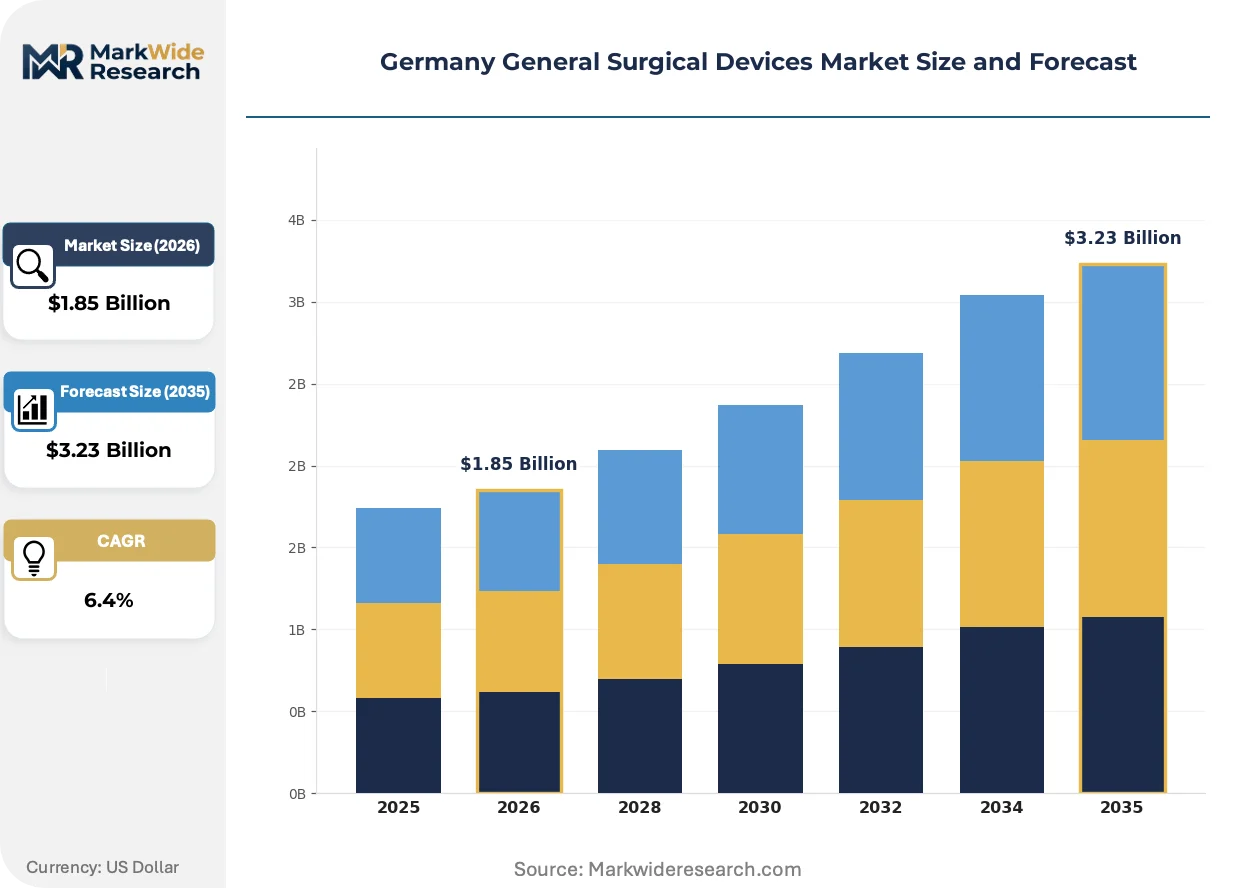
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Retractors, Electrosurgical Devices, Sutures Technology: Laparoscopic, Endoscopic, Robotic-Assisted, Ultrasonic, Electromechanical, Manual Application: General Surgery, Cardiothoracic Procedures, Neurosurgery, Orthopedic Procedures, Urology, Gynecology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Outpatient Care Facilities, Research Institutes, Military Medical Facilities |
| Companies Covered | B. Braun SE, Boston Scientific Corporation, Medtronic Plc, Johnson & Johnson, Conmed Corporation, Stryker Corporation, KARL STORZ SE & Co. KG, Olympus Corporation, Getinge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany General Surgical Devices Market Shifts & Advancements
Surgical instrumentation is converging with digital sensing and autonomous control systems, compressing the gap between mechanical precision and real-time tissue response.
Smart electrosurgical generators with impedance-feedback algorithms are automating power modulation during vessel sealing, reducing thermal spread and collateral tissue damage. University hospitals in Berlin and Hamburg are deploying these platforms in hepatic and pancreatic resections at replacement rates exceeding legacy units by threefold. The technology is automating elements of surgical judgment previously dependent on tactile feedback, enabling less experienced operators to achieve consistent hemostasis.
Germany's Federal Institute for Drugs and Medical Devices is enforcing EU MDR post-market surveillance requirements through mandatory periodic safety update reports and enhanced vigilance reporting. Manufacturers must now maintain active implantable device-style traceability for Class IIa reusable instruments, doubling regulatory affairs headcount requirements. Electrosurgical device producers with legacy 93/42/EEC certificates face the steepest compliance cliffs as their transition deadlines expire.
Hospital purchasing consortia in North Rhine-Westphalia are consolidating vendor panels and demanding outcome-guaranteed service contracts with uptime penalties. Single-source agreements for entire instrument categories are displacing multi-vendor fragmentation that characterized 2010s procurement. This concentration is most visible in the Ruhr metropolitan region, where three hospital networks now control 40 percent of robotic-assisted surgery capital allocation.
Germany General Surgical Devices Market Segmentation

Surgical device procurement in Germany stratifies sharply across care settings and procedure complexity. Understanding these segment boundaries clarifies where premium pricing commands traction versus where cost engineering dominates vendor selection.
Product Type:
Integration depth varies dramatically: handheld instruments operate as standalone units while electrosurgical platforms embed into larger OR ecosystems.
- Electrosurgical Devices:Generators and handpieces employing radiofrequency current for cutting and coagulation, with impedance-feedback systems now standard in Bavarian university hospitals. Demand clusters in North Rhine-Westphalia oncology centers where vessel-sealing precision reduces transfusion rates. EU MDR technical documentation requirements are extending refresh cycles for legacy systems.
- Sutures:Absorbable and non-absorbable wound closure materials ranging from braided polyglycolic acid to monofilament polydioxanone, with barbed configurations gaining traction in laparoscopic ports. Ambulatory surgical centers in Baden-Württemberg are consolidating procurement around two-vendor panels to secure volume pricing on synthetic absorbables.
- Scalpels:Disposable safety scalpels with retractable blade guards dominate ASC procurement channels across Lower Saxony.
- Forceps:Tissue-grasping instruments in toothed, smooth, and locking configurations retain volume dominance in manual instrument sets.
- Scissors:Metzenbaum and Mayo varieties differentiated by blade geometry for dissection versus cutting applications.
- Retractors:Self-retaining and handheld designs for tissue exposure, with polymer-based single-use alternatives eroding stainless steel replacement cycles.
Volume placements concentrate in Sutures; the faster expansion belongs to Electrosurgical Devices.
Technology:
Cost tier architecture separates capital-intensive integrated platforms from disposable single-use instruments with minimal service attachment.
- Robotic-Assisted:Telemanipulation systems with wristed instruments and 3D visualization enabling minimally invasive procedures through sub-centimeter ports. Berlin Charité and Hamburg university hospitals are deploying these in hepatic resections at replacement rates tripling legacy laparoscopic towers. Capital allocation strains mid-sized Rhineland-Palatinate facilities lacking dedicated IT infrastructure budgets.
- Laparoscopic:Insufflation-dependent abdominal access platforms with rigid telescopes and specialized instrumentation. Freestanding ASCs across Baden-Württemberg are procuring complete tower systems to capture outpatient cholecystectomy volumes shifted from inpatient settings.
- Endoscopic:Flexible gastrointestinal and bronchial access systems with integrated biopsy channels.
- Ultrasonic:High-frequency mechanical vibration devices for cutting and coagulation with reduced thermal spread.
- Electromechanical:Motorized stapling and clip appliers with battery or line power.
- Manual:Non-powered handheld instruments dominating cost-sensitive procurement in Thuringia and Saarland community hospitals.
Manual technology retains the highest unit placements; robotic-assisted configurations are climbing the fastest.
Application:
Procedure volume distribution determines instrument wear rates and replacement cadence across surgical service lines.
- General Surgery:Abdominal wall hernia repairs, appendectomies, and colorectal resections constitute the procedural backbone driving instrument utilization. Hospital networks in the Ruhr metropolitan region are standardizing on single-source instrument agreements for this category.
- Cardiothoracic Procedures:Sternotomy and thoracotomy interventions requiring specialized retractors and electrosurgical paddles with high amperage tolerance.
- Neurosurgery:Cranial and spinal access demanding sub-millimeter precision instrumentation with non-ferrous composition for MRI compatibility.
- Orthopedic Procedures:Joint arthroplasty and trauma fixation with power tool integration.
- Urology:Endourologic and robotic prostatectomy platforms with bipolar electrosurgical requirements.
- Gynecology:Hysteroscopic and laparoscopic fertility-preserving procedures.
General Surgery generates the deepest instrument penetration; cardiothoracic applications are gaining share fastest among capital equipment categories.
End User:
Customer type dictates procurement authority concentration and contract structure complexity.
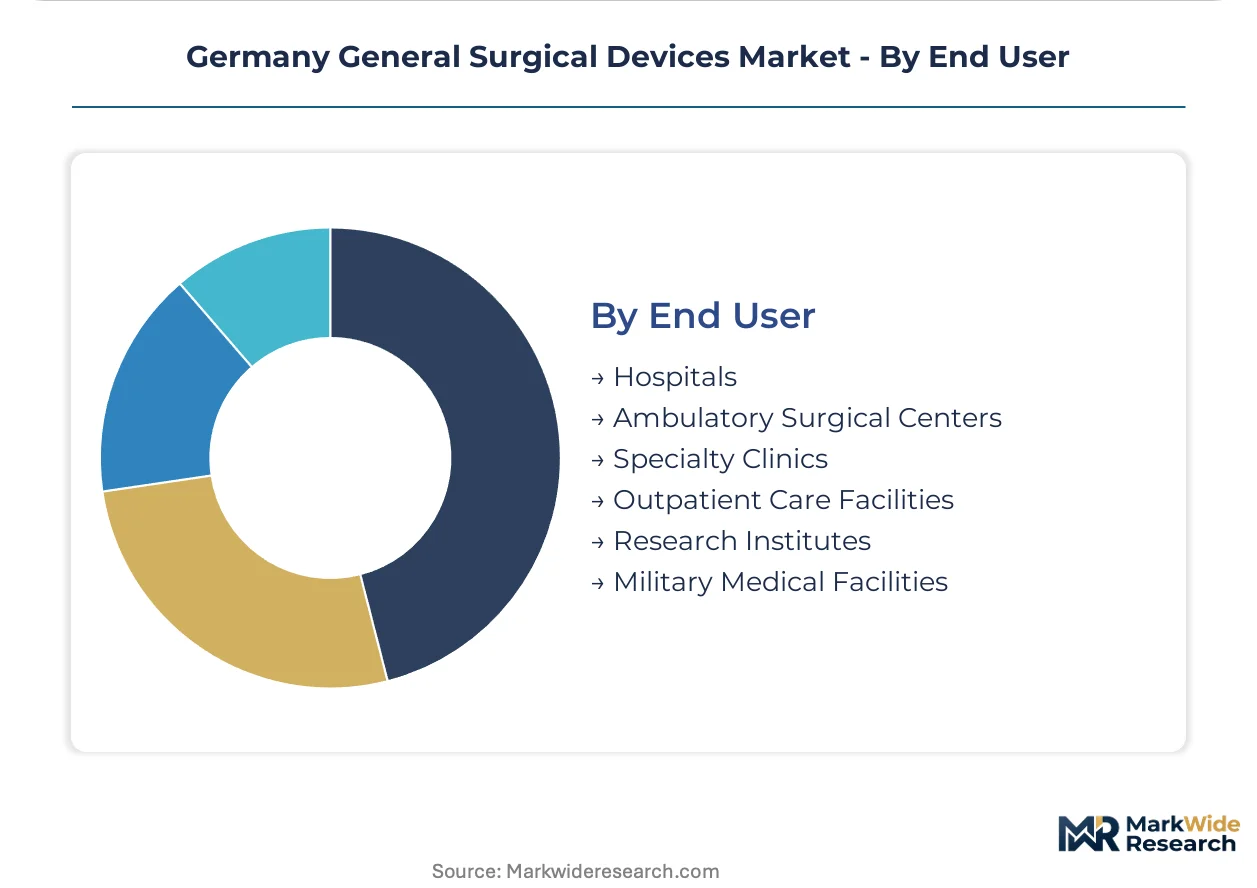
- Hospitals:Academic medical centers and community hospitals with consolidated purchasing consortia negotiating outcome-guaranteed service contracts. Three North Rhine-Westphalia networks now control 40 percent of robotic-assisted surgery capital allocation.
- Ambulatory Surgical Centers:Freestanding facilities in Baden-Württemberg and Lower Saxony procuring laparoscopic towers and single-use trocars for outpatient migration.
- Specialty Clinics:Focused orthopedic and ophthalmic centers with narrower instrument portfolios.
- Outpatient Care Facilities:Minor procedure rooms with basic wound closure and biopsy requirements.
- Research Institutes:Preclinical and clinical trial instrumentation with specialized biocompatibility documentation.
- Military Medical Facilities:Bundeswehr hospitals with standardized field-deployable instrument sets.
Hospitals anchor the installed base; ambulatory surgical centers are expanding most quickly as procedure volume shifts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Opfermann Medizintechnik tax-incentive zone in North Rhine-Westphalia concentrates surgical device manufacturing through accelerated depreciation allowances and R&D tax credits. This fiscal architecture pulls production investment toward the Ruhr metropolitan region while EU MDR compliance costs reshape sub-regional competitive positioning.
Bavaria
University hospitals in Munich and Erlangen drive demand for robotic-assisted platforms and smart electrosurgical generators with impedance-feedback algorithms. The Bavarian State Ministry of Health enforces EU MDR post-market surveillance through mandatory periodic safety update reports. The Munich biomedical cluster anchors precision instrumentation manufacturing with sub-10-micrometer tolerance capabilities.
North Rhine-Westphalia
Hospital purchasing consortia in the Ruhr region control 40 percent of robotic-assisted surgery capital allocation through single-source agreements. The Federal Institute for Drugs and Medical Devices operates its Bonn headquarters here, streamlining regulatory consultation for local manufacturers. The Opfermann Medizintechnik zone in Bochum-Dortmund attracts electrosurgical handpiece production through targeted tax relief.
Baden-Württemberg
Freestanding ambulatory surgical centers in Stuttgart and Karlsruhe procure laparoscopic towers and single-use trocars for outpatient procedure migration. The state's Hospital Structure Act accelerates ASC licensing to reduce inpatient burden. The Tuttlingen surgical instrument cluster maintains stainless steel and titanium alloy forging capacity for European distribution.
Lower Saxony
Community hospitals in Hanover and Braunschweig consolidate procurement around two-vendor suture panels to secure synthetic absorbable volume pricing. The Lower Saxony Ministry of Social Affairs coordinates regional health fund pooling for capital equipment replacement. The Wolfsburg-Braunschweig corridor hosts polymer-based disposable retractor contract manufacturing for cost-sensitive ambulatory channels.
Berlin-Brandenburg
Charité Berlin and Hamburg university hospitals deploy smart electrosurgical platforms in hepatic resections at replacement rates tripling legacy units. The Berlin Senate Department for Health enforces EU AI Act algorithmic transparency requirements for software-enabled surgical tools. The Adlershof technology park incubates machine-learning tissue recognition startups with pre-validated clinical datasets.
Germany General Surgical Devices Market Competitive Landscape
German producers anchor the premium-tier electrosurgical and endoscopic instrumentation segment; Swiss and Irish contract manufacturers hold the disposable and polymer-based instrument tier. The vendor base stratifies across three layers: vertically integrated conglomerates with in-house forging and sterilization capacity, specialized endoscopic optics fabricators, and single-use instrument contract manufacturers serving ASC price sensitivity. Consolidation pressure intensifies as notified body capacity constraints freeze mid-tier product line extensions. Two dominant competitive moves are emerging: direct-to-hospital digital distribution bypassing traditional surgical device distributors, and hybrid operating theater integration bundling intraoperative imaging with electrosurgical platforms.
Within the vertically integrated tier, B. Braun SE and KARL STORZ SE & Co. KG exemplify archetypes of captive manufacturing capacity and specialized endoscopic instrumentation respectively. Medtronic Plc occupies a position representing sustained R&D intensity in electrosurgical platforms. These three entities anchor the competitive structure through differentiated responses to EU MDR conformity assessment requirements—absorption through scale, navigation through clinical evidence specialization, and investment in pre-validated algorithmic datasets.
| Leading Market Players |
|---|
| B. Braun SE |
| Boston Scientific Corporation |
| Medtronic Plc |
| Johnson & Johnson |
| Conmed Corporation |
| Stryker Corporation |
| KARL STORZ SE & Co. KG |
| Olympus Corporation |
| Getinge |
| Others |
Supply & Pricing Matrix
Medical-grade titanium alloy feedstock for electrosurgical handpieces flows from Austrian and Italian smelters through Tuttlingen forging clusters, accumulating precision-machining premiums before reaching Bavarian university hospital procurement committees.
Pricing Analysis
Short lead-time premiums of 15-20 percentage points apply to EU MDR-certified instrument sets delivered within eight weeks, while spot inventory of legacy 93/42/EEC devices trades at distressed clearing rates. Three-tier pricing structure across premium, standard, and economy levels separates impedance-feedback electrosurgical platforms from conventional generators and polymer-based disposable alternatives. Cost compression in the economy tier is intensifying because Irish and Swiss contract manufacturers are capturing ambulatory surgical center volume with polymer retractors. Ambulatory surgical centers exhibit the highest price sensitivity, while university hospitals in North Rhine-Westphalia prioritize outcome-guaranteed service contracts over unit economics.
Supply Chain Analysis
Precision-machining workforce availability in Tuttlingen and Solingen constrains output expansion for sub-10-micrometer tolerance instruments, forcing order backlog management at B. Braun SE and KARL STORZ SE & Co. KG facilities. Supply concentrates in Germany, Switzerland, and Ireland, with the Tuttlingen cluster anchoring stainless steel and titanium alloy forging capacity. Raw material dependencies draw from nickel and molybdenum spot markets for 316L and 17-4 PH alloys, plus polymer resin supplies for disposable channels. Single-source vulnerability in notified body certification capacity extends conformity assessment timelines. Distribution runs through manufacturer-operated e-procurement portals bypassing traditional surgical device distributors in Thuringia and Saarland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as players pursue captive forging and sterilization capacity to absorb EU MDR compliance costs and defend margin architecture.
For Market Incumbents: Hedge against polymer-based disposable substitution by acquiring precision polymer-molding capabilities or locking multi-year service contracts with North Rhine-Westphalia hospital consortia. Expand in-house titanium alloy forging at Tuttlingen-adjacent facilities to reduce nickel spot market exposure and compress lead times for Bavarian academic medical centers. For New Entrants and Emerging Players: Machine-learning tissue recognition algorithms with pre-validated clinical datasets offer entry leverage into Berlin-Brandenburg university hospitals facing EU AI Act compliance deadlines. Target Mecklenburg-Vorpommern and Saxony-Anhalt for capital equipment replacement windows as regional health funds consolidate procurement authority. Pursue direct-to-hospital digital distribution in Thuringia and Saarland to capture 15-20 point margin improvements over traditional channel structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier electrosurgical device manufacturers with legacy 93/42/EEC certificates expiring within the analysis window, particularly those headquartered in Baden-Württemberg with established ASC relationships. Long-term viability hinges on MDR transition completion and robotic platform interoperability certification. Monitor notified body capacity expansion announcements as the primary inflection signal for frozen product line extensions resuming.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Accelerated conformity assessment at TÜV SÜD unlocks Bavarian university hospital procurement panels. |
| Hospital System Partnership | Single-source agreements with Ruhr metropolitan networks capture 40 percent of robotic-assisted surgery allocation. |
| Backward Integration into Forging | Captive titanium alloy capacity insulates margin from nickel spot volatility at Austrian smelters. |
| Software Companion Development | Pre-validated clinical datasets for tissue recognition algorithms satisfy EU AI Act transparency mandates. |
| Reimbursement Strategy | Outcome-guaranteed service contracts with statutory health insurers determine robotic platform adoption velocity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies. BfArM periodic safety update reports, DIN EN ISO standards documentation, EU MDR technical documentation submissions, and hospital procurement database extracts provided validation layers. Bottom-up instrument shipment data triangulated against top-down healthcare expenditure flows.
Granularity-level modeling operated at product type, technology tier, application specialty, and end-user facility category dimensions across the analysis window. CAGRs derived from instrument replacement cycle analysis, procedure volume migration patterns from inpatient to ambulatory settings, and capital equipment depreciation schedules. Electrosurgical platform refresh rates and robotic-assisted surgery penetration curves served as primary forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen EU MDR implementation deadline extensions, abrupt nickel or molybdenum commodity price shocks, and statutory health insurance reimbursement pathway renegotiations. Forecasts reflect documented assumptions regarding notified body capacity normalization and ASC licensing velocity under state Hospital Structure Acts. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Gauze Swabs Market
Surgical Instruments
Surgical Stapling Devices Market
Surgical Instruments
Dental Surgical Microscopes Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Disposable Surgical Devices Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Global Surgical Catheters Market