
 United States Behavioral Rehabilitation Market | 2026-2036
United States Behavioral Rehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
United States Behavioral Rehabilitation Market Analytics
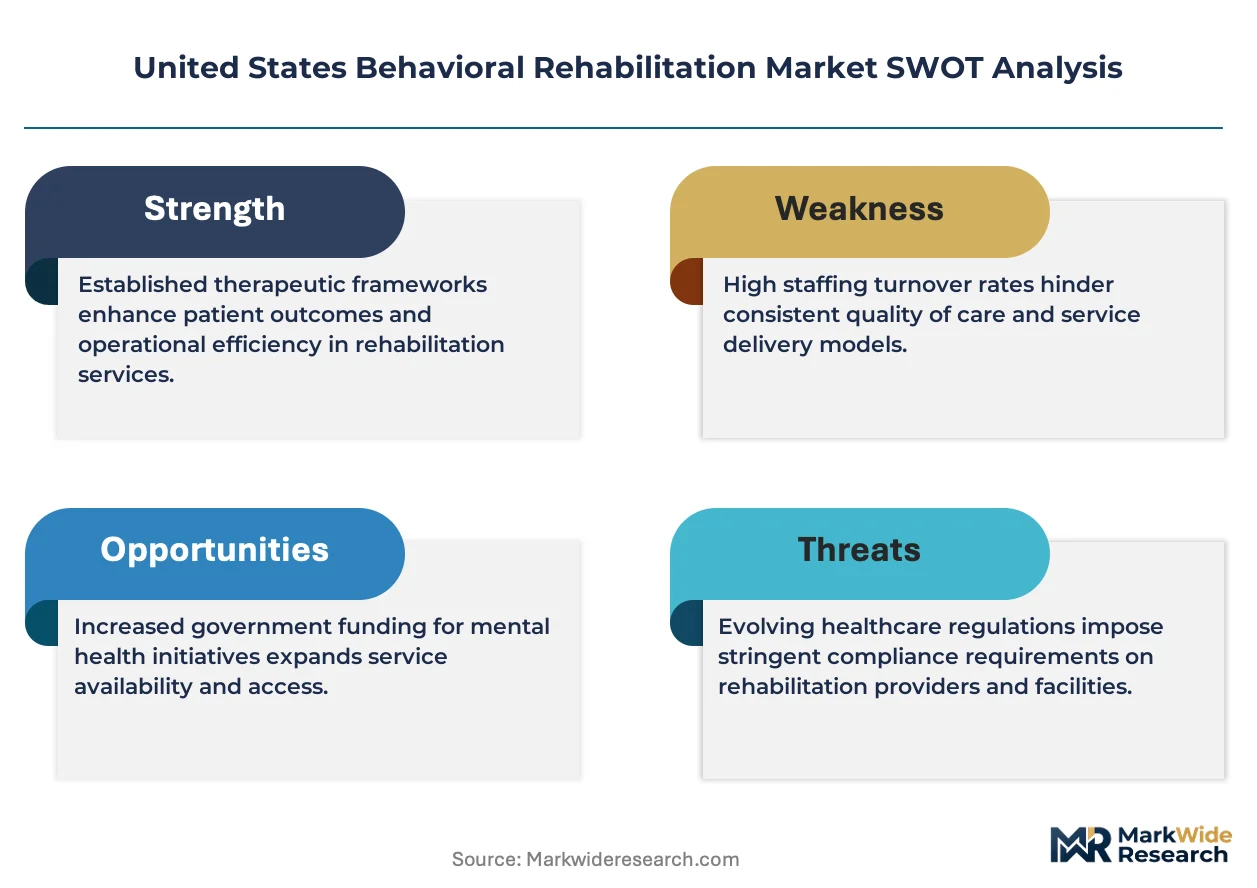
Joint Commission accreditation is rotating toward digital health integration standards, raising the bar for facility-based operators. Acadia Healthcare leverages its scale across residential and outpatient footprints to sustain bed utilization rates. Universal Health Services anchors its position through acute psychiatric hospital networks in underserved metropolitan corridors. Promises Behavioral Health differentiates via specialized trauma and addiction programming in resort-clinical settings.
Behavioral rehabilitation encompasses structured therapeutic interventions for substance use disorders, psychiatric conditions, and behavioral health crises, typically delivered through supervised residential stays, clinical outpatient protocols, or intensive day programs incorporating medication-assisted treatment, cognitive behavioral therapy, and peer support modalities. Inpatient Care commands the largest revenue share due to higher per-episode reimbursement and regulatory requirements for detoxification oversight, while Telehealth Services within the Delivery Mode dimension is expanding fastest as state licensure compacts and platform reimbursement codes mature. Outpatient Therapy maintains stable margins through lower fixed-cost intensity and recurring visit economics.
CMS reimbursement rules, FDA oversight of digital therapeutics, and state-level certificate-of-need laws collectively determine market access and service expansion feasibility across jurisdictions. The Mental Health Parity and Addiction Equity Act enforcement by the Department of Labor and state insurance commissioners shapes plan benefit design and prior authorization requirements for residential levels of care. Stakeholders must monitor evolving DEA scheduling decisions for psychedelic-assisted therapies and state Medicaid expansion timelines for uninsured patient eligibility.
Market Dynamics
The Mental Health Parity and Addiction Equity Act enforcement is compressing prior authorization timelines for residential levels of care, forcing payers to accelerate benefit design changes and providers to reconfigure intake workflows around real-time eligibility verification.
Growth Catalysts
- Medicaid 1115 Waivers:Texas and California are leveraging these waivers to expand bed capacity for substance use disorder treatment, unlocking federal matching funds for residential services previously excluded from state plans.
- Telehealth Licensure Compacts:The Psychology Interjurisdictional Compact is dissolving state licensing barriers, enabling multi-state providers to scale virtual intensive outpatient programs without facility duplication.
- Veterans Affairs Expansion:VA health systems are consolidating behavioral health contracts under enterprise purchasing agreements, creating predictable demand pipelines for PTSD and addiction programming.
Market Restraints
- Certificate-of-Need Laws:Thirty-five states maintain CON restrictions on psychiatric bed expansion, concentrating supply in legacy hospital systems and blocking independent entrants in high-need corridors.
- Workforce Pipeline Collapse:The American Psychological Association documents acute shortages of licensed clinical psychologists, particularly in rural counties where vacancy rates exceed forty percent.
- Reimbursement Compression:CMS rate-setting for inpatient psychiatric facilities lags acute medical hospital updates by approximately twelve percent, squeezing margin structures for standalone operators.
Strategic Opportunities
- Underserved Metropolitan Corridors:Riverside-San Bernardino and Houston-The Woodlands show bed deficits exceeding thirty percent against population-adjusted benchmarks, presenting greenfield development targets.
- Digital Therapeutics Integration:FDA-cleared prescription digital therapeutics for substance use disorder are creating hybrid reimbursement codes that blend device and therapy billing.
- Justice-Involved Populations:State Medicaid expansion for recently incarcerated individuals is opening dedicated reentry programming contracts with county probation departments.
Industry Challenges
- Joint Commission Digital Standards:New accreditation requirements for electronic health record interoperability and remote patient monitoring are forcing mid-size operators into seven-figure capital outlays.
- DEA Scheduling Uncertainty:Pending rescheduling decisions for psychedelic-assisted therapies are freezing investment in clinical infrastructure until prescribing pathways clarify.
- Prior Authorization Friction:Commercial payers are deploying algorithmic utilization management tools that deny residential authorization at rates requiring dedicated appeals staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Behavioral Rehabilitation Market |
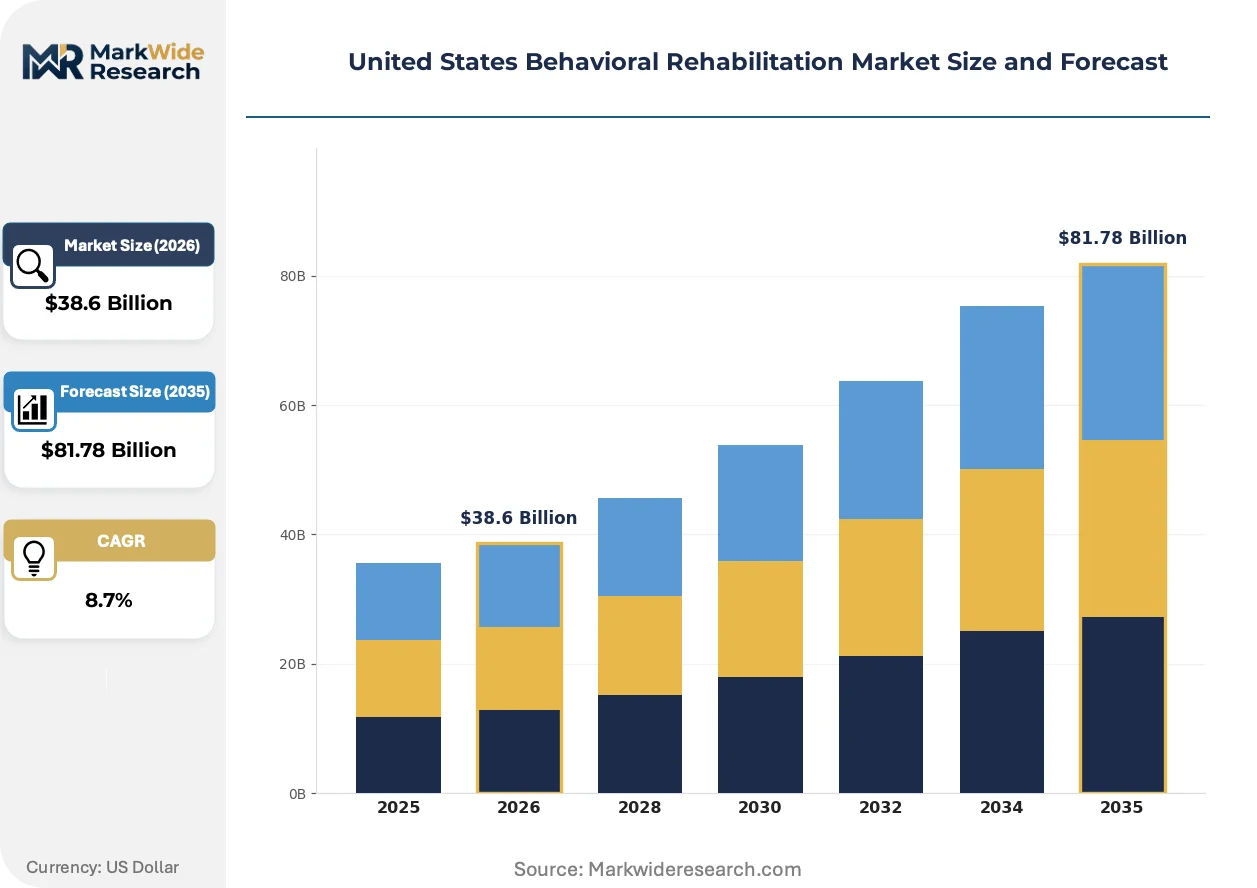
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inpatient Care, Outpatient Therapy, Intensive Outpatient, Partial Hospitalization End User: Adults, Adolescents, Children, Families Therapy Area: Substance Abuse, Mental Health Disorders, Eating Disorders, Trauma Recovery Delivery Mode: Telehealth Services, Face-to-Face Sessions, Group Therapy, Individual Counseling |
| Companies Covered | Aurora Behavioral Health System, Haven Behavioral Healthcare, Acadia Healthcare, Springstone, Promises Behavioral Health, Universal Health Services, Behavioral Health Group, Addiction Campuses, Magellan Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Behavioral Rehabilitation Market Evolving Landscape
Platform-based care coordination is fragmenting traditional episode bundling, creating new competitive arenas around data liquidity and real-time outcome measurement that reward operators with superior interoperability architecture.
Artificial intelligence-powered clinical decision support is decomposing static treatment protocols into adaptive, patient-specific pathways. Veterans Affairs systems are piloting these tools for suicide risk stratification, compressing the gap between assessment and intervention. The structural consequence is a shift toward technology-enabled credentialing that privileges vendors with FDA-cleared algorithms over legacy therapeutic brands.
The Mental Health Parity and Addiction Equity Act is reshaping state insurance commissioner enforcement priorities, triggering market conduct examinations of large commercial plans. Carriers are responding by eliminating quantitative treatment limits for residential care in Texas and Florida, though prior authorization stringency persists as a cost control lever. Self-insured employers in the manufacturing and transportation sectors are most affected, accelerating direct contracting with specialized provider networks.
County governments and municipal courts are consolidating behavioral health purchasing through single-source regional contracts, displacing fragmented referrals from individual social workers and family physicians. California's Medi-Cal managed care plans are piloting these arrangements in Los Angeles and San Diego counties, where justice-involved and homeless populations concentrate. The shift compresses sales cycles but demands providers absorb population health risk through capitated arrangements.
United States Behavioral Rehabilitation Market Segmentation
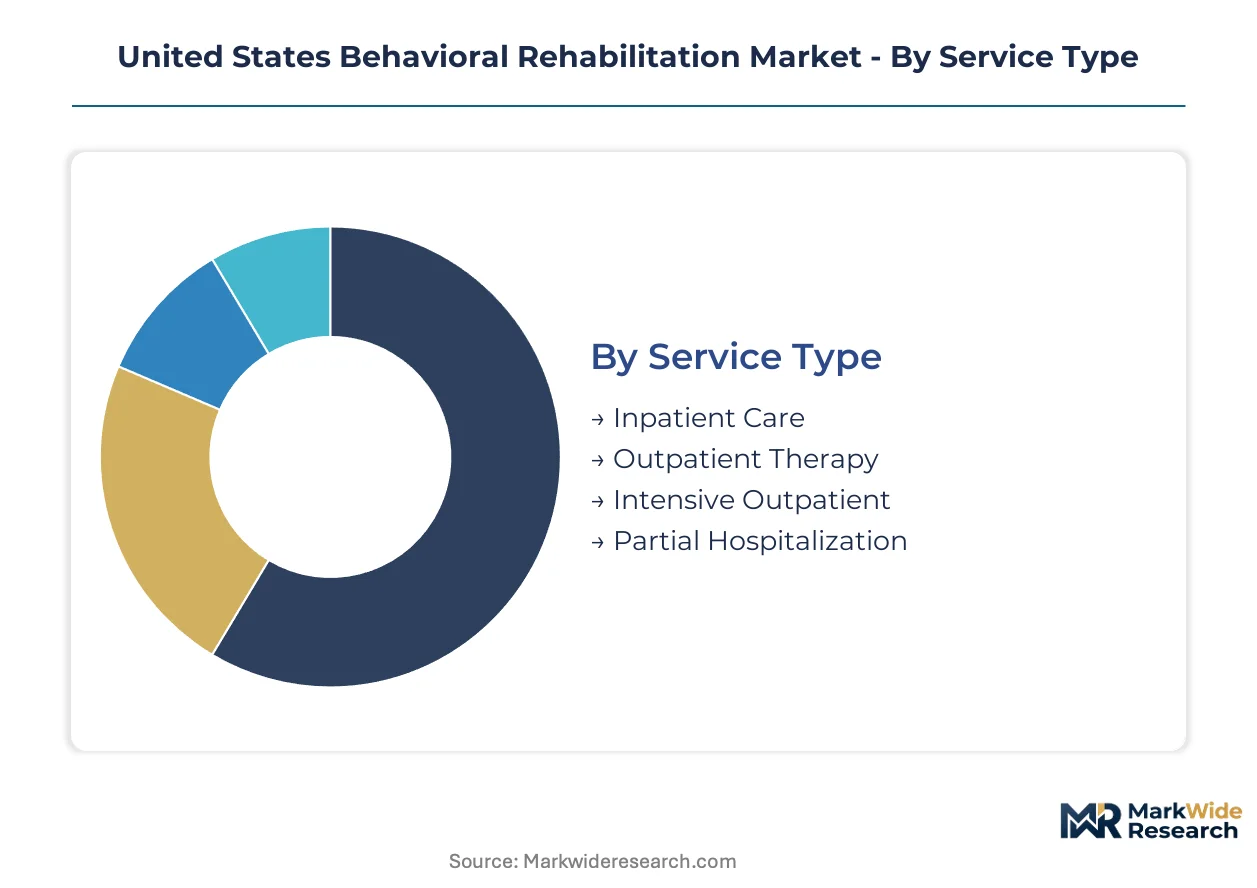
Behavioral rehabilitation operators configure service portfolios around reimbursement mechanics, patient acuity thresholds, and state-level regulatory constraints. Segmentation clarity determines capital allocation between high-fixed-cost residential infrastructure and scalable virtual platforms.
Service Type:
Telehealth platforms and outpatient alternatives are exerting substitution pressure on traditional inpatient admissions, particularly for stable psychiatric conditions and maintenance-phase addiction treatment.
- Inpatient Care:Twenty-four-hour medically supervised residential treatment incorporating detoxification protocols, medication management, and crisis stabilization. Texas and California Medicaid 1115 waivers are expanding bed capacity for substance use disorder episodes previously diverted to emergency departments.
- Outpatient Therapy:Scheduled clinical sessions without overnight supervision, spanning individual counseling and group modalities. Florida's state employee health plans are driving volume through parity-mandated benefit expansions that eliminate prior authorization for outpatient mental health visits.
- Intensive Outpatient:Structured programming delivering nine or more hours of weekly therapeutic contact while preserving patient residence and employment. The format captures patients stepping down from residential care or requiring more support than standard outpatient permits.
- Partial Hospitalization:Day-program intensity approximating inpatient clinical hours without overnight stay, typically serving eating disorders and acute mood conditions requiring medical monitoring.
Inpatient Care anchors the volume base while Telehealth-enabled outpatient alternatives gain share at the steepest rate.
End User:
Cost tier differentiation separates high-acuity adult populations with commercial insurance coverage from publicly funded adolescent and family segments where reimbursement rates compress margins.
- Adults:The largest addressable population spanning working-age individuals with employer-sponsored coverage and Medicare-eligible seniors. Veterans Affairs enterprise purchasing agreements concentrate demand for PTSD and addiction programming among military veterans.
- Adolescents:Patients aged twelve to seventeen requiring specialized developmental approaches and family systems integration. Certificate-of-need restrictions in thirty-five states limit dedicated adolescent bed expansion to legacy hospital systems.
- Children:Pre-adolescent populations needing play-based therapeutic modalities and school-based coordination. Medicaid expansion timelines in holdout states determine eligibility for uninsured pediatric behavioral health services.
- Families:Multi-generational treatment units addressing systemic dysfunction, codependency patterns, and intergenerational trauma. County-level procurement consolidation in California is creating capitated contracts for justice-involved family units.
Adult segments generate the revenue concentration while adolescent programming climbs fastest under school-based Medicaid billing reforms.
Therapy Area:
Application focus determines staffing mix and facility requirements, with substance abuse and mental health disorders commanding distinct regulatory frameworks and reimbursement codes.
- Substance Abuse:Structured interventions for alcohol, opioid, and stimulant use disorders incorporating medication-assisted treatment and peer recovery support. DEA scheduling decisions for psychedelic-assisted therapies are freezing investment in novel clinical infrastructure until prescribing pathways clarify.
- Mental Health Disorders:Treatment for depression, anxiety, bipolar disorder, and schizophrenia spectrum conditions. Artificial intelligence-powered clinical decision support is compressing assessment-to-intervention timelines for suicide risk stratification in Veterans Affairs systems.
- Eating Disorders:Specialized medical and psychiatric management of anorexia, bulimia, and binge-eating presentations requiring nutritional rehabilitation. The segment demands higher nursing ratios and longer average lengths of stay than general psychiatric conditions.
- Trauma Recovery:Evidence-based protocols for PTSD, complex trauma, and dissociative conditions. Promises Behavioral Health differentiates through resort-clinical settings targeting high-net-worth individuals seeking privacy.
Substance abuse programming anchors utilization while trauma recovery services expand most quickly under Veterans Affairs contract consolidation.
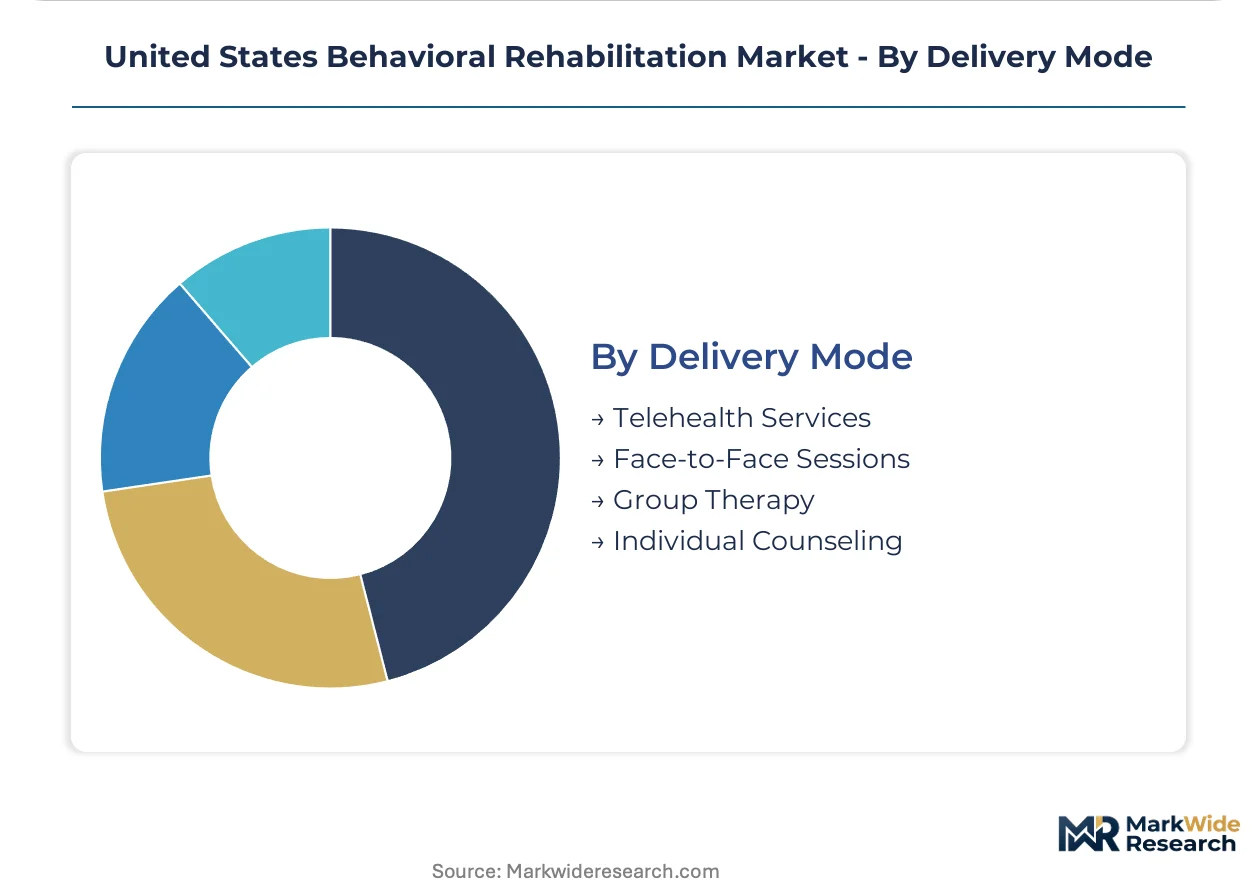
Delivery Mode:
Supply concentration favors established platforms with multi-state licensure, while technology-enabled entrants fragment traditional episode economics.
- Telehealth Services:Virtual delivery of individual counseling, group therapy, and psychiatric medication management through HIPAA-compliant platforms. The Psychology Interjurisdictional Compact is dissolving state licensing barriers for multi-state virtual intensive outpatient program scaling.
- Face-to-Face Sessions:In-person clinical encounters in outpatient offices, community mental health centers, and hospital-based clinics. Legacy operators maintain advantage where digital literacy barriers or severe symptomatology preclude virtual care.
- Group Therapy:Facilitated peer interaction in structured formats spanning psychoeducation, skills training, and process-oriented support. The modality reduces per-patient clinician hours while building recovery capital through peer accountability.
- Individual Counseling:One-to-one therapeutic relationship delivering personalized assessment, treatment planning, and progress monitoring. Acute workforce shortages in rural counties where licensed clinical psychologist vacancy rates exceed forty percent constrain expansion.
Face-to-face delivery maintains the patient volume base while telehealth services capture the steepest expansion trajectory under state licensure compact maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicaid 1115 waivers and Veterans Affairs procurement consolidation are redistributing behavioral rehabilitation capacity across state-level markets. Certificate-of-need restrictions and workforce availability create divergent expansion trajectories that favor jurisdictions with regulatory flexibility.
California
Medi-Cal managed care plans in Los Angeles and San Diego counties are piloting capitated contracts for justice-involved populations. The state's Medicaid 1115 waiver unlocks federal matching funds for residential substance use disorder services. The Riverside-San Bernardino corridor shows bed deficits exceeding thirty percent against population-adjusted benchmarks.
Texas
State employee health plans are driving volume through parity-mandated benefit expansions. The state's Medicaid 1115 waiver targets bed capacity expansion for substance use disorder treatment previously diverted to emergency departments. Houston-The Woodlands presents greenfield development opportunities with similar bed deficit metrics.
Florida
Commercial payers are eliminating quantitative treatment limits for residential care under Mental Health Parity and Addiction Equity Act enforcement. State insurance commissioner market conduct examinations are accelerating benefit design changes. Miami-Dade and Broward counties concentrate demand for adolescent programming under school-based Medicaid billing reforms.
New York
The Northeast Corridor maintains dense outpatient infrastructure serving commercially insured working-age adults. Certificate-of-need laws limit psychiatric bed expansion to legacy hospital systems. New York City anchors telehealth platform scaling under Psychology Interjurisdictional Compact participation.
Ohio
Midwest manufacturing and transportation sector employers are accelerating direct contracting with specialized provider networks. State Medicaid expansion timelines determine eligibility for uninsured patient populations. Cleveland and Columbus metropolitan areas show concentrated Veterans Affairs contract demand for PTSD programming.
United States Behavioral Rehabilitation Market Competitive Landscape
Player mix skews toward diversified health systems with multi-state footprints and specialized operators with clinical differentiation. National networks leverage scale across residential and outpatient platforms to sustain utilization rates. Two strategic archetypes dominate: acute psychiatric hospital chains anchoring underserved metropolitan corridors, and resort-clinical settings targeting high-net-worth trauma recovery segments. Competitive moves center on portfolio diversification into telehealth-enabled intensive outpatient programs and geographic expansion through Medicaid waiver-aligned bed capacity.
Within the diversified health system tier, Acadia Healthcare and Universal Health Services occupy positions defined by scale-driven network economics. Acadia exemplifies the residential-outpatient hybrid model with broad geographic dispersion. Universal Health Services anchors the acute psychiatric hospital archetype through metropolitan corridor concentration. Promises Behavioral Health represents the specialized differentiation vector, occupying the resort-clinical positioning for trauma and addiction programming.
| Leading Market Players |
|---|
| Aurora Behavioral Health System |
| Haven Behavioral Healthcare |
| Acadia Healthcare |
| Springstone |
| Promises Behavioral Health |
| Universal Health Services |
| Behavioral Health Group |
| Addiction Campuses |
| Magellan Health |
| Others |
Value Network & Pricing Analysis
Bed utilization rates across multi-state networks determine fixed-cost absorption thresholds and establish minimum viable pricing floors for residential operators. Acadia Healthcare's scale economics compress per-bed overhead while Certificate-of-Need restrictions in thirty-five states limit supply expansion, concentrating pricing power among incumbent hospital systems.
Pricing Analysis
Joint Commission accreditation tier creates the primary spread between premium and standard rate cards, with digitally-integrated facilities commanding fifteen to twenty percent reimbursement premiums over legacy operators. Pricing stratifies across Joint Commission-accredited, state-licensed, and non-certified tiers based on interoperability readiness and remote monitoring capability. Price compression runs through standard-tier residential beds as Medicaid rate-setting lags acute medical hospital updates. Self-insured employers in manufacturing and transportation sectors show lowest price sensitivity due to parity-mandated benefit expansions, while county procurement offices exhibit highest sensitivity under capitated justice-involved contracts.
Supply Chain Analysis
Specialized clinical workforce lead times now stretch fourteen to eighteen months for licensed psychologists in rural counties, constraining bed activation timelines. Supply concentrates in Texas, Florida, and California where Medicaid 1115 waivers unlock federal matching funds for residential expansion. The network draws from pharmaceutical distributors for medication-assisted treatment protocols, EHR platform vendors for interoperability compliance, and specialized construction firms for resort-clinical facility fit-outs. Tariff exposure on imported medical equipment creates margin vulnerability for operators scaling physical infrastructure. Distribution runs through Veterans Affairs enterprise purchasing agreements, county probation department contracts, and commercial payer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Behavioral Rehabilitation Market sits at an inflection where telehealth licensure compacts and FDA-cleared digital therapeutics are dissolving traditional geographic moats. The Mental Health Parity and Addiction Equity Act enforcement is compressing prior authorization timelines and forcing real-time eligibility verification as table stakes.
For Market Incumbents: Compound network density in Riverside-San Bernardino and Houston-The Woodlands corridors where bed deficits exceed thirty percent against population-adjusted benchmarks. Accelerate backward integration into EHR interoperability architecture to defend against algorithmic utilization management tools deployed by commercial payers. Prioritize Psychology Interjurisdictional Compact licensure to scale virtual intensive outpatient programs without facility duplication.
For New Entrants and Emerging Players: Lead with FDA-cleared prescription digital therapeutics for substance use disorder, creating hybrid reimbursement codes that blend device and therapy billing. Target justice-involved reentry programming in California's Medi-Cal managed care pilots where county procurement consolidation favors specialized providers willing to absorb population health risk. Deploy direct-to-employer contracting with manufacturing sector self-insured plans bypassing traditional payer networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with multi-state licensure and digital health integration capabilities over pure-play residential assets. Five-to-ten year viability hinges on Medicaid waiver alignment and Veterans Affairs contract concentration. Watch DEA scheduling decisions for psychedelic-assisted therapies as the signal for clinical infrastructure investment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Psychology Interjurisdictional Compact participation enables multi-state virtual intensive outpatient scaling without facility duplication. |
| Medicaid 1115 Waiver Alignment | Texas and California federal matching funds unlock residential substance use disorder bed capacity previously excluded from state plans. |
| Digital Therapeutics Development | FDA-cleared prescription digital therapeutics create hybrid reimbursement codes blending device and therapy billing streams. |
| Justice-Involved Contracting | County probation department partnerships in California and Florida capture dedicated reentry programming under capitated arrangements. |
| Veterans Affairs Network Participation | Enterprise purchasing agreements concentrate demand pipelines for PTSD and addiction programming among military veterans. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CMS reimbursement databases, state Medicaid waiver filings, Veterans Affairs procurement records, and Joint Commission accreditation directories. Clinical directors at residential facilities, behavioral health GPO contracts managers, state insurance commissioner enforcement staff, and telehealth platform executives provided operational perspective. Hospital purchasing committees and county probation department administrators supplied demand-side intelligence. Bottom-up bed capacity counts triangulate against top-down expenditure flows from Medicare and Medicaid administrative data.
Segmentation dimensions modeled include service type, end user population, therapy area focus, and delivery mode across the projection horizon. CAGRs derive from facility-level revenue per bed, payer mix trajectories, and waiver expansion timelines. Forecast inputs incorporate workforce vacancy rates from the American Psychological Association and DEA scheduling decision probabilities for novel therapeutic classes.
The analysis sits within stated boundaries; outcomes outside continued Mental Health Parity and Addiction Equity Act enforcement or altered Medicaid expansion timelines would require recalibration. Forecasts reflect documented assumptions regarding licensure compact maturation and digital therapeutic reimbursement code development. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
Neurorehabilitation Gaming Systems Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
Global Medical Rehabilitation Services Market