
 Rehabilitation Therapy Services Market | 2026-2036
Rehabilitation Therapy Services Market Size, Share, and Industry Trends Forecast 2026-2036
Rehabilitation Therapy Services Market Outlook
CMS reimbursement rulemaking is restructuring capital deployment across outpatient therapy networks. Select Medical leverages its scale across inpatient rehabilitation facilities to sustain margin stability under bundled payment models. Encompass Health anchors its national footprint through hospital-based rehabilitation units that compete on outcomes metrics. U.S. Physical Therapy differentiates via clinic density in suburban markets where referral control determines volume capture.
Rehabilitation therapy services encompass skilled clinical interventions delivered by licensed professionals to restore functional capacity following injury, illness, or surgical procedures, incorporating modalities such as neuromuscular re-education, therapeutic exercise prescription, and assistive device training to achieve measurable patient-reported outcome improvements. Physical therapy leads service type revenue due to orthopedic procedure volume and direct access statutes expanding in multiple states, while teleRehabilitation represents the fastest-expanding technology segment as synchronous video platforms gain parity reimbursement. Geriatric application demand concentrates where Medicare Advantage penetration deepens, with margin pools shifting toward home health care end users as site-of-service differentials widen.
The Centers for Medicare & Medicaid Services shapes demand through annual physician fee schedule updates and quality reporting mandates, while state-level physical therapy licensure boards govern scope-of-practice parameters that determine service line expansion feasibility. The FDA regulates emerging therapeutic devices including robotic exoskeletons and virtual reality systems that therapists increasingly integrate into clinical protocols. Stakeholders must monitor whether Medicare's forthcoming site-neutral payment adjustments will compress hospital-based rehabilitation margins relative to outpatient and home-based alternatives.
Market Dynamics
Medicare's site-neutral payment adjustments are compressing hospital-based rehabilitation margins while redirecting capital toward outpatient and home-based delivery models. This reimbursement recalibration is restructuring network footprints across the post-acute care landscape.
Growth Catalysts
- Medicare Advantage Penetration:The shift toward managed care capitation in Medicare Advantage plans creates per-member-per-month incentives that favor preventive rehabilitation interventions. This payment model rewards outcomes-based therapy utilization across geriatric populations.
- Direct Access Statutes:State-level physical therapy licensure reforms permitting patient self-referral expand addressable patient pools. Twenty-eight states now allow direct access without physician gatekeeping, compressing time-to-treatment intervals.
- TeleRehabilitation Platforms:Synchronous video-based therapy delivery is integrating into standard-of-care protocols as parity reimbursement statutes expand. Rural health systems deploy these platforms to extend specialist reach without facility capex.
Market Restraints
- Skilled Labor Supply Constraints:Physical therapist vacancy rates exceed 11% nationally, with rural markets experiencing acute shortages. Educational program throughput limits constrain workforce expansion regardless of demand signals.
- Medicare Fee Schedule Compression:Annual conversion factor updates from CMS have reduced outpatient therapy reimbursement by 9% in real terms since 2020. This deflationary pressure squeezes operating margins for clinic-based providers.
- Prior Authorization Burdens:Commercial payers impose episode limits and pre-approval requirements that create administrative friction. Therapy practices dedicate 14-18% of staff hours to documentation and appeals processes.
Strategic Opportunities
- Home Health Integration:Site-of-service payment differentials widening under Medicare's 2024 physician fee schedule create arbitrage opportunities. Providers capturing patients at discharge for home-based therapy capture 23-31% reimbursement premiums over facility settings.
- Robotic Exoskeleton Deployment:FDA-cleared lower-limb exoskeletons for spinal cord injury rehabilitation command premium reimbursement under device-specific billing codes. Inpatient rehabilitation facilities differentiate outcomes metrics through this technology.
- Workers' Compensation Expansion:State mandates for early intervention physical therapy in occupational injury protocols open employer-paid channels. These segments bypass Medicare reimbursement constraints entirely.
Industry Challenges
- Interoperability Standards Fragmentation:Electronic health record systems lack unified data exchange protocols for therapy-specific outcome measures. This documentation gap complicates value-based contracting with risk-bearing entities.
- Outcome Measurement Standardization:Patient-reported outcome instruments vary across payer networks, preventing apples-to-apples quality comparisons. Therapy networks must maintain multiple reporting frameworks simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rehabilitation Therapy Services Market |
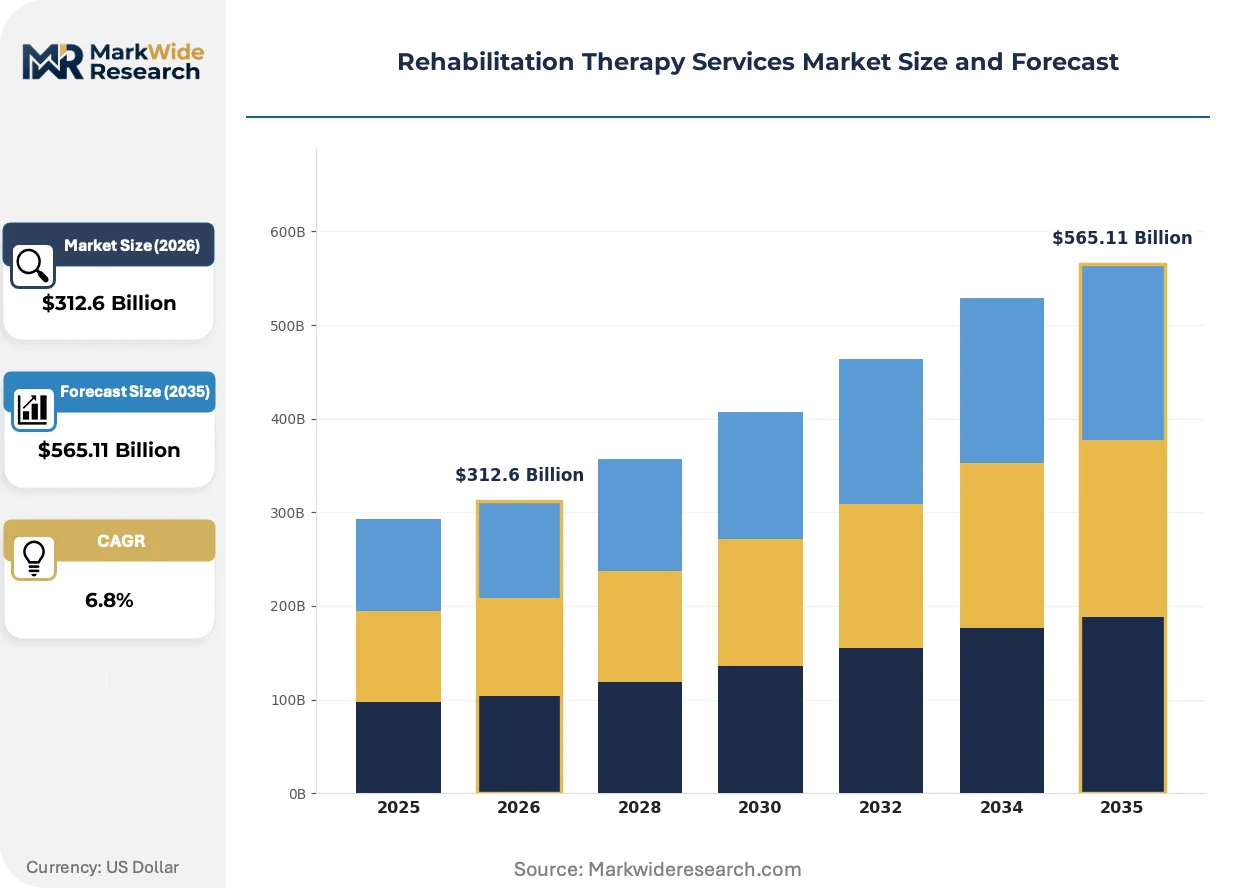
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Physical Therapy, Occupational Therapy, Speech Therapy, Recreational Therapy End User: Hospitals, Clinics, Home Health Care, Rehabilitation Centers Technology: TeleRehabilitation, Manual Therapy, Exercise Therapy, Virtual Reality Application: Orthopedic Rehabilitation, Neurological Rehabilitation, Pediatric Rehabilitation, Geriatric Rehabilitation |
| Companies Covered | Select Medical, Encompass Health, U.S. Physical Therapy, Athletico Physical Therapy, ATI Physical Therapy, Upstream Rehabilitation, Kaiser Permanente, UnitedHealth Group, Lifepoint Rehabilitation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rehabilitation Therapy Services Market Strategic Shifts
Clinical workflow digitization and reimbursement model experimentation are converging to redefine how rehabilitation services are delivered, measured, and compensated across care settings.
Virtual reality systems for motor rehabilitation are integrating into neurorehabilitation protocols at an accelerating pace. Stroke centers and traumatic brain injury programs deploy immersive environments for upper-extremity task training. This technology is integrating sensory feedback loops that were previously unavailable in conventional therapy, enabling intensity levels that manual therapy cannot replicate.
CMS's forthcoming site-neutral payment adjustments for hospital outpatient departments will compress reimbursement differentials between settings. The policy recalibration targets the 70% premium currently paid for identical services delivered in hospital-based clinics. Freestanding outpatient therapy networks stand to capture volume migration as price transparency tools expose these arbitrage opportunities to referring physicians and patients.
Episode-based bundled payments for joint replacement are reshaping referral patterns toward therapy networks with proven cost-outcome profiles. Orthopedic surgeons in Medicare's Comprehensive Care for Joint Replacement model increasingly direct patients to pre-qualified therapy partners. Texas and Florida markets exhibit the most pronounced concentration effects, where surgeon-therapy affiliations determine volume allocation.
Rehabilitation Therapy Services Market Segmentation
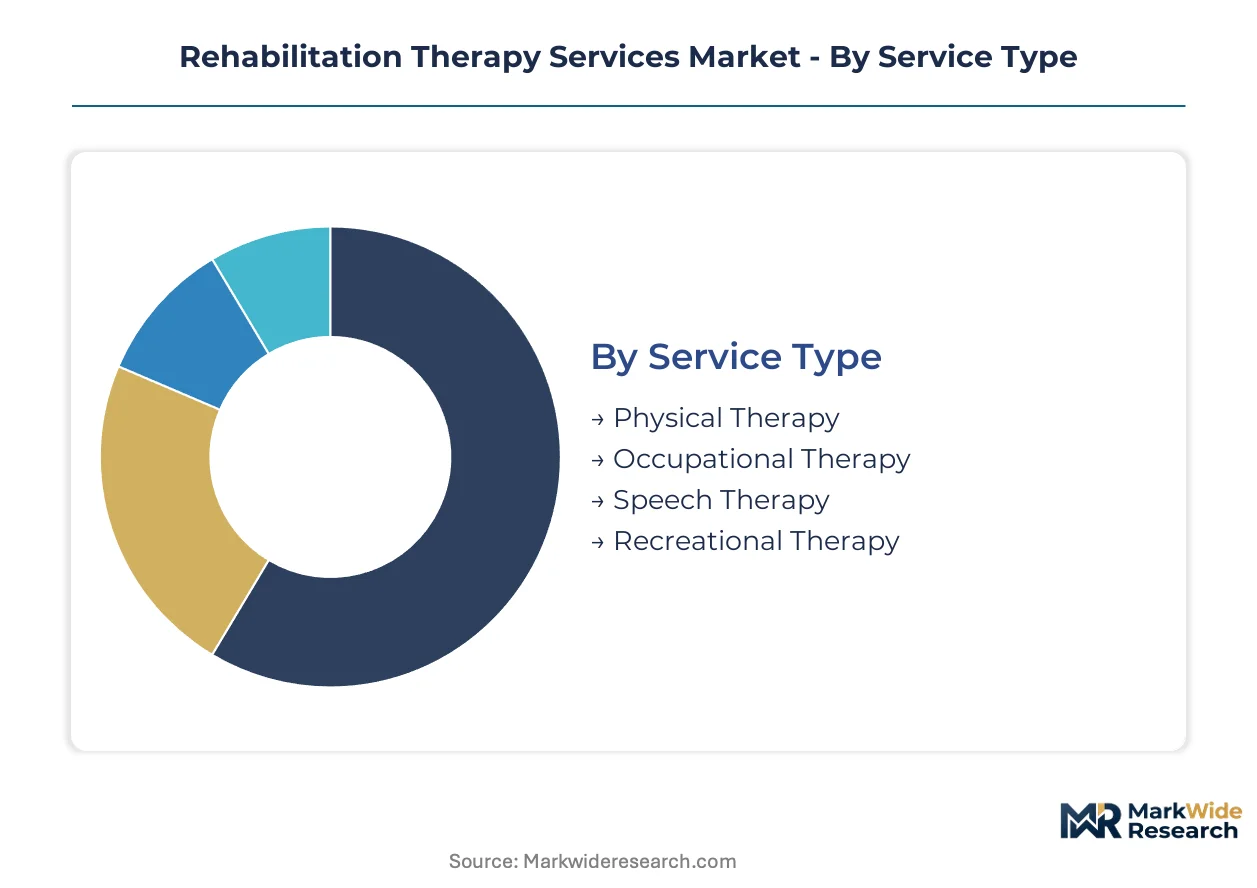
Rehabilitation therapy services fragment across multiple clinical and operational dimensions that determine reimbursement pathways, capital requirements, and margin profiles. Understanding these segment boundaries enables precise capacity planning and payer contract positioning.
Service Type:
Standardization dominates manual therapy protocols while customization intensifies with patient acuity and neurological complexity.
- Physical Therapy:Musculoskeletal intervention protocols address post-surgical recovery, sports injuries, and chronic pain management through therapeutic exercise and manual techniques. Demand concentrates in orthopedic practices across Texas and Florida where direct access statutes eliminate physician referral requirements. Medicare Advantage penetration in these states drives per-member-per-month incentives that reward episode completion rates.
- Occupational Therapy:Activities-of-daily-living retraining focuses on upper-extremity function, cognitive adaptation, and environmental modification for home safety. Geriatric populations in Medicare Advantage plans generate concentrated demand as capitated payments incentivize preventive functional maintenance. Home health agencies capture margin premiums through site-of-service arbitrage.
- Speech Therapy:Swallowing and communication rehabilitation serves stroke recovery and neurodegenerative conditions.
- Recreational Therapy:Community reintegration programs leverage activity-based interventions for psychiatric and cognitive rehabilitation.
Most installed capacity flows through Physical Therapy. Expansion is steepest in Occupational Therapy.
End User:
Cost tier stratification separates facility-based reimbursement from home-based alternatives under CMS site-neutral payment adjustments.
- Hospitals:Inpatient rehabilitation units and hospital-based outpatient departments command premium reimbursement under current Medicare fee schedules. Encompass Health anchors national footprint through IRF-exempt units that compete on CMS quality metrics. Site-neutral payment compression threatens this margin advantage as 2024 physician fee schedule revisions narrow setting differentials.
- Home Health Care:Post-acute therapy delivery at patient residences captures 23-31% reimbursement premiums over facility settings under Medicare's site-of-service adjustments. Skilled nursing shortages constrain expansion regardless of demand signals. Rural health systems deploy teleRehabilitation platforms to extend reach without facility capex.
- Clinics:Freestanding outpatient networks compete on referral control and clinic density in suburban markets.
- Rehabilitation Centers:Dedicated post-acute facilities specialize in intensive multidisciplinary protocols for complex conditions.
Volume concentrates in Hospitals. Patient migration accelerates toward Home Health Care.
Technology:
Application maturity separates established manual techniques from emerging digital platforms seeking parity reimbursement status.
- TeleRehabilitation:Synchronous video-based therapy delivery integrates into standard-of-care protocols as state parity statutes expand. Rural health systems deploy these platforms to extend specialist reach without capital expenditure. CMS reimbursement recognition drives adoption across Medicare Advantage networks seeking to reduce transportation barriers for geriatric populations.
- Virtual Reality:Immersive motor rehabilitation environments enable upper-extremity task training intensity levels that manual therapy cannot replicate. Stroke centers and traumatic brain injury programs deploy FDA-regulated systems for neurorehabilitation protocols. Device-specific billing codes command premium reimbursement for spinal cord injury applications.
- Manual Therapy:Hands-on techniques remain the clinical standard for musculoskeletal conditions.
- Exercise Therapy:Prescriptive movement protocols form the foundation of orthopedic rehabilitation programs.
Manual Therapy maintains dominant installed base. Virtual Reality claims the steepest expansion trajectory.
Application:
Customer type segmentation separates acute episodic demand from chronic population health management under risk-bearing payment models.
- Orthopedic Rehabilitation:Post-surgical and injury recovery protocols dominate service volume through joint replacement episodes and sports medicine referrals. Medicare's Comprehensive Care for Joint Replacement model reshapes referral patterns toward therapy networks with proven cost-outcome profiles. Texas and Florida markets exhibit pronounced concentration effects where surgeon-therapy affiliations determine volume allocation.
- Geriatric Rehabilitation:Functional maintenance and fall prevention programs align with Medicare Advantage capitation incentives. Per-member-per-month payments reward preventive interventions that reduce acute utilization. Home health integration captures site-of-service premiums while addressing transportation barriers for mobility-limited populations.
- Neurological Rehabilitation:Stroke, traumatic brain injury, and neurodegenerative condition protocols require specialized clinician training.
- Pediatric Rehabilitation:Early intervention services address developmental delays and congenital conditions through school-based and clinic delivery.
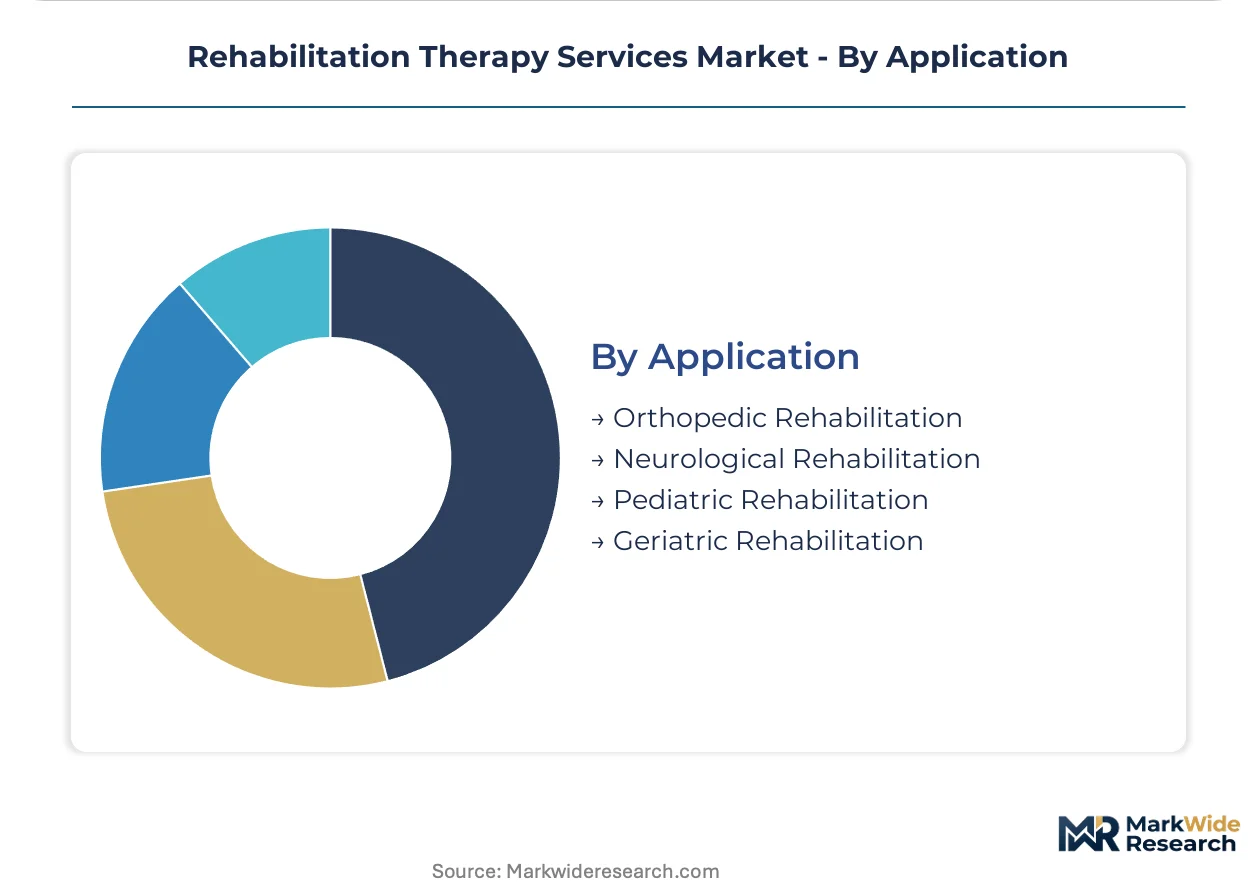
Orthopedic Rehabilitation commands largest volume share. Geriatric Rehabilitation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed physical therapist concentrations in the United States, Germany, Japan, Australia, and Canada anchor regional service capacity. Medicare policy divergence and aging demographic profiles reshape where capital deploys across these markets.
United States
Medicare Advantage penetration exceeds 50% in Florida and Texas, driving per-member-per-month incentives for preventive rehabilitation. CMS site-neutral payment adjustments compress hospital-based margins while expanding home health arbitrage opportunities. The Dallas-Fort Worth metroplex concentrates outpatient clinic networks competing on referral density.
Germany
Statutory health insurance rehabilitation budgets favor ambulatory over inpatient settings, redirecting patient volumes toward outpatient therapy centers. The EMA regulates emerging robotic exoskeleton devices entering neurorehabilitation protocols. The Rhine-Ruhr industrial corridor hosts dense networks of orthopedic rehabilitation clinics serving manufacturing workforce injuries.
Japan
Super-aging demographics concentrate geriatric rehabilitation demand in metropolitan Tokyo and Osaka prefectures. METI promotes teleRehabilitation adoption to address rural therapist shortages through remote delivery platforms. The Nagoya medical device cluster accelerates VR-based motor rehabilitation system development for stroke recovery protocols.
Australia
NDIS funding expansion broadens disability-related therapy access beyond traditional Medicare channels. The TGA regulates therapeutic device imports including FDA-cleared robotic systems entering private rehabilitation centers. Sydney and Melbourne anchor national outpatient networks where direct access statutes eliminate physician referral requirements.
Canada
Provincial health authority procurement centralizes rehabilitation service contracting in Ontario and Quebec. Health Canada oversees therapeutic device approvals for robotic and VR platforms entering hospital-based units. The Greater Toronto Area concentrates academic medical center rehabilitation research programs driving protocol standardization.
Rehabilitation Therapy Services Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the post-acute therapy landscape. Hospital-based rehabilitation units anchor national footprints through IRF-exempt facilities, while freestanding outpatient networks compete on suburban clinic density. Three archetypes dominate: integrated health systems with captive referral bases, dedicated rehabilitation facility operators, and clinic-scale physical therapy chains. M&A activity concentrates suburban market share, while technology licensing partnerships accelerate robotic and VR platform deployment.
Among dedicated rehabilitation operators, Select Medical and Encompass Health exemplify facility-based scale strategies, while U.S. Physical Therapy represents the clinic-density archetype competing on suburban referral control. These three occupy distinct competitive positions without overlapping service configurations.
| Leading Market Players |
|---|
| Select Medical |
| Encompass Health |
| U.S. Physical Therapy |
| Athletico Physical Therapy |
| ATI Physical Therapy |
| Upstream Rehabilitation |
| Kaiser Permanente |
| UnitedHealth Group |
| Lifepoint Rehabilitation |
| Others |
Value Chain & Pricing Dynamics
Licensed physical therapist wages cascade through service delivery tiers from hospital-based units to freestanding clinics and home health agencies, with Medicare's site-neutral payment adjustments compressing the premium spreads that previously separated these settings.
Pricing Analysis
Bundled episode payments for joint replacement rehabilitation contrast with unbundled per-visit fee-for-service structures across outpatient networks. Three-tier pricing structure across premium robotic-assisted protocols, standard manual therapy, and economy teleRehabilitation sessions reflects technology intensity and clinician specialization. Pricing pressure stems from CMS conversion factor compression reducing outpatient therapy reimbursement in real terms since 2020. Medicare Advantage capitated plans demonstrate lowest price sensitivity due to per-member-per-month incentives, while self-pay patients in direct-access states exhibit highest elasticity.
Supply Chain Analysis
Freight and logistics costs for FDA-cleared robotic exoskeletons and VR rehabilitation systems concentrate supply dependencies on United States, Germany, and Japan manufacturing clusters. Equipment sourcing draws from precision motor suppliers in Japan, sensor arrays from German industrial component makers, and software platforms from United States development hubs. Single-source vulnerability for robotic actuators creates supply chain risk given limited qualified medical device component vendors. Distribution runs through hospital procurement committees, GPO contracts, and direct-to-clinic equipment leasing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rehabilitation therapy services market functions as a stable compounder underpinned by demographic aging that sustains demand inelasticity regardless of reimbursement cycles.
For Market Incumbents: Anchor margin stability through vertical integration into home health delivery where site-of-service premiums persist under Medicare fee schedule adjustments. Consolidate suburban clinic density in Texas and Florida markets where direct access statutes eliminate referral gatekeeping. Defend against teleRehabilitation platform disruption by embedding synchronous video capabilities into existing patient workflows rather than ceding volume to pure-play digital entrants. For New Entrants and Emerging Players: Capture white-space opportunity in rural Medicare Advantage networks where therapist vacancy rates exceed national averages and transportation barriers limit facility access. Penetrate the geriatric home health segment fastest through teleRehabilitation parity reimbursement statutes expanding across state legislatures. Deploy direct-to-patient marketing channels that bypass physician referral dependencies where state licensure permits self-referral. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented outpatient clinic networks lack scale to absorb Medicare fee schedule compression. Target acquisition archetypes combine suburban clinic density with proven outcomes metrics under bundled payment models. Watch Medicare Advantage penetration rates as the inflection signal determining whether capitated or fee-for-service reimbursement frameworks dominate capital deployment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Home Health Integration | Site-of-service arbitrage captures 23-31% reimbursement premiums under Medicare adjustments. |
| Robotic Exoskeleton Deployment | FDA-cleared lower-limb systems command premium billing codes in spinal cord injury rehabilitation. |
| TeleRehabilitation Platform Launch | State parity statutes extend specialist reach into rural markets without facility capital expenditure. |
| Medicare Advantage Network Contracting | Per-member-per-month incentives reward preventive interventions reducing acute utilization. |
| Direct Access State Expansion | Self-referral licensure reforms in 28 states compress time-to-treatment and expand addressable pools. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rehabilitation network executives, physical therapy clinic operators, Medicare policy specialists, hospital procurement managers, and GPO contract administrators with secondary validation against CMS physician fee schedule rulemakings, FDA 510(k) device clearance databases, state physical therapy licensure board records, and Medicare Advantage plan penetration reports. Bottom-up clinic capacity modeling and top-down reimbursement flow analysis provided triangulation.
Segment-weighting approaches distributed volume and value estimates across service type, end user, technology, and application dimensions throughout the forecast period. CAGRs derived from historical Medicare utilization trends, therapist workforce pipeline projections, and technology adoption curves specific to teleRehabilitation parity expansion and robotic device integration timelines. Pricing dynamics incorporated site-neutral payment adjustment impacts and Medicare Advantage capitation incentive structures.
Underlying measurement precision varies by segment; hospital-based rehabilitation units carry tighter precision than fragmented outpatient clinic networks due to consolidated reporting requirements. Forecasts reflect assumptions regarding CMS rulemaking continuity, state licensure reform trajectories, and technology reimbursement recognition timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Global Neurorehabilitation Devices Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Global Home Rehabilitation Products and Services Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
United States Behavioral Rehabilitation Market