
 US Retail Packaged Bread Market | 2026-2036
US Retail Packaged Bread Market Size, Share, and Industry Trends Forecast 2026-2036
US Retail Packaged Bread Market Analysis
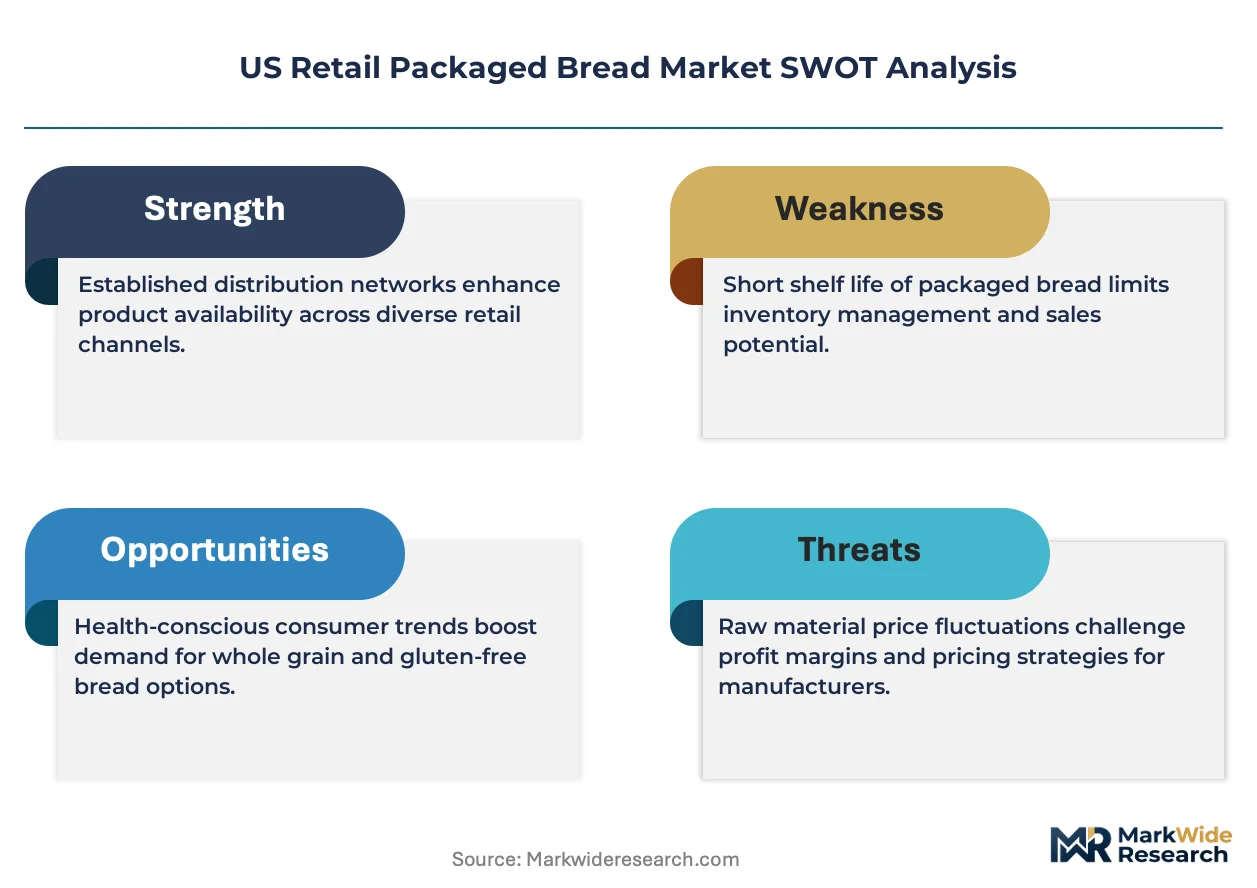
Supermarket center-store shelf space is reconfiguring as private-label and branded bread suppliers compete for reduced linear footage. Flowers Foods sustains broad geographic coverage through its direct-store-delivery network spanning the eastern and southern states. Bimbo Bakeries USA leverages its plant bakeries and warehouse distribution to control cost structures in high-volume segments. Alpha Baking specializes in artisan-style packaged breads that differentiate through regional flavor profiles.
US retail packaged bread denotes commercially manufactured, pre-sliced or whole-loaf bread products sold in sealed packaging through retail channels, typically formulated with enriched wheat flour, water, yeast, and preservatives to achieve shelf lives of five to fourteen days under ambient storage. The primary commercial purpose is to provide standardized, food-safe carbohydrate staples for household consumption and foodservice preparation. White bread remains the mature volume base, though margin pools are shifting toward multigrain and gluten-free varieties where ingredient premiums support higher unit economics. Online retailers represent the fastest-growing distribution channel, while supermarkets retain the dominant share of absolute dollar throughput.
The FDA governs ingredient standards and nutrition labeling under the Federal Food, Drug, and Cosmetic Act, while the USDA oversees organic bread certification through its National Organic Program. These frameworks shape demand by mandating disclosure of added sugars and sodium content, pushing manufacturers toward reformulation. State-level cottage food laws and the FDA's Food Safety Modernization Act further constrain market access for smaller entrants. Stakeholders must monitor evolving sodium reduction targets and clean-label ingredient sourcing requirements as competitive differentiators.
Market Dynamics
Supermarket shelf reconfiguration is compressing linear footage for center-store bread, forcing suppliers to defend space through velocity guarantees and direct-store-delivery service levels rather than slotting fees alone.
Growth Catalysts
- Convenience store channel expansion:C-store operators are widening packaged bread assortments to capture commuter breakfast and lunch occasions, creating incremental velocity for single-serve and smaller loaf formats.
- FDA added-sugar disclosure mandates:The updated Nutrition Facts panel requirements are accelerating reformulation toward reduced-sugar profiles that qualify for front-of-package claims.
- Southeast population clustering:In-migration to Georgia and Florida is concentrating household formation in markets with established baking infrastructure and efficient distribution radii.
Market Restraints
- Wheat input cost volatility:Domestic flour milling capacity concentration in the Great Plains exposes margins to weather-driven supply shocks and rail logistics constraints.
- Private-label shelf space capture:Retailer-owned brands are securing preferential placement through margin-sharing agreements that compress branded supplier negotiating leverage.
- Fresh bakery perimeter competition:In-store bakery programs at Kroger and Albertsons are capturing impulse purchases through sensory cues that packaged bread cannot replicate.
Strategic Opportunities
- Online grocery penetration:Amazon Fresh and Instacart fulfillment centers represent underdeveloped bread distribution infrastructure where temperature-controlled last-mile solutions can establish first-mover advantage.
- Clean-label ingredient positioning:The USDA National Organic Program certification pathway offers premium positioning for suppliers who can secure certified organic flour supply contracts.
- Foodservice co-manufacturing:Restaurant chain bun and roll specifications present volume outlets for excess plant capacity during retail demand troughs.
Industry Challenges
- FSMA compliance timeline compression:The FDA Food Safety Modernization Act preventive controls rule requires hazard analysis documentation that strains quality assurance staffing at mid-tier bakeries.
- Legacy DSD route optimization:Direct-store-delivery networks built for five-day-a-week service face cost restructuring pressure as retailers demand seven-day coverage with reduced order minimums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Retail Packaged Bread Market |
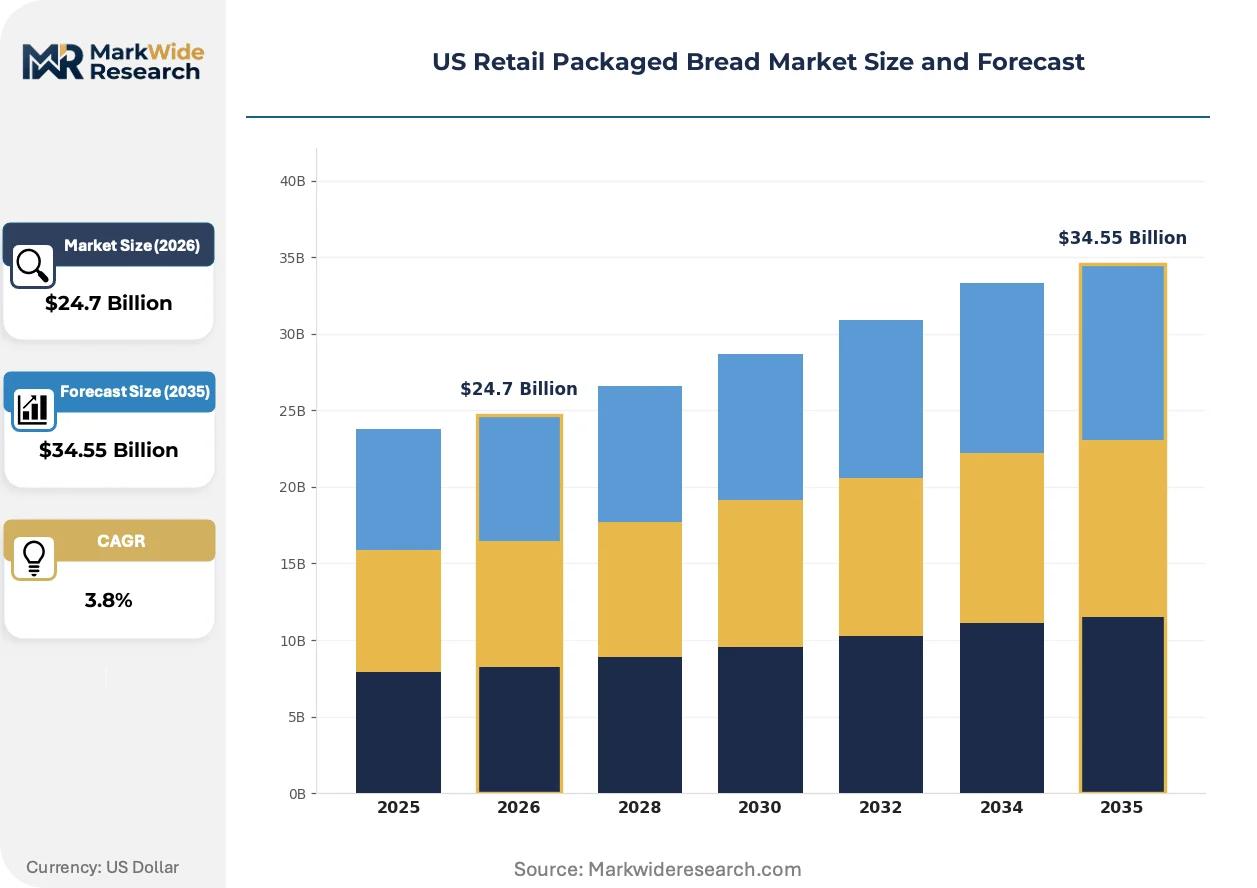
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $34.55 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Bread, Whole Wheat Bread, Multigrain Bread, Gluten-Free Bread Packaging Type: Loaves, Buns, Rolls, Sliced Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores Customer Type: Households, Foodservice, Bakeries, Institutions |
| Companies Covered | Hostess Brands, Sara Lee Frozen Bakery, Flowers Foods, Campbell Soup Company, Harvest Moon Baking, Bimbo Bakeries USA, Alpha Baking, Gruma, Gonnella Baking, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Retail Packaged Bread Market Emerging Trajectories
Reformulation chemistry and distribution logistics are converging to redefine shelf-stable bread economics, with preservation science and channel strategy now interdependent rather than sequential decisions.
High-pressure processing is migrating from refrigerated ready-to-eat meats into ambient bread applications as a clean-label mold inhibition alternative to calcium propionate. Premium positioned brands are piloting HPP-treated sourdough lines in Pacific Northwest test markets. The technology is enabling fourteen-to-twenty-one day shelf life extensions without chemical preservatives, compressing the traditional trade-off between ingredient simplicity and distribution reach.
The FDA Food Safety Modernization Act's intentional adulteration rule is mandating documented food defense plans for bakeries above specified production thresholds. Large-scale plant bakeries are investing in access control and ingredient tracking systems to satisfy compliance audits. Facilities in California and Texas are most affected due to their scale concentration and proximity to population centers requiring heightened security protocols.
Household pantry loading patterns have shifted toward stock-up shopping trips with extended inter-purchase intervals. Club store channels are capturing this behavioral change through multiloop bread packaging that reduces per-unit cost. The shift is most visible in suburban markets where Costco and Sam's Club locations anchor weekly shopping routines.
US Retail Packaged Bread Market Segmentation
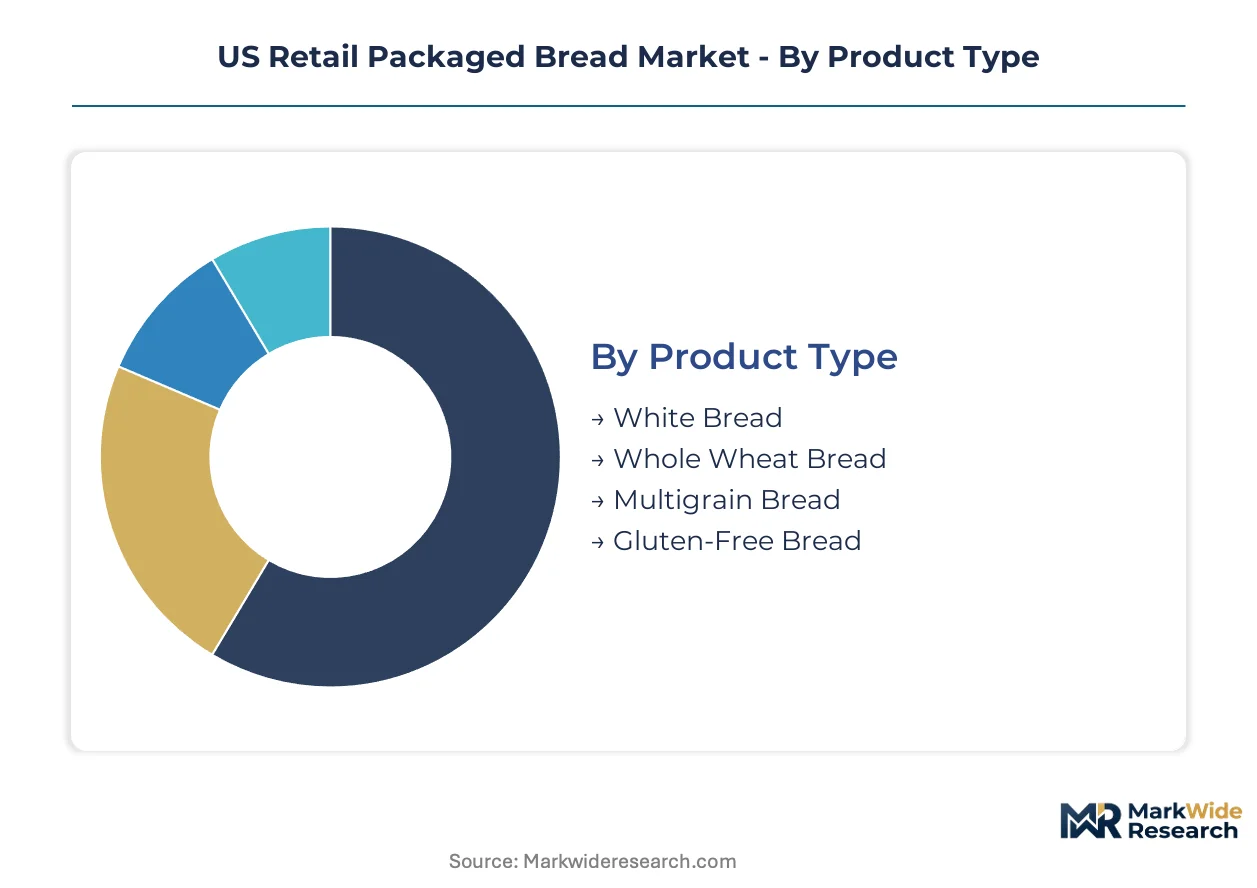
Packaged bread segmentation reveals how formulation chemistry, packaging engineering, and channel economics intersect to determine margin capture. Each dimension shapes procurement priorities and shelf placement negotiations differently across the value chain.
Product Type:
Cost tier stratification defines competitive intensity, with ingredient premiums determining whether suppliers compete on velocity or margin extraction.
- White Bread:Formulated with enriched wheat flour and minimal fiber content, this segment delivers standardized carbohydrate staples at lowest unit cost. Demand concentrates in the Southeast, where established baking infrastructure in Georgia and Florida supports high-volume production with compressed distribution radii.
- Whole Wheat Bread:Retains bran and germ fractions to meet FDA whole grain labeling thresholds, commanding ingredient premiums that support higher retail price points. Households in suburban markets with Costco and Sam's Club locations are rotating toward stock-up formats that reduce per-unit cost exposure.
- Multigrain Bread:Incorporates oats, barley, and seeds for texture differentiation and front-of-package health claims.
- Gluten-Free Bread:Formulated with rice flour, tapioca starch, and xanthan gum to replace wheat gluten structure, targeting diagnosed celiac and discretionary avoidance segments.
White bread holds installed capacity. Gluten-free is rotating up the share rankings.
Packaging Type:
Volume throughput and occasion specificity determine which formats secure linear footage in reconfigured center-store layouts.
- Loaves:Standard 20-24 oz poly-bagged configurations dominate household pantry loading patterns with five-to-fourteen-day ambient shelf life. Club store channels are capturing behavioral shifts through multiloop packaging that aligns with extended inter-purchase intervals.
- Sliced:Pre-portioned products reduce preparation friction for foodservice sandwich assembly and institutional feeding programs. The Southeast's population clustering in Georgia and Florida concentrates demand where efficient distribution radii minimize logistics cost.
- Buns:Sized for hamburger and hot dog specifications, these formats compete with in-store bakery programs at Kroger and Albertsons.
- Rolls:Dinner and sandwich roll configurations serve foodservice co-manufacturing opportunities during retail demand troughs.
Loaves hold installed capacity. Sliced is rotating up the share rankings.
Distribution Channel:
Customer type and purchase occasion fragmentation force suppliers to defend space through service levels rather than slotting fees alone.
- Supermarkets:Center-store shelf reconfiguration is compressing linear footage, forcing velocity guarantees and direct-store-delivery service levels. Private-label shelf space capture through margin-sharing agreements compresses branded supplier negotiating leverage.
- Online Retailers:Amazon Fresh and Instacart fulfillment centers represent underdeveloped bread distribution infrastructure where temperature-controlled last-mile solutions can establish first-mover advantage.
- Convenience Stores:C-store operators are widening assortments to capture commuter breakfast and lunch occasions, creating incremental velocity for single-serve formats.
- Specialty Stores:Regional flavor profile positioning through artisan-style packaged breads targets premium household segments.
Supermarkets hold installed capacity. Online retailers are rotating up the share rankings.
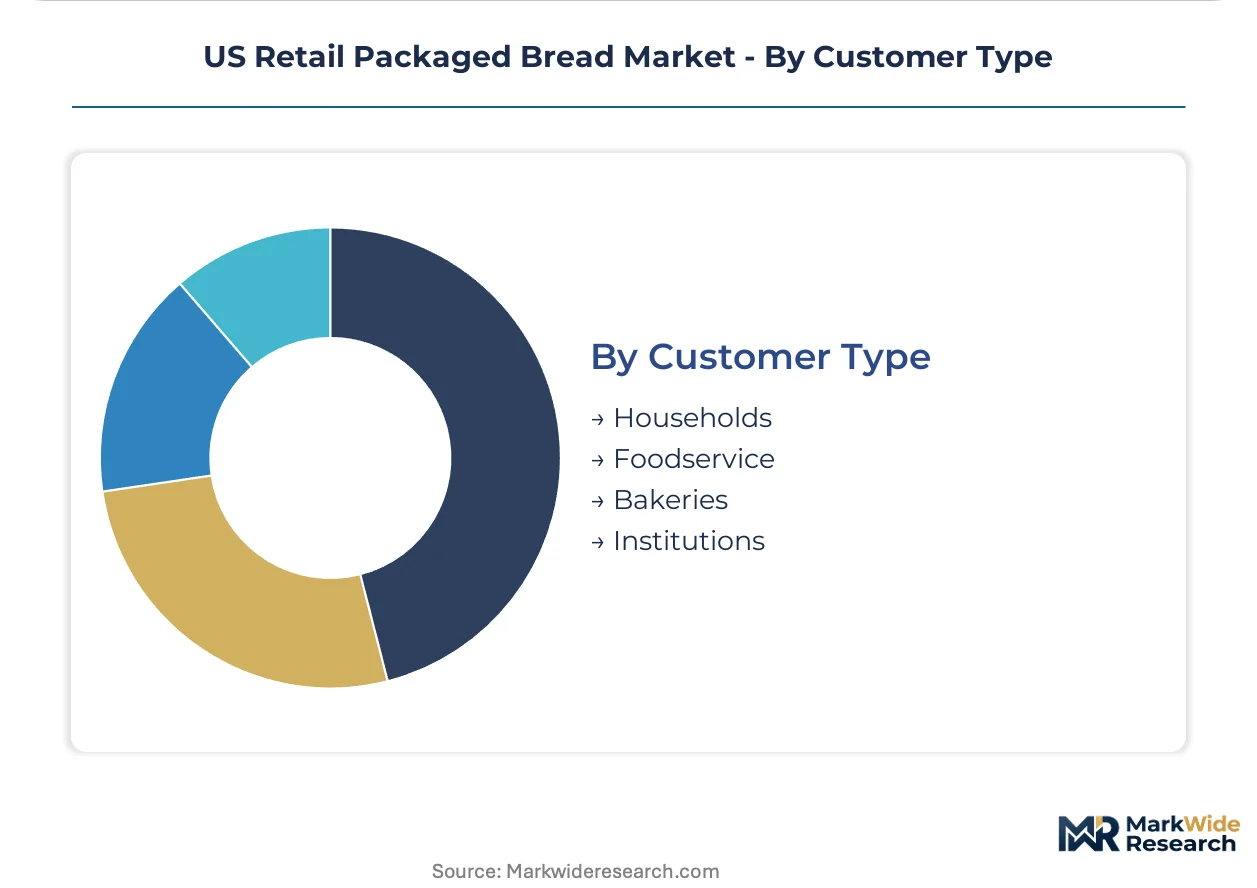
Customer Type:
Application-specific specifications determine whether production runs prioritize retail velocity or foodservice contract stability.
- Households:Pantry loading patterns have shifted toward stock-up shopping trips with extended inter-purchase intervals, favoring multiloop packaging formats.
- Foodservice:Restaurant chain bun and roll specifications present volume outlets for excess plant capacity during retail demand troughs.
- Bakeries:Ingredient sourcing requirements for clean-label positioning strain quality assurance staffing at mid-tier facilities.
- Institutions:School and healthcare feeding programs demand cost-competitive sliced formats with documented nutritional compliance.
Households hold installed capacity. Foodservice is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate highway network and Class I rail corridors through the Great Plains link grain elevators to milling capacity, underwriting the Southeast's concentration of packaged bread manufacturing.
Southeast
Population in-migration to Georgia and Florida concentrates household formation in markets with established baking infrastructure. The FDA's updated Nutrition Facts labeling requirements for added sugars are accelerating regional reformulation toward lower-sugar profiles. Efficient distribution radii from Atlanta and Orlando plant bakeries minimize logistics cost for high-velocity white and whole wheat segments.
Midwest
Domestic flour milling capacity concentration in Illinois and Ohio exposes margins to weather-driven supply shocks. State-level cottage food laws and the FDA Food Safety Modernization Act constrain market access for smaller entrants. Chicago and Detroit serve as consolidation points for rail-sourced wheat and outbound truck distribution to retail chains.
West Coast
Pacific Northwest test markets are piloting high-pressure processing for clean-label mold inhibition in sourdough lines. California's scale concentration triggers heightened FDA food defense plan requirements for intentional adulteration compliance. Los Angeles and Seattle facilities invest in access control systems to satisfy audit protocols.
Northeast
Club store channels through suburban New York and Boston markets capture stock-up shopping patterns with multiloop packaging formats. The USDA National Organic Program certification pathway supports premium positioning for suppliers securing organic flour contracts. Philadelphia and Hartford distribution centers manage temperature-controlled last-mile solutions for online grocery penetration.
Southwest
Texas plant bakeries face cost restructuring pressure as retailers demand seven-day direct-store-delivery coverage. The FDA's preventive controls rule strains quality assurance staffing at mid-tier facilities. Dallas and Houston anchor foodservice co-manufacturing relationships for restaurant chain bun and roll specifications.
US Retail Packaged Bread Market Vendor Landscape
On the supply side, the industry is consolidating around national-scale plant bakeries with direct-store-delivery networks and regional artisan specialists. Three strategic archetypes dominate: diversified consumer packaged goods conglomerates with bakery divisions, independent baking companies with geographic density in specific corridors, and private-label suppliers aligned with retailer margin-sharing agreements. Competitive moves center on route optimization technology deployment and clean-label ingredient sourcing certifications.
Within the national-scale tier, Flowers Foods and Bimbo Bakeries USA exemplify archetypes built on distribution infrastructure breadth. Alpha Baking occupies a position representing specialty and artisan-style differentiation through regional flavor profiles. These three anchors illustrate how scale economies and positioning specialization coexist as viable competitive vectors.
| Leading Market Players |
|---|
| Hostess Brands |
| Sara Lee Frozen Bakery |
| Flowers Foods |
| Campbell Soup Company |
| Harvest Moon Baking |
| Bimbo Bakeries USA |
| Alpha Baking |
| Gruma |
| Gonnella Baking |
| Others |
Supply Flow & Price Mechanics
Class I rail corridors through the Great Plains transmit weather-driven wheat cost volatility into downstream price stratification, compressing margins for unhedged millers while rewarding suppliers with captive flour supply. This freight-cost dynamic concentrates negotiating leverage among integrated plant bakeries that control both milling capacity and direct-store-delivery networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs shelf placement economics, with multigrain and gluten-free varieties capturing ingredient-premium markups while white bread competes on velocity. Price differentiation rests on USDA organic certification status and direct-store-delivery service frequency rather than slotting fees alone. Pricing pressure stems from private-label margin-sharing agreements that compress branded supplier leverage. Foodservice buyers exhibit highest price sensitivity due to contract bidding cycles, while specialty store channels absorb premium positioning with lower volume elasticity.
Supply Chain Analysis
Export-control regimes on agricultural biotechnology germplasm constrain access to drought-resistant wheat varieties, limiting domestic breeding program advancement. Geographic supply concentration centers on Great Plains grain elevators, Illinois and Ohio milling capacity, and Southeast plant bakeries in Georgia and Florida. Raw material dependencies encompass hard red winter wheat, enriched flour additives, and clean-label mold inhibitors. Single-source vulnerability runs through concentrated rail logistics from grain belt to milling hubs. Distribution runs through direct-store-delivery networks for retail velocity and warehouse fulfillment for club store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US retail packaged bread market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA Food Safety Modernization Act compliance documentation and preventive controls requirements create structural barriers that mid-tier entrants cannot readily replicate.
For Market Incumbents: Insulate route density advantages through seven-day direct-store-delivery coverage commitments that smaller competitors cannot cost-justify, while accelerating high-pressure processing pilot programs to capture fourteen-to-twenty-one-day shelf life extensions ahead of clean-label reformulation curves. Private-label shelf space capture and fresh bakery perimeter competition at Kroger and Albertsons represent immediate threats requiring velocity guarantee renegotiation. For New Entrants and Emerging Players: Pursue foodservice co-manufacturing contracts for restaurant chain bun and roll specifications during retail demand troughs, exploiting excess capacity windows at underutilized plant bakeries. Online grocery penetration through Amazon Fresh and Instacart fulfillment centers offers the most penetrable white space, where temperature-controlled last-mile infrastructure remains underdeveloped and first-mover advantage is achievable through regional flavor profile differentiation. For Investors and Strategic Acquirers: Regional artisan specialists with established USDA National Organic Program certification pathways and locked organic flour supply contracts present the most compelling acquisition target archetype, given premium positioning durability and input cost hedge characteristics. Long-term viability over a five-to-ten year window hinges on clean-label ingredient sourcing scalability rather than volume scale alone. Watch sodium reduction target announcements from FDA as the critical inflection indicator forcing accelerated reformulation capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Store-Delivery Network Expansion | Seven-day coverage commitments lock in shelf space against warehouse-distributed competitors at Kroger and Albertsons. |
| High-Pressure Processing Pilot Scale-Up | Fourteen-to-twenty-one-day shelf life extensions without calcium propionate satisfy Pacific Northwest clean-label demand clusters. |
| USDA Organic Certification Investment | National Organic Program status commands front-of-package premium positioning in Northeast club store channels. |
| Foodservice Co-Manufacturing Partnership | Restaurant chain bun specifications absorb excess Texas and California plant capacity during retail demand troughs. |
| Online Grocery Last-Mile Infrastructure | Temperature-controlled fulfillment solutions for Amazon Fresh establish defensive positioning in fastest-growing distribution channel. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings, with plant bakery operations directors, category buyers at Albertsons and Kroger, direct-store-delivery route managers, and FDA compliance officers contributing operational perspective. Secondary sources encompass FDA Food Safety Modernization Act guidance documents, USDA National Organic Program certification databases, SEC 10-K filings from publicly traded baking companies, and Nielsen retail audit data. Bottom-up volume modeling from regional plant capacity and top-down expenditure flow analysis triangulate market sizing.
Calibration against historical volume trajectories and input cost elasticity patterns informs the analytical framework across the projection horizon. Segmentation dimensions encompass product type stratification, packaging format engineering, distribution channel economics, and customer application specifications. CAGRs derive from regression analysis of population migration patterns, household formation rates, and channel shift velocities. Industry-specific forecast inputs include wheat futures curve movements and convenience store channel expansion capex disclosures.
Macroeconomic conditions sit as an overlay; deviation in rail freight rates, diesel fuel costs, and wheat harvest yields would shift the trajectory. Forecasts reflect documented assumptions regarding FDA enforcement timelines and retailer shelf reconfiguration pace. Material shifts in preventive controls rule implementation stringency or intentional adulteration audit protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread Dough Improver Market
Bakery Products
Matcha Cookie Market
Bakery Products
Flatbread Market
Bakery Products
Bakery Emulsions Market
Bakery Products
North America Sweet Biscuits Market
Bakery Products
Dough Conveyor Market
Bakery Products
Biscuits Market
Bakery Products
Bakery Flavors Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
No-Fat Cake Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Doughnuts Market
Bakery Products
Europe Sourdough Market
Bakery Products
Batter and Breader Premixes Market
Bakery Products
Frozen Bakery Market
Bakery Products
Biscuit Mixes Market