
 Multigrain Bread Mix Market | 2026-2036
Multigrain Bread Mix Market Size, Share, and Industry Trends Forecast 2026-2036
Multigrain Bread Mix Market Analytics
The gap between premium artisan-grade multigrain blends and commodity supermarket mixes is broadening, driven by divergent ingredient sourcing standards and protein content specifications. King Arthur Baking Company leverages its direct-to-consumer channel and heritage positioning to sustain loyalty among home bakers seeking certified organic formulations. Lesaffre Group anchors the commercial bakery segment through yeast and bread improver integration that streamlines multigrain production at scale. General Mills, Inc. competes via mass-market distribution density, while Bob's Red Mill Natural Foods differentiates through stone-ground processing transparency and gluten-free multigrain alternatives.
Multigrain bread mix denotes a pre-formulated dry blend combining two or more cereal flours—typically wheat, rye, oat, and barley—with functional additives such as vital wheat gluten, malted barley flour, and emulsifiers to achieve consistent hydration, fermentation tolerance, and crumb structure in finished loaves. The blend serves commercial bakeries and foodservice operators seeking batch standardization without proprietary milling infrastructure. Whole wheat and oat variants lead volume due to established consumer familiarity and lower per-unit cost, while barley-based formulations represent the fastest-growing product type as beta-glucan labeling claims attract functional food positioning. Pouch packaging captures momentum in online retail channels where portion control and resealability reduce spoilage, though bag formats still dominate supermarket shelves. Bakeries and cafes constitute the most concentrated end-user margin pool, as these accounts prioritize consistent performance over price sensitivity and often specify custom protein levels.
EFSA nutrition and health claims regulations govern permissible fiber and whole-grain marketing statements across European markets, while FDA enforcement of Food Safety Modernization Act preventive controls affects import and domestic manufacturing standards in the United States. India's FSSAI fortification guidelines for edible-grade flours additionally influence export-oriented producers targeting institutional buyers. Stakeholders must monitor evolving whole-grain definition harmonization between Codex Alimentarius and national regulators, as divergent thresholds for multigrain labeling create compliance fragmentation that favors regionally adaptive formulation strategies.
Market Dynamics
Clean-label regulatory pressure from EFSA and FDA is fragmenting formulation standards across export corridors, forcing producers to maintain parallel SKUs with divergent additive allowances and fiber thresholds rather than unified global recipes.
Growth Catalysts
- EFSA nutrition claims harmonization:Permissible beta-glucan and whole-grain marketing thresholds in Europe validate functional positioning for barley- and oat-dominant blends, accelerating retail shelf placement.
- Artisan bakery channel expansion:Health-focused cafes in Germany, India, and Brazil specify custom protein levels and stone-ground credentials, creating premium margin pools insulated from commodity pricing.
- Stone-ground processing revival:Heritage milling transparency attracts direct-to-consumer purchasers seeking minimal processing narratives alongside gluten-free multigrain alternatives.
Market Restraints
- Vital wheat gluten cost volatility:Protein concentrate prices fluctuate with biofuel-driven wheat diversion, compressing margins on high-protein commercial bakery formulations.
- Malted barley flour supply concentration:Malting capacity clusters in specific agrarian regions, exposing blenders to harvest-quality variability and contract allocation constraints.
- Codex Alimentarius divergence:Non-harmonized whole-grain definitions between international standards and national regulators create labeling compliance friction for cross-border producers.
Strategic Opportunities
- FSSAI fortification guidelines:India's institutional flour fortification mandates create specification pathways for export-oriented producers targeting school feeding and government procurement channels.
- Pouch packaging channel innovation:Resealable portion-control formats capture online retail momentum where home bakers prioritize freshness management and trial-sized experimentation.
- Functional food convergence:Beta-glucan labeling claims intersect with digestive health positioning, opening pharmacy and wellness retail distribution beyond conventional grocery.
Industry Challenges
- Fermentation tolerance engineering:Multigrain hydration variability demands skilled technical service teams to troubleshoot batch consistency for commercial bakery accounts with automated production lines.
- Preventive controls compliance:FDA Food Safety Modernization Act enforcement requires validated supply-chain documentation that strains smaller millers lacking enterprise-grade traceability systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multigrain Bread Mix Market |
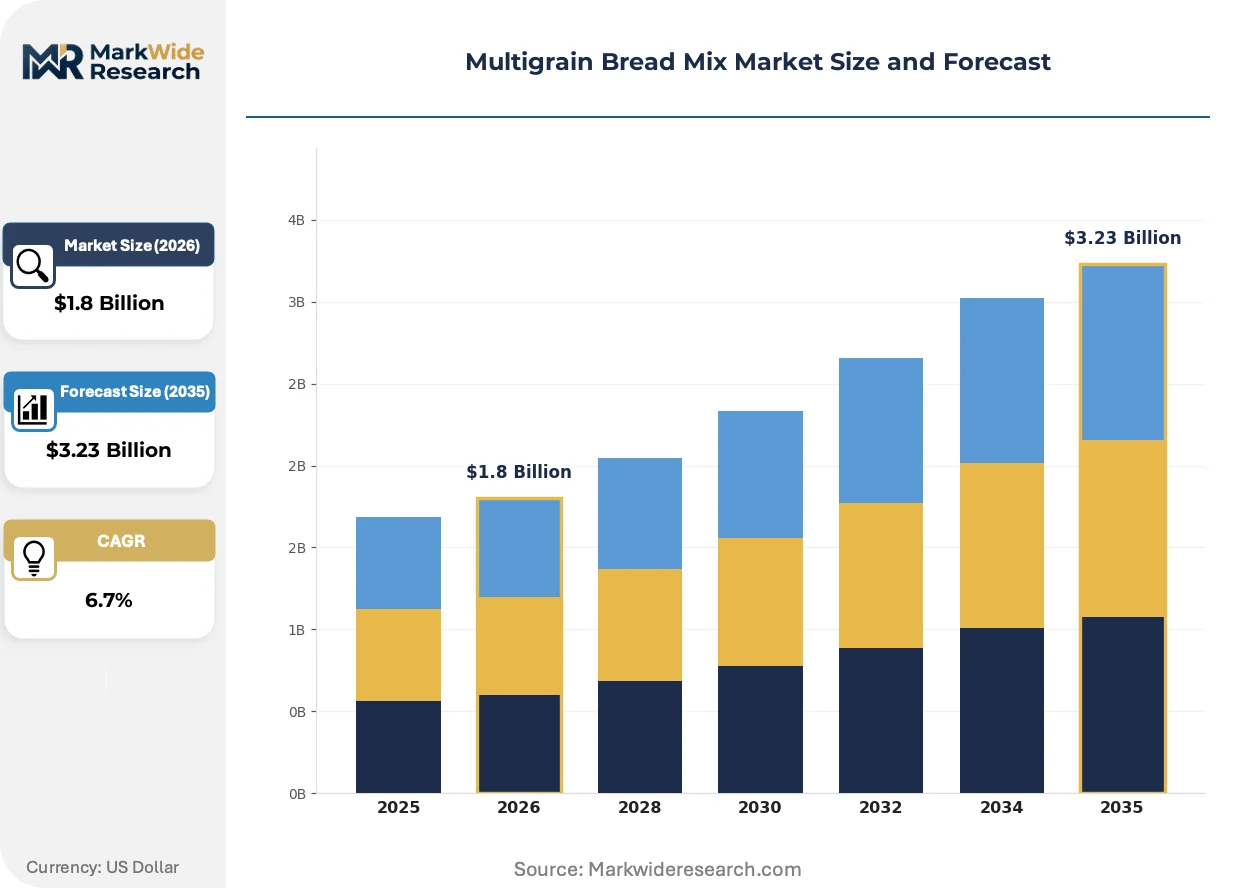
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, Rye, Oat, Barley Packaging Type: Bags, Boxes, Jars, Pouches Distribution Channel: Supermarkets, Health Stores, Online Retail, Local Markets End User: Households, Restaurants, Bakeries, Cafes |
| Companies Covered | King Arthur Baking Company, Lesaffre Group, General Mills, Inc., AB Mauri India, Orowheat, Archer Daniels Midland Company, Bob's Red Mill Natural Foods, Bakels Worldwide, Puratos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multigrain Bread Mix Market Evolving Landscape
Formulation science and packaging engineering are converging to address the tension between extended shelf stability and clean-label ingredient panels, reshaping how producers balance functional performance with consumer transparency demands.
Sourdough starter integration into dry multigrain blends is unifying the convenience of pre-mixed formulations with the fermentation complexity artisan bakers demand. Small commercial bakeries in Germany and urban India adopt these hybrid products to reduce labor-intensive starter maintenance. This convergence is compressing the traditional divide between scratch baking and industrial mix dependency.
EFSA's evolving enforcement of nutrition and health claims regulations is tightening permissible fiber marketing language across European markets. Blend producers reformulate to meet specific beta-glucan thresholds rather than general whole-grain percentages. Barley-dominant SKUs face the steepest compliance recalibration as claim substantiation requirements intensify.
Home baking experimentation patterns are shortening repurchase cycles as consumers trial multiple grain combinations before settling on preferred formulations. Direct-to-consumer channels capture this behavior through subscription and sampler assortments that supermarket bag formats cannot replicate. This rotation is most pronounced in US and German markets where heritage brand loyalty competes with discovery-driven purchasing.
Multigrain Bread Mix Market Segmentation
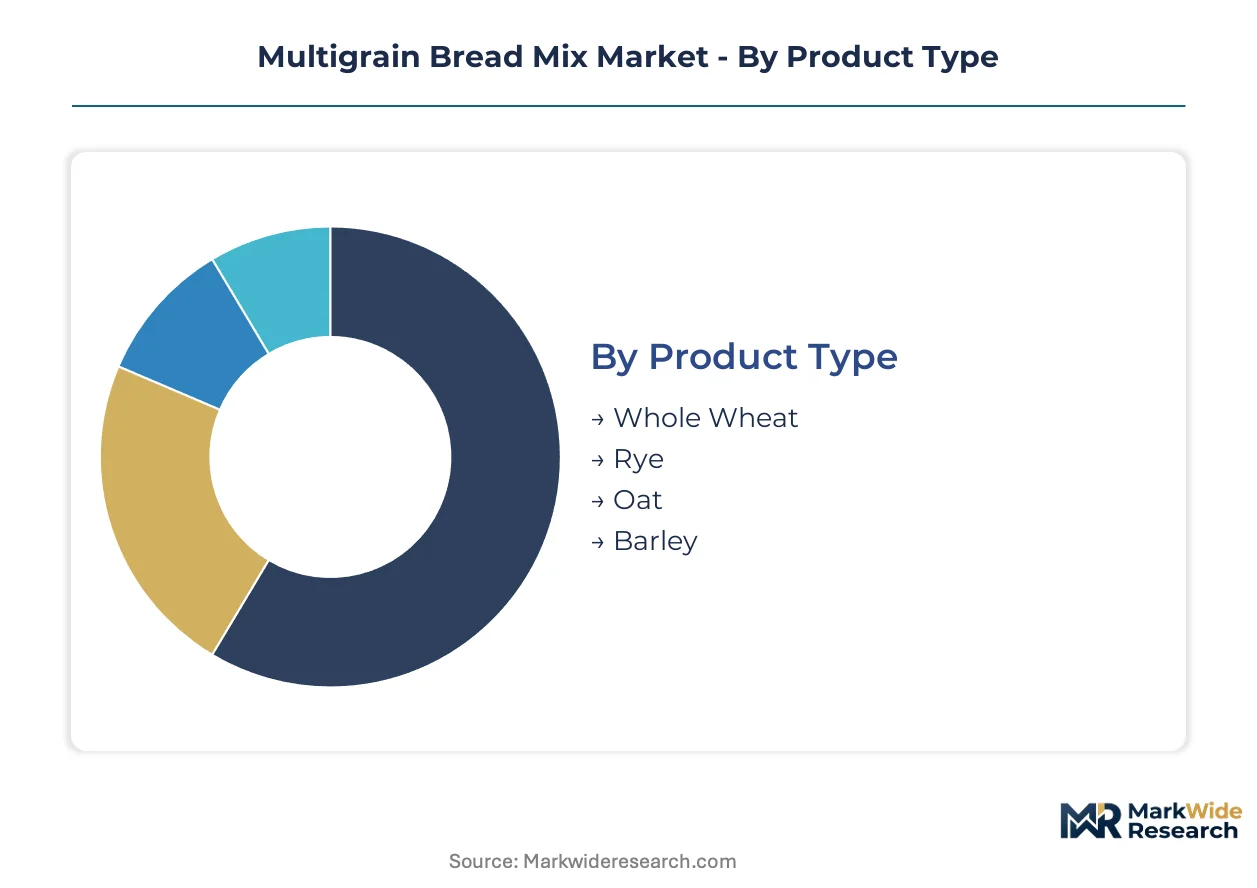
Multigrain bread mix segmentation reflects divergent performance requirements across artisan and industrial baking environments. Producers calibrate protein content, hydration tolerance, and fermentation stability differently for each channel, creating distinct margin pools and technical service demands.
Product Type:
Customization intensity varies sharply across this category, with heritage formulations commanding premium positioning against commodity blends optimized for automated production lines.
- Whole Wheat:Dominant volume segment combining hard red winter wheat with vital wheat gluten for structural integrity in high-speed commercial bakery applications. German artisan bakeries and Indian urban cafes specify protein levels above 13% to ensure oven spring in deck ovens, though biofuel-driven wheat diversion creates input cost volatility that compresses margins on standardized formulations.
- Barley:Beta-glucan soluble fiber content enables EFSA-validated cholesterol reduction claims in European markets, accelerating placement in pharmacy and wellness retail channels beyond conventional grocery. German health-focused cafes and Brazilian functional food specialists specify this segment for digestive health positioning, though malting capacity concentration in specific agrarian regions exposes supply chains to harvest-quality variability.
- Oat:Mild flavor profile and established consumer familiarity support mass-market penetration, with lower per-unit cost driving volume in supermarket channels.
- Rye:Traditional fermentation complexity demands skilled technical support for hydration management, limiting adoption to heritage bakeries and specialty accounts.
Leading the category by volume: Whole Wheat. Expanding most quickly: Barley.
Packaging Type:
Cost tiers separate industrial-scale formats from convenience-oriented solutions targeting home baking experimentation patterns.
- Pouches:Resealable portion-control formats capture online retail momentum where freshness management and trial-sized experimentation drive repurchase cycles. Direct-to-consumer channels in the United States and Germany deploy subscription assortments that supermarket bag formats cannot replicate, shortening consumer discovery phases before preference consolidation.
- Bags:Dominant supermarket format optimized for cost efficiency at scale, though limited resealability accelerates spoilage in humid climates and reduces home baker satisfaction scores.
- Boxes:Premium positioning through structural protection and gift-ready aesthetics, concentrated in specialty retail and seasonal purchasing occasions.
- Jars:Airtight storage appeals to ingredient-conscious home bakers seeking extended pantry stability, though shipping weight disadvantages limit e-commerce penetration.
Fastest channel shift: Pouches gaining share in online retail. Largest installed base: Bags.
Distribution Channel:
Customer type determines margin structure, with specification-driven accounts prioritizing technical service over price sensitivity.
- Supermarkets:Mass-market density demands standardized SKUs with broad fermentation tolerance, though slotting fees and promotional calendars compress net margins for blend producers competing on price.
- Online Retail:Direct-to-consumer experimentation patterns favor sampler assortments and subscription models, enabling heritage brands to bypass retail intermediaries and capture full margin on certified organic formulations.
- Health Stores:Pharmacy and wellness retail placement requires beta-glucan threshold documentation and clean-label ingredient panels that strain smaller millers lacking enterprise-grade traceability systems.
- Local Markets:Fragmented procurement in India and Brazil creates specification inconsistency, though FSSAI fortification guidelines open institutional pathways for export-oriented producers targeting government feeding programs.
Highest margin concentration: Health Stores. Steepest volume growth: Online Retail.
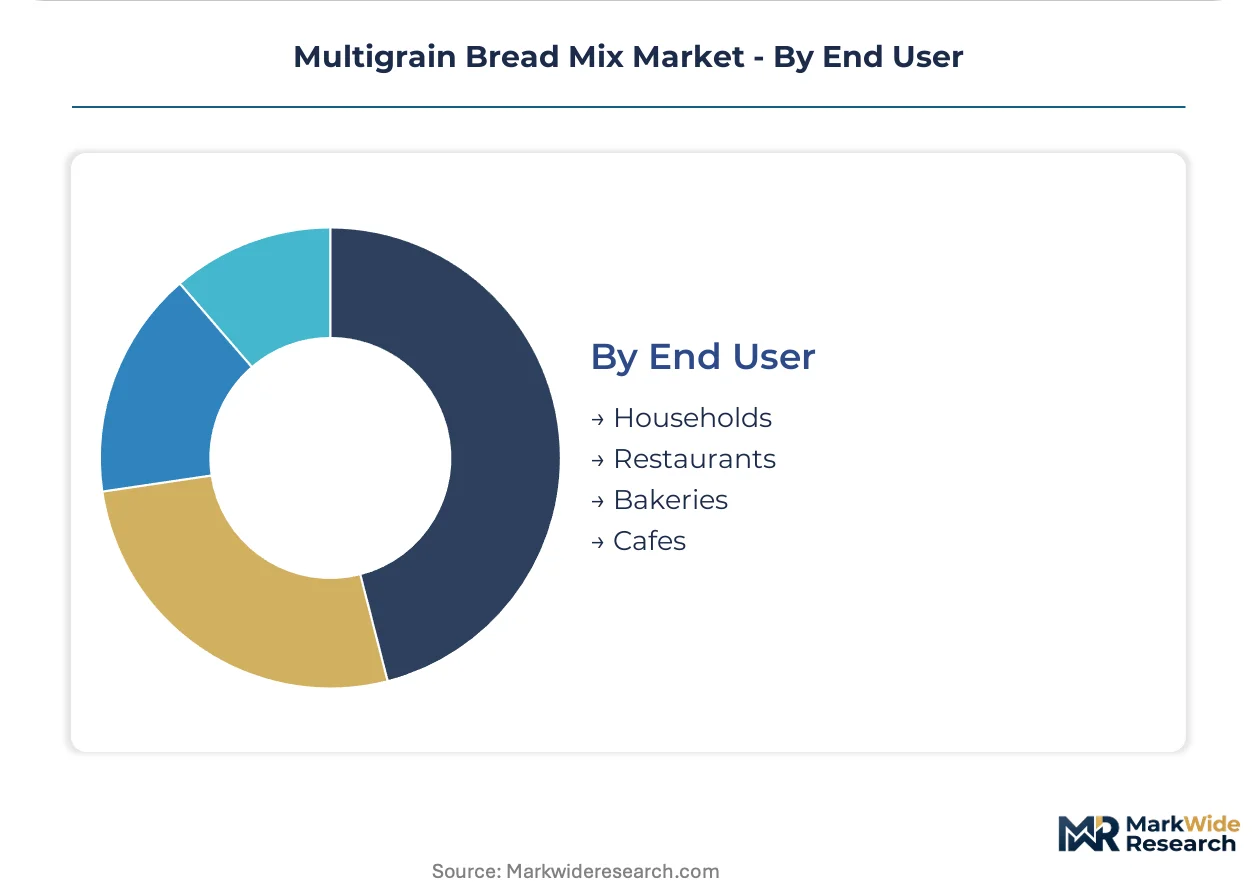
End User:
Maturity gradients separate established commercial baking infrastructure from emerging home baking segments.
- Bakeries:Most concentrated margin pool as accounts specify custom protein levels and stone-ground credentials, creating insulation from commodity pricing through technical service relationships and batch standardization requirements.
- Cafes:Health-focused operators in Germany, India, and Brazil drive artisan-grade demand, specifying fermentation tolerance and heritage milling transparency that commands premium positioning.
- Households:Home baking experimentation shortens repurchase cycles as consumers trial multiple grain combinations, though price sensitivity limits adoption of premium formulations beyond occasional purchasers.
- Restaurants:Foodservice operators prioritize consistent performance over brand loyalty, favoring commercial bakery suppliers with validated supply-chain documentation for FDA preventive controls compliance.
Deepest technical service requirements: Bakeries. Fastest adoption acceleration: Cafes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European multigrain bread mix innovation through its dense concentration of artisan bakeries and health-focused cafes that specify custom protein formulations. This Bavarian hub intersects traditional bread culture with functional nutrition trends that reshape regional demand patterns.
Germany
Artisan bakeries in Bavaria and Baden-Württemberg drive specification-grade demand for stone-ground multigrain blends with protein levels exceeding 13%. EFSA nutrition claims harmonization validates beta-glucan marketing for barley-dominant formulations, accelerating pharmacy and wellness retail placement. The Munich-Stuttgart corridor concentrates technical service relationships between blend producers and heritage milling operations.
United States
Home baking experimentation in metropolitan areas shortens repurchase cycles through direct-to-consumer subscription models. FDA enforcement of Food Safety Modernization Act preventive controls strains smaller millers lacking enterprise-grade traceability systems. The Pacific Northwest and Northeast corridors anchor stone-ground processing revival among ingredient-conscious consumers seeking minimal processing narratives.
India
Urban cafes in Mumbai and Bangalore specify fermentation tolerance and heritage credentials that command premium positioning for multigrain formulations. FSSAI fortification guidelines for edible-grade flours create specification pathways for export-oriented producers targeting institutional buyers. The Maharashtra-Karnataka corridor concentrates health-focused foodservice adoption.
Brazil
Functional food specialists in São Paulo and Rio de Janeiro accelerate barley-based blend adoption for digestive health positioning. ANVISA regulatory frameworks govern permissible fiber marketing statements that influence product formulation standards. The Southeast region concentrates demand from wellness retail channels beyond conventional grocery distribution.
Multigrain Bread Mix Market Competitive Landscape
Premium-margin players sit above commodity-margin players across ingredient sourcing standards and protein content specifications, creating tiered competitive dynamics. The vendor base spans heritage millers, commercial bakery suppliers, and mass-market distributors with divergent technical service capabilities. Three archetypes dominate: direct-to-consumer heritage brands, commercial bakery integrators, and mass-market distributors. M&A activity concentrates on yeast and bread improver integration, while capacity expansion targets pouch packaging for online retail channels.
Among US-based heritage specialists, King Arthur Baking Company and Bob's Red Mill Natural Foods exemplify the direct-to-consumer archetype through certified organic positioning and stone-ground processing transparency. Lesaffre Group anchors the commercial bakery segment as a French multinational with yeast and bread improver integration capabilities. These three entities occupy distinct margin tiers that insulate premium players from commodity pricing pressure.
| Leading Market Players |
|---|
| King Arthur Baking Company |
| Lesaffre Group |
| General Mills, Inc. |
| AB Mauri India |
| Orowheat |
| Archer Daniels Midland Company |
| Bob's Red Mill Natural Foods |
| Bakels Worldwide |
| Puratos Group |
| Others |
Value Network & Pricing Analysis
EFSA clean-label mandates and FDA Food Safety Modernization Act enforcement gate qualified supply access and premium-tier pricing power for multigrain bread mix producers. Compliance documentation burdens favor enterprise-grade millers with validated traceability systems, compressing margins for smaller operators unable to absorb certification costs.
Pricing Analysis
Yield-per-batch performance anchors value-based pricing for commercial bakery accounts specifying fermentation tolerance and protein content thresholds. Three-tier pricing structure separates certified organic stone-ground formulations from standard commercial blends and economy supermarket SKUs. Cost compression in the commodity tier intensifies as biofuel-driven wheat diversion elevates vital wheat gluten input expenses. Home baking households exhibit highest price sensitivity, while artisan bakeries and health-focused cafes prioritize technical service relationships over per-unit cost.
Supply Chain Analysis
Milling technician shortages in Germany, France, and the United States constrain malting capacity expansion for barley-dominant formulations. Supply chains draw from concentrated agrarian regions in Bavaria, the American Midwest, and the Canadian prairies for premium wheat and malting barley inputs. Single-source vulnerability in malted barley flour contracts exposes blenders to harvest-quality variability and allocation constraints. Distribution runs through direct-to-consumer channels for heritage brands and commercial bakery integrators, with mass-market density flowing through supermarket and foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EFSA and FDA compliance documentation burdens will force smaller millers lacking enterprise-grade traceability systems toward acquisition or exit.
For Market Incumbents: Extend technical service capabilities into fermentation tolerance engineering to defend against emerging sourdough-starter hybrid entrants. Capture backward integration into malting capacity in Bavaria and the American Midwest to secure barley supply against harvest variability. Prioritize pouch packaging capacity additions for online retail channels where subscription models capture full margin. For New Entrants and Emerging Players: Direct-to-consumer subscription routes offer lowest barrier to entry for heritage-positioned brands targeting home baking experimentation patterns in Germany and the United States. White-space concentrates in FSSAI-compliant fortification blends for Indian institutional procurement and beta-glucan validated formulations for Brazilian wellness retail. Launch through sampler assortments that shorten consumer discovery phases before preference consolidation. For Investors and Strategic Acquirers: ANVISA regulatory framework finalization in Brazil is the leading indicator that pharmacy and wellness retail channel penetration will accelerate for functional positioning claims. Target acquisition archetypes include stone-ground heritage millers with certified organic credentials and established direct-to-consumer infrastructure. Watch for EFSA beta-glucan threshold enforcement tightening as signal for barley-dominant formulation premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Malting Capacity | Captive barley supply secures beta-glucan sourcing against harvest-quality variability in concentrated agrarian regions. |
| Pouch Packaging Line Expansion | Resealable formats capture online retail momentum where King Arthur and Bob's Red Mill dominate subscription channels. |
| FSSAI Fortification Certification | Compliance opens institutional procurement pathways for Indian school feeding and government flour programs. |
| Sourdough Starter Hybrid Development | Convenience-positioned products compress the scratch-baking versus industrial-mix divide for German artisan bakeries. |
| Direct-to-Consumer Platform Buildout | Bypassing retail intermediaries captures full margin on certified organic formulations for ingredient-conscious households. |
Research Methodology
Independent corroboration across commercial bakery procurement directors, artisan miller technical leads, and health-store category buyers underwrites the qualitative findings in this study. Primary fieldwork with foodservice operators in Munich, Mumbai, and São Paulo combined with secondary validation from EFSA guidance documents, FDA FSMA enforcement records, and FSSAI fortification circulars. Bottom-up volume modeling from grain input flows and top-down demand triangulation from retail channel audits anchored the analysis.
Comparable historical reference periods spanning pre-pandemic baseline, supply disruption interval, and normalization phase anchored the forecast window across the projection horizon. Segmentation dimensions modeled include product type granularity, packaging format evolution, distribution channel margin structure, and end-user technical service intensity. CAGRs derived from elasticity-adjusted demand curves incorporating protein content specification trends and clean-label regulatory trajectory. Forecast inputs integrated malting capacity utilization rates and biofuel policy impacts on wheat diversion.
The model holds under stable regulatory enforcement intensity and intact malting supply contracts; deviation in EFSA claim substantiation requirements or severe harvest-quality disruption would shift volume and value trajectories. Forecasts embed assumptions about continued artisan bakery channel expansion and online retail penetration rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Gulf Cooperation Council Frozen Bakery Products Market
Bakery Products
Baking Mixes Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Cake Base Discs Market
Bakery Products
Premixed Bread Flour Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Global Cake Mix Market
Bakery Products
Pizza Crust Market
Bakery Products
Cookies Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Bake Stable Pastry Fillings Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Bakery Mixes Market