
 Matcha Cookie Market | 2026-2036
Matcha Cookie Market Size, Share, and Industry Trends Forecast 2026-2036
Matcha Cookie Market Insights
The EU Green Deal is pivoting European food manufacturers toward lower-carbon ingredient sourcing and cleaner processing labels. Meiji leverages its integrated tea supply chain in Shizuoka Prefecture to control matcha quality from leaf to finished cookie. Nestle competes through global distribution density, placing matcha cookie variants in mainstream retail channels across multiple continents. Glico specializes in texture-engineered formats that balance matcha bitterness with sweetness profiles calibrated for regional palates.
Matcha cookies combine finely ground shade-grown green tea powder with conventional baking bases to deliver antioxidant content and distinct umami-bitter flavor. The manufacturing process requires low-temperature drying of tencha leaves before stone grinding to preserve catechin integrity and color stability. Organic cookies command premium shelf positioning as health-conscious consumers prioritize pesticide-free tea sourcing and non-GMO flour credentials. Online retail represents the fastest-growing distribution vector, driven by subscription snack boxes and direct-to-consumer tea brand extensions. Individual packs dominate convenience-oriented channels, while boxes sustain gift-market revenue pools in Japan and during seasonal windows in Western markets.
FDA food labeling requirements and EFSA novel food assessments shape formulation standards for matcha-infused products entering U.S. and European markets. Japan's Ministry of Agriculture, Forestry and Fisheries (MAFF) maintains geographical indication protections for Uji and Nishio matcha that influence premium sourcing claims and export pricing structures. Stakeholders must monitor how evolving organic certification thresholds and sugar-reduction mandates in major import markets reshape product development priorities and supplier qualification criteria.
Market Dynamics
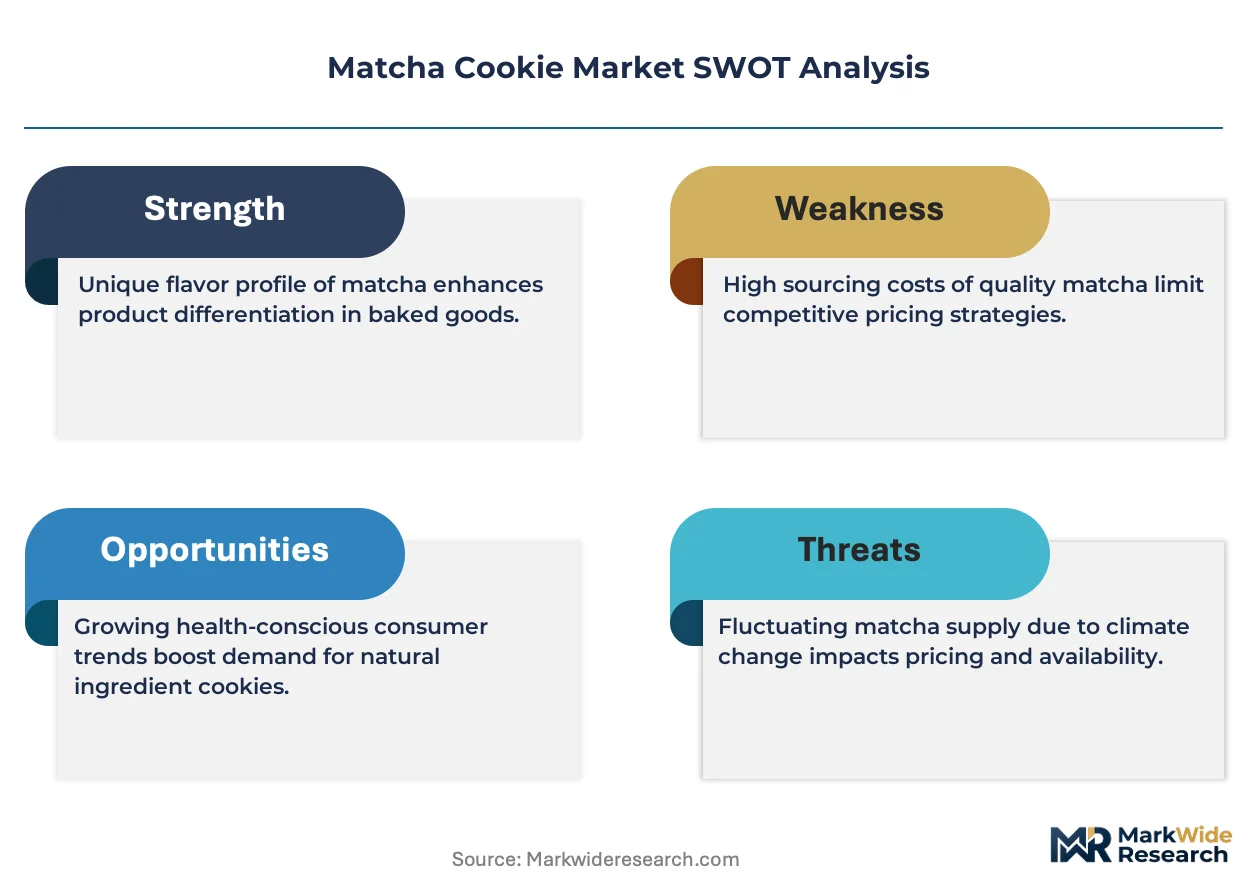
Clean-label mandates from FDA and EFSA are compressing formulation flexibility while organic matcha supply concentrates in Shizuoka and Nishio prefectures, forcing manufacturers to qualify limited certified suppliers or absorb premium input costs.
Growth Catalysts
- Functional beverage crossover:Wellness-oriented café chains in Los Angeles and New York are extending matcha lattes into baked goods, creating pull-through demand for antioxidant-positioned cookies.
- EU Green Deal procurement standards:Lower-carbon ingredient sourcing requirements are favoring matcha over cocoa in European private-label development, rewarding suppliers with verified supply chain transparency.
- Stone-grinding automation:Precision temperature-controlled grinding equipment is preserving catechin integrity at commercial scale, reducing batch-to-batch color variation that previously limited retail distribution.
Market Restraints
- Shade-grown tea acreage constraints:Tencha cultivation requires 20-30 days of shading before harvest, capping raw material expansion regardless of downstream demand acceleration.
- MAFF geographical indication enforcement:Uji and Nishio origin claims face strict documentation requirements, blocking non-authentic matcha from premium positioning and compressing margin pools for generic alternatives.
- Bitterness calibration complexity:Matcha's inherent umami-bitter profile demands regional reformulation, fragmenting production runs and elevating R&D overhead for multi-market portfolios.
Strategic Opportunities
- Subscription snack box penetration:Direct-to-consumer tea brand extensions are bypassing traditional retail slotting fees, capturing lifetime value through recurring revenue models.
- Reduced-sugar formulation white space:Japan's Ministry of Health, Labour and Welfare sugar-reduction guidelines are creating demand for monk fruit and allulose-sweetened variants that maintain clean-label positioning.
- Individual pack convenience channels:Single-serve formats are displacing bulk boxes in grab-and-go retail, unlocking vending machine and transit hub distribution previously inaccessible to bakery categories.
Industry Challenges
- Organic certification timeline compression:USDA and JAS organic audits require 3-year transition periods for new tea gardens, constraining supplier diversification efforts amid demand acceleration.
- Color stability expertise scarcity:Low-temperature drying protocol optimization demands specialized food engineering talent that concentrates in legacy Japanese equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Matcha Cookie Market |
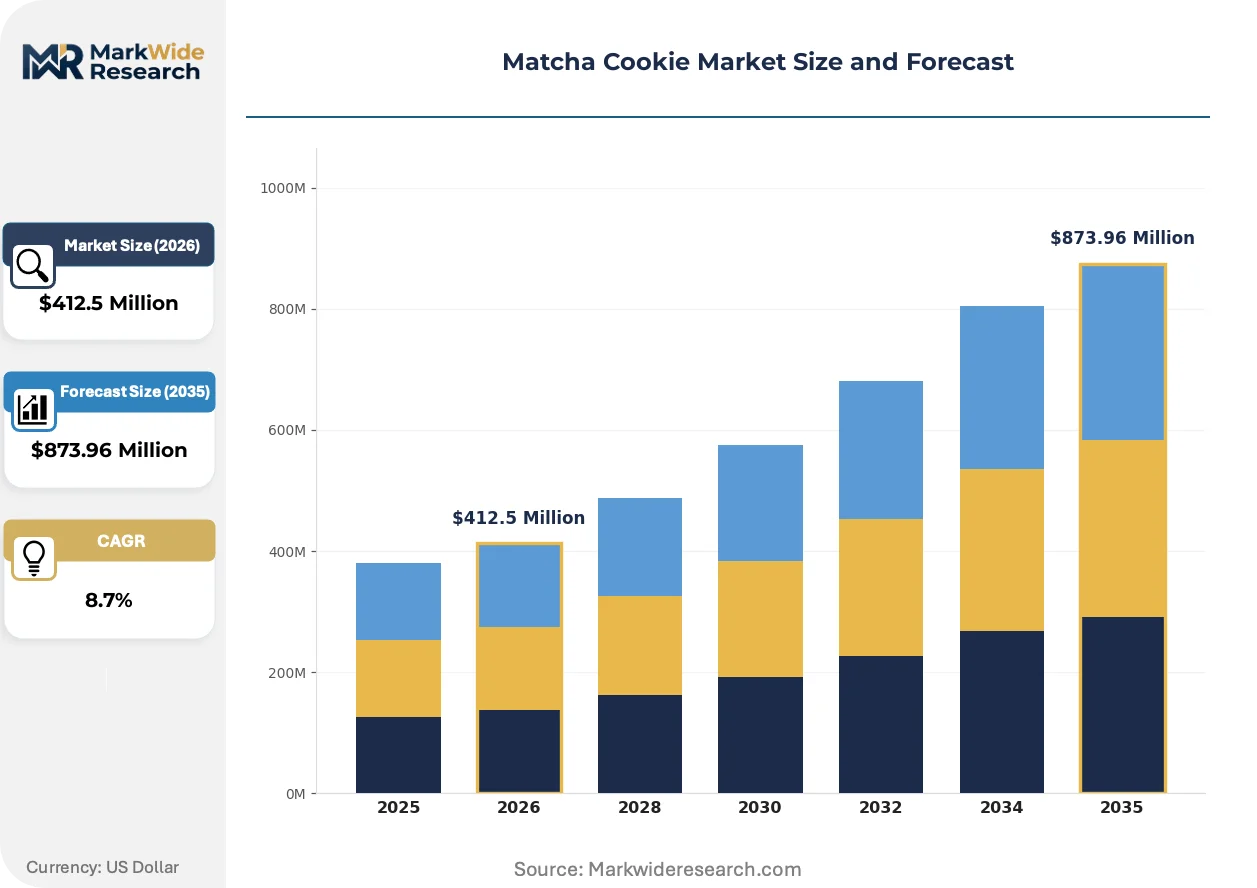
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Cookies, Gluten-Free Cookies, Vegan Cookies, Standard Cookies Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service Customer Type: Health-Conscious Consumers, Young Adults, Families, Food Enthusiasts Package Type: Bags, Boxes, Tubs, Individual Packs |
| Companies Covered | Three Squirrels, Haoxiangni, Meiji, Akai Bohshi, Glico, Mondelez International, BESTORE, ITO EN Ltd., Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Matcha Cookie Market Trends and Innovations
Formulation science and distribution architecture are evolving in parallel as matcha cookies migrate from specialty tea houses into mainstream retail, with regulatory compliance and sensory engineering converging to define competitive differentiation.
Cold-extraction matcha processing is expanding into conventional bakery manufacturing, preserving chlorophyll content that heat-degraded alternatives lose during standard mixing cycles. Premium private-label programs at Whole Foods and Erewhon are adopting this technology to support antioxidant claims on front-of-pack labeling. The structural consequence is a tiered supply base where cold-processed inputs command 40-60% premiums over commodity matcha, compressing margin for mid-tier brands without processing partnerships.
EFSA novel food assessments are reshaping ingredient approval pathways for matcha-infused products entering European markets, with synthetic additive restrictions tightening alongside botanical extract documentation requirements. Manufacturers must now submit full tencha sourcing traceability and heavy metal testing protocols before market entry. Bakery divisions at multinational food conglomerates are responding by pre-qualifying Shizuoka-origin suppliers with existing EU import histories, front-loading compliance investment to accelerate subsequent product line approvals.
Wellness-oriented retail formats are displacing conventional grocery as the primary volume driver for matcha cookie sales, with specialty tea houses and functional beverage cafés capturing trial occasions that convert to pantry stocking. Los Angeles, San Francisco, and Portland represent the densest concentration of this channel shift, where matcha lattes function as gateway purchases that normalize the flavor profile for subsequent baked goods exploration. Legacy cookie manufacturers without tea house distribution partnerships face rising customer acquisition costs as these controlled environments capture premium positioning and repeat purchase loyalty.
Matcha Cookie Market Segmentation
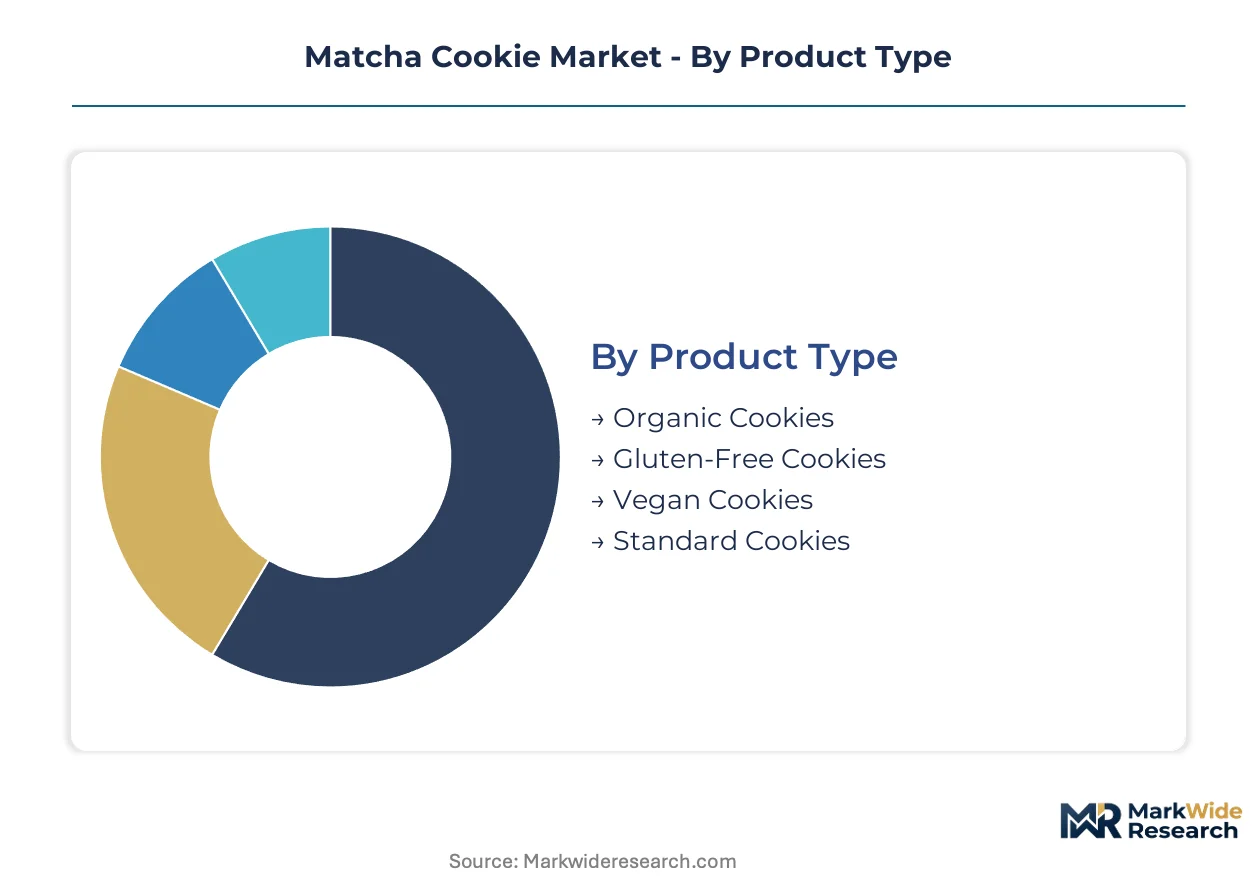
Matcha cookie manufacturers navigate four distinct segmentation axes that determine formulation priorities, channel investments, and margin structures. Product certification tiers separate premium positioning from commodity competition, while distribution channel selection dictates packaging formats and customer acquisition economics.
Product Type:
Buyers in this category differentiate primarily by ingredient transparency thresholds and dietary restriction compliance, not price sensitivity alone.
- Organic Cookies:Formulated with USDA or JAS-certified matcha and non-GMO flour bases, these products command shelf positioning in wellness-oriented retail formats. Demand concentrates in coastal U.S. cities and Japanese premium gift markets, where pesticide-free tencha sourcing validates antioxidant claims on front-of-pack labeling.
- Gluten-Free Cookies:Rice flour and almond meal substitutions replace wheat bases to serve celiac and low-inflammation diet adherents. Health-conscious consumers in Los Angeles and Portland drive trial through specialty tea house partnerships that cross-sell with matcha lattes.
- Vegan Cookies:Plant-based butter alternatives and egg replacers accommodate dairy-free and ethical consumption preferences.
- Standard Cookies:Conventional wheat flour and dairy formulations target price-sensitive trial purchasers in mainstream retail.
Standard cookies lead volumes today; organic cookies are gaining share fastest.
Distribution Channel:
Channel selection in this category tracks customer lifetime value potential against slotting fee tolerance and inventory velocity requirements.
- Online Retail:Subscription snack boxes and direct-to-consumer tea brand extensions bypass traditional retail gatekeepers, capturing recurring revenue through curated discovery models. Young adults in urban Japan and the U.S. drive conversion via Instagram-native brand storytelling and limited-edition drops.
- Supermarkets:Mass-market placement requires compliance with retailer-specific clean-label scorecards and regional sugar-reduction mandates.
- Specialty Stores:Erewhon, Whole Foods, and Japanese depachika food halls provide antioxidant claim validation through controlled assortment curation.
- Food Service:Café chains and hotel breakfast programs absorb individually wrapped formats for grab-and-go integration.
Supermarkets anchor current volume; online retail climbs the fastest as subscription models mature.
Customer Type:
Purchase frequency and basket composition vary sharply across demographic cohorts with divergent flavor familiarity and health claim responsiveness.
- Health-Conscious Consumers:Catechin content and chlorophyll preservation drive purchase decisions, with cold-extraction processing claims validating premium price acceptance. These buyers concentrate in specialty retail channels and demonstrate high subscription retention rates.
- Young Adults:Social media discovery and café environment normalization of matcha flavor profiles convert trial to pantry stocking in Los Angeles, San Francisco, and Tokyo.
- Families:Multi-pack box formats and moderate sweetness calibration accommodate household consumption and lunchbox portability needs.
- Food Enthusiasts:Limited-edition collaborations and single-origin tencha provenance attract collector behavior and gift-market purchasing.
Families generate the highest absolute volumes; young adults show the steepest expansion trajectory as café channel penetration deepens.
Package Type:
Format selection reflects consumption occasion fragmentation between immediate consumption, pantry stocking, and ceremonial gifting.
- Individual Packs:Single-serve sachets unlock vending machine, transit hub, and hotel minibar distribution previously inaccessible to bakery categories. Convenience-oriented channels in Japan and coastal U.S. cities absorb these formats for on-the-go consumption.
- Boxes:Rigid gift packaging sustains premium pricing in Japanese seasonal gift markets and Western holiday windows.
- Bags:Flexible pouches balance resealability with shelf visibility for pantry stocking segments.
- Tubs:Bulk containers serve food service accounts and family-size retail requirements with cost-per-ounce efficiency.
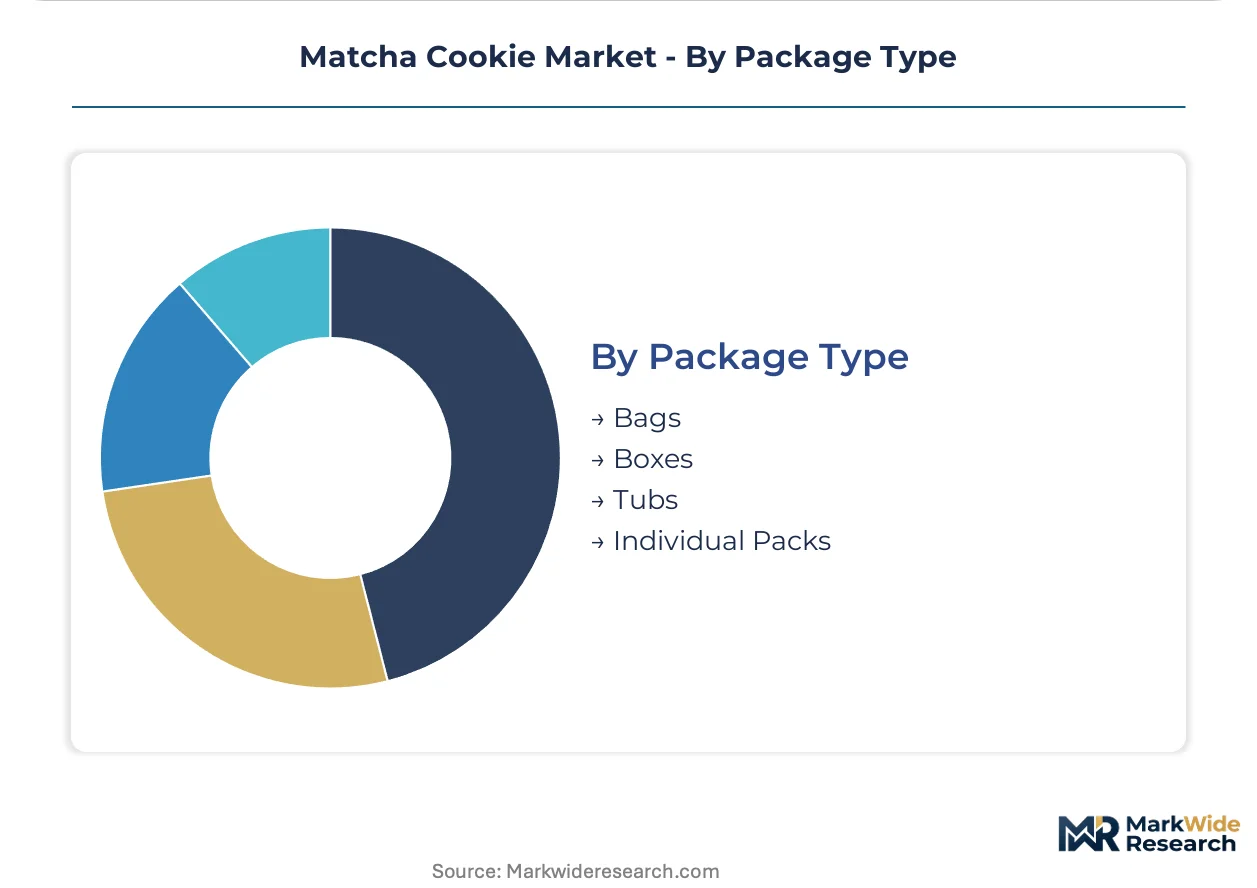
Boxes dominate gift-market revenue; individual packs are expanding most quickly as convenience channels proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Matcha cultivation originated in Tang Dynasty China before Japanese Zen Buddhist monks refined tencha processing in Uji during the 12th century, establishing the geographic and cultural foundations that persist in today's commercial cookie trade.
Japan
Shizuoka and Nishio prefectures supply the majority of certified organic tencha, with stone-grinding cooperatives in Uji maintaining MAFF geographical indication protections. METI's regional cluster policies support integrated tea-to-bakery supply chains that preserve catechin integrity through controlled temperature protocols. Tokyo's depachika food halls and Osaka's specialty confectionery districts anchor premium gift-market distribution for boxed formats.
United States
Wellness-oriented café chains in Los Angeles and New York normalize matcha flavor profiles through latte-to-cookie cross-selling, generating pull-through demand for antioxidant-positioned snacks. FDA food labeling requirements mandate substantiation of health claims, compressing formulation flexibility for imported products. The Pacific Northwest and coastal California concentrate subscription snack box fulfillment infrastructure serving young adult demographics.
China
Domestic matcha processing capacity in Zhejiang and Anhui provinces expands to serve bakery ingredient demand, though shade-grown tencha acreage remains limited versus conventional green tea. SAMR's national food safety standards govern heavy metal thresholds and pesticide residue limits for tea-derived ingredients. Shanghai and Beijing specialty retail corridors absorb premium imported Japanese matcha cookies alongside emerging domestic brands.
Germany
EU Green Deal procurement standards favor lower-carbon ingredient sourcing, positioning matcha as a cocoa alternative in private-label bakery development. EFSA novel food assessments require comprehensive tencha traceability documentation before market authorization. Berlin and Munich wellness retail clusters drive trial adoption through functional beverage café integration.
United Kingdom
London's specialty tea houses and health-focused grab-and-go formats import matcha cookie variants through established Japanese and European supplier relationships. Food Standards Agency guidance aligns with EFSA additive restrictions, shaping clean-label formulation requirements. The Southeast England logistics corridor handles refrigerated distribution for chilled bakery matcha products entering premium supermarket channels.
Matcha Cookie Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the matcha cookie category, with integrated tea processors controlling upstream raw material quality while contract bakery specialists optimize regional flavor calibration. Market structure tilts toward consolidation at the premium tier, where supply chain ownership and geographical indication access create defendable positioning, while mid-market segments fragment across private-label and regional artisan producers. Three archetypes dominate: heritage Japanese confectioners with captive tencha supply, multinational snack conglomerates leveraging global distribution density, and direct-to-consumer wellness brands bypassing traditional retail gatekeepers. Competitive moves concentrate on backward integration into certified organic tea gardens and strategic partnerships with cold-extraction processing equipment vendors.
Among heritage Japanese producers, Meiji and Glico occupy positions defined by integrated supply chain control and texture-engineering specialization respectively. Meiji exemplifies the vertically integrated archetype through Shizuoka Prefecture tencha sourcing, while Glico represents formulation science capabilities calibrated for regional palate adaptation. Nestle sits within the multinational tier, utilizing mainstream retail channel density across multiple continents to place matcha variants in mass-market distribution. These three anchors illustrate how competitive positioning diverges between supply chain ownership, sensory engineering, and route-to-market scale.
| Leading Market Players |
|---|
| Three Squirrels |
| Haoxiangni |
| Meiji |
| Akai Bohshi |
| Glico |
| Mondelez International |
| BESTORE |
| ITO EN Ltd. |
| Nestle |
| Others |
Pricing and Supply Chain Analysis
Captive tencha sourcing through Shizuoka Prefecture cooperatives anchors both supply security and premium pricing power for heritage Japanese producers, while contract manufacturers without upstream control absorb volatile organic certification premiums that compress mid-tier margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cold-extraction organic variants from conventional heat-processed lines and commodity private-label alternatives. Price differentiation hinges on JAS/USDA certification grade and tencha provenance documentation, with Uji-origin claims commanding substantial shelf-position premiums. Cost compression in the standard tier is intensifying because EFSA novel food assessment fees and heavy metal testing protocols elevate compliance overhead. Families purchasing multi-pack boxes demonstrate highest price sensitivity, while health-conscious subscribers in specialty retail show lowest elasticity.
Supply Chain Analysis
Returns and quality-failure flows are minimal in matcha cookie supply chains because perishable bakery categories lack refurbishment economics, though temperature excursions during transit trigger disposal protocols that strain cold-chain partners. Raw material sourcing concentrates in Japan's Shizuoka and Nishio prefectures, with secondary tencha cultivation expanding in China's Zhejiang province. Tencha leaf, stone-grinding capacity, and organic certification infrastructure constitute critical input dependencies. Single-source vulnerability in certified organic shade-grown acreage exposes manufacturers to MAFF geographical indication enforcement actions. Distribution runs through integrated tea-to-bakery cooperatives in Japan and third-party logistics providers serving subscription snack box fulfillment in coastal U.S. markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in cold-extraction processing partnerships and direct-to-consumer subscription models that bypass traditional retail slotting fees.
For Market Incumbents: Anchor defensible positioning through backward integration into certified organic tea gardens with existing JAS audit histories, while securing exclusive equipment partnerships with legacy Japanese stone-grinding manufacturers to lock in color stability expertise. Emerging contract bakery specialists with regional flavor calibration capabilities threaten premium positioning through rapid private-label replication. Channel control through tea house distribution partnerships represents the critical retention lever against customer acquisition cost inflation. For New Entrants and Emerging Players: Reduced-sugar formulation adherents in Japan's metropolitan corridors represent an underserved buyer archetype with limited incumbent coverage, creating white-space entry through monk fruit and allulose-sweetened variants that satisfy Ministry of Health, Labour and Welfare guidelines. Cold-extraction processing partnerships with Shizuoka-origin suppliers enable premium antioxidant claims without captive garden investment. Direct-to-consumer launch through Instagram-native storytelling and limited-edition drops converts café-normalized young adults in Los Angeles and Tokyo. For Investors and Strategic Acquirers: Consolidation pressure builds where organic certification timelines compress supplier diversification options and specialized food engineering talent concentrates in legacy equipment manufacturers. Long-term viability favors vertically integrated heritage producers with captive tencha supply and established EU import histories over asset-light brands dependent on contract manufacturing. Cold-extraction processing capability penetration into conventional bakery manufacturing serves as the primary inflection indicator for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Tencha Gardens | JAS and USDA certification ownership secures supply priority during demand acceleration windows. |
| Cold-Extraction Processing Partnership | Chlorophyll preservation validates antioxidant claims for Erewhon and Whole Foods placement. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass slotting fees and capture lifetime value from young adult cohorts. |
| Reduced-Sugar Formulation Development | Monk fruit and allulose variants align with Japan's sugar-reduction guidelines and expand addressable base. |
| Individual Pack Format Expansion | Single-serve sachets unlock vending machine and transit hub distribution in Japan and coastal U.S. cities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tea house operators, bakery R&D directors, organic certification auditors, and specialty retail category buyers with secondary validation through FDA food labeling guidance documents, EFSA novel food assessment records, MAFF geographical indication registries, and customs trade data for tencha and matcha powder shipments. Bottom-up demand modeling across subscription snack box, supermarket, specialty store, and food service channels triangulated against top-down category value estimates.
Comparable historical reference periods anchored the projection horizon, with growth trajectories derived from segment-level expansion patterns across organic, gluten-free, vegan, and standard product certifications. Segmentation dimensions modeled included product certification tier, distribution channel economics, customer type responsiveness, and package format occasion fragmentation. Catechin content preservation rates and cold-extraction processing adoption curves served as category-specific forecast inputs alongside regulatory compliance timeline assumptions.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in real-time tencha harvest yield data and private-label contract terms introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented base-case assumptions regarding organic certification audit timelines, EFSA assessment processing durations, and shade-grown acreage expansion constraints. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
United States Bread Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Pie Shells Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Bakery Improvers Market
Bakery Products
Vegan Donuts Market
Bakery Products
Frozen Bakery Products Market
Bakery Products
Dough Whitener Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Doughnuts Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Europe Zwieback Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Pancake Mixes Market
Bakery Products
Bread and Baked Food Market