
 Doughnuts Market | 2026-2036
Doughnuts Market Size, Share, and Industry Trends Forecast 2026-2036
Doughnuts Market Analysis
Retail bakery profit pools is tilting toward made-to-order and premium customization stations within convenience and grocery channels. Dunkin' Donuts leverages its drive-thru density and beverage bundling to sustain morning-daypart dominance across the eastern United States. Krispy Kreme anchors its competitive position through hot-light theater production and direct-store-delivery freshness protocols. J.CO Donuts & Coffee differentiates with lower-sugar Asian flavor profiles and café-style seating in Southeast Asian malls.
Doughnuts are chemically leavened or yeast-raised fried dough products, typically containing between 25% and 40% fat content by weight, with moisture levels critical to shelf stability and mouthfeel. The primary commercial purpose centers on impulse-purchase breakfast and snack occasions, with texture and glaze integrity serving as key quality benchmarks. Glazed varieties occupy the largest volume share due to operational simplicity and universal palate acceptance, while filled doughnuts command higher per-unit margins through premium positioning. Bakeries as a channel concentrate artisanal and limited-batch production, whereas supermarkets compete on family-pack value and extended-code distribution.
The FDA oversees standardized identity requirements and allergen labeling for fried bakery products sold in the United States, while the EU EFSA governs acrylamide thresholds and additive authorizations under REACH-aligned food contact frameworks. These regulators shape formulation choices, frying oil specifications, and cross-border export eligibility for multinational producers. Stakeholders must monitor evolving trans-fat restrictions and front-of-pack labeling mandates that will determine permissible ingredient decks and marketing claims across their operating territories.
Market Dynamics
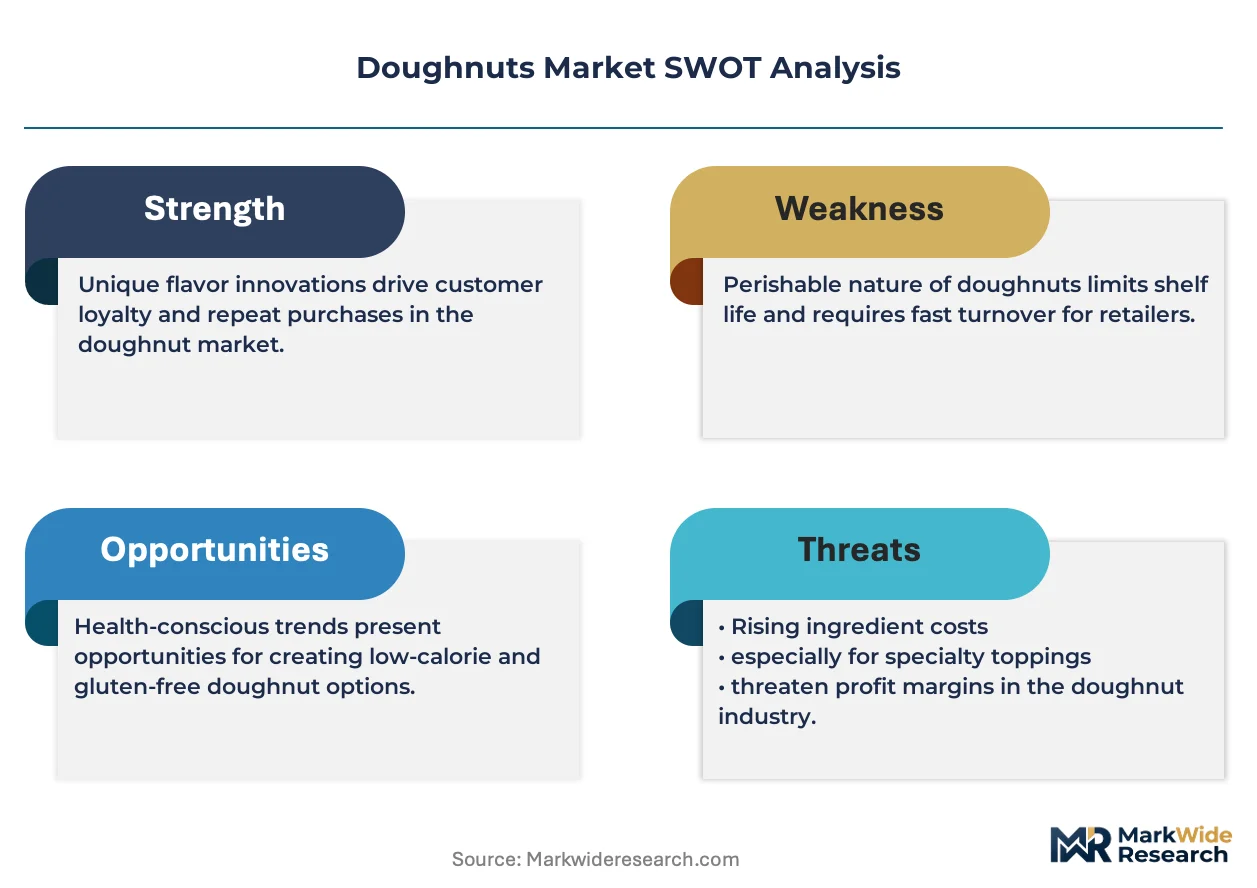
Clean-label mandates from the FDA and EU EFSA are forcing reformulation across the doughnuts sector, eliminating artificial trans fats and synthetic preservatives while reshaping ingredient sourcing and production economics.
Growth Catalysts
- Convenience Store Fresh Programs:North American c-store chains are expanding hot doughnut counters to capture morning traffic and build beverage attachment rates.
- REACH-Aligned Additive Frameworks:EU EFSA authorizations for natural emulsifiers and colorants enable cleaner ingredient decks that command retail shelf placement premiums.
- Yeast-Raised Production Automation:Continuous fryer and glazing line upgrades reduce labor dependency while standardizing texture benchmarks across high-volume outlets.
Market Restraints
- Palm Oil Price Volatility:Sustainable certification premiums and weather-driven supply disruptions from Southeast Asian plantations compress margin predictability.
- Acrylamide Threshold Compliance:EU EFSA maximum levels for fried starch products necessitate capital-intensive fryer temperature controls and monitoring systems.
- Refrigerated Distribution Gaps:Cold-chain infrastructure deficits in tier-two Indian and Indonesian cities limit filled-doughnut freshness windows and geographic expansion.
Strategic Opportunities
- India Mall-Based Café Formats:Underpenetrated premium doughnut seating in tier-one Indian shopping centers offers white-space positioning akin to Southeast Asian J.CO models.
- US Front-of-Pack Labeling Tailwinds:FDA-added sugar disclosure mandates create first-mover advantage for reduced-sugar yeast-raised lines in health-conscious coastal markets.
- Direct-Store-Delivery Digital Integration:IoT-enabled freshness tracking and dynamic routing algorithms compress delivery windows for hot-light theater concepts.
Industry Challenges
- Artisan Fryer Technician Scarcity:Specialized skills for yeast-raised dough management and glaze consistency remain concentrated among aging workforce cohorts in traditional bakery channels.
- Legacy Equipment Retrofit Costs:Acrylamide-reduction fryer modifications and oil filtration system upgrades demand substantial capex from mid-scale independent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Doughnuts Market |
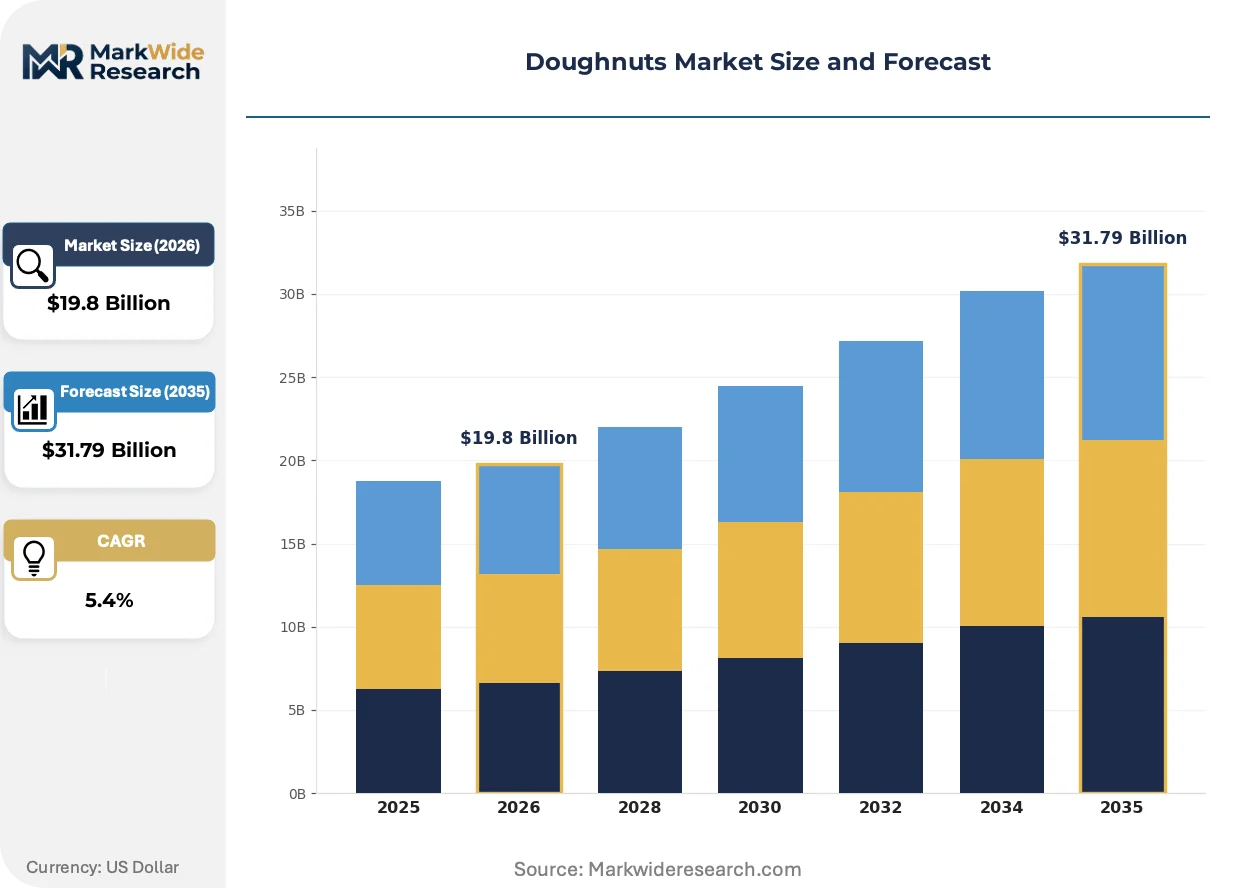
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $31.79 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed, Chocolate, Filled, Old-Fashioned Sales Channel: Online, Supermarkets, Convenience Stores, Bakeries Customer Type: Individuals, Corporations, Events, Cafés Flavor Profile: Sweet, Savory, Fruity, Spicy |
| Companies Covered | Dunkin' Donuts, Krispy Kreme, Grupo Bimbo, Tim Hortons, Shipley Do-Nuts, JAB Holding Company, Daylight Donut Flour, Winchell's Donut House, J.CO Donuts & Coffee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Doughnuts Market Emerging Trajectories
Digital ordering infrastructure and automated production systems are compressing traditional bakery economics while regulatory pressure on frying chemistry accelerates equipment and formulation investment cycles.
Closed-loop oil filtration with real-time polar compound monitoring is virtualizing freshness protocols across convenience and grocery channels. High-volume operators in the United States are adopting these systems to extend frying oil life while maintaining FDA-compliant fat quality benchmarks. This technology is virtualizing the traditional distinction between central commissary and store-level production by enabling consistent output with reduced labor oversight.
The EU EFSA acrylamide mitigation regulation is tightening maximum permissible levels in fried cereal products sold across European Union member states. Industrial fryer manufacturers must now certify equipment for precise temperature curve control and rapid oil turnover rates. Yeast-raised doughnut categories face the steepest compliance costs given their extended frying cycles and higher starch surface exposure.
Mobile pre-ordering with curbside pickup is displacing impulse-counter purchases in US suburban and exurban markets. Convenience store chains are reallocating floor space from self-service cases to dedicated pickup staging areas with beverage bundling stations. This shift concentrates order value in morning dayparts while reducing per-transaction dwell time and labor interaction costs.
Doughnuts Market Segmentation
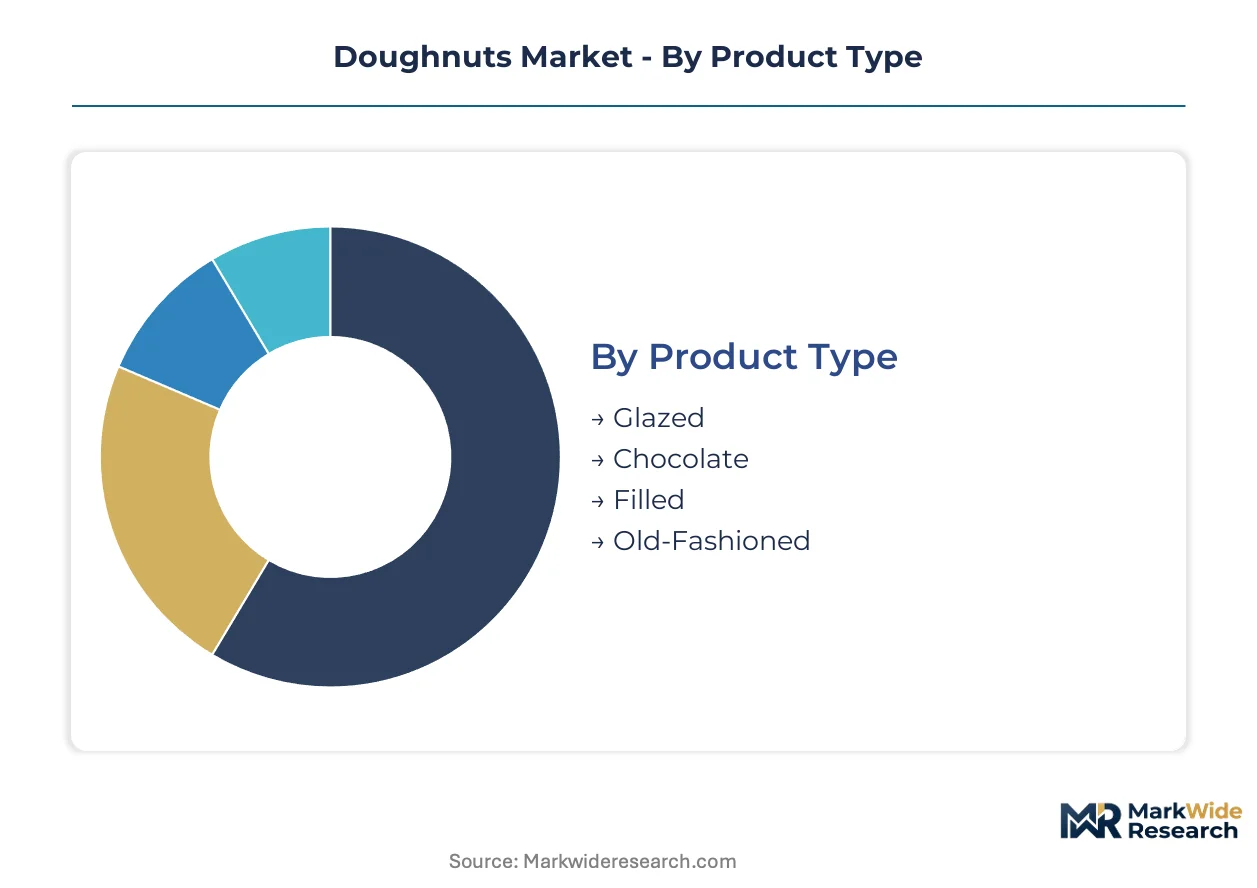
Doughnut segmentation reveals how production economics, distribution reach, and consumption occasions fragment across distinct value propositions. Understanding these divides illuminates where margin pools concentrate and which channel-product combinations justify capital allocation.
Product Type:
After-sales service intensity varies sharply across product types, with yeast-raised glazed varieties demanding fryer technician maintenance and glaze consistency protocols that filled lines do not require.
- Glazed:Yeast-raised dough rings with sugar glaze coating constitute the operational baseline for high-volume chains. Demand concentrates in US drive-thru and convenience channels where speed of service and visual uniformity drive repeat traffic. The category absorbs the bulk of continuous fryer automation investment.
- Filled:Shell-type doughnuts injected with cream, fruit, or custard fillings command premium positioning through portion perception and flavor complexity. European bakeries and Southeast Asian café formats concentrate demand here, with freshness windows limited by refrigerated distribution availability.
- Chocolate:Cocoa-based coatings and frostings require tempering equipment and controlled cooling tunnels that raise capital thresholds for entry.
- Old-Fashioned:Cake-style chemically leavened varieties with cracked surfaces appeal to nostalgic positioning in independent US bakeries and seasonal limited-time offerings.
By volume, Glazed leads. By growth pace, Filled is ahead.
Sales Channel:
Channel cost tiers separate capital-light digital entrants from infrastructure-heavy retail networks with frozen distribution requirements.
- Convenience Stores:Hot counter programs with made-to-order capability capture morning traffic through beverage bundling and reduced dwell time. North American chains expand fresh doughnut installations to defend against quick-service breakfast encroachment.
- Supermarkets:Family-pack value positioning with extended-code distribution depends on par-baked frozen supply chains and in-store bakery labor models. The channel concentrates volume in suburban US and European grocery consolidation markets.
- Bakeries:Artisan production with limited-batch scheduling serves premium customization and local ingredient sourcing preferences.
- Online:Direct-to-consumer shipping with specialized packaging addresses gifting occasions and subscription models in urban coastal US markets.
Convenience Stores dominate transaction frequency. Online expands most quickly.
Customer Type:
Customer maturity levels segment from impulse individual purchasers to contracted corporate accounts with predictable volume scheduling.
- Individuals:Single-serve and small-pack purchases drive the majority of unit volume through immediate consumption occasions. US morning commuter patterns and European snack traditions concentrate demand here.
- Corporations:Office catering and meeting refreshment contracts require early-day delivery reliability and dietary accommodation labeling that favors established direct-store-delivery networks.
- Events:Wedding, conference, and celebration orders favor premium customization and visual presentation over per-unit cost efficiency.
- Cafés:Seating-venue attachment rates in Southeast Asian malls and emerging Indian tier-one shopping centers create white-space positioning for experiential consumption formats.
Individuals generate the highest absolute volume. Cafés show the steepest expansion trajectory.
Flavor Profile:
Supply concentration for natural flavor extracts and regional palate adaptation shapes geographic deployment decisions.
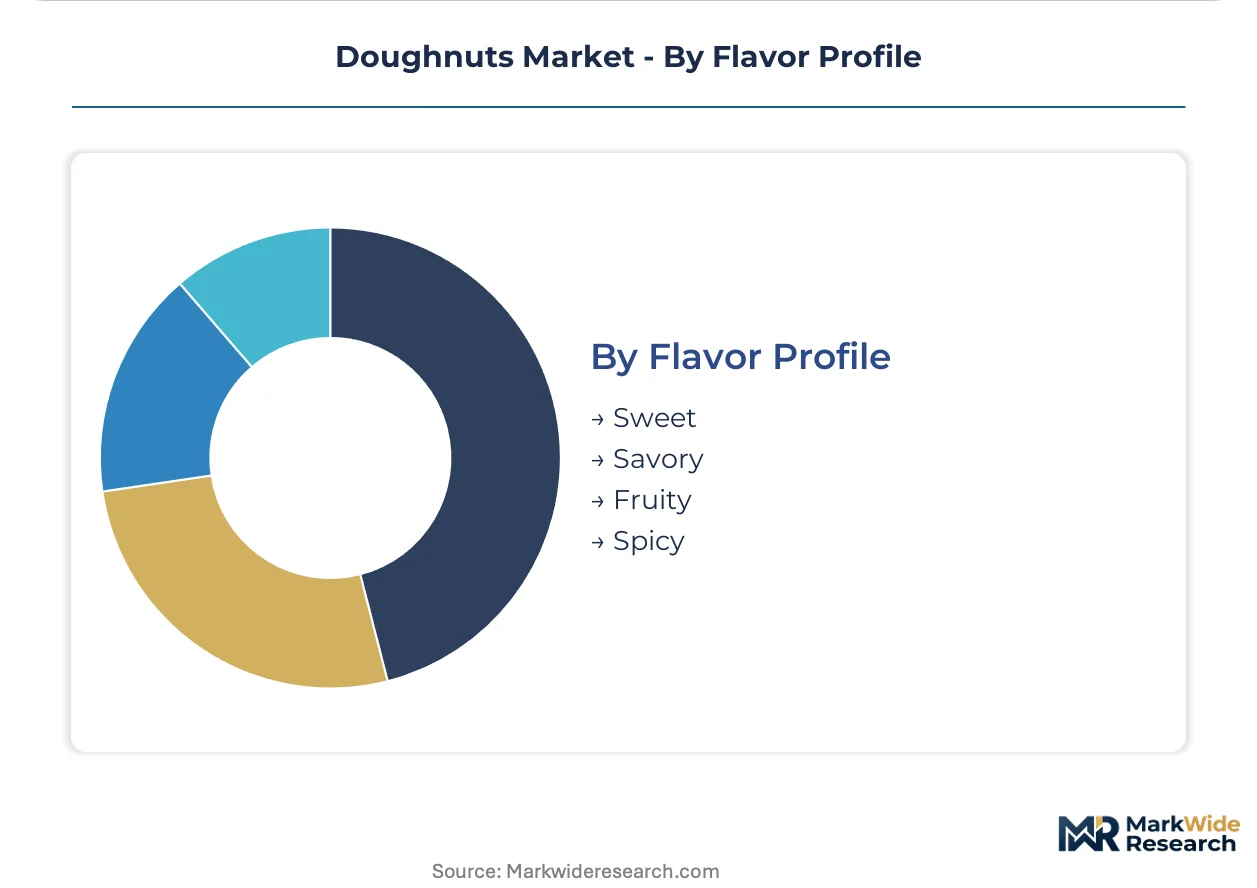
- Sweet:Vanilla, caramel, and traditional sugar-based profiles dominate US and European mass-market acceptance with formulation stability advantages.
- Fruity:Berry, citrus, and tropical infusions command seasonal rotation strategies and limited-time offering velocity in Asian markets.
- Savory:Cheese, herb, and umami-forward profiles penetrate snacking occasions beyond breakfast dayparts in Middle Eastern and Mediterranean markets.
- Spicy:Cinnamon, chili, and warming spice blends align with winter seasonal programming and emerging fusion experimentation in coastal US cities.
Sweet maintains volume leadership. Savory is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: US consumers favor drive-thru velocity and beverage bundling, while Southeast Asian markets emphasize café seating and lower-sugar flavor profiles, and European demand concentrates on clean-label compliance and acrylamide-conscious production.
United States
Drive-thru density and morning commuter traffic anchor demand, with convenience store chains expanding fresh doughnut counters to defend against quick-service breakfast encroachment. FDA standardized identity requirements and allergen labeling govern formulation and packaging standards. The Southeast and Midwest concentrate franchise expansion, where hot-light theater concepts and direct-store-delivery networks compress freshness windows.
Indonesia
Mall-based café formats with experiential seating drive premium positioning, particularly in Jakarta and Surabaya shopping centers where J.CO-style models have demonstrated traction. The country's national food safety regulator, BPOM, oversees additive authorizations and hygiene certification for imported ingredients. Tier-two cities face refrigerated distribution gaps that limit filled-doughnut geographic expansion.
Germany
EU EFSA acrylamide thresholds and REACH-aligned additive frameworks shape industrial fryer specifications and oil turnover protocols. Bavaria and North Rhine-Westphalia host automated production facilities serving pan-European supermarket distribution. Clean-label mandates accelerate reformulation away from synthetic preservatives, compressing margin structures for mid-scale operators.
India
Tier-one metropolitan shopping centers in Mumbai and Bangalore present white-space positioning for premium café formats, with underpenetrated seating-venue attachment rates relative to Southeast Asian benchmarks. FSSAI labeling and food additive regulations govern import eligibility and domestic production standards. Cold-chain infrastructure deficits in secondary cities constrain filled-product freshness windows.
Japan
Convenience store chains dominate transaction frequency through compact store formats and seasonal limited-time offerings that rotate monthly. METI standards and the Consumer Affairs Agency regulate front-of-pack labeling and health claims. Tokyo-Osaka corridor concentration supports high-frequency delivery logistics for yeast-raised freshness protocols.
Doughnuts Market Vendor Landscape
Capability concentration sits with artisan fryer technicians and glaze consistency specialists; scale advantage sits with automated continuous-fryer networks and direct-store-delivery density. The market structures around three tiers: global chains with beverage-bundling ecosystems, regional café-format specialists, and independent bakeries with limited-batch production. Competitive moves concentrate on hot-counter expansion in convenience channels and digital pre-ordering infrastructure deployment.
Within the global chain tier, Dunkin' Donuts and Krispy Kreme occupy positions defined by drive-thru density and freshness theater respectively. J.CO Donuts & Coffee exemplifies the regional café-format archetype through its Southeast Asian mall-based positioning. Among diversified food conglomerates, Grupo Bimbo S.A.B. de C.V. represents packaged bakery integration into retail grocery channels.
| Leading Market Players |
|---|
| Dunkin' Donuts |
| Krispy Kreme |
| Grupo Bimbo |
| Tim Hortons |
| Shipley Do-Nuts |
| JAB Holding Company |
| Daylight Donut Flour |
| Winchell's Donut House |
| J.CO Donuts & Coffee |
| Others |
Supply Flow & Price Mechanics
Jakarta's palm oil refining cluster anchors global frying fat supply, with capacity utilization swings in Indonesian and Malaysian plantations transmitting directly into margin compression for doughnut manufacturers dependent on tropical oil inputs.
Pricing Analysis
Long-term offtake contracts dominate industrial-scale procurement, locking in six-month to annual pricing windows for high-volume chains while spot markets serve independent bakeries exposed to commodity volatility. Three-tier pricing structure across premium, standard, and economy levels separates artisanal bakeries with customization premiums from convenience store value tiers and supermarket family-pack positioning. Cost compression in the economy tier is intensifying because palm oil certification premiums and sustainable sourcing mandates stack onto base ingredient costs. Corporate catering buyers exhibit lowest price sensitivity due to predictable volume scheduling, whereas individual impulse purchasers at convenience counters drive highest elasticity.
Supply Chain Analysis
Upstream wheat flour and palm oil feedstock concentration in Indonesia, Malaysia, and Argentina shapes input cost predictability for global doughnut production networks. Manufacturing draws from specialized yeast strains, emulsifier formulations, and frying oil stabilizers sourced through chemical supplier networks. Single-source vulnerability concentrates in Southeast Asian palm plantations where weather-driven supply disruptions ripple through frying fat markets. Distribution runs through direct-store-delivery networks for freshness-critical yeast-raised lines and frozen par-baked supply chains for supermarket extended-code distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory mandates from FDA and EU EFSA are accelerating a technological inflection in frying chemistry and ingredient sourcing that rewards first-mover reformulation investments across the doughnuts sector.
For Market Incumbents: Harden defensive positions by embedding IoT-enabled freshness tracking into direct-store-delivery networks to compress delivery windows against emerging digital-native entrants. Deepen upstream control over sustainable palm oil certification pipelines to lock in supply security as EU EFSA acrylamide thresholds tighten fryer specifications and exclude non-compliant suppliers. For New Entrants and Emerging Players: Pursue white-space positioning in tier-one Indian shopping centers where café-format seating attachment rates remain underdeveloped relative to Southeast Asian benchmarks. Target reduced-sugar yeast-raised lines in US coastal markets ahead of FDA-added sugar disclosure mandates, deploying mobile pre-ordering infrastructure to bypass incumbent drive-thru density advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated continuous-fryer equipment manufacturers and natural emulsifier specialists with REACH-aligned certification portfolios. Long-term viability hinges on regulatory compliance scalability rather than brand equity alone, making EU EFSA authorization status the critical signal to watch for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | Eliminates synthetic preservatives to meet FDA and EU EFSA mandates while commanding retail shelf placement premiums. |
| Direct-Store-Delivery Digital Integration | Compresses freshness windows through IoT tracking and dynamic routing algorithms for hot-light theater concepts. |
| Convenience Store Hot Counter Expansion | Captures morning traffic through beverage bundling and made-to-order capability against quick-service breakfast encroachment. |
| India Mall-Based Café Format Entry | Replicates J.CO-style experiential positioning in underpenetrated tier-one metropolitan shopping centers. |
| Acrylamide-Reduction Fryer Retrofit | Installs precise temperature curve controls to comply with EU EFSA maximum levels for fried starch products. |
Methodological Framework
Initial hypotheses were tested against primary input from bakery operations directors, convenience store category managers, frying equipment engineers, and palm oil procurement specialists and refined through secondary validation against FDA standardized identity filings, EU EFSA additive authorization databases, customs trade records for tropical oil imports, and SEC filings from diversified food conglomerates. Bottom-up volume modeling across product type, sales channel, and regional regulatory clusters was triangulated against top-down macroeconomic demand indicators.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning yeast-raised versus chemically leavened production methods, convenience store versus supermarket versus bakery channel economics, and clean-label compliance tiers. CAGRs were derived from installed base growth rates for automated fryer equipment and per-capita consumption elasticity models, incorporating acrylamide mitigation technology adoption curves and palm oil price volatility scenarios as industry-specific forecast inputs.
Sensitivities concentrate around EU EFSA acrylamide threshold revisions, palm oil supply disruptions from Southeast Asian weather events, and FDA front-of-pack labeling mandate timing. Forecasts reflect documented assumptions regarding regulatory implementation schedules and commodity price normalization. Cross-checking against Nielsen retail audit data and IEA agricultural commodity benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Global Bakery Product Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Pizza Crust Market
Bakery Products
Bread and Baked Food Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Bake Stable Pastry Fillings Market
Bakery Products
South America Bakery Products Market
Bakery Products
Wedding Cakes Market
Bakery Products
Pastry Premixes Market
Bakery Products
Waffle Market
Bakery Products
Cake Concentrate Market
Bakery Products
Fortified Bakery Market
Bakery Products
No-Fat Cake Market
Bakery Products
South America Ice Cream Market
Bakery Products
Low Calorie Cake Market