
 Batter and Breader Premixes Market | 2026-2036
Batter and Breader Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Batter and Breader Premixes Market Analysis
Shortages of certified food technologists with extrusion and emulsion expertise is reorganizing how premix suppliers staff their innovation labs. Kerry Group PLC leverages its global ingredient science network to sustain formulation leadership across European and North American accounts. House-Autry Mills anchors its position through deep regional distribution control in the southeastern United States. Solina Group specializes in customized coating systems for protein processors seeking differentiated texture profiles.
Batter and breader premixes are engineered dry blends containing wheat flour, starches, leavening agents, and functional hydrocolloids, designed to adhere to protein or vegetable substrates before frying or baking; critical parameters include viscosity at hydration, pick-up percentage, and oil absorption rates to ensure consistent yield and shelf stability in commercial operations. The breader segment occupies the largest share of current volume due to its ubiquity in fast-food chicken and frozen fish applications, while gluten-free options represent the fastest-growing category as celiac-safe menus expand across restaurant chains. Fried batter formulations command premium positioning in seafood processing, where adhesion and crisp-hold properties determine processor selection.
USDA grading standards for poultry and seafood directly influence coating specification requirements for suppliers serving American food manufacturers, while FDA food-contact substance notifications govern novel starch modifications entering premix formulations. In Europe, EFSA evaluations of modified starches and the EU Green Deal's processing sustainability targets are redirecting R&D investment toward reduced-oil absorption systems. Stakeholders must monitor how diverging trans-fat regulations between the FDA's updated guidance and emerging WHO recommendations will force reformulation decisions across export-oriented production networks.
Market Dynamics
Clean-label procurement mandates from major restaurant chains are forcing premix suppliers to eliminate synthetic additives and rebuild formulations around recognizable ingredient decks, compressing R&D timelines and raising qualification barriers for new market entrants.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon-based refrigeration systems is accelerating equipment replacement cycles in frozen breaded product facilities, creating retrofit demand for coating lines compatible with lower-temperature processing protocols.
- Quick-service chicken chains:Standardized batter adhesion specifications across franchise networks are consolidating supplier relationships toward premix partners capable of national distribution with batch-to-batch consistency guarantees.
- Extrusion-cooked starches:Modified pre-gelatinized wheat and potato starches with enhanced cold-water dispersibility are reducing hydration time and energy input in high-throughput breading operations.
Market Restraints
- Wheat gluten volatility:Protein content variability in North American hard red winter wheat harvests creates formulation adjustment costs for suppliers maintaining viscosity specifications across crop years.
- Modified starch import dependence:European processors rely on tapioca and waxy maize starch supply concentrated in Southeast Asian processing hubs, exposing margin structures to freight rate fluctuations and port congestion.
- REACH registration thresholds:Novel hydrocolloid introductions face extended toxicological evaluation timelines at ECHA, delaying commercialization of next-generation adhesion systems by 18-36 months versus conventional ingredient pathways.
Strategic Opportunities
- Plant-based protein coating:Meat analog processors require batter systems engineered for fibrous soy and pea protein substrates with distinct hydration absorption profiles versus conventional poultry applications.
- Air-fryer optimized formulations:Reduced-oil absorption breader systems compatible with residential and commercial air-frying equipment address the WHO trans-fat reduction guidelines while maintaining crisp texture.
- Direct-to-processor e-commerce:Specialized ingredient distributors are building digital procurement platforms allowing mid-sized protein processors to configure custom premix specifications without minimum order quantity penalties.
Industry Challenges
- Food technologist scarcity:Formulation chemists with simultaneous expertise in starch gelatinization kinetics and protein interface chemistry command premium compensation, constraining innovation bandwidth at regional premix suppliers.
- Dual certification complexity:Suppliers serving both USDA-inspected poultry facilities and FDA-regulated seafood operations must maintain parallel hazard analysis protocols, doubling documentation and audit preparation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Batter and Breader Premixes Market |
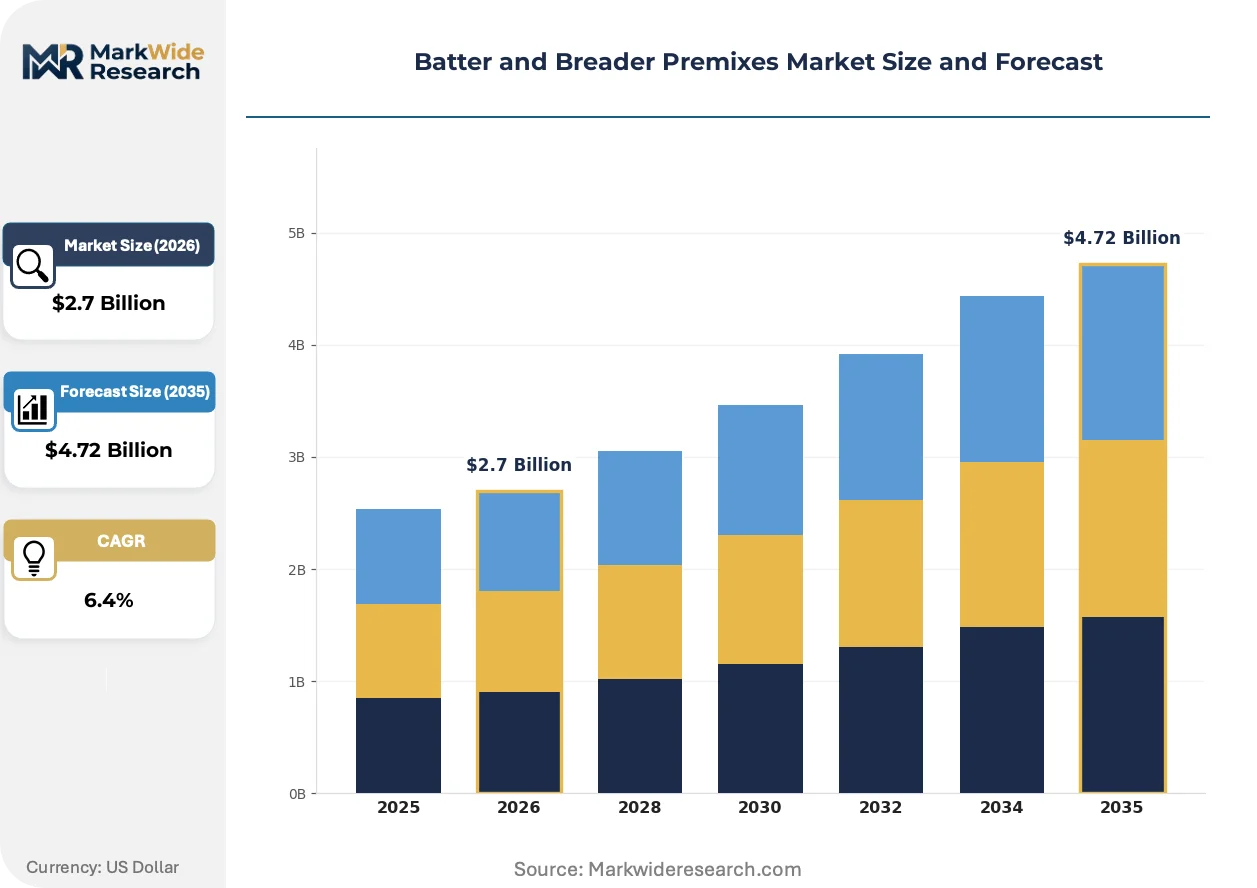
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fried Batter, Breader, Coating Mix, Gluten-Free Options Application: Frozen Foods, Snacks, Fast Food, Seafood End User: Restaurants, Food Manufacturers, Cafes, Catering Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Food Service Distributors |
| Companies Covered | Bowman Ingredients, House-Autry Mills, Kerry Group PLC, Solina Group, Ingredion Incorporated, Newly Weds Foods, McCormick & Company, Archer Daniels Midland, Blendex Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Batter and Breader Premixes Market Emerging Trajectories
Digital formulation tools and alternative protein substrates are converging to reshape how coating systems are designed, tested, and scaled from pilot batches to commercial production runs.
Clean-label leavening systems based on encapsulated sodium bicarbonate and organic acid combinations are fragmenting the traditional chemical leavening segment. Mid-sized processors in Germany and the Netherlands are adopting these systems to meet retailer free-from lists while maintaining expansion control in high-moisture batter applications. The technology is fragmenting supplier hierarchies by enabling smaller ingredient houses to compete on label simplicity against established premix brands with legacy phosphate-dependent portfolios.
REACH compliance protocols for modified food starches are tightening disclosure requirements for acetylated and hydroxypropylated derivatives entering European coating formulations. EFSA evaluations now demand expanded migration studies for starch derivatives used in high-temperature frying applications, extending new product introduction timelines. Frozen seafood processors exporting to EU member states are prioritizing premix suppliers with established regulatory dossiers to avoid border detention risks.
Specification-led procurement is consolidating buyer power as restaurant chains centralize coating decisions at corporate headquarters rather than granting regional autonomy. This shift is displacing fragmented distributor relationships with direct manufacturer contracts spanning multi-year volume commitments. The pattern is most visible in North American quick-service chicken networks, where procurement teams now mandate identical batter performance metrics across franchise locations exceeding five thousand units.
Batter and Breader Premixes Market Segmentation
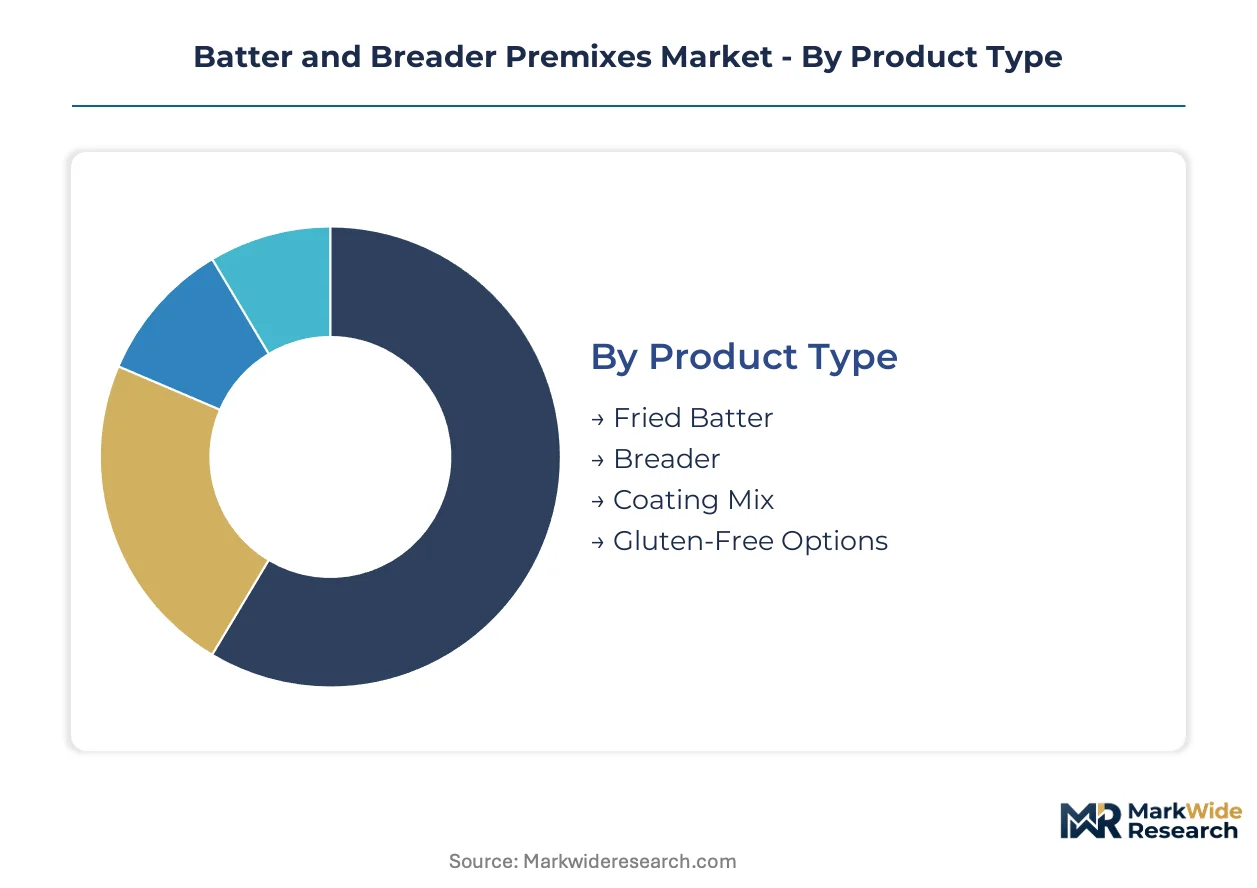
Segmentation in batter and breader premixes reveals how formulation specifications diverge across frozen food factories versus quick-service kitchen operations. Channel requirements dictate viscosity ranges, packaging formats, and minimum order quantities that suppliers must navigate simultaneously.
Product Type:
Food service distributors move breader and coating mix volumes through broadline networks, while specialty stores and online retail concentrate gluten-free and premium fried batter SKUs for smaller operators.
- Breader:Dry particulate blends of wheat flour, cracker meal, and seasoning designed for dredging operations before frying. Quick-service chicken chains in the United States specify adhesion strength and color development under standardized fryer conditions, consolidating supplier relationships toward partners with national distribution infrastructure.
- Fried Batter:Hydrated systems combining flour, leavening, and hydrocolloids for tempura and beer-batter applications. Seafood processors in Germany prioritize cold-water dispersibility and extended crisp-hold properties for export-ready frozen fillet programs.
- Coating Mix:Multi-functional blends suitable for both breading and batter applications with adjustable hydration ratios.
- Gluten-Free Options:Rice flour, tapioca starch, and xanthan gum-based systems certified for celiac-safe menus.
By volume, breader leads. By growth pace, gluten-free options are climbing the fastest.
Application:
Margin structures vary sharply across application segments, with frozen foods commanding formulation consistency at scale while fast food rewards batch-to-batch reproducibility under tight procurement windows.
- Frozen Foods:Industrial-scale premixes engineered for blast-freeze compatibility and extended shelf stability in breaded poultry and fish portions. Mid-sized German processors upgrading coating lines for export-ready schnitzel production drive specification tightening around freeze-thaw resistance.
- Fast Food:High-throughput batter systems optimized for continuous fryer operations with 90-second cook cycles. Standardized adhesion metrics across franchise networks exceeding five thousand units in North America consolidate buyer power at corporate procurement headquarters.
- Seafood:Specialized formulations addressing delicate protein substrates and oil temperature sensitivity.
- Snacks:Seasoned breader applications for mozzarella sticks, onion rings, and vegetable appetizers.
Frozen foods generates the highest absolute tonnage. Fast food exhibits the steepest specification escalation trajectory.
End User:
Customer scale determines service intensity, with food manufacturers requiring technical field support for line integration while cafes and catering services prioritize packaging flexibility over formulation customization.
- Food Manufacturers:Large-scale processors of frozen breaded proteins with dedicated R&D collaboration demands. USDA grading standards for poultry and FDA food-contact substance notifications govern coating specifications, forcing dual certification maintenance at supplier quality departments.
- Restaurants:Independent and chain operators with varying batch size requirements and equipment constraints.
- Catering Services:Event-focused operators requiring portion-controlled packaging and extended hold-time performance.
- Cafes:Limited-menu establishments with small-footprint storage and simplified preparation protocols.
Food manufacturers dominate procurement volume. Restaurants show the most rapid channel expansion for direct-supplier relationships.
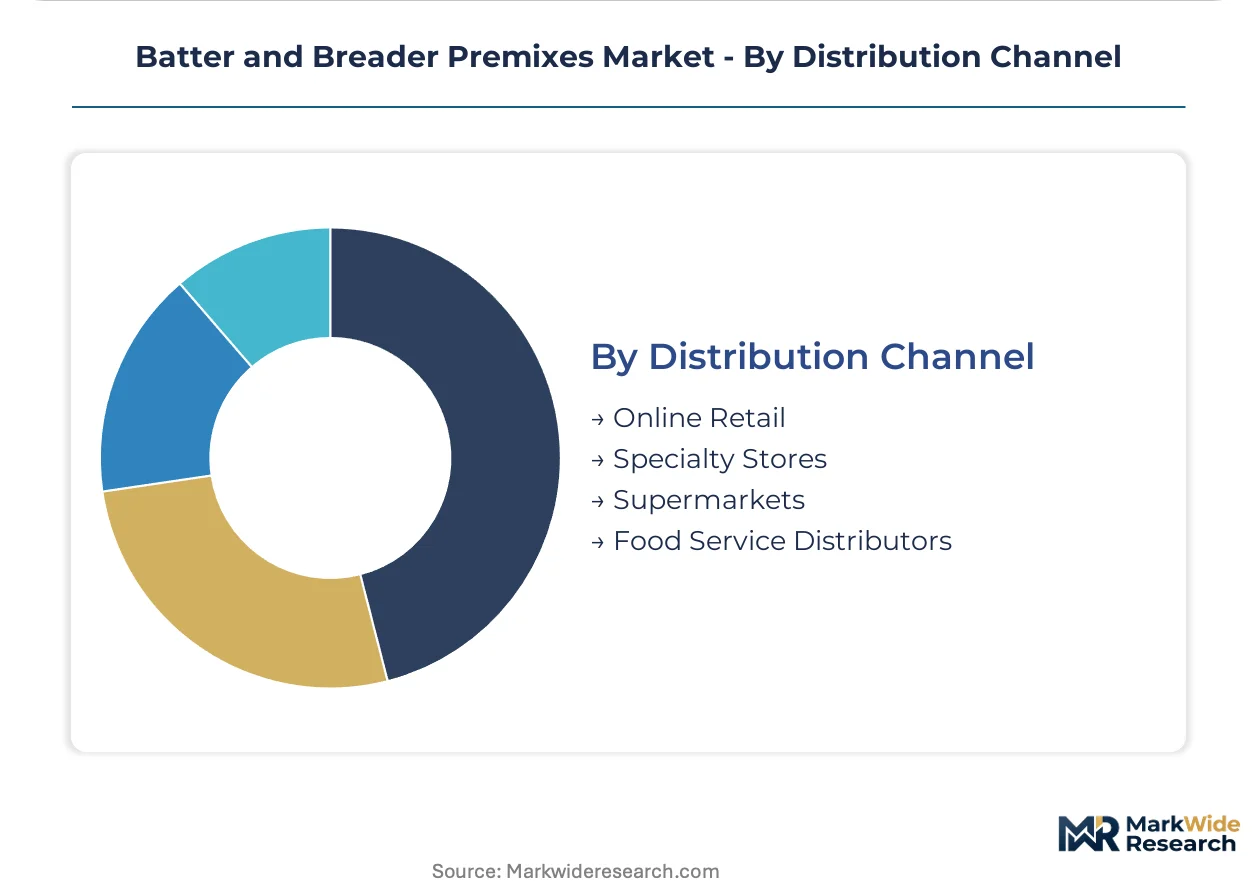
Distribution Channel:
Supply chain configuration determines minimum viable order sizes and technical service accessibility, fragmenting how premix suppliers organize their sales operations.
- Food Service Distributors:Broadline networks carrying multi-category portfolios with consolidated delivery schedules. These intermediaries absorb inventory risk for regional restaurant chains while compressing margins for premix manufacturers through annual rebate negotiations.
- Specialty Stores:Independent ingredient retailers serving small processors and ethnic food manufacturers with niche formulation requirements.
- Supermarkets:Retail channels for consumer-packaged coating mixes with brand recognition demands.
- Online Retail:Emerging digital procurement platforms enabling mid-sized processors to configure custom specifications without traditional minimum order quantity penalties.
Food service distributors handle the greatest throughput. Online retail is gaining share fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors demand through USDA grading standards and FDA food-contact substance notifications that govern coating specifications for poultry and seafood processors. Germany, China, Japan, and Brazil concentrate distinct industrial clusters responding to localized regulatory and procurement pressures.
United States
Quick-service chicken chains exceeding five thousand franchise units mandate standardized batter adhesion metrics, consolidating procurement at corporate headquarters. FDA oversight of novel starch modifications forces premix suppliers to maintain dual certification protocols for USDA-inspected poultry and FDA-regulated seafood operations. Southeastern distribution networks center on regional milling and coating blend facilities serving broadline food service distributors.
Germany
Mid-sized processors upgrading coating lines for export-ready frozen schnitzel production drive specification tightening around freeze-thaw resistance and lower-temperature processing compatibility. EU F-Gas Regulation phase-down of hydrofluorocarbon-based refrigeration systems accelerates equipment replacement cycles in frozen breaded product facilities. Industrial clusters in Lower Saxony and Bavaria concentrate coating innovation labs responding to EFSA evaluations of modified starches.
China
Domestic quick-service expansion and frozen seafood export programs generate formulation demand for high-throughput breading operations with reduced hydration time requirements. SAMR oversight of food-contact substances and GB standards for wheat flour quality create compliance layering for multinational premix suppliers. Yangtze River Delta processing hubs integrate modified starch supply chains with regional protein processing corridors.
Japan
Tempura and specialized fried batter applications in seafood processing prioritize cold-water dispersibility and extended crisp-hold properties for premium export fillet programs. METI processing sustainability targets and JIS standards for food machinery redirect R&D investment toward reduced-oil absorption systems. Kansai and Chubu industrial zones concentrate coating formulation expertise for delicate protein substrates.
Brazil
Poultry processing scale and expanding quick-service penetration drive breader volume demand with batch-to-batch consistency requirements under tight procurement windows. ANVISA registration protocols for modified food starches create qualification barriers for imported premix formulations. São Paulo state anchors industrial coating capacity serving Mercosur export networks and domestic fast-food chain supply.
Batter and Breader Premixes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the batter and breader premixes market. The upper tier commands multi-regional distribution infrastructure and direct relationships with corporate procurement teams at major restaurant chains. Specialist competitors occupy niche positions through customized coating systems, regional distribution control, or proprietary starch modification capabilities. Competitive moves concentrate on strategic partnerships for clean-label ingredient sourcing and portfolio diversification into gluten-free and plant-based protein coating formulations.
Within the integrated multinational tier, Kerry Group PLC and Archer Daniels Midland exemplify scale-driven positioning through global ingredient science networks and starch processing infrastructure. Among regional specialists, House-Autry Mills anchors southeastern United States distribution control, while Solina Group occupies the customized coating systems segment for protein processors seeking differentiated texture profiles. Bowman Ingredients and Newly Weds Foods represent mid-scale fabricators with technical field service capabilities for line integration support.
| Leading Market Players |
|---|
| Bowman Ingredients |
| House-Autry Mills |
| Kerry Group PLC |
| Solina Group |
| Ingredion Incorporated |
| Newly Weds Foods |
| McCormick & Company |
| Archer Daniels Midland |
| Blendex Company |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day starch inventory positions at European coating blenders concentrate pricing power with modified starch distributors holding Southeast Asian supply contracts, while North American millers leverage crop-year wheat futures to compress regional premix margins.
Pricing Analysis
Price spreads between European and North American breader premixes reflect freight-adjusted modified starch premiums and wheat protein content differentials. Three-tier pricing structure across premium clean-label, standard phosphate-based, and economy commodity-grade formulations segments buyer tiers. Cost compression in economy-grade wheat flour blends is intensifying because of hard red winter harvest variability. Quick-service chicken chains with national distribution mandates exhibit lowest price sensitivity, while independent seafood processors show highest elasticity to formulation cost shifts.
Supply Chain Analysis
Ninety-day tapioca starch inventory cycles at Dutch coating facilities expose margin structures to port congestion at Rotterdam and Antwerp. Supply concentrates in Thailand, Vietnam, and Germany for modified starch processing and wheat milling respectively. Raw material flows draw from Southeast Asian cassava cultivation, North American hard red winter wheat belts, and European potato starch extraction. Single-source vulnerability in pre-gelatinized waxy maize supply creates qualification bottlenecks for clean-label reformulations. Distribution runs through broadline food service distributors with annual rebate-negotiated contracts consolidating downstream buyer power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as clean-label procurement mandates from restaurant chains displace legacy phosphate-dependent portfolios, creating niches for ingredient houses with rapid regulatory dossier capabilities.
For Market Incumbents: Fortify formulation leadership by acquiring Southeast Asian starch modification assets to secure tapioca supply contracts against freight volatility. Deepen technical field service teams in Germany and the southeastern United States to defend against emerging clean-label specialists capturing mid-sized processor accounts. For New Entrants and Emerging Players: Anchor in gluten-free coating systems for celiac-safe quick-service menus, the most penetrable segment given certification gaps at established suppliers. Pursue direct-to-processor e-commerce platforms with configurable premix specifications and no minimum order penalties as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification-led procurement at restaurant chain headquarters is displacing fragmented distributor relationships toward direct manufacturer contracts. Target regional coating blenders with established EFSA regulatory dossiers and freeze-thaw resistant formulation libraries. Watch REACH registration timelines for novel hydrocolloids as the inflection signal indicating next-generation adhesion system commercialization windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Modified Starch Processing | Captive tapioca supply from Thai processing hubs insulates margin structures from freight rate volatility. |
| Clean-Label Certification Investment | EFSA-compliant encapsulated leavening systems unlock procurement contracts with EU quick-service chains. |
| Direct-to-Processor E-Commerce Platform Launch | Digital configuration tools bypass broadline distributor rebates and capture mid-sized seafood processor volume. |
| Technical Field Service Expansion | On-site line integration support in Lower Saxony industrial clusters defends against Solina Group customization offerings. |
| Plant-Based Protein Coating R&D Partnership | Fibrous soy and pea protein substrate expertise addresses meat analog processor hydration absorption requirements. |
Methodological Framework
A standing panel of coating line engineers at mid-sized German processors, procurement directors at North American quick-service chains, technical R&D directors at starch modification facilities, and regulatory affairs leads navigating EFSA evaluations provided ongoing calibration across the study period. Primary interview data combined with secondary validation from USDA grading standards documentation, FDA food-contact substance notification databases, EU F-Gas Regulation implementation reports, and REACH registration timelines at ECHA. Bottom-up volume estimates from processor coating line capacity and top-down value triangulation from broadline distributor rebate structures converged on segment-level outputs.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product type, application, end-user scale, and distribution channel complexity. CAGRs derived from processor capacity expansion announcements, restaurant chain unit growth trajectories, and equipment replacement cycles under EU refrigeration phase-down mandates. Industry-specific inputs incorporated wheat protein content variability bands and modified starch migration study timelines.
Material uncertainties — trans-fat regulation divergence between FDA and WHO guidance, wheat harvest protein content swings, and EFSA evaluation delays for acetylated starch derivatives — sit outside the modeled envelope. Forecasts reflect assumptions about clean-label procurement mandate adoption rates and REACH compliance cost pass-through structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Dough Conveyor Market
Bakery Products
Europe Zwieback Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Bakery Mixes Market
Bakery Products
Flatbread Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Dough Whitener Market
Bakery Products
Yeastless Dough Market
Bakery Products
Bakery Cases Market
Bakery Products
Frozen Bakery Market
Bakery Products
Teaseed Cake Market
Bakery Products
Cake Concentrate Market
Bakery Products
Pie Shells Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Latin America Frozen Bakery Market
Bakery Products
Vegan Certified Cake Mixes Market