
 Bakery Emulsions Market | 2026-2036
Bakery Emulsions Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Emulsions Market Outlook
ISO 22000 certification is rotating as the decisive gating standard for supplier qualification among industrial bakeries and co-manufacturers. Palsgaard A/S leverages its integrated emulsifier-blending facilities across Denmark and Singapore to sustain consistent batch quality for multinational accounts. Corbion N.V. anchors its position through microbial fermentation-derived solutions that reduce dependency on soy and palm feedstocks.
Bakery emulsions comprise surface-active agents dispersed in aqueous or lipid carriers, typically containing mono- and diglycerides at concentrations between 10% and 60% by weight, designed to stabilize fat-water interfaces in dough and batter systems. Their primary commercial purpose is to secure uniform crumb structure, extend shelf life through retrogradation control, and enable fat reduction without sensory degradation. Mono- and Diglycerides dominates volume owing to cost efficiency and broad regulatory acceptance, while Natural Emulsifiers captures expanding margin pools as clean-label formulations displace synthetic alternatives in premium bread and pastry segments. The Powder form leads in industrial-scale logistics, though Liquid emulsions gain traction in artisan channels requiring pumpable dosing.
FDA GRAS determinations and EFSA re-evaluations of emulsifier toxicology are reshaping permissible additive portfolios and import documentation burdens for cross-border suppliers. BIS standards in India and China's GB 2760 food additive codes add further compliance layers for manufacturers seeking multi-territory distribution. Stakeholders must monitor evolving maximum-level restrictions and invest in analytical certification capacity before regulatory divergence fragments formulation strategies.
Market Dynamics
Industrial bakeries are consolidating procurement around ISO 22000-certified suppliers as REACH purity specifications tighten across European import channels, forcing reformulation of legacy emulsifier portfolios and reshaping competitive access.
Growth Catalysts
- REACH framework tightening:ECHA purity mandates on food-contact substances are accelerating replacement of partially hydrogenated oil systems with clean-label emulsifiers in German milling clusters.
- Clean-label displacement:Premium bread and pastry segments are demanding natural emulsifiers over synthetic alternatives, expanding margin pools for microbial fermentation-derived solutions.
- Artisan channel pumpability:Liquid emulsion formats are capturing share in small-batch bakeries requiring precise dosing equipment without dry-blend infrastructure.
Market Restraints
- Soy and palm feedstock volatility:Agricultural commodity price swings directly compress margins for lecithin-dependent formulations.
- Regulatory documentation burdens:Cross-border suppliers face escalating EFSA re-evaluation requirements for toxicology dossiers.
- Technical shelf-life ceilings:Natural emulsifiers still underperform synthetic alternatives in retrogradation control for extended-distribution bread.
Strategic Opportunities
- India BIS certification gap:Early movers securing FSSAI-aligned analytical capacity can capture share before maximum-level restrictions harden.
- Microbial fermentation convergence:Biotechnology platforms combining enzymatic processing with precision fermentation unlock feedstock independence.
- Co-manufacturer channel expansion:Industrial bakeries outsourcing production are consolidating vendor lists, creating single-source contract potential.
Industry Challenges
- ISO 22000 certification timelines:Supplier qualification cycles now extend 12-18 months, freezing out mid-tier emulsifier blenders.
- Analytical capacity capex:Multi-territory compliance requires investment in contaminant testing infrastructure for GB 2760, BIS, and EFSA parallel standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Emulsions Market |
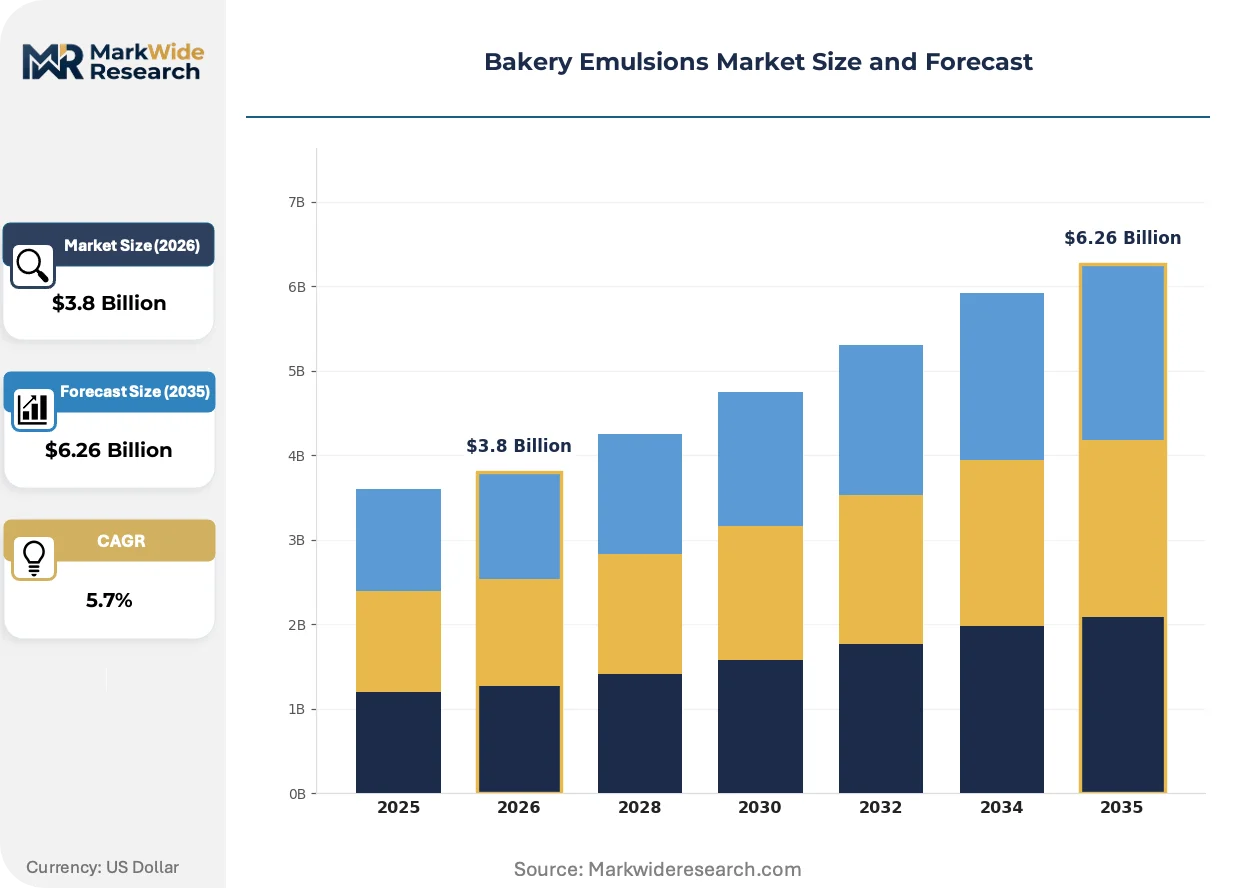
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Emulsifiers, Synthetic Emulsifiers, Lecithin, Mono- and Diglycerides Functionality: Texture Improvement, Shelf Life Extension, Moisture Retention, Flavor Enhancement Form: Liquid, Powder, Granule, Paste Application: Bread, Cakes, Pastries, Cookies |
| Companies Covered | Palsgaard A/S, DSM-Firmenich, Cargill Inc., DuPont de Nemours, BASF SE, Archer Daniels Midland Company, Corbion N.V., Puratos Group, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Emulsions Market Strategic Shifts
Formulation science and regulatory chemistry are converging to redefine emulsifier value propositions, with functionality claims now inseparable from purity documentation and feedstock traceability.
Enzymatic interesterification is fragmenting traditional chemical processing routes for mono- and diglyceride production. European industrial bakeries are adopting enzymatic systems at pilot scale, drawn by lower processing temperatures and reduced trans-fat residuals. The technology is fragmenting capital allocation across integrated facilities versus toll-manufacturing networks.
EFSA re-evaluations of emulsifier toxicology are forcing systematic reformulation of additive portfolios. Maximum permitted levels for select esters are under review, compelling suppliers to rebuild safety dossiers. Cross-border manufacturers serving EU and Asia-Pacific markets face divergent permissible additive lists, complicating unified formulation strategies.
Specification-driven procurement now dominates industrial bakery vendor selection. Large milling clusters in Germany are consolidating supplier panels around certified blenders with captive analytical laboratories. This concentration is visible across Northern European co-manufacturing networks, where single-source contracts now extend to five-year horizons with embedded volume commitments.
Bakery Emulsions Market Segmentation
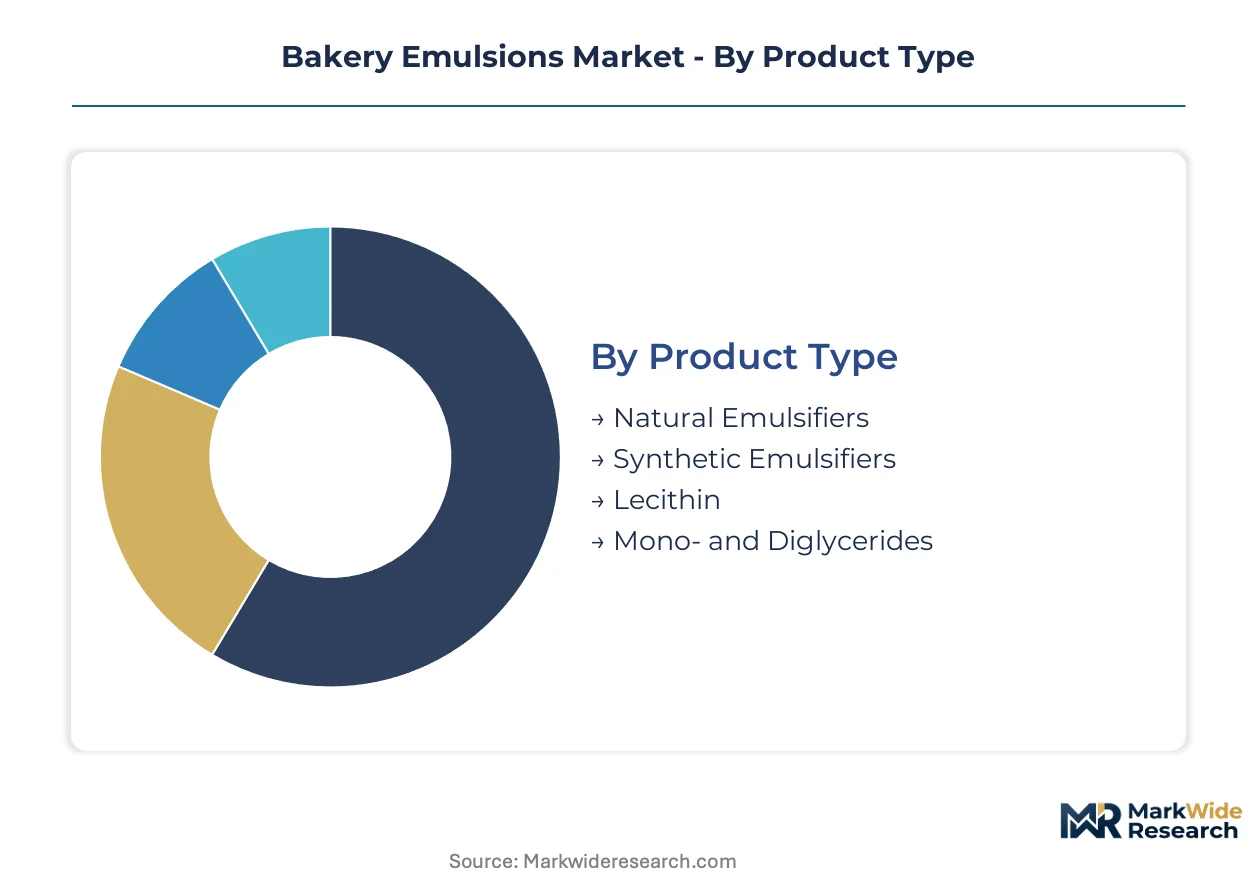
Bakery emulsions fragment across four functional dimensions, each carrying distinct margin profiles and procurement requirements. Specification-driven buyers now weight clean-label credentials and ISO 22000 certification parity alongside traditional performance metrics.
Product Type:
Margin pools concentrate in microbial fermentation-derived systems that decouple pricing from agricultural commodity cycles.
- Mono- and Diglycerides:Surface-active agents produced through glycerolysis of triglycerides, typically comprising 40-60% alpha-monoglyceride content. Industrial bakeries in Germany's milling clusters procure these in bulk volumes for standardized bread production, prioritizing cost efficiency over feedstock provenance.
- Natural Emulsifiers:Fermentation-derived or enzymatically processed alternatives to chemically synthesized systems. Premium bread and pastry segments across Northern Europe are displacing synthetic portfolios, accepting price premiums for clean-label positioning and EFSA-aligned toxicology dossiers.
- Lecithin:Phospholipid mixtures extracted from soy or sunflower feedstocks, standardized by acetone-insoluble matter specifications. Soy price volatility compresses margins for legacy suppliers dependent on commodity agriculture.
- Synthetic Emulsifiers:Chemically esterified systems including DATEM and SSL, facing reformulation pressure as REACH purity specifications tighten and maximum permitted levels come under EFSA review.
The dominant share belongs to Mono- and Diglycerides, while Natural Emulsifiers is closing the gap fastest.
Functionality:
Application requirements determine which functional claims command specification premiums in vendor selection.
- Shelf Life Extension:Retrogradation control through amylose-complexing emulsifiers, critical for extended-distribution bread networks. Synthetic alternatives still outperform natural systems in technical efficacy, creating formulation tension for clean-label targets.
- Texture Improvement:Crumb structure stabilization and gas cell uniformity in high-volume industrial production. Artisan bakeries lacking dry-blend infrastructure prioritize pumpable liquid systems for precise dosing control.
- Moisture Retention:Staling delay through water-binding at starch granule interfaces, valued in cake and pastry segments where eating quality degrades rapidly post-bake.
- Flavor Enhancement:Fat encapsulation and controlled release systems, capturing niche positioning in premium cookie and filled pastry applications.
Shelf Life Extension commands the largest procurement volumes, though Texture Improvement is gaining share fastest in artisan channel conversions.
Form:
Logistics infrastructure and dosing equipment determine format selection across customer tiers.
- Powder:Free-flowing blends with standardized particle size distributions, optimized for pneumatic conveying in industrial-scale milling operations. Northern European co-manufacturers specify powder for five-year contract horizons with embedded volume commitments.
- Liquid:Pumpable emulsions with defined viscosity ranges for metered addition. Small-batch bakeries lacking dry-blend infrastructure are adopting liquid formats for precise dosing without capital equipment investment.
- Granule:Low-dust alternatives to fine powders, addressing occupational exposure concerns in high-throughput facilities.
- Paste:High-concentration systems for specialized applications requiring minimal water activity contribution.
Powder leads industrial procurement, while Liquid is expanding most quickly in artisan and co-manufacturing channels.
Application:
End-use specifications diverge sharply between commoditized volume bread and premium pastry segments.
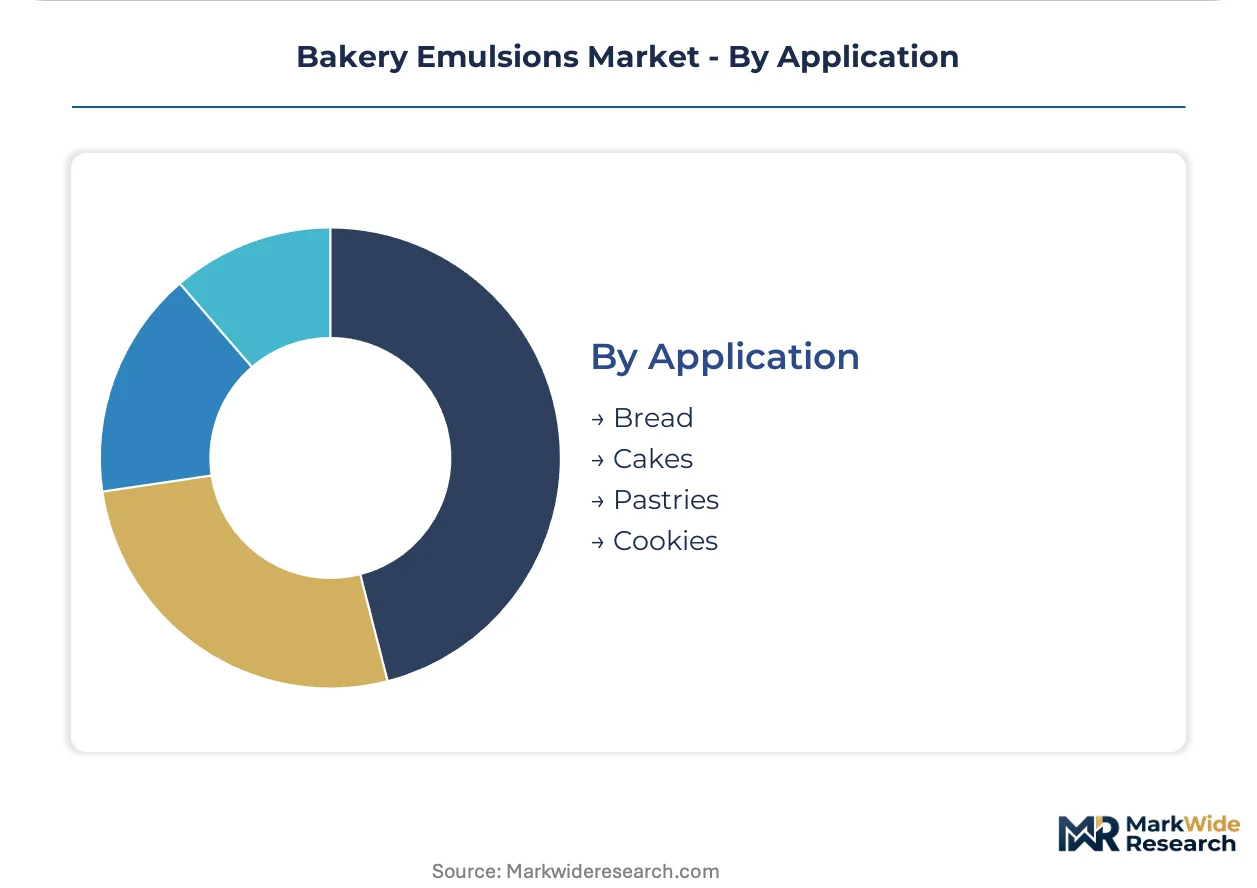
- Bread:High-volume standardized production where emulsifier cost efficiency dominates procurement decisions. German milling clusters drive bulk procurement of lecithin and mono-diglyceride systems with REACH-aligned purity documentation.
- Cakes:Aeration stability and moisture retention requirements create specification premiums for specialized emulsifier blends. Clean-label displacement is accelerating as premium positioning demands microbial fermentation-derived alternatives.
- Pastries:Laminated dough performance depends on fat crystallization control and plasticity maintenance through sheeting operations.
- Cookies:Spread control and surface appearance specifications favor specific emulsifier selections for snap and texture targets.
Bread captures the greatest emulsifier tonnage, though Cakes is climbing the fastest on clean-label premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA purity mandates and REACH framework tightening are redirecting procurement flows toward certified suppliers in Northern European milling clusters. Industrial bakeries in Germany, the Netherlands, and France are consolidating vendor panels around ISO 22000-certified blenders with captive analytical laboratories. Cross-border suppliers face escalating documentation burdens as maximum-level restrictions diverge across jurisdictions.
Germany
Large milling and baking clusters in North Rhine-Westphalia and Bavaria drive bulk procurement of lecithin and mono-diglyceride systems. ECHA REACH specifications on food-contact substances are forcing reformulation of legacy emulsifier portfolios. The Hamburg port complex anchors import channels for soy-derived feedstocks, though microbial fermentation alternatives are gaining specification share.
United States
FDA GRAS determinations on emulsifier toxicology are reshaping permissible additive portfolios for industrial bakeries and co-manufacturers. The Chicago metropolitan area concentrates Midwest milling operations requiring extended-distribution bread formulations. California's artisan bakery sector is adopting pumpable liquid emulsion formats for precise dosing without dry-blend infrastructure.
China
GB 2760 food additive codes are adding compliance layers for manufacturers seeking multi-territory distribution alongside domestic market penetration. Yangtze River Delta baking clusters are scaling emulsion use to replace partially hydrogenated oils in standardized bread production. Shanghai's import inspection regime is tightening purity documentation for cross-border emulsifier shipments.
India
FSSAI-aligned analytical capacity is becoming a decisive gating factor for supplier qualification among industrial bakeries. Maharashtra's milling operations in the Mumbai-Pune corridor are consolidating procurement around certified blenders. BIS standards on food-contact substances are hardening maximum-level restrictions, creating first-mover advantages for early compliance investors.
Netherlands
Rotterdam's port infrastructure supports bulk import and blending operations for lecithin and specialty emulsifier systems. EFSA re-evaluations of emulsifier toxicology are compelling suppliers to rebuild safety dossiers for EU market access. The Randstad region's co-manufacturing networks are extending single-source contracts to five-year horizons with embedded volume commitments.
Bakery Emulsions Market Competitive Environment
Player mix skews toward integrated multinational ingredient suppliers with captive fermentation and blending capabilities. The supplier base concentrates around three strategic archetypes: biotechnology platforms leveraging microbial fermentation, integrated emulsifier blenders with multi-territory certification capacity, and diversified agribusiness operators with upstream oilseed processing. Competitive moves center on analytical certification infrastructure investment and co-manufacturer channel consolidation through long-term supply agreements.
Within the biotechnology platform tier, Corbion N.V. exemplifies feedstock-independent positioning through precision fermentation-derived solutions. Among integrated European blenders, Palsgaard A/S occupies a position representing multi-facility quality consistency for multinational accounts. BASF SE anchors the diversified chemical conglomerate archetype with synthetic emulsifier portfolios facing reformulation pressure from clean-label displacement trends.
| Leading Market Players |
|---|
| Palsgaard A/S |
| DSM-Firmenich |
| Cargill Inc. |
| DuPont de Nemours |
| BASF SE |
| Archer Daniels Midland Company |
| Corbion N.V. |
| Puratos Group |
| Kerry Group |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at integrated emulsifier-blending facilities in Denmark and Singapore shapes both supply concentration and price floors, as multi-territory certification requirements freeze out mid-tier competitors and compress margin bands for non-certified suppliers.
Pricing Analysis
Certification level (ISO 22000/REACH-aligned/FDA-grade) creates the primary spread between supplier tiers, with three-tier pricing structure across premium, standard, and economy levels. Premium microbial fermentation-derived systems command specification premiums from clean-label buyers, while commodity mono-diglyceride volumes face cost compression from soy feedstock volatility. Industrial bakeries in Germany's milling clusters exhibit lowest price sensitivity due to five-year contract horizons with embedded volume commitments, whereas artisan channel buyers without dry-blend infrastructure show highest sensitivity to per-kilogram differentials.
Supply Chain Analysis
Strait of Malacca transit underwrites feedstock flows for palm-derived lecithin reaching European compounding facilities, creating logistics vulnerability for legacy suppliers. Manufacturing concentrates in Denmark, the Netherlands, and Singapore where integrated fermentation and blending capabilities coexist with captive analytical laboratories. Raw material dependencies span soy phospholipids, palm oil fractions, and microbial fermentation substrates, with commodity price volatility representing the dominant structural risk. Distribution runs through Rotterdam and Hamburg port complexes for bulk industrial procurement, while liquid emulsion formats feed artisan channels via specialized chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bakery emulsions sit in early-cycle expansion as clean-label displacement accelerates across premium bread and pastry segments, with microbial fermentation platforms capturing specification share from chemically synthesized alternatives.
For Market Incumbents: Secure multi-territory certification parity before BIS standards in India and China's GB 2760 codes harden maximum-level restrictions, locking out reformulation laggards. Anchor analytical capacity investments in captive laboratories serving Northern European co-manufacturing networks, while extending single-source contract horizons to five-year terms with embedded volume commitments that freeze out emerging biotechnology platforms.
For New Entrants and Emerging Players: Anchor in India's FSSAI-aligned analytical capacity gap before compliance requirements consolidate around early movers, targeting Maharashtra's Mumbai-Pune milling corridor with certified blender positioning. Exploit artisan channel pumpability demand with liquid emulsion formats requiring no dry-blend infrastructure, leveraging enzymatic processing claims to differentiate from legacy chemical glycerolysis routes.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated emulsifier blenders with multi-territory ISO 22000 certification and five-year co-manufacturer contracts, suggesting durable cash flow quality across the investment horizon. Target biotechnology platforms combining precision fermentation with enzymatic processing capabilities that achieve feedstock independence from agricultural commodity cycles. Monitor EFSA re-evaluation timelines for emulsifier toxicology as the critical inflection signal, with maximum-level restriction announcements likely to trigger portfolio consolidation among synthetic-dependent suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Territory Certification Investment | ISO 22000, REACH, and GB 2760 alignment unlocks cross-border procurement from German milling clusters. |
| Microbial Fermentation Scale-Up | Precision fermentation platforms decouple pricing from soy and palm agricultural commodity volatility. |
| Co-Manufacturer Channel Consolidation | Single-source contracts with five-year horizons embed volume commitments and freeze out mid-tier blenders. |
| Enzymatic Processing Adoption | Lower-temperature interesterification reduces trans-fat residuals for EFSA-aligned toxicology dossiers. |
| Analytical Laboratory Captivity | In-house contaminant testing infrastructure satisfies divergent BIS, GB 2760, and EFSA parallel standards. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, spanning industrial bakery procurement directors, co-manufacturer technical managers, emulsifier blending plant operators, and regulatory affairs specialists at multinational ingredient suppliers. Secondary validation drew from EFSA safety dossier re-evaluations, REACH registration databases, China's GB 2760 food additive codes, and customs trade data tracking lecithin and mono-diglyceride flows through Rotterdam and Hamburg. Bottom-up segment sizing triangulated against top-down macro validation across product type, functionality, form, and application dimensions.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented growth rate derivation, with CAGRs computed from base-year scaling factors applied to penetration curves in bread, cakes, pastries, and cookies applications. Modeled dimensions included mono-diglyceride versus natural emulsifier substitution rates, powder-to-liquid format shifts in artisan channels, and REACH-driven reformulation timelines in German milling clusters. Industry-specific inputs encompassed soy and palm feedstock price elasticity coefficients and ISO 22000 certification adoption curves among industrial bakeries.
Underlying assumptions cover sustained clean-label premiumization in Northern European bakery segments, with deviation risk concentrated in EFSA maximum-level restriction severity and agricultural commodity price volatility. Forecasts reflect these documented conditions, with revision triggers tied to regulatory announcement timelines and feedstock market inflections. Practitioners should keep alternative scenarios live as ECHA purity mandates and biotechnology platform cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread and Baked Food Market
Bakery Products
Ice Cream Market
Bakery Products
India Cake Market
Bakery Products
Cake Base Discs Market
Bakery Products
Cake Concentrate Market
Bakery Products
Marzipan Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Flour Mixes Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Wedding Cakes Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Fondant Market
Bakery Products
Dough Whitener Market
Bakery Products
Bread Improver Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Middle East and Africa Bakery Products Market