
 Frozen Bakery Market | 2026-2036
Frozen Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Bakery Market Intelligence
The EU Green Deal is decoupling frozen bakery demand from carbon-intensive production models across European supply chains. Grupo Bimbo leverages its vertically integrated flour-to-retail network to secure cost advantages in frozen bread. General Mills sustains R&D intensity in clean-label frozen dough formulations. Europastry dominates the food service channel through specialized pre-baked croissant and pastry lines.
Frozen bakery encompasses dough-based products preserved at sub-zero temperatures to arrest staling and microbial activity, typically formulated with modified starches and emulsifiers to ensure post-thaw structural integrity for commercial baking or direct consumption. The product type dimension shows frozen pastries capturing premium margin pools while frozen bread anchors volume throughput in retail channels. Within distribution channels, online retail is expanding fastest as direct-to-consumer cold-chain logistics mature, though supermarkets still control the bulk of frozen cake and cookie sales through temperature-controlled aisle networks.
EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant choices and additive portfolios for frozen bakery manufacturers operating in Europe. The US FDA and USDA jointly oversee frozen dough safety standards, with the FDA prescribing pathogen controls for ready-to-bake formulations. Stakeholders must monitor evolving refrigerant phase-down schedules and clean-label certification requirements to preserve market access across jurisdictions.
Market Dynamics
The EU Green Deal is decoupling frozen bakery demand from carbon-intensive production models across European supply chains. Manufacturers now face binding emissions targets that reshape ingredient sourcing, energy procurement, and cold-chain logistics from flour milling through retail distribution.
Growth Catalysts
- Clean-label reformulation:Consumer demand for additive-free frozen dough is pulling reformulation investment toward enzyme-based alternatives and natural emulsifiers that maintain freeze-thaw stability without synthetic preservatives.
- France:Food service operators in Paris and Lyon are expanding pre-baked croissant procurement as labor costs rise and skilled bakers become scarcer in urban centers.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating cold-chain infrastructure upgrades that reduce energy intensity per pallet in frozen bakery distribution.
Market Restraints
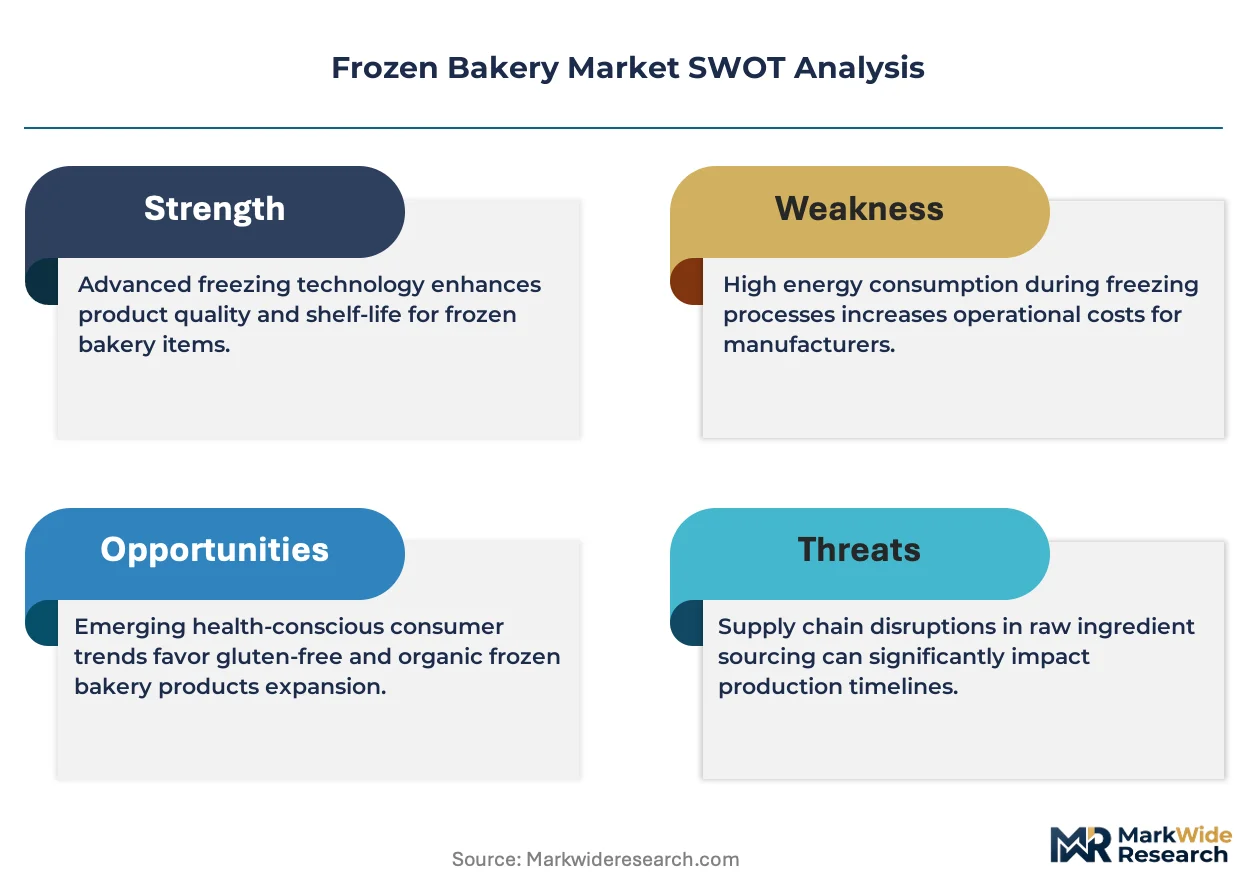
- Wheat price volatility:Input cost swings for high-protein bread flour compress margin predictability for frozen dough manufacturers operating on annual food service contracts.
- Industrial freezer concentration:Third-party cold storage capacity clusters in northern Italy and the Netherlands, creating geographic single-point-of-failure risk for southern European distributors.
- Clean-label technical ceiling:Natural preservatives currently fail to match synthetic alternatives for shelf-life extension in ambient-thaw scenarios, limiting product format expansion.
Strategic Opportunities
- Poland:Modern retail expansion in Warsaw and Krakow outpaces frozen bakery penetration, creating whitespace for premium pastry lines in hypermarket freezer sections.
- Carbon labeling mandates:Early compliance with the EU Green Deal's product-level carbon disclosure requirements positions suppliers for preferential listing with sustainability-focused retail banners.
- Direct-to-consumer subscription:Specialized frozen sourdough and viennoiserie boxes bypass wholesale margins and build recurring revenue through temperature-controlled last-mile networks.
Industry Challenges
- Refrigeration technician scarcity:The specialized workforce for ammonia and CO2 cascade system maintenance is thinning as veteran technicians retire without sufficient apprenticeship pipelines.
- Dual certification timelines:Simultaneous pursuit of organic and carbon-neutral certifications for frozen pastry lines extends time-to-market by 8-14 months versus conventional products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Bakery Market |
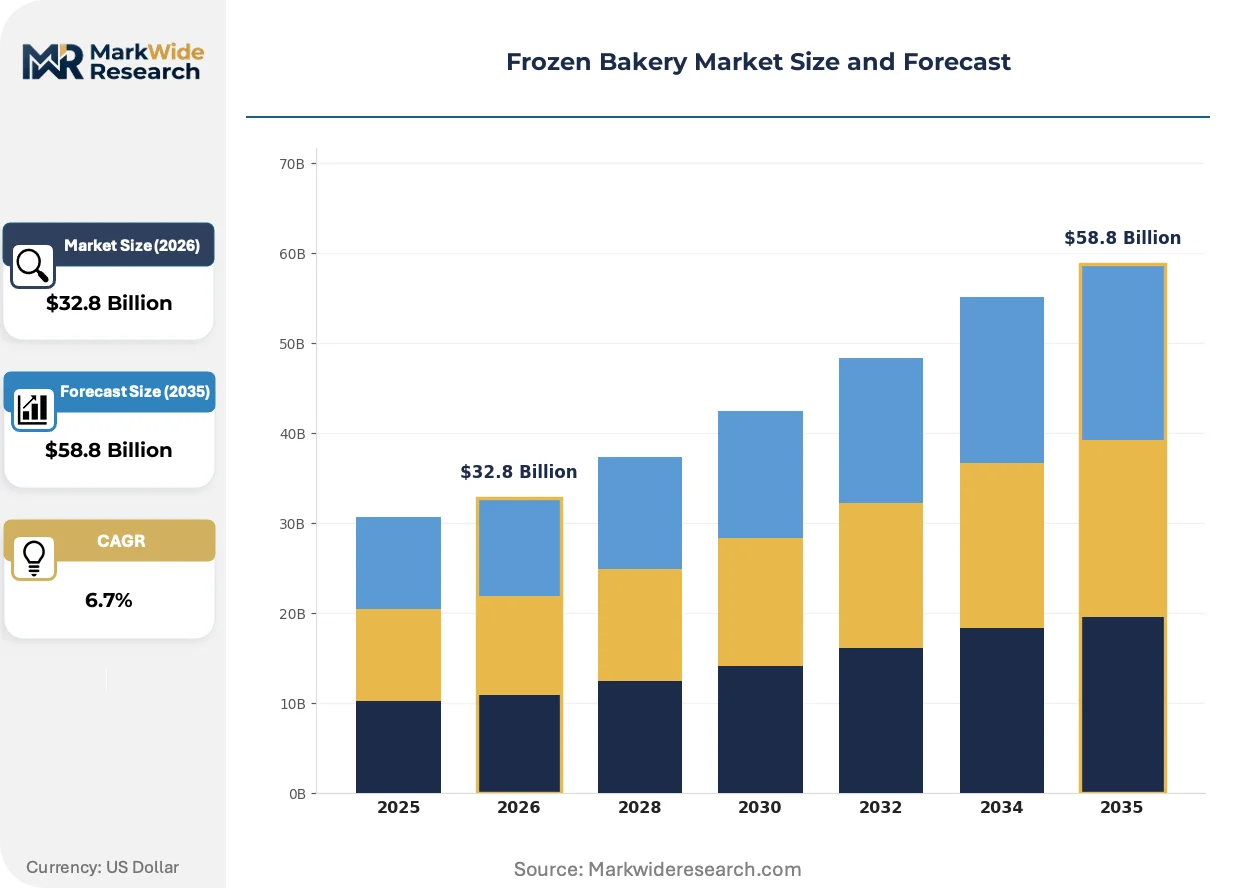
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $58.8 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Bread, Frozen Pastries, Frozen Cakes, Frozen Cookies End Use: Retail Outlets, Food Service, Catering, Cafés Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers Form: Pre-baked, Dough, Ready-to-eat, Heat-and-serve |
| Companies Covered | Grupo Bimbo, General Mills, Rich Products Corporation, Aryzta AG, Europastry, Lantmännen Unibake, Vandemoortele, Conagra Brands, Flowers Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Bakery Market Strategic Shifts & Innovations
Active reformulation is compressing ingredient lists while preserving functional performance. Three convergent developments are restructuring competitive advantage in frozen bakery manufacturing.
Modified starch alternatives derived from pulse flours are absorbing the structural load previously carried by chemically modified wheat starches in frozen dough formulations. Clean-label bakery brands in Germany and Denmark are adopting these ingredients at accelerating rates. The shift is absorbing premium positioning power from established emulsifier suppliers and transferring it to ingredient innovators with patent-protected protein-starch complexes.
REACH compliance deadlines for emulsifier reauthorization are forcing portfolio rationalization among additive suppliers serving European frozen bakery manufacturers. The industrial consequence is reduced formulation flexibility as certain legacy emulsifiers face non-renewal. Frozen bread and roll producers are responding fastest, accelerating enzyme-based clean-label transitions ahead of pastry and cake segments where structural demands are more complex.
Food service procurement is consolidating around frozen pre-baked formats that eliminate proofing labor while delivering finished-product consistency. Contract catering operators and quick-service bakery chains are displacing scratch-baking and fully-baked frozen alternatives alike. This behavioral pivot is most visible in Spain and Portugal, where tourism-dependent hospitality groups prioritize kitchen space efficiency and staff training reduction.
Frozen Bakery Market Segmentation
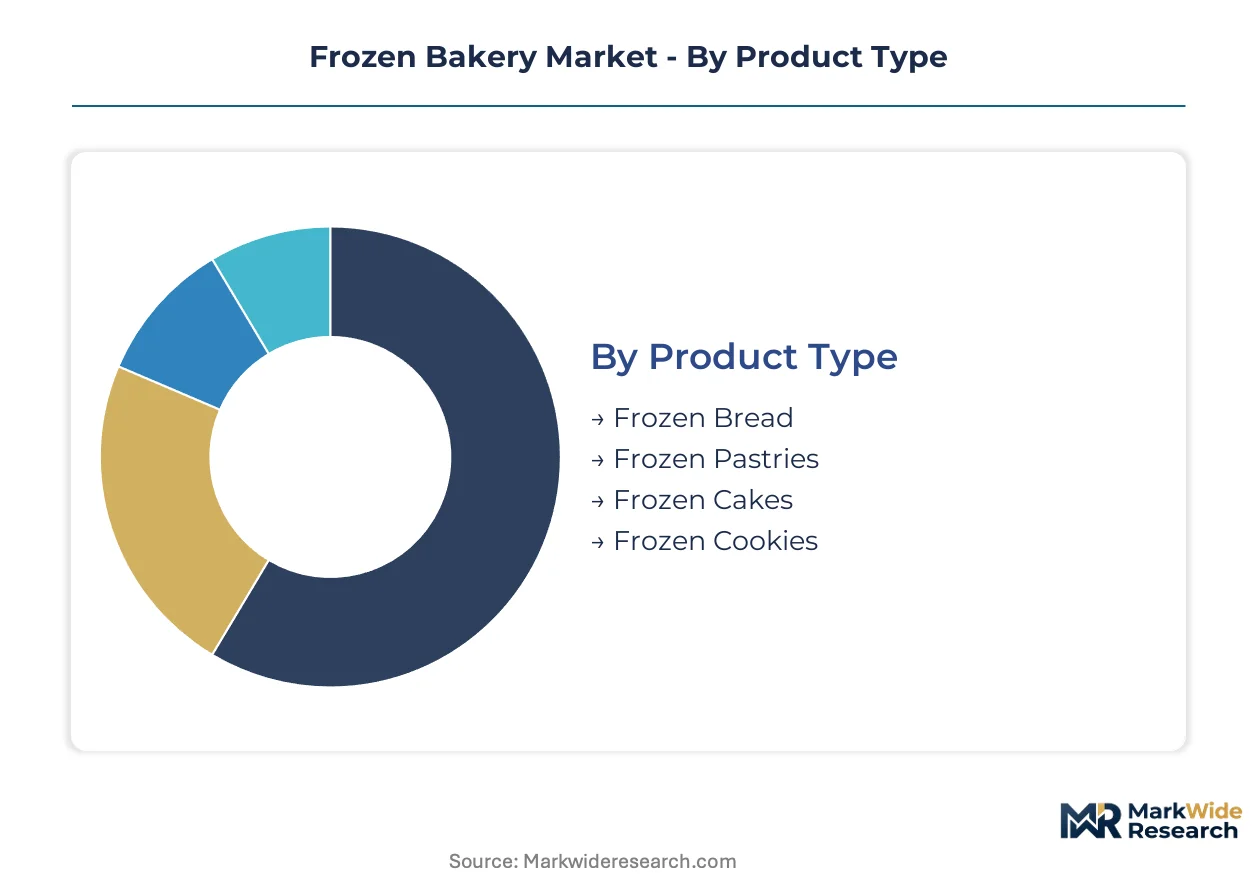
Frozen bakery manufacturers configure production lines around distinct demand profiles that separate high-volume commodity flows from premium-margin specialty formats. Understanding these segment boundaries clarifies where capital allocation yields the highest returns across temperature-controlled supply chains.
Product Type:
Volume throughput and premium positioning diverge sharply across frozen bakery categories, with bread anchoring tonnage and pastries capturing margin expansion.
- Frozen Bread:High-protein wheat formulations with modified starches and emulsifiers ensure post-thaw structural integrity for sandwich loaves, burger buns, and artisan rolls. German industrial bakery clusters and French hypermarket chains drive procurement concentration as food service operators seek labor-saving alternatives to scratch baking.
- Frozen Pastries:Laminated dough products including croissants, Danish, and puff pastry rely on controlled fat crystallization to preserve flake layers through freeze-thaw cycles. Paris and Lyon food service channels are expanding pre-baked croissant procurement as skilled baker scarcity intensifies and kitchen labor costs climb.
- Frozen Cakes:Aerated sponge and buttercream formulations stabilized with hydrocolloids maintain texture integrity across cold chain distribution.
- Frozen Cookies:Portion-controlled dough formats and fully baked variants serve retail convenience positioning and café grab-and-go channels.
Today's leader: Frozen Bread. Tomorrow's challenger: Frozen Pastries.
End Use:
Customer operational constraints reshape product format requirements from freezer-to-oven simplicity to finished-goods direct service.
- Retail Outlets:Supermarket in-store bakeries and hypermarket freezer sections demand thaw-and-sell or bake-off formats that minimize equipment investment and staff training. Polish modern retail expansion in Warsaw and Krakow outpaces frozen bakery penetration, creating whitespace for premium pastry lines.
- Food Service:Contract catering operators and quick-service bakery chains consolidate procurement around pre-baked formats that eliminate proofing labor while delivering finished-product consistency. Spain and Portugal tourism-dependent hospitality groups prioritize kitchen space efficiency.
- Catering:Event and institutional food service requires bulk formats with extended hold times post-thaw.
- Cafés:Independent coffee shop chains seek differentiated viennoiserie and sourdough varieties for premium positioning.
Food Service commands current volume; Catering shows the steepest expansion trajectory as institutional procurement professionalizes.
Distribution Channel:
Cold chain maturity and last-mile temperature control determine which channels can sustain frozen bakery integrity to point of sale.
- Supermarkets:Temperature-controlled aisle networks with dedicated freezer sections dominate frozen cake and cookie sales through impulse placement and promotional velocity.
- Convenience Stores:Limited freezer capacity restricts assortment to high-turnover bread and pastry formats with compact packaging.
- Online Retail:Direct-to-consumer subscription models for specialized frozen sourdough and viennoiserie boxes bypass wholesale margins and build recurring revenue through temperature-controlled last-mile networks.
- Wholesalers:Broadline food service distributors aggregate demand from independent bakeries and regional restaurant chains.
Supermarkets retain volume dominance; Online Retail is gaining share fastest as logistics infrastructure matures.
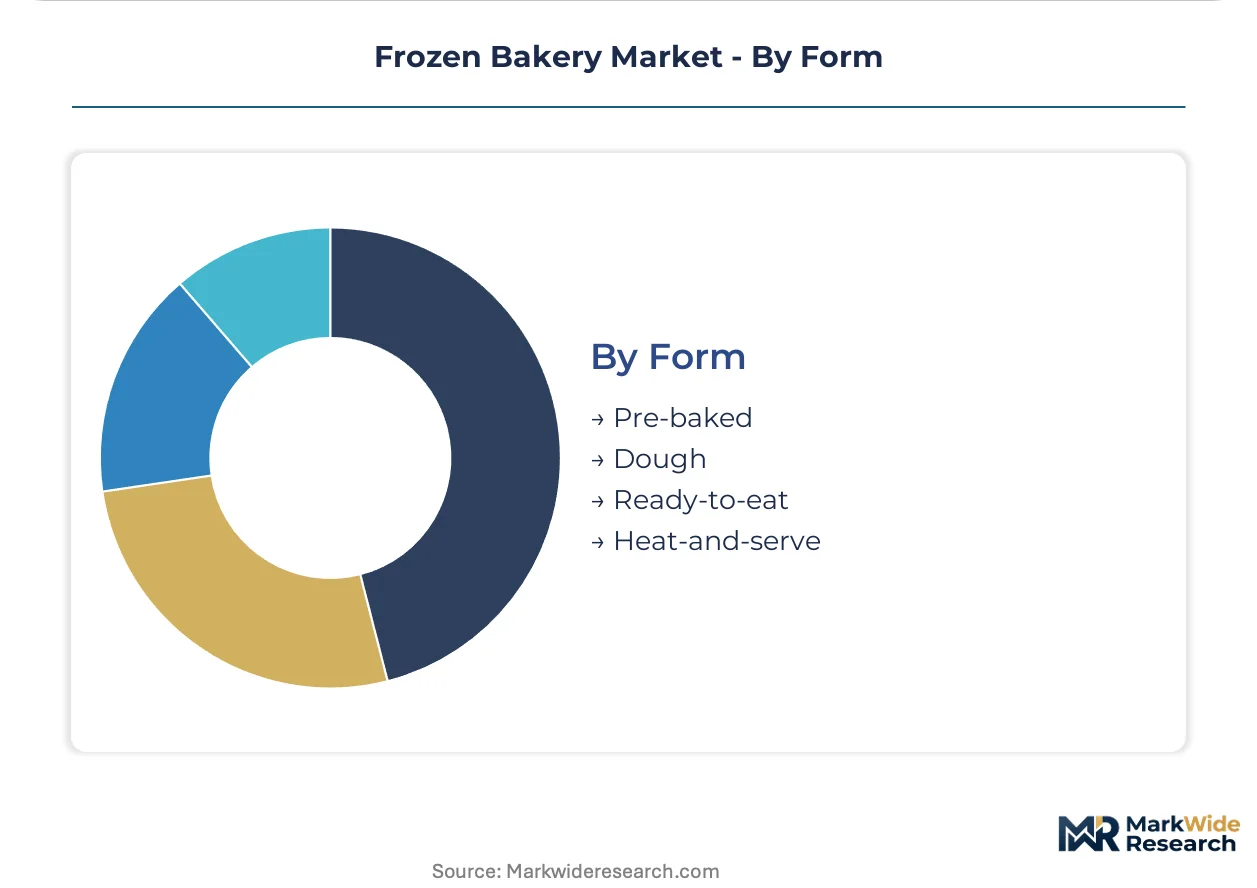
Form:
Processing stage at freezing point determines customer labor input and equipment requirements across the value chain.
- Pre-baked:Partially baked products arrested at staling threshold require only final oven finish, eliminating proofing labor and skill requirements. This format is displacing both scratch-baking and fully-baked frozen alternatives in Spain and Portugal hospitality procurement.
- Dough:Frozen unbaked formulations demand proofing capacity and trained staff but offer freshest finished product positioning.
- Ready-to-eat:Fully baked and frozen products serve immediate consumption with no customer-side processing.
- Heat-and-serve:Finished products requiring only warming for optimal texture and aroma delivery.
Pre-baked leads current adoption; Dough retains premium positioning for artisan-oriented channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled bakery technicians and refrigeration specialists concentrate in Germany's industrial baking clusters, anchoring European frozen dough production capacity. Their expertise underpins high-volume pastry manufacturing and cold-chain logistics that distribute across the continent.
Germany
Industrial bakery clusters in Lower Saxony and Bavaria drive frozen bread and roll production for food service operators seeking labor-saving alternatives. The EU F-Gas Regulation mandates refrigerant phase-downs that accelerate ammonia and CO2 cascade system adoption in regional cold storage facilities. Munich and Hamburg distribution hubs coordinate pan-European frozen pastry logistics through temperature-controlled rail and road networks.
France
Paris and Lyon food service channels expand pre-baked croissant procurement as skilled baker scarcity intensifies and kitchen labor costs climb. REACH compliance deadlines for emulsifier reauthorization force portfolio rationalization among additive suppliers serving French frozen bakery manufacturers. Brittany and Normandy industrial zones concentrate laminated dough production for export to neighboring markets.
United States
Contract catering operators and quick-service bakery chains consolidate procurement around frozen pre-baked formats that eliminate proofing labor. The FDA and USDA jointly oversee frozen dough safety standards, with pathogen controls prescribed for ready-to-bake formulations. Midwest grain corridors and Southeast distribution clusters support national frozen bread and cookie supply chains.
Poland
Modern retail expansion in Warsaw and Krakow outpaces frozen bakery penetration, creating whitespace for premium pastry lines in hypermarket freezer sections. EU Green Deal sustainability targets pressure manufacturers to reformulate recipes and reduce carbon footprints in production. Poznań and Wrocław emerge as secondary distribution nodes connecting to broader European cold-chain infrastructure.
Spain
Tourism-dependent hospitality groups in Barcelona and Madrid prioritize kitchen space efficiency and staff training reduction through frozen pre-baked adoption. The EU F-Gas Regulation drives cold-chain infrastructure upgrades that reduce energy intensity per pallet in distribution. Valencia and Bilbao industrial zones support frozen bread manufacturing for both domestic consumption and export to Portugal.
Frozen Bakery Market Key Industry Players
Capital-heavy producers compete with asset-light designers across frozen bakery manufacturing, separating integrated flour-to-retail networks from specialized formulation houses. The market structure consolidates around three tiers: multinational conglomerates with captive ingredient supply, mid-scale regional specialists with channel-specific expertise, and niche artisan brands targeting direct-to-consumer subscription models. Strategic archetypes include vertically integrated commodity producers, clean-label reformulation specialists, and food service channel dominators. Competitive intensity centers on M&A activity for regional cold-chain assets and strategic partnerships for enzyme-based clean-label technology access.
Among multinational conglomerates, Grupo Bimbo and General Mills occupy positions as scale-driven archetypes with integrated supply networks. Europastry exemplifies the food service channel specialist, while Aryzta AG and Lantmännen Unibake represent European-centered industrial bakery operators with regional cold-chain density. These named entities anchor industry-level commentary on competitive positioning without implying specific strategic actions or market shares beyond their visible archetype representation.
| Leading Market Players |
|---|
| Grupo Bimbo |
| General Mills |
| Rich Products Corporation |
| Aryzta AG |
| Europastry |
| Lantmännen Unibake |
| Vandemoortele |
| Conagra Brands |
| Flowers Foods |
| Others |
Cost & Logistics Intelligence
Food service operators in Paris and Lyon expanding pre-baked croissant procurement are compressing supplier margins through volume consolidation, forcing manufacturers to absorb wheat flour volatility while maintaining fixed annual contract terms. This demand-side pressure reshapes how frozen pastry producers balance input cost exposure against long-term customer lock-in.
Pricing Analysis
The bundled-versus-unbundled service split separates commodity frozen bread transactions from premium pastry offerings that include technical support and formulation customization. Three-tier pricing structure across premium clean-label, standard industrial, and economy private-label levels stratifies the market, with certification tier and volume scale as the primary price differentiation drivers. Pricing pressure stems from high-protein wheat flour cost compression in annual food service contracts. Contract catering operators show highest price sensitivity, while artisan café channels absorb premiums for enzyme-based clean-label formulations.
Supply Chain Analysis
Refrigeration technician scarcity in Germany's Lower Saxony and Bavaria industrial clusters constrains ammonia and CO2 cascade system maintenance capacity, tightening cold-chain throughput. Manufacturing concentrates in Germany, France, and Poland, with supply anchored in high-protein wheat from Midwest grain corridors and specialized emulsifiers subject to REACH reauthorization deadlines. Single-source vulnerability runs through third-party cold storage clustering in northern Italy and the Netherlands. Distribution runs through temperature-controlled rail and road networks coordinated from Munich and Hamburg hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen bakery market reads as a late-cycle quality story where food service procurement consolidation around pre-baked formats shifts margin capture toward suppliers with clean-label certification and technical service bundling.
For Market Incumbents: Cement channel control through captive cold-chain assets in Poland's Warsaw-Krakow corridor while accelerating enzyme-based clean-label transitions ahead of REACH emulsifier deadlines. Threat of industrial freezer concentration in northern Italy demands geographic diversification of third-party storage partnerships. Capacity addition in Poznań and Wrocław distribution nodes is the defensive priority. For New Entrants and Emerging Players: Pulse-flour modified starch alternatives offer a technology-first wedge into German and Danish clean-label bakery brand supply chains. Polish hypermarket freezer sections show lowest penetration relative to modern retail expansion velocity. Direct-to-consumer subscription models for specialized sourdough and viennoiserie boxes bypass wholesale margin capture through temperature-controlled last-mile networks. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale regional specialists possessing channel-specific expertise in food service pre-baked formats and EU Green Deal carbon-labeling compliance infrastructure. Long-term viability over a multi-year horizon favors acquisition targets with dual organic and carbon-neutral certification pipelines. The signal to watch is refrigerant phase-down acceleration under EU F-Gas Regulation tightening timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Enzyme-based alternatives to synthetic emulsifiers secure REACH compliance and premium positioning in German retail. |
| Cold-Chain Infrastructure Expansion | Ammonia and CO2 cascade systems in Poland reduce energy intensity per pallet and EU F-Gas Regulation exposure. |
| Direct-to-Consumer Subscription Launch | Specialized frozen sourdough boxes bypass wholesale margins through temperature-controlled last-mile logistics. |
| Carbon-Neutral Certification Pursuit | Early EU Green Deal product-level disclosure compliance secures preferential listing with sustainability-focused retail banners. |
| Food Service Channel Consolidation | Pre-baked format specialization captures procurement consolidation among Paris and Lyon contract catering operators. |
Research Approach
Coverage spans Germany, France, Poland, Spain, and the United States, with primary inputs from each market combining structured interviews with frozen bakery plant managers, food service procurement leads, retail category buyers, cold-chain logistics operators, and regulatory affairs specialists. Secondary validation draws from EU F-Gas Regulation filings, REACH compliance databases, FDA food safety guidance, customs trade data, and industry association reports. Bottom-up segment sizing and top-down macroeconomic triangulation cross-verify volume and value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, end-use channel, distribution format, and processing stage at freezing point. CAGRs derive from trend extrapolation of historical procurement patterns adjusted for regulatory phase-in schedules and technology substitution curves. Forecast inputs incorporate wheat price volatility scenarios and skilled baker scarcity indices in urban French food service markets.
The model holds under stable EU Green Deal implementation timelines and REACH reauthorization schedules; deviation in refrigerant phase-down acceleration or emulsifier non-renewal decisions would shift competitive positioning and margin structures. Forecasts reflect assumptions about cold-chain infrastructure investment continuity and food service labor cost trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Healthy Biscuits Market
Bakery Products
Bakery Premixes Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Sweet Biscuits Market
Bakery Products
Biscuits Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Low Fat Bread Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Low-Calorie Toast Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market