
 Potassium Propionate Market | 2026-2036
Potassium Propionate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Propionate Market Analytics
Modular formulation packs combining potassium propionate with calcium propionate and sodium benzoate is hardening as the default procurement option for mid-size bakeries seeking multi-barrier preservation. A.M. Food Chemical Co., Ltd. leverages its integrated propionic acid supply chain to dominate food-grade output in Asia-Pacific. Niacet Corporation anchors North American demand through specialized propionate blends for clean-label applications. Tengzhou Tenglong Chemical Co., Ltd. competes on technical-grade volume for industrial non-food uses.
Potassium propionate is the potassium salt of propionic acid, typically manufactured through neutralization of propionic acid with potassium hydroxide to yield a white crystalline powder with minimum 98.5% assay purity; it functions primarily as a mold inhibitor and shelf-life extender in baked goods and processed foods. Food-grade formulations lead volume due to widespread bakery and snack applications, while pharmaceutical-grade segments command premium pricing through USP certification requirements. Direct sales channels sustain margin pools for bulk industrial buyers, though distributor networks extend reach across fragmented regional bakery markets.
FDA food additive regulations under 21 CFR 184.1784 govern potassium propionate usage levels in baked goods, while EFSA evaluates propionate safety thresholds under EU food additive reauthorization cycles. China's SAMR enforces GB standards for propionate purity and labeling, creating compliance costs that favor larger manufacturers with in-house testing laboratories. Stakeholders must monitor evolving clean-label certification requirements from retail chains and propionic acid feedstock volatility tied to petrochemical supply fluctuations.
Market Dynamics
Clean-label bakery demand is compressing synthetic preservative use while tightening purity requirements from Chinese SAMR and EU EFSA reauthorization cycles force simultaneous compliance investments. Manufacturers face dual pressure to eliminate artificial additives and meet ascending analytical thresholds for propionate salts.
Growth Catalysts
- EFSA Reauthorization Cycles:Propionate safety reviews under EU additive renewal protocols sustain technical-grade investment in analytical testing infrastructure.
- East Asian Processed Food Manufacturing:Shanghai and Jiangsu province clusters concentrate demand for mold inhibitors in packaged baked goods and snack production.
- Dual-Barrier Formulation Technology:Modular packs combining potassium propionate with calcium propionate and sodium benzoate extend shelf life without single-chemical dependence.
Market Restraints
- Propionic Acid Feedstock Volatility:Petrochemical supply fluctuations transmit directly to propionate salt production economics.
- Chinese Supply Concentration:A.M. Food Chemical and Tengzhou Tenglong anchor Asia-Pacific capacity, creating single-source vulnerability for food-grade output.
- Clean-Label Substitution Pressure:Fermented wheat flour and cultured dextrose displace chemical preservatives in premium bakery positioning.
Strategic Opportunities
- Indian Processed Food Expansion:FSSAI regulatory harmonization with CODEX standards opens preservative adoption in organized bakery and dairy sectors.
- Pharmaceutical-Grade Certification:USP-grade potassium propionate for parenteral and oral dosage forms commands pricing premiums through analytical documentation.
- Direct Channel Penetration:Bulk industrial buyers bypass distributor networks through manufacturer-owned digital procurement platforms.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA 21 CFR 184.1784 compliance, EFSA additive renewal, and SAMR GB standard adherence stretches regulatory affairs capacity.
- Analytical Laboratory Capex:In-house purity testing for heavy metals and assay verification requires capital deployment that disadvantages smaller compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Propionate Market |
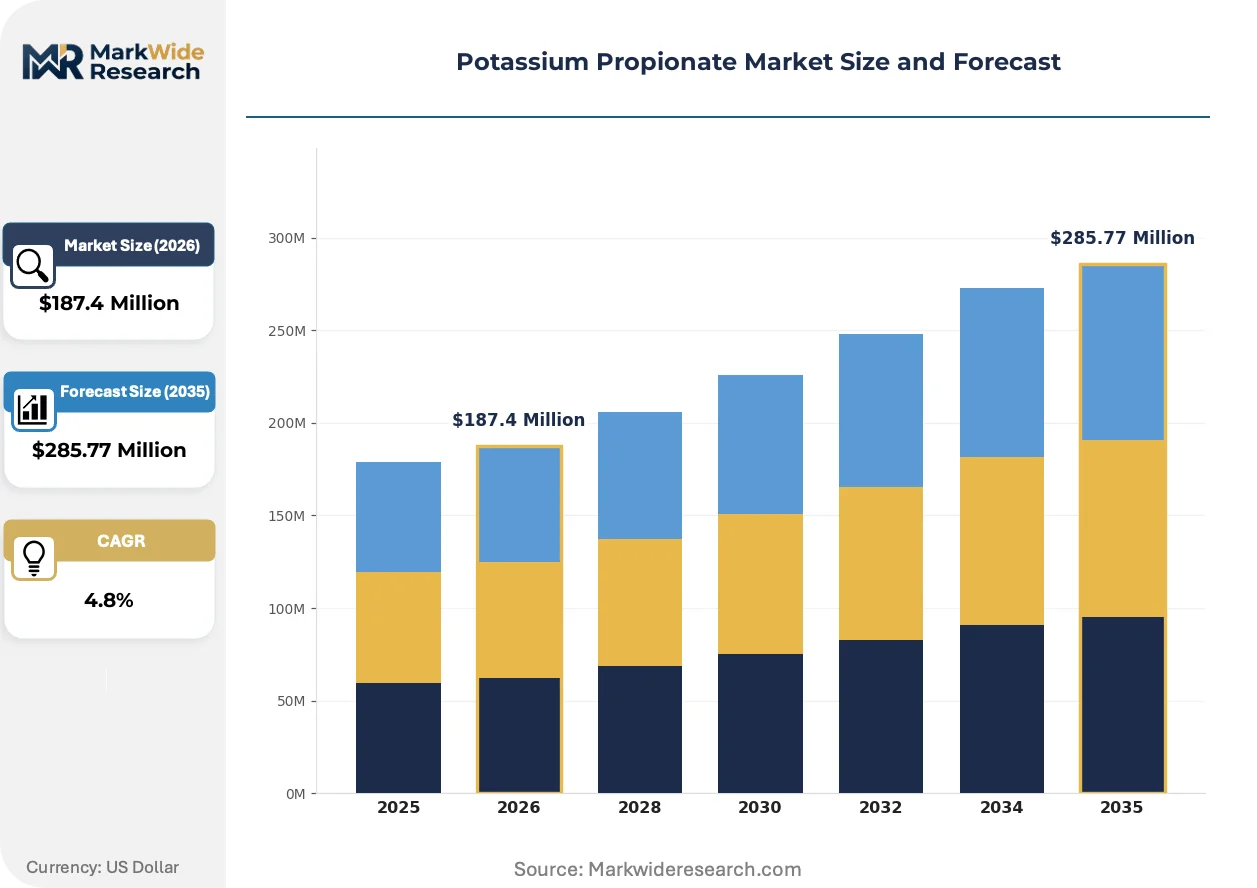
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Technical Grade, Pharmaceutical Grade, Feed Grade Application: Food Preservation, Animal Feed, Personal Care, Pharmaceuticals End User: Food & Beverage Industry, Agriculture, Healthcare, Cosmetics Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | A.M. Food Chemical Co., Ltd., AB Mauri, Niacet Corporation, Tengzhou Tenglong Chemical Co., Ltd., Kemira Oyj, Triveni Chemicals, Macco Organiques Inc., Tokyo Chemical Industry Co., Ltd., Sigma-Aldrich Co. LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Propionate Market Evolving Landscape
Formulation science and regulatory analytics are converging to reshape how preservative systems get specified, tested, and procured across food manufacturing value chains. Technical capabilities now separate contract winners from commodity suppliers.
Encapsulated potassium propionate using lipid and polymer matrices is absorbing moisture-triggered release requirements in high-humidity bakery applications. Large-scale commercial bakeries in Southeast Asia are adopting these systems to prevent surface mold without altering dough rheology. This absorption of controlled-release functionality is compressing demand for conventional crystalline powder formats in tropical climate zones.
EFSA's ongoing propionate reauthorization under EU food additive regulation 1333/2008 is forcing submission of extended toxicological datasets and exposure assessments. Compounders must generate new dietary intake modeling across member states to maintain approved status. The bakery and fine bakery wares segment is responding by accelerating reformulation trials with alternative preservation systems before final scientific opinions publish.
Consolidated procurement by retail bakery chains is concentrating specification-setting power among fewer buyers with dedicated technical staff. Regional distributors serving fragmented independent bakeries are losing influence as direct manufacturer relationships offer technical support and batch certification documentation. This concentration is most visible in Germany and France where retail bakery consolidation has advanced furthest.
Potassium Propionate Market Segmentation
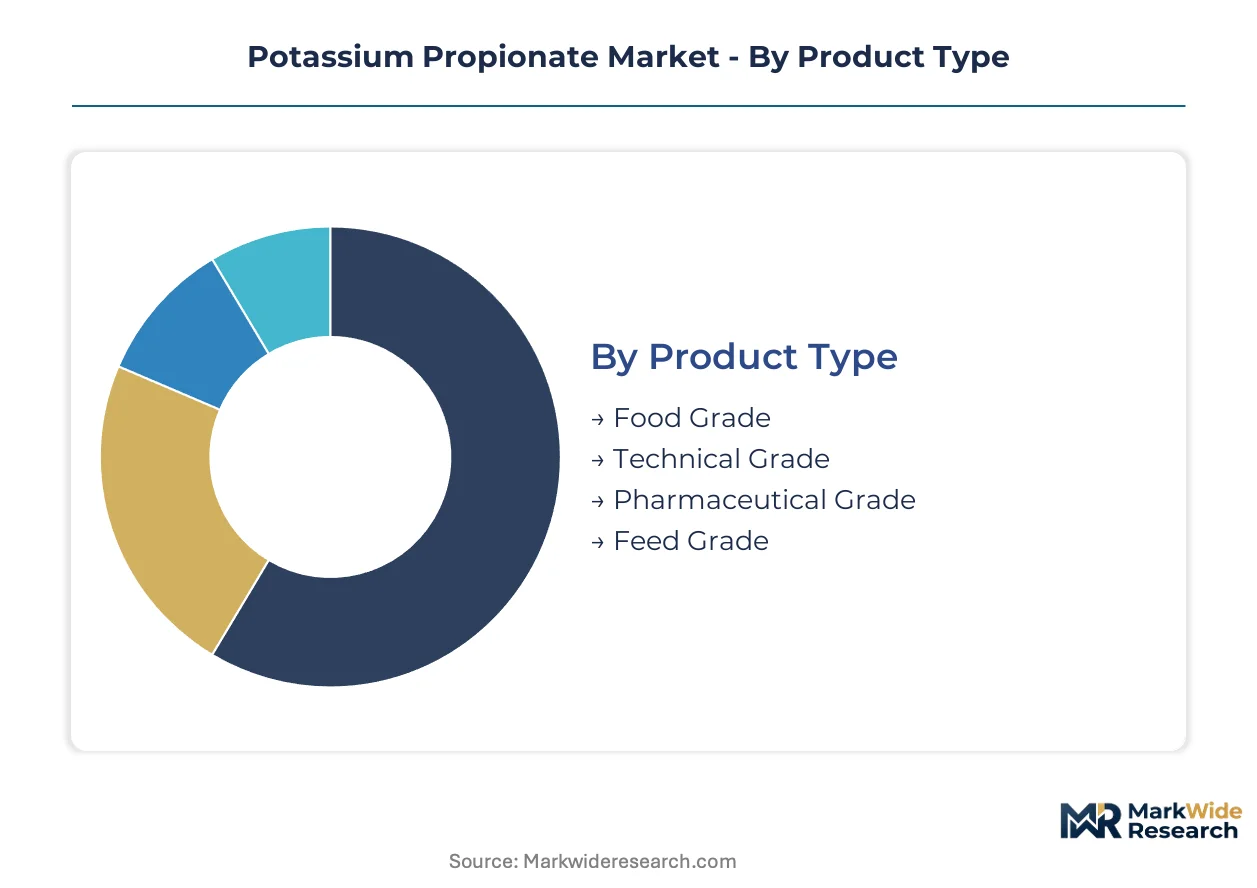
Segmentation in potassium propionate markets reveals how purity specifications and end-use compliance requirements fragment procurement patterns. Manufacturers configure production lines around grade-specific analytical thresholds rather than commodity scale economics.
Product Type:
Specification purity and certification tier determine pricing architecture across propionate salt production, with assay thresholds and heavy metal limits creating distinct manufacturing protocols.
- Food Grade:Minimum 98.5% assay purity with tight heavy metal controls dominates bakery and processed food applications. Shanghai and Jiangsu province manufacturing clusters absorb the highest volumes for packaged baked goods and snack production.
- Technical Grade:Industrial non-food applications tolerate broader specification bands, serving chemical synthesis and manufacturing processes where USP or food additive compliance is unnecessary.
- Pharmaceutical Grade:USP certification with exhaustive analytical documentation supports parenteral and oral dosage forms in regulated healthcare markets.
- Feed Grade:Animal nutrition applications prioritize cost efficiency over the purity thresholds required for human consumption, with propionate salts functioning as mold inhibitors in grain storage and compound feeds.
Food grade leads on scale; pharmaceutical grade leads on momentum.
Application:
Functional requirements across preservation, nutrition, and therapeutic uses create divergent formulation specifications and regulatory submission pathways.
- Food Preservation:Mold inhibition in baked goods and processed foods drives the dominant consumption share, with dual-barrier formulations combining potassium propionate with calcium propionate extending shelf life without single-chemical dependence.
- Animal Feed:Grain storage and livestock nutrition applications concentrate demand in agricultural processing regions, particularly where humidity challenges require propionate-based mold control.
- Personal Care:Cosmetic preservation applications command premium positioning through clean-label compatibility, though volumes remain constrained by alternative natural preservative competition.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient uses require batch-level certification documentation, with parenteral formulations demanding the most stringent analytical verification.
Food preservation commands volume concentration; pharmaceuticals show the steepest expansion trajectory.
End User:
Procurement scale and technical sophistication vary sharply between fragmented bakery operations and consolidated pharmaceutical manufacturers.
- Food & Beverage Industry:Organized retail bakery chains in Germany and France consolidate specification-setting power, while independent bakeries rely on distributor networks for smaller batch procurement.
- Agriculture:Compound feed manufacturers and grain storage operators prioritize cost-efficient technical-grade supply, with procurement timing tied to harvest cycles and inventory management.
- Healthcare:Pharmaceutical manufacturers demand USP-grade material with complete analytical documentation, creating long qualification timelines and stable supplier relationships.
- Cosmetics:Formulation houses seek clean-label compatible preservation systems, with potassium propionate competing against fermented alternatives in premium positioning.
Food and beverage leads on scale; healthcare leads on margin stability.
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and the need for batch certification documentation.
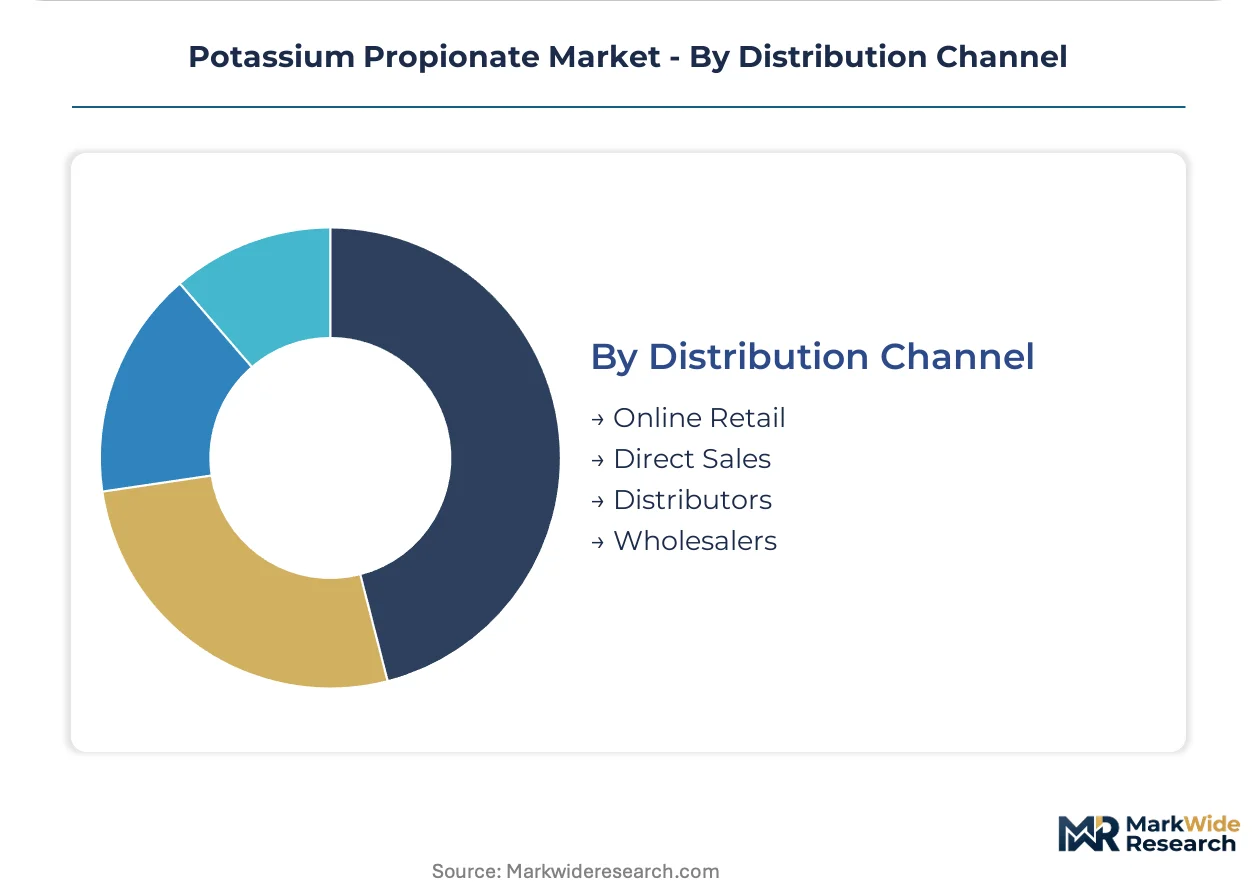
- Direct Sales:Bulk industrial buyers bypass intermediaries through manufacturer relationships, securing technical support and customized formulation services.
- Distributors:Regional networks serve fragmented independent bakeries and smaller compounders, though consolidation in retail baking erodes their influence.
- Online Retail:Digital procurement platforms extend reach to mid-size operations seeking transparent pricing and rapid fulfillment for standard grades.
- Wholesalers:Volume aggregation for commodity technical-grade material supports agricultural and industrial users with predictable demand patterns.
Direct sales leads on scale; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propionic acid neutralization chemistry first achieved commercial scale in German industrial clusters during the early twentieth century, establishing the technical foundation for potassium propionate manufacturing that subsequently diffused to Asia-Pacific food processing centers.
China
Shanghai and Jiangsu province manufacturing clusters absorb the highest volumes for packaged baked goods production. SAMR enforces GB standards for propionate purity and labeling that favor larger manufacturers with in-house testing laboratories. A.M. Food Chemical Co., Ltd. leverages integrated propionic acid supply chains to dominate food-grade output across East Asian processed food operations.
Germany
Organized retail bakery chains consolidate specification-setting power through dedicated technical staff and direct manufacturer relationships. EFSA propionate reauthorization under EU food additive regulation 1333/2008 forces submission of extended toxicological datasets from compounders serving German industrial bakers. Consolidated procurement compresses distributor influence in the most advanced European bakery market.
United States
FDA food additive regulations under 21 CFR 184.1784 govern potassium propionate usage levels in baked goods and processed foods. Niacet Corporation anchors North American demand through specialized propionate blends targeting clean-label bakery applications. Midwest and Southeast bakery manufacturing clusters drive preservative procurement through direct sales channels bypassing traditional distributors.
India
FSSAI regulatory harmonization with CODEX standards opens preservative adoption in organized bakery and dairy sectors previously reliant on unorganized supply chains. Maharashtra and Gujarat processed food manufacturing corridors concentrate emerging demand for mold inhibitors in packaged bread and snack production. Triveni Chemicals occupies a position within the developing supplier base serving this regulatory transition.
Japan
METI industrial standards and PMDA pharmaceutical regulations create dual compliance pathways for food-grade and USP-grade propionate salts. Tokyo Chemical Industry Co., Ltd. represents the specialist chemical distribution archetype serving laboratory and pharmaceutical formulation markets. Kanto region pharmaceutical manufacturing maintains premium-grade demand through exhaustive analytical documentation requirements.
Potassium Propionate Market Competitive Landscape
The competitive structure tilts toward integrated chemical manufacturers with captive propionic acid supply. Food-grade output concentrates among Asia-Pacific compounders with backward integration into petrochemical feedstocks, while pharmaceutical-grade segments reward specialists with analytical certification capabilities. Two archetypes dominate: integrated acid-to-salt manufacturers and regional formulation blenders. Capacity expansion in East Asian propionic acid plants and strategic partnerships between acid producers and salt compounders represent the dominant competitive moves reshaping supply availability.
Within the integrated manufacturer tier, A.M. Food Chemical Co., Ltd. and Tengzhou Tenglong Chemical Co., Ltd. exemplify the Asia-Pacific concentration of food-grade capacity. Niacet Corporation occupies a position representing North American specialization in clean-label propionate blends. These three anchors demonstrate how geographic proximity to propionic acid production and regulatory compliance infrastructure determine competitive positioning across grade-specific market segments.
| Leading Market Players |
|---|
| A.M. Food Chemical Co., Ltd. |
| AB Mauri |
| Niacet Corporation |
| Tengzhou Tenglong Chemical Co., Ltd. |
| Kemira Oyj |
| Triveni Chemicals |
| Macco Organiques Inc. |
| Tokyo Chemical Industry Co., Ltd. |
| Sigma-Aldrich Co. LLC |
| Others |
Value Network & Pricing Analysis
China's dual carbon goals and tightening GB standards under SAMR gate qualified supply for potassium propionate manufacturers while reserving premium-tier pricing access to compounders with in-house analytical laboratories and captive propionic acid production. Food-grade certification compliance costs compress margins for smaller compounders unable to absorb heavy metals testing infrastructure, concentrating pricing power among integrated manufacturers serving East Asian processed food clusters.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food, and technical grades separates USP-certified batch documentation from standard food-grade assay thresholds and industrial non-food specifications. Price differentiation hinges on certification level—FDA 21 CFR 184.1784 compliance and EFSA additive renewal documentation command substantial premiums over technical-grade material—and volume scale, with bulk industrial buyers securing contracted offtake discounts unavailable to fragmented bakery procurement. Cost compression in food-grade tiers intensifies because propionic acid feedstock volatility transmits directly through neutralization economics, while pharmaceutical manufacturers show least price sensitivity due to long qualification timelines and supplier switching costs.
Supply Chain Analysis
Propionic acid supply rests on petrochemical producers in China, South Korea, and Germany, with neutralization capacity concentrating around Shanghai and Jiangsu province manufacturing clusters. Raw material dependencies span ethylene-based propionic acid, potassium hydroxide, and analytical reagents for heavy metals verification. Single-source vulnerability runs through Asia-Pacific food-grade output where A.M. Food Chemical and Tengzhou Tenglong anchor capacity, exposing buyers to geographic concentration risk. Distribution runs through direct sales channels for bulk industrial buyers and consolidated retail bakery chains, while regional distributor networks serve fragmented independent bakeries with diminishing influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Potassium propionate functions as a stable compounder, with preservative demand in packaged baked goods and processed foods providing steady growth underpinned by shelf-life extension requirements in humid climates.
For Market Incumbents: Extend analytical certification capabilities to capture pharmaceutical-grade premiums as USP documentation requirements tighten qualification barriers against commodity compounders. Defend food-grade positioning through backward integration into propionic acid supply, neutralizing feedstock volatility that threatens margin stability. Channel control through direct digital procurement platforms compresses distributor margins while locking in consolidated retail bakery chains with technical support services. For New Entrants and Emerging Players: Launch via online retail and distributor partnerships targeting India's organized bakery sector where FSSAI harmonization with CODEX standards opens preservative adoption previously constrained by unorganized supply chains. White-space concentration sits with technical-grade volume for industrial non-food applications where specification tolerance permits cost-efficient entry without food additive compliance investment. Direct manufacturer relationships with Maharashtra and Gujarat processed food corridors bypass established distributor networks in this regulatory transition window. For Investors and Strategic Acquirers: Valuations sit cheapest among technical-grade compounders lacking certification infrastructure, though long-term viability across a 5-10 year window favors integrated manufacturers with captive acid supply and multi-jurisdiction compliance capabilities. Acquisition target archetype: mid-cap compounders with established East Asian customer relationships and upgradeable analytical laboratories for pharmaceutical-grade pivot. The signal to watch is EFSA propionate reauthorization timing, with final scientific opinions triggering reformulation acceleration that reshapes demand toward alternative preservation systems or reinforces incumbent positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propionic Acid | Captive feedstock supply from Chinese and South Korean petrochemical producers neutralizes raw material price volatility. |
| Pharmaceutical-Grade Certification Investment | USP-grade analytical documentation opens parenteral and oral dosage form markets with premium pricing durability. |
| Direct Digital Procurement Platform Launch | Manufacturer-owned channels bypass distributor networks to serve consolidated German and French retail bakery chains. |
| Encapsulated Formulation Development | Lipid and polymer matrix technology addresses moisture-triggered release requirements in Southeast Asian tropical bakery applications. |
| Indian Market Regulatory Alignment | FSSAI-CODEX harmonization enables organized sector penetration in Maharashtra and Gujarat processed food corridors. |
Research Methodology
Bottom-up bakery and pharmaceutical demand modeling reconciled against top-down propionic acid supply tracking forms the analytical core of this study. Primary interviews with plant managers at potassium propionate compounders, procurement leads at downstream food manufacturers, distribution channel partners serving regional bakery markets, and technical R&D directors at preservative blenders combined with secondary validation from SAMR GB standard filings, EFSA additive reauthorization documentation, FDA 21 CFR registers, and customs trade data for propionate salt flows. Triangulation between consumption-side volume builds and production-capacity assessments ensures consistency across estimation approaches.
Input-output matrices map propionic acid availability through neutralization capacity to grade-specific output across food, pharmaceutical, technical, and feed tiers over the projection horizon. Segmentation dimensions span purity grade, end-use application, buyer scale, and regional regulatory cluster, with CAGRs derived from intensity-of-use modeling in baked goods production and pharmaceutical formulation growth. Forecast inputs include propionic acid feedstock pricing dynamics, EFSA reauthorization timeline uncertainty, and clean-label substitution elasticity in premium bakery positioning.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propionic acid supply disruption or accelerated EFSA propionate restriction. Forecasts reflect documented assumptions regarding regulatory adherence costs, certification timeline durations, and substitution technology penetration rates. A small set of named triggers—EFSA final scientific opinion publication, SAMR enforcement intensity shifts, and Indian organized sector expansion velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Egypt Food Preservatives Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
South America Food Colorants Market