
 Flatbread Market | 2026-2036
Flatbread Market Size, Share, and Industry Trends Forecast 2026-2036
Flatbread Market Intelligence
Organic certification under USDA National Organic Program standards is unwinding competitive barriers for mid-scale bakers seeking premium shelf placement. Gruma leverages its vertical integration in corn flour milling to control input costs across tortilla production. Conagra Brands sustains broad retail distribution through multi-brand portfolios spanning frozen and refrigerated flatbread lines. Kontos Foods specializes in Mediterranean formats, dominating foodservice channels with hand-stretched lavash and pita.
Flatbread denotes unleavened or minimally leavened bread products typically baked at high temperatures, with moisture content ranging from 25% to 35% and thickness under 10 millimeters, serving as carriers for fillings or standalone accompaniments in commercial and home meal preparation. Tortilla leads volume across North American retail and foodservice due to entrenched Mexican cuisine integration, while naan posts the fastest growth among premium ethnic offerings in European supermarkets. Frozen form commands margin pools through extended shelf life and reduced spoilage rates, though fresh formats retain pricing power in urban foodservice.
The FDA enforces Current Good Manufacturing Practice and preventive controls under FSMA for domestic and imported flatbread facilities, raising compliance costs but filtering out sub-scale producers. USDA organic and non-GMO verification programs create dual-tier market access, with certified products commanding differentiated placement. EFSA gluten-free labeling thresholds in Europe shape reformulation investments for wheat-alternative flatbreads. Stakeholders must monitor evolving front-of-pack labeling mandates and carbon accounting rules that will reshape supplier qualification criteria and regional sourcing decisions.
Market Dynamics
Quick-service restaurant chains in the United States are standardizing tortilla and pita formats as wrap carriers, compressing procurement cycles and forcing bakeries to retool lines for high-volume, consistent output specifications.
Growth Catalysts
- FSMA Preventive Controls:The FDA's updated Food Safety Modernization Act rules on preventive controls for human food are filtering out sub-scale producers and creating shelf space for compliant mid-scale bakers.
- Organized Retail Expansion:India's supermarket and hypermarket chains are expanding frozen and fresh flatbread sections, extending distribution reach for branded naan and roti producers beyond traditional kirana stores.
- High-Temperature Baking Automation:Continuous belt ovens with precision temperature profiling are enabling foodservice suppliers to achieve consistent thickness and moisture content at commercial scale.
Market Restraints
- Wheat Price Volatility:Input cost swings for wheat and corn flour concentrate margin pressure on tortilla and pita producers lacking captive milling capacity.
- Gluten-Free Labeling Thresholds:EFSA's strict gluten-free certification requirements in Europe impose reformulation costs and limit wheat-alternative flatbread market access.
- Fresh Format Spoilage:Short shelf life for non-frozen flatbreads creates distribution radius constraints and cold chain dependency in urban foodservice channels.
Strategic Opportunities
- USDA Organic Certification:The National Organic Program standard creates dual-tier market access with premium placement for certified flatbreads in conventional retail.
- Carbon Accounting Integration:EU Green Deal reporting requirements are reshaping supplier qualification criteria, favoring regional sourcing and low-emission production facilities.
- Direct-to-Restaurant Platforms:Digital procurement channels are emerging as alternatives to broadline distribution for independent Mediterranean and Middle Eastern restaurants seeking specialized lavash and pita formats.
Industry Challenges
- Preventive Controls Qualified Individual Shortage:FSMA-mandated PCQI certification requirements outpace training program output, delaying facility compliance timelines for smaller producers.
- Legacy Equipment Retrofit Costs:Continuous baking lines require substantial capital outlay for temperature monitoring and allergen segregation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flatbread Market |
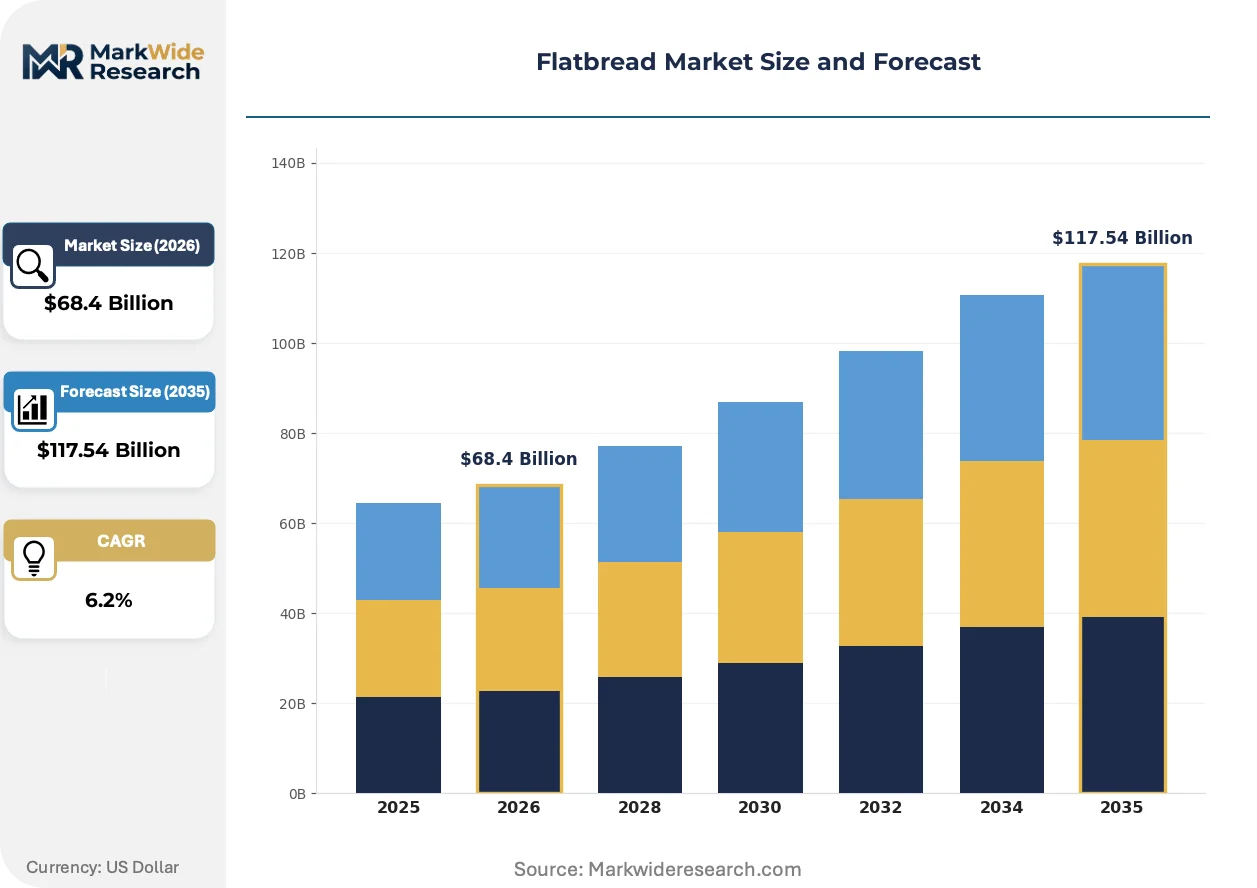
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pita, Naan, Tortilla, Lavash Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice Form: Frozen, Fresh, Semi-Dry, Baked End User: Households, Restaurants, Cafés, Food Trucks |
| Companies Covered | Conagra Brands, Kontos Foods, Gruma, California Lavash, Klosterman Baking Company, Grupo Bimbo, Tyson Foods, Flowers Foods, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flatbread Market Strategic Shifts & Innovations
Automation and alternative ingredient systems are compressing traditional production economics while regulatory transparency requirements reshape competitive qualification criteria across supply tiers.
Sourdough-fermented flatbread formulations are fragmenting the premium shelf-stable segment. Artisan bakeries and mid-scale co-manufacturers are adopting extended fermentation protocols to develop flavor complexity without chemical preservatives. This process innovation is fragmenting the boundary between fresh and shelf-stable categories, enabling ambient distribution for products previously confined to refrigerated channels.
REACH chemical registration requirements in Europe are tightening scrutiny on processing aids and packaging migrants in frozen flatbread supply chains. The regulation is forcing reformulation of anti-sticking agents and liner materials. Frozen format producers serving EU retail are accelerating migration to mineral oil-free packaging and native starch-based release coatings.
Foodservice procurement consolidation among US quick-service chains is compressing supplier qualification cycles. Chains are unbundling flatbread specifications from broadline distribution contracts and negotiating directly with specialized bakeries. This pattern is most visible in the Southwest and Southeast regions where Mexican and Mediterranean cuisine penetration drives dedicated tortilla and pita line investments.
Flatbread Market Segmentation
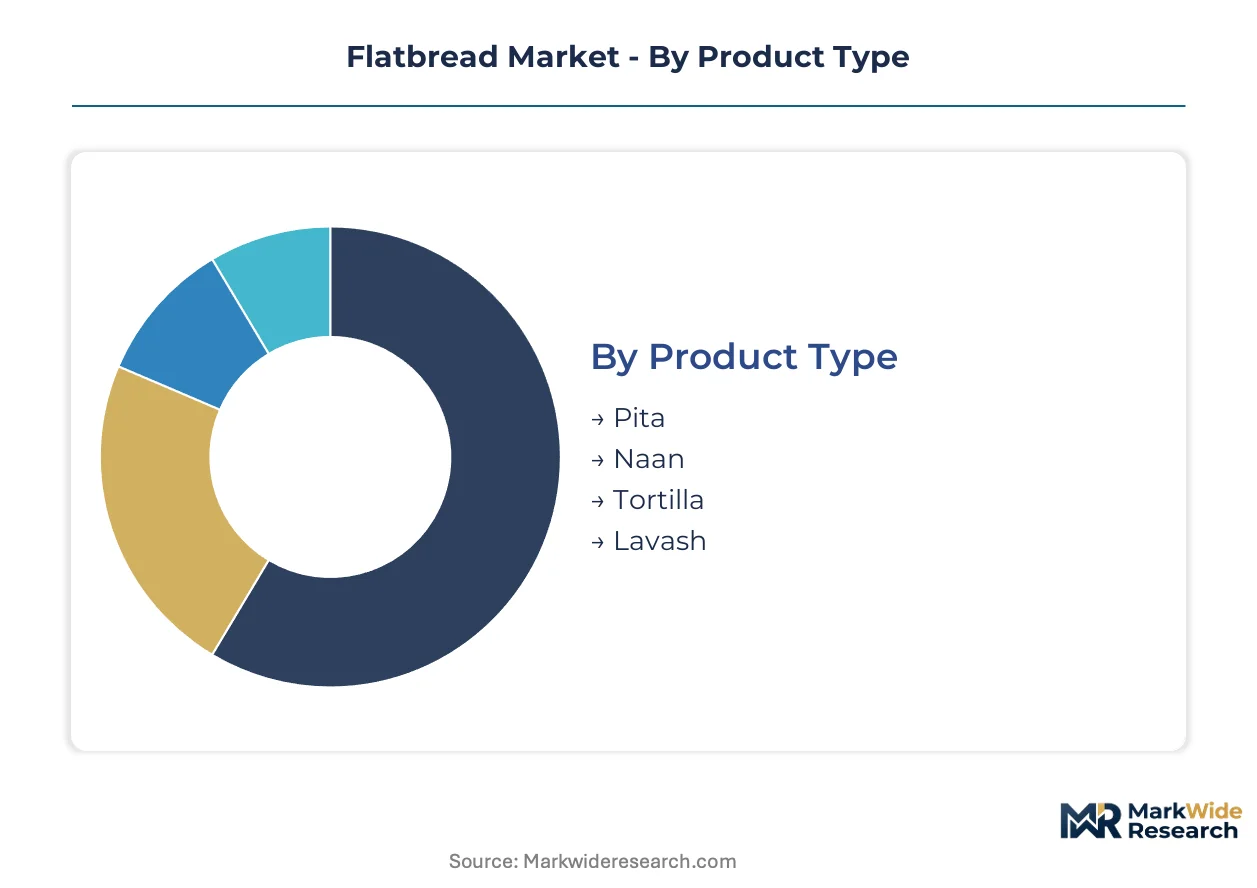
Flatbread producers configure product portfolios around margin concentration points that vary sharply by format and channel. Segment boundaries are blurring as sourdough fermentation and high-temperature automation reshape traditional category definitions.
Product Type:
Margin pools concentrate in formats serving high-volume foodservice contracts with standardized specifications.
- Tortilla:Corn and wheat flour variants dominate North American quick-service procurement with thickness specifications between 1.5 and 2.5 millimeters. US chains in the Southwest and Southeast regions are unbundling tortilla specifications from broadline distribution contracts to negotiate directly with specialized bakeries.
- Naan:Leavened wheat dough with yogurt or milk enrichment carries moisture content above 30 percent, requiring precise high-temperature baking. Premium ethnic offerings in European supermarkets are climbing the fastest as Indian diaspora populations expand and organized retail dedicates freezer space to branded roti and naan lines.
- Pita:Pocket-forming yeast-leavened breads serve wrap and sandwich carriers across Mediterranean and Middle Eastern foodservice channels. Hand-stretched production methods retain pricing power in independent restaurant segments.
- Lavash:Thin unleavened sheets from wheat flour serve wrap and cracker applications with extended shelf stability. Armenian and Persian foodservice specialists in urban clusters drive specialized demand.
Tortilla holds installed capacity across industrial-scale production lines. Naan is rotating up the share rankings in premium retail placement.
Distribution Channel:
Channel selection determines cold chain investment requirements and pricing power retention.
- Foodservice:Direct procurement relationships with quick-service chains and independent restaurants command volume concentration but compress margins through specification standardization. Digital procurement platforms are emerging as alternatives to broadline distribution for specialized formats.
- Supermarkets:Multi-temperature retail sections spanning frozen, refrigerated, and ambient shelves create placement competition. India's supermarket and hypermarket chains are expanding frozen and fresh flatbread sections beyond traditional kirana store reach.
- Convenience Stores:Grab-and-go refrigerated formats with abbreviated ingredient lists target immediate consumption occasions. Shelf space constraints favor shelf-stable or frozen over fresh deliveries.
- Online Retail:Direct-to-consumer frozen shipments require insulated packaging and last-mile cold chain coordination. Subscription models for artisan sourdough flatbreads are fragmenting premium segments.
Foodservice channels anchor volume throughput. Online retail is rotating up the share rankings as cold chain logistics mature.
Form:
Moisture retention and shelf stability specifications divide capital requirements and margin structures.
- Frozen:Blast-freezing at minus 18 degrees Celsius extends shelf life to 12 months and enables national distribution radius. Extended shelf life and reduced spoilage rates command margin pools, though mineral oil-free packaging reformulation is accelerating under REACH chemical registration requirements in Europe.
- Fresh:Non-frozen formats with 7 to 14 day refrigerated shelf life retain pricing power in urban foodservice but create distribution radius constraints. Short shelf life generates cold chain dependency and limits penetration beyond metropolitan clusters.
- Semi-Dry:Intermediate moisture products bridge ambient stability and eating quality for emergency stock and military supply. Specialized packaging with oxygen scavengers extends shelf life without frozen infrastructure.
- Baked:Ambient-stable formats with modified atmosphere packaging serve retail shelf-stable segments. Sourdough fermentation protocols are enabling ambient distribution for products previously confined to refrigerated channels.
Frozen formats hold installed capacity across industrial freezing tunnels. Fresh formats are rotating up the share rankings in premium urban foodservice.
End User:
User type dictates batch size requirements, customization tolerance, and specification stringency.
- Restaurants:Quick-service chains standardize tortilla and pita formats as wrap carriers, compressing procurement cycles and forcing bakeries to retool for high-volume consistent output. Independent Mediterranean and Middle Eastern restaurants seek specialized lavash and pita with hand-stretched characteristics.
- Households:Retail purchasers balance convenience against ingredient transparency, with organic certification under USDA National Organic Program standards unlocking premium placement. Multi-packs and single-serve formats split demand by household size.
- Cafés:Coffee-forward establishments prioritize visual appeal and Instagram-compatible presentation in flatbread-based menu items. Limited kitchen footprints favor pre-baked or par-baked formats requiring minimal finishing.
- Food Trucks:Mobile operators demand durability under heat lamp holding and rapid assembly compatibility. Wrap formats with structural integrity under filling weight concentrate procurement.
Restaurants hold installed capacity through foodservice supply relationships. Households are rotating up the share rankings as organized retail expands branded access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSMA preventive controls are filtering sub-scale producers across multiple jurisdictions, while organized retail expansion and diaspora-driven cuisine adoption reshape demand geography. National regulators are tightening chemical registration and carbon accounting rules that will determine facility qualification and sourcing patterns.
United States
Quick-service chains in the Southwest and Southeast regions are unbundling tortilla and pita specifications from broadline distribution contracts to negotiate directly with specialized bakeries. FDA preventive controls under FSMA raise compliance costs but create shelf space for certified mid-scale producers. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate high-temperature baking automation investments serving regional chain procurement.
India
Supermarket and hypermarket chains are expanding frozen and fresh flatbread sections beyond traditional kirana store reach, extending distribution for branded naan and roti producers. FSSAI food safety standards and the PLI scheme for food processing incentivize organized sector capacity expansion. Mumbai and Delhi-NCR industrial corridors anchor automated production facilities targeting modern retail and export channels.
Germany
REACH chemical registration requirements are tightening scrutiny on processing aids and packaging migrants in frozen flatbread supply chains, forcing reformulation of anti-sticking agents. EFSA gluten-free labeling thresholds shape wheat-alternative product development investments. The Munich-Stuttgart corridor hosts specialized Mediterranean format producers serving foodservice channels across Central Europe.
United Kingdom
Premium ethnic offerings in supermarkets are climbing fastest as Indian diaspora populations expand and organized retail dedicates freezer space to branded roti and naan lines. Front-of-pack labeling mandates under evolving UK nutrition policy reshape supplier qualification criteria. The London metropolitan cluster concentrates sourdough-fermented flatbread innovation and direct-to-restaurant digital procurement platforms.
Mexico
Entrenched Mexican cuisine integration sustains tortilla volume leadership across North American retail and foodservice channels with thickness specifications between 1.5 and 2.5 millimeters. NOM food safety standards align with FDA preventive controls for cross-border supply chains. The Mexico City metropolitan area and Nuevo León state anchor industrial-scale corn and wheat flour tortilla production serving export markets.
Flatbread Market Key Industry Players
Player mix skews toward diversified food conglomerates with multi-brand portfolios spanning frozen and refrigerated lines, alongside specialized Mediterranean format producers dominating foodservice channels. Strategic archetypes include vertically integrated corn flour millers controlling input costs, artisan-leaning specialists retaining hand-stretched production pricing power, and broadline bakers sustaining retail distribution through scale. Dominant competitive moves encompass direct procurement negotiations with quick-service chains and mineral oil-free packaging reformulation for EU market access.
Among diversified North American conglomerates, Conagra Brands and Tyson Foods occupy positions spanning multi-temperature retail segments, while Gruma exemplifies upstream integration into corn flour milling. Kontos Foods represents the specialized Mediterranean format archetype, with California Lavash anchoring the thin-sheet lavash segment. These entities collectively illustrate the competitive tension between scale-driven retail distribution and format-specific foodservice expertise.
| Leading Market Players |
|---|
| Conagra Brands |
| Kontos Foods |
| Gruma |
| California Lavash |
| Klosterman Baking Company |
| Grupo Bimbo |
| Tyson Foods |
| Flowers Foods |
| General Mills |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between US quick-service chains and specialized tortilla bakeries lock in both supply access and price visibility across the Southwest and Southeast corridors. These arrangements compress spot market participation while amplifying cost pass-through pressure when wheat and corn flour inputs swing.
Pricing Analysis
Certification level under USDA National Organic Program standards creates the primary spread between premium shelf placement and conventional positioning. Three-tier pricing structure across premium organic, standard commercial, and economy private-label levels dominates retail channels. Cost compression in the economy tier is intensifying because private-label buyers demand volume guarantees without brand premium support. Quick-service chains exhibit lowest price sensitivity due to specification lock-in, while independent Mediterranean restaurants negotiate hardest on per-unit delivered costs.
Supply Chain Analysis
Mexico-US border crossing infrastructure underwrites just-in-time tortilla delivery to Southwestern distribution centers. Geographic supply concentration centers on Mexico, the United States, and India for distinct format specializations. Raw material flows draw from North American wheat belts, Mexican corn flour milling clusters, and Indian atta processing facilities. Single-source vulnerability in specialized Mediterranean format production creates exposure when hand-stretched capacity concentrates in urban foodservice hubs. Distribution runs through broadline foodservice networks, direct-to-restaurant digital platforms, and multi-temperature retail sections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated quick-service procurement offices unbundling flatbread specifications from legacy distribution contracts. This fragmentation among suppliers concentrates negotiating leverage with chains operating across 500-plus locations.
For Market Incumbents: Compound defensive positioning by securing FSMA Preventive Controls Qualified Individual certification ahead of compliance deadlines, locking out sub-scale competitors. Add high-temperature baking automation capacity in Dallas-Fort Worth and Phoenix metropolitan clusters to serve regional chain procurement concentration. Deepen backward integration into corn flour milling to offset wheat price volatility threatening margin pools.
For New Entrants and Emerging Players: Digital procurement platform under-service by incumbents creates entry space for specialized lavash and pita formats targeting independent Mediterranean and Middle Eastern restaurants. Target the UK premium ethnic retail segment where Indian diaspora expansion outpaces branded naan and roti supply. Pursue direct-to-restaurant subscription models bypassing broadline distribution margin extraction.
For Investors and Strategic Acquirers: Mid-scale sourdough-fermented flatbread specialists with ambient distribution capabilities represent priority acquisition targets as category boundaries fragment. Long-term viability hinges on carbon accounting integration readiness under EU Green Deal reporting requirements. Monitor REACH chemical registration enforcement intensity as the signal indicating packaging reformulation cost acceleration and competitive filtration timing.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | Unlocks premium retail placement and dual-tier market access under National Organic Program standards. |
| High-Temperature Baking Automation | Enables consistent thickness and moisture specifications demanded by quick-service chain procurement offices. |
| Mineral Oil-Free Packaging Reformulation | Ensures continued EU market access under REACH chemical registration scrutiny on processing aids. |
| Direct-to-Restaurant Digital Platform Launch | Bypasses broadline distribution consolidation serving independent Mediterranean format specialists. |
| Backward Integration into Corn Flour Milling | Captures input cost control across tortilla production volumes exposed to commodity price swings. |
Research Approach
The analysis maps tortilla, naan, pita, and lavash production segments, each validated through plant managers at industrial baking facilities, procurement leads at quick-service chains, category buyers at supermarket chains, and distribution channel partners. Primary interview intelligence triangulates against secondary sources including FDA FSMA guidance documents, USDA organic certification databases, EFSA food safety opinions, customs and trade flow records, and SEC filings from diversified food conglomerates. Bottom-up facility capacity estimates reconcile with top-down consumption surveys across household, restaurant, café, and food truck end-use categories.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, distribution channel, form, and end-user segmentation dimensions alongside regional regulatory cluster variations. CAGRs derive from slope analysis of annualized growth trajectories calibrated against wheat and corn flour price indices, quick-service chain expansion pipelines, and organized retail square footage growth in India and the United Kingdom. Industry-specific forecast inputs include high-temperature baking automation deployment rates and FSMA compliance timeline acceleration.
Forecasts assume regulatory continuity in FDA preventive controls enforcement, EFSA gluten-free labeling thresholds, and REACH chemical registration requirements; material policy shifts would require re-modeling. Specific risk factors encompass wheat price volatility spikes, Preventive Controls Qualified Individual training bottlenecks, and carbon accounting rule acceleration under EU Green Deal implementation. Practitioners should keep alternative scenarios live as quick-service procurement consolidation patterns and diaspora-driven cuisine adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Bread Premix Market
Bakery Products
Bakery Flavors Market
Bakery Products
Ice Cream Market
Bakery Products
Malted Rye Flour Market
Bakery Products
United States Bread Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Wedding Cakes Market
Bakery Products
Bakery Fats Market
Bakery Products
Bread and Baked Food Market
Bakery Products
Pie Shells Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Cake Concentrate Market
Bakery Products
Dough Conveyor Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Ready-To-Finish Bakery Products Market