
 US Residential Construction Market | 2026-2036
US Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
US Residential Construction Market Outlook
Energy-efficient certification tiers is bifurcating the US residential construction market into premium and baseline product lanes. D.R. Horton leverages its national scale to dominate entry-level production across multiple Sun Belt metros. Lennar Corp. anchors its position through integrated technology packages and mortgage financing arms. Meritage Homes Corp. differentiates via standardized green building protocols that reduce buyer energy costs.
US residential construction encompasses the assembly of single-family dwellings, multi-family structures, and attached housing units using wood framing, concrete foundations, steel reinforcement, and drywall systems to create habitable structures compliant with local building codes. The primary purpose spans shelter provision, wealth accumulation through homeownership, and rental income generation for investors. Single-family homes command the largest share of construction value, while modular design represents the fastest-expanding construction category as labor scarcity drives prefabrication adoption. Sustainable construction methods capture disproportionate margin pools as utility rebate programs and insurance discounts reward certified green buildings.
FHA lending criteria, local zoning boards, and the International Energy Conservation Code shape builder product mix and geographic expansion decisions across US municipalities. EPA stormwater regulations and OSHA fall-protection standards further dictate site preparation costs and framing crew deployment protocols. Stakeholders must monitor interest rate trajectories and municipal permitting velocity to time land acquisition and community launch cycles effectively.
Market Dynamics
FHA lending criteria and municipal zoning reforms are compressing development timelines and concentrating builder activity in Sun Belt corridors where entitlement friction remains lowest. These regulatory mechanics now override raw land availability as the primary expansion determinant for national production builders.
Growth Catalysts
- First-time buyer mortgage access:FHA loan limits and down-payment assistance programs in Texas and Florida are unlocking entry-level demand that conventional financing excludes.
- OSHA fall-protection mandates:Standardized safety protocols are accelerating prefabrication adoption as builders move framing operations off-site to reduce compliance exposure.
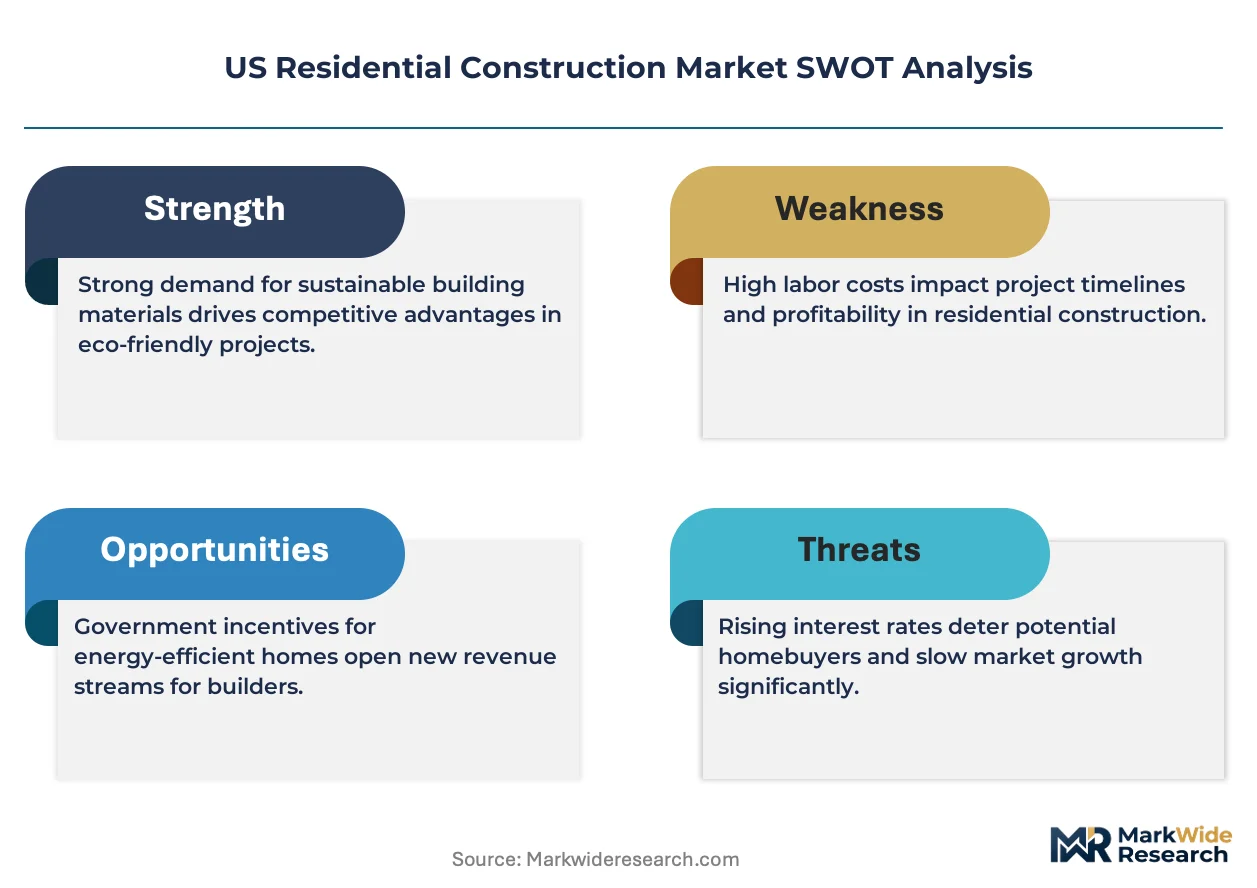
- Utility rebate stacking:Layered incentives from municipal power authorities and state energy offices are shortening payback periods for green certification investments.
Market Restraints
- Lumber futures volatility:Pacific Northwest mill capacity constraints and Canadian softwood tariff exposure are compressing gross margins on wood-framed product lines.
- EPA stormwater permitting:NPDES construction general permit delays in high-growth counties are extending pre-construction timelines by 90-120 days.
- Skilled trades scarcity:Electrician and HVAC technician pipeline gaps in Arizona and Florida are capping community absorption rates regardless of market demand.
Strategic Opportunities
- Modular assembly penetration:Factory-built wall and roof systems are capturing share in labor-constrained Texas metros where site-built cycle times have doubled.
- Insurance premium differentiation:Fortified roof and impact-resistant window certifications are opening margin pools in Florida where carriers are restricting coverage on unimproved stock.
- Build-to-rent channel expansion:Institutional single-family rental operators are absorbing entire subdivision phases, converting traditional for-sale production to recurring revenue streams.
Industry Challenges
- International Energy Conservation Code adoption lag:Jurisdictional variance in 2021 IECC implementation is forcing builders to maintain multiple specification sets across adjacent municipalities.
- Land entitlement timeline compression:Accelerated community launches are colliding with archaeological review and wetlands delineation requirements that resist schedule pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Residential Construction Market |
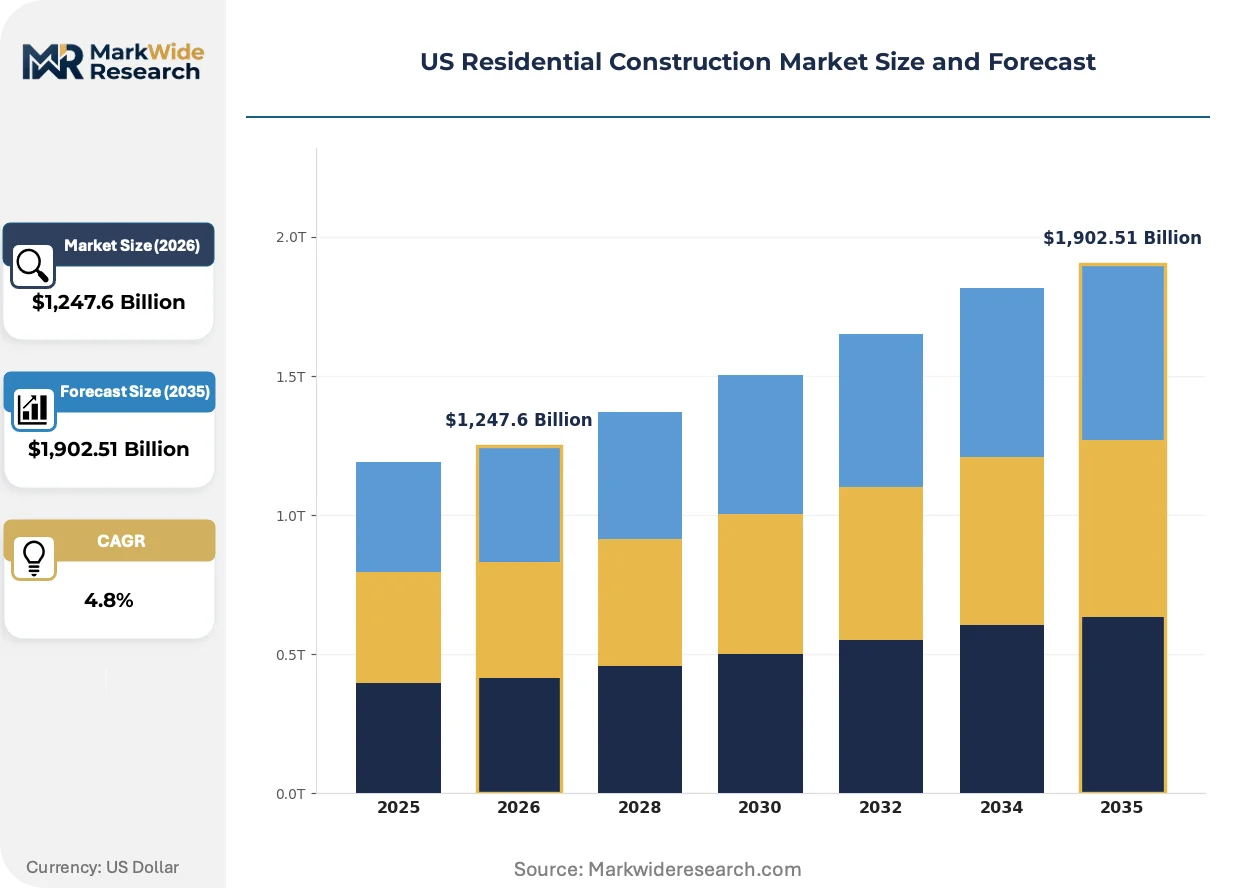
| Market Size in 2026 | $1,247.6 Billion |
| Market Size in 2035 | $1,902.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Family Homes, Multi-Family Units, Townhouses, Condominiums End User: First-Time Buyers, Real Estate Investors, Homeowners, Commercial Developers Building Material: Wood, Steel, Concrete, Drywall Construction Design: Traditional, Modern, Sustainable, Modular |
| Companies Covered | NVR, KB Home, D.R. Horton, Century Communities, Meritage Homes Corp., Lennar Corp., Taylor Morrison, Clayton Properties Group, PulteGroup, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Residential Construction Market Strategic Shifts
Prefabrication methods and energy-performance certification are converging to redefine competitive positioning in US residential construction. These shifts are compressing traditional site-built advantages while elevating factory-controlled quality as a differentiator.
Cross-laminated timber (CLT) and mass plywood panels are penetrating mid-rise multifamily construction as engineered wood alternatives to steel and concrete. Sun Belt developers in Austin and Phoenix are specifying these materials for five-over-one podiums to accelerate structural schedules. The technology is miniaturizing foundation and framing crews while reducing crane-day requirements on tight urban infill sites.
The International Energy Conservation Code 2021 cycle is mandating blower-door testing and thermal envelope commissioning in jurisdictions covering roughly one-third of new US housing starts. Builders in California and Washington are pre-certifying entire product lines to avoid per-unit inspection delays. The standard is concentrating builder investment in air-sealing protocols and HVAC right-sizing that exceed baseline code minimums.
Direct-to-builder procurement platforms are displacing traditional lumberyard intermediaries for commodity structural materials. National production builders in Florida and Arizona are contracting OSB and framing lumber through digital exchanges that aggregate volume across multiple divisions. This channel shift is compressing delivered cost variance and reducing inventory carrying requirements in volatile price environments.
US Residential Construction Market Segmentation
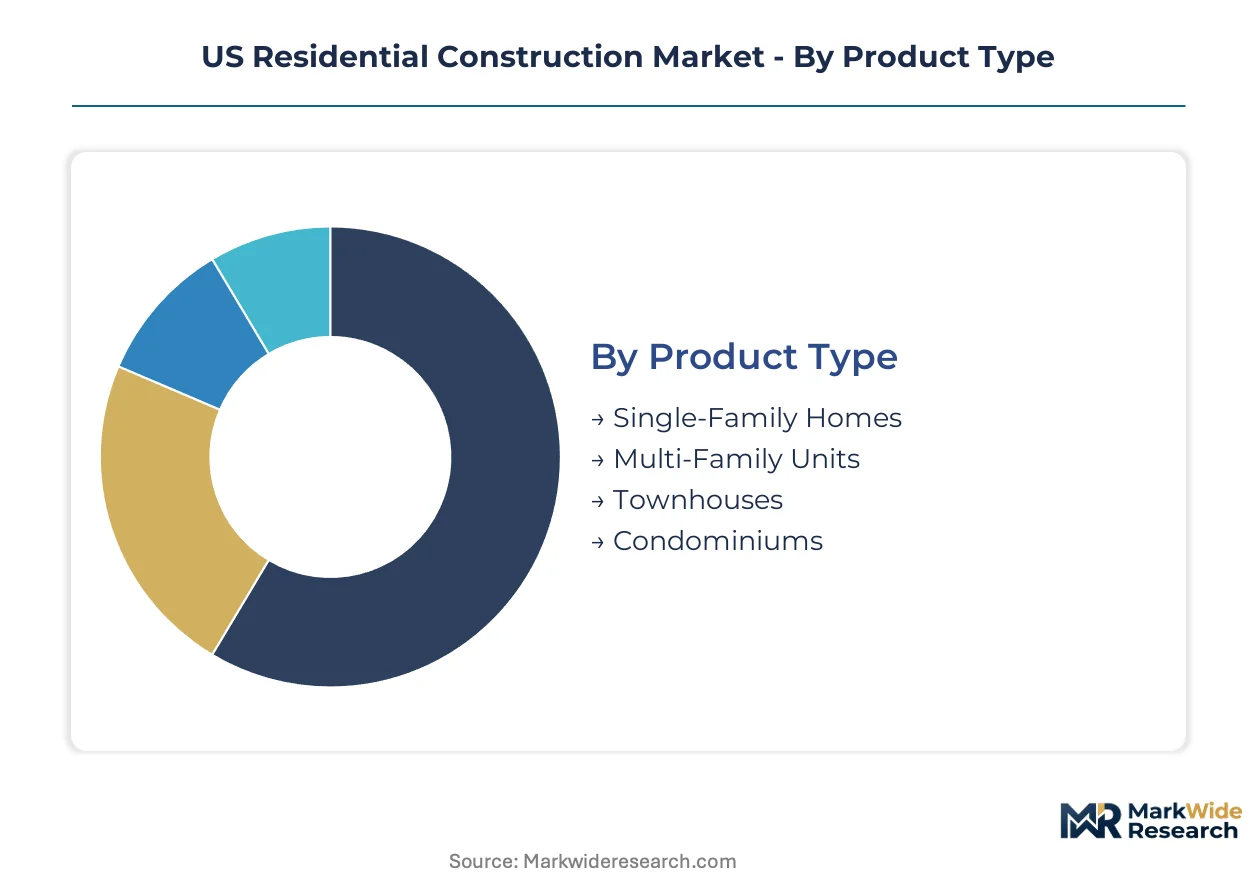
US residential construction segments along four distinct axes that determine builder capital allocation, regulatory exposure, and margin capture. FHA lending criteria, IECC adoption timelines, and local zoning density requirements fragment product strategies across these dimensions.
Product Type:
Regulatory differentiation separates single-family from attached housing through FHA loan limits and municipal density bonuses.
- Single-Family Homes:Detached structures on individually platted lots using wood framing and concrete slab foundations. Demand concentrates in Texas and Florida Sun Belt metros where FHA down-payment assistance programs unlock first-time buyer purchasing power.
- Multi-Family Units:Structures containing five or more dwelling units sharing common walls and utility infrastructure. Apartment construction dominates in Phoenix and Austin where zoning reforms permit higher density near transit corridors.
- Townhouses:Attached single-family dwellings sharing vertical walls with separate ground-floor entries. Popular in constrained Florida land markets where lot scarcity elevates land-use efficiency.
- Condominiums:Individually owned units within multi-story structures with common area maintenance obligations. Concentrated in Arizona retirement destinations where HOA-governed amenities attract seasonal residents.
Single-family homes handle the majority of throughput; modular construction methods within multi-family are gaining share fastest.
End User:
Customer type determines financing channel, specification tier, and community absorption velocity.
- First-Time Buyers:Entry-level purchasers qualifying for FHA-insured mortgages with reduced down-payment requirements. Texas and Florida markets see concentrated activity where state assistance programs stack with federal loan products.
- Real Estate Investors:Institutional and individual buyers acquiring properties for rental income or capital appreciation. Build-to-rent operators in Arizona are absorbing entire subdivision phases before foundation pour.
- Homeowners:Move-up and relocation purchasers utilizing conventional financing with stronger credit profiles. IECC 2021 jurisdictions attract this segment through utility rebate programs that reduce total cost of ownership.
- Commercial Developers:Entities constructing residential product for sale or lease as part of mixed-use portfolios. Active in Florida urban infill where entitlement complexity rewards experienced entitlement teams.
First-time buyers anchor volume absorption; institutional investors are expanding most quickly as a share of annual starts.
Building Material:
Material selection traces directly to IECC thermal performance mandates and regional labor availability.
- Wood:Dimensional lumber and engineered wood products forming structural frames, floor systems, and roof assemblies. Dominates in Texas where framing crews remain available despite regional scarcity.
- Steel:Cold-formed steel studs and structural beams for multi-story construction and high-wind zones. Specified in Florida coastal counties where fortified construction standards exceed wood-frame capacity.
- Concrete:Cast-in-place and precast systems for foundations, podiums, and structural cores. Cross-laminated timber hybrids are displacing pure concrete in Austin mid-rise applications.
- Drywall:Gypsum wallboard for interior partition and ceiling systems across all structural types. Factory-finished panels are accelerating modular assembly timelines in Phoenix.
Wood commands the majority of structural volume; engineered wood alternatives are climbing the fastest as labor constraints bite.
Construction Design:
Design philosophy determines certification pathway, insurance premium tier, and resale velocity.
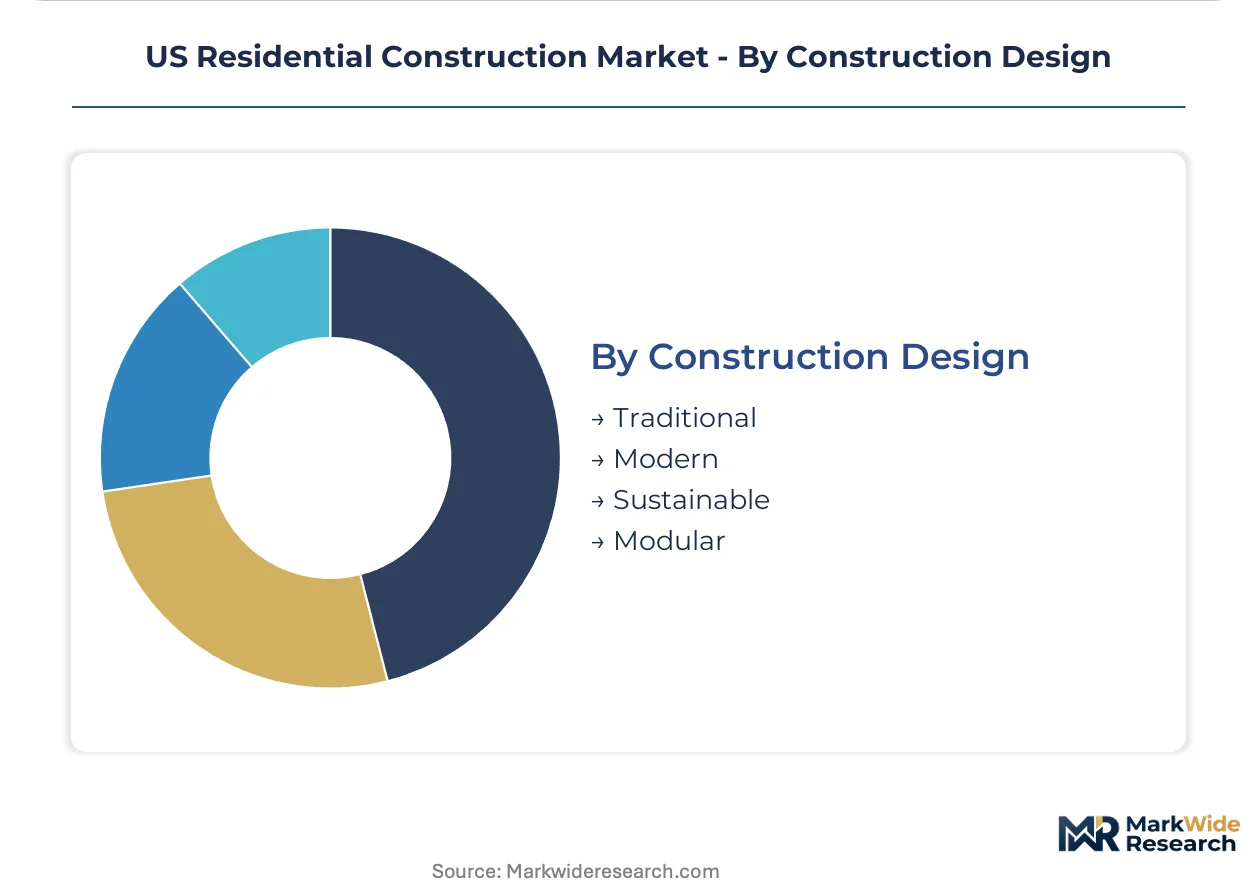
- Traditional:Conventional site-built methods with established supply chains and trade contractor networks. Prevails in markets where permitting velocity rewards predictable construction schedules.
- Modern:Open-plan layouts with minimal ornamentation and integrated smart-home infrastructure. Lennar and similar builders deploy this specification in Arizona to differentiate from commodity competition.
- Sustainable:Energy-performance certification through LEED, ENERGY STAR, or utility-specific green building programs. EPA stormwater compliance and IECC 2021 alignment drive specification in California-influenced jurisdictions.
- Modular:Factory-built volumetric units transported to site for foundation connection and finish work. Expanding in Texas metros where site-built cycle times have doubled due to electrician and HVAC technician shortages.
Traditional methods handle the majority of annual completions; modular systems show the steepest expansion trajectory as prefabrication scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian softwood lumber exports supply framing materials to Sun Belt builders, while Mexican manufactured housing components cross into Texas and Arizona markets. This North American trade corridor shapes material cost structures across the US residential construction value chain.
Southwest
Phoenix and Tucson absorb manufactured housing components from Nogales assembly plants at rates exceeding regional lumber consumption. Arizona Department of Housing down-payment assistance programs stack with FHA loan products to unlock first-time buyer demand. Electrician and HVAC technician shortages in Maricopa County cap community absorption rates regardless of permit velocity.
Southeast
Florida's fortified construction standards exceed wood-frame capacity in coastal counties, accelerating steel and concrete specification. Miami-Dade County wind-borne debris regulations mandate impact-resistant glazing that adds structural cost premiums. Jacksonville and Tampa Bay clusters concentrate production builder activity where entitlement friction remains lowest among Atlantic metros.
Texas Triangle
Houston, Dallas-Fort Worth, and Austin absorb entire subdivision phases from build-to-rent operators before foundation pour. Texas Department of Housing and Community Affairs programs layer state assistance atop federal FHA products for entry-level purchasers. Modular wall and roof systems capture share in labor-constrained San Antonio and Austin metros where site-built cycle times have doubled.
Mountain West
Las Vegas and Reno builders face NPDES construction general permit delays extending pre-construction timelines by 90-120 days. Nevada Housing Division tax credit allocations steer affordable unit production toward Clark County employment corridors. Cross-laminated timber hybrids displace pure concrete in five-over-one podiums across Salt Lake City infill sites.
Pacific Coast
California's 2021 IECC adoption mandates blower-door testing and thermal envelope commissioning across jurisdictions covering one-third of state housing starts. Los Angeles and San Diego builders pre-certify entire product lines to avoid per-unit inspection delays. Factory-finished drywall panels accelerate modular assembly timelines in Sacramento and Riverside production facilities.
US Residential Construction Market Competitive Environment
Listed leaders compete with private specialists across capital access and land position dimensions. The US residential construction market concentrates around national production builders with multi-state entitlement capabilities and regional specialists with sub-market density advantages. Three archetypes dominate: scale-driven volume producers, sustainability-focused green builders, and land-rich regional operators. M&A activity targets entitled land pipelines, while strategic partnerships with institutional rental operators convert traditional for-sale production to recurring revenue streams.
Within the scale-driven tier, D.R. Horton and Lennar Corp. exemplify national production builders with multi-division operating platforms. Meritage Homes Corp. occupies a position within the sustainability-focused archetype, representing standardized green building protocols that reduce buyer energy costs. These three companies anchor competitive positioning across entry-level single-family and build-to-rent channels where FHA lending access and utility rebate stacking determine absorption velocity.
| Leading Market Players |
|---|
| NVR |
| KB Home |
| D.R. Horton |
| Century Communities |
| Meritage Homes Corp. |
| Lennar Corp. |
| Taylor Morrison |
| Clayton Properties Group |
| PulteGroup |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lumber inventory cycles at Pacific Northwest mills concentrate pricing power among Canadian softwood exporters and reshape builder procurement strategies across Sun Belt markets. This lead-time compression elevates spot-market exposure for wood-framed product lines while tilting contract negotiations toward volume-commitment structures that lock in delivered cost certainty.
Pricing Analysis
First-time buyers anchor a three-tier pricing structure across premium, standard, and economy levels in entry-level single-family segments. Price differentiation separates IECC 2021 pre-certified homes with utility rebate eligibility from baseline code-minimum product, with green certification tiers commanding absorption premiums in California-influenced jurisdictions. Pricing pressure stems from lumber futures volatility and Pacific Northwest mill capacity constraints that compress gross margins on wood-framed lines. Real estate investors demonstrate lowest price sensitivity due to institutional capital deployment timelines, while FHA-dependent first-time buyers exhibit highest sensitivity to down-payment and closing cost structures.
Supply Chain Analysis
Port congestion at Vancouver and Prince Rupert elevates inbound logistics costs for Canadian softwood lumber destined for Texas and Florida markets. Raw material flows draw from British Columbia, Alberta, and Quebec sawmills for dimensional lumber, while engineered wood products feed from Oregon and Washington manufacturing clusters. Supply chain risk centers on Canadian softwood tariff exposure and Pacific Northwest wildfire season disruptions that constrain mill operating rates. Distribution runs through national lumberyard networks and emerging direct-to-builder digital exchanges that aggregate volume across production builder divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across municipal regulatory variance, where jurisdictional differences in IECC adoption and zoning density create sub-market niches for specialized builders. First-time buyer demand concentration in Texas and Florida Sun Belt corridors amplifies these niche formation dynamics.
For Market Incumbents: Consolidate land positions in entitled Sun Belt corridors before build-to-rent operators absorb remaining pipeline capacity. D.R. Horton and Lennar Corp. should deepen backward integration into prefabrication facilities to offset electrician and HVAC technician scarcity that caps community absorption rates. Certification investment in IECC 2021 pre-approval protocols defends margin position against inspection-delay penalties in California-influenced jurisdictions.
For New Entrants and Emerging Players: Differentiate on modular assembly capabilities in labor-constrained Austin and Phoenix metros where site-built cycle times have doubled. Target Arizona retirement destinations for condominium product where HOA-governed amenities attract seasonal residents underserved by national production builders. Pursue direct-to-builder digital procurement platforms as go-to-market angle, displacing traditional lumberyard intermediaries for commodity structural materials.
For Investors and Strategic Acquirers: Carve-out targets emerge from regional specialists with sub-market density advantages in Florida entitlement-complex urban infill. Long-term viability favors land-rich operators with multi-year entitled pipelines over speculative land-bank models. Monitor NPDES construction general permit velocity in high-growth counties as inflection indicator for pre-construction timeline compression risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Assembly Scale-Up | Factory-built wall systems offset electrician scarcity in Austin and Phoenix labor markets. |
| Green Certification Pre-Approval | IECC 2021 product line pre-certification eliminates per-unit inspection delays in California jurisdictions. |
| Build-to-Rent Channel Partnership | Institutional rental operator alliances convert traditional for-sale production to recurring revenue streams. |
| Direct Procurement Platform | Digital lumber exchanges aggregate volume across divisions to compress delivered cost variance. |
| Fortified Construction Specification | Impact-resistant glazing and roof certifications open margin pools in Florida coastal counties with carrier restrictions. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, Census Bureau construction spending data, and municipal permitting databases. Primary interviews engaged division presidents at national production builders, regional land acquisition directors, framing contractor crew leaders, and FHA lending officers at Texas and Florida financial institutions. Bottom-up community absorption rates triangulate against top-down housing start projections across the analysis window.
Segmentation dimensions modeled include product type, end-user category, building material specification, and construction design philosophy. CAGRs derive from historical permit velocity trends, mortgage rate sensitivity analysis, and regional employment growth correlations. Forecast inputs incorporate utility rebate program stacking effects and IECC adoption timeline variance across state jurisdictions.
Forecasts assume regulatory continuity in EPA NPDES permitting and OSHA fall-protection enforcement; material policy shifts would require re-modeling. Lumber tariff exposure, Federal Reserve interest rate trajectory, and municipal zoning reform velocity represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Residential Roofing Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Swimming Pool Construction Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
Germany Residential Construction Market