
 Europe Prefabricated Housing Market | 2026-2036
Europe Prefabricated Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Prefabricated Housing Market Foresight
Germany's factory-based housing capacity expansion is rewriting competitive dynamics across Northern Europe. SchwörerHaus KG leverages timber-frame engineering depth to dominate premium modular deliveries. Hanse Haus GmbH anchors its position through controlled distribution across German-speaking markets. Bouygues Construction competes via industrialized concrete panel systems scaled for French social housing programs.
Prefabricated housing encompasses factory-manufactured structural units transported to sites for rapid assembly, with wall panels typically achieving U-values below 0.15 W/m²K through integrated insulation layers. Modular Homes command the largest production volume as developers seek repeatable apartment configurations. Panelized Homes capture margin concentration in custom single-family builds where architects specify material mixes spanning wood, steel, and composite substrates. Disaster Relief applications remain structurally smaller but exhibit the fastest procurement velocity as civil defense agencies pre-position rapid-response inventory.
CE marking under the EU Construction Products Regulation governs structural safety and fire performance across member states, while national building codes in Germany enforce specific energy efficiency thresholds that factory production reliably satisfies. The EU Green Deal's renovation wave targets and France's RE2020 environmental regulations are tightening embodied carbon limits, effectively mandating low-carbon material selection and process documentation. Stakeholders must monitor how the EU AI Act's emerging conformity requirements intersect with automated manufacturing quality systems before committing capital to new production lines.
Market Dynamics
Factory automation and EU Green Deal energy mandates are compressing traditional construction timelines while elevating precision-engineered modules over site-built alternatives across Northern Europe.
Growth Catalysts
- EU Green Deal renovation targets:Mandatory energy performance upgrades in existing building stock are diverting capital toward net-zero-ready prefabricated replacements that guarantee compliance through factory-controlled assembly.
- Timber-frame engineering advances:Cross-laminated timber and glulam systems now achieve structural spans exceeding 12 meters, enabling multi-story modular apartment configurations previously restricted to concrete.
- German first-time buyer concentration:Urban housing shortages in Berlin, Munich, and Hamburg are funneling mortgage-qualified households toward certified modular suppliers with guaranteed delivery timelines.
Market Restraints
- Cross-laminated timber supply concentration:Austrian and Nordic sawmill capacity limits are creating input bottlenecks for premium timber-frame producers, extending order backlogs beyond 14 months.
- Transportation cost volatility:Oversized module haulage faces diesel price sensitivity and driver shortages on intra-EU routes, eroding the cost advantage of centralized factory production for distant sites.
- Site-built concrete substitution:Established masonry contractors in Southern Europe continue to underbid modular alternatives where energy codes remain less stringent and labor costs suppress factory premiums.
Strategic Opportunities
- Polish and Romanian manufacturing expansion:Lower labor costs and proximity to German demand corridors position Central European greenfield factories to capture margin from Western European incumbents.
- Disaster relief pre-positioning contracts:Civil defense agencies in earthquake-prone Italy and flood-exposed Belgium are tendering multi-year rapid-response housing reserves with 72-hour deployment requirements.
- France RE2020 embodied carbon limits:The regulation's lifecycle carbon accounting favors timber and bio-based insulation modules, creating procurement preference for low-carbon factory producers in social housing tenders.
Industry Challenges
- Building information modeling integration:Architects and factory engineers operate on incompatible software platforms, forcing manual translation of design specifications and introducing dimensional errors during module fabrication.
- CE marking timeline compression:National notified bodies face inspection backlogs exceeding eight months for novel composite wall systems, delaying market entry for innovative thermal envelope products.
- Site crane coordination complexity:Just-in-time module delivery requires precise alignment between factory output, transport logistics, and foundation readiness, with weather disruptions cascading through entire project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Prefabricated Housing Market |
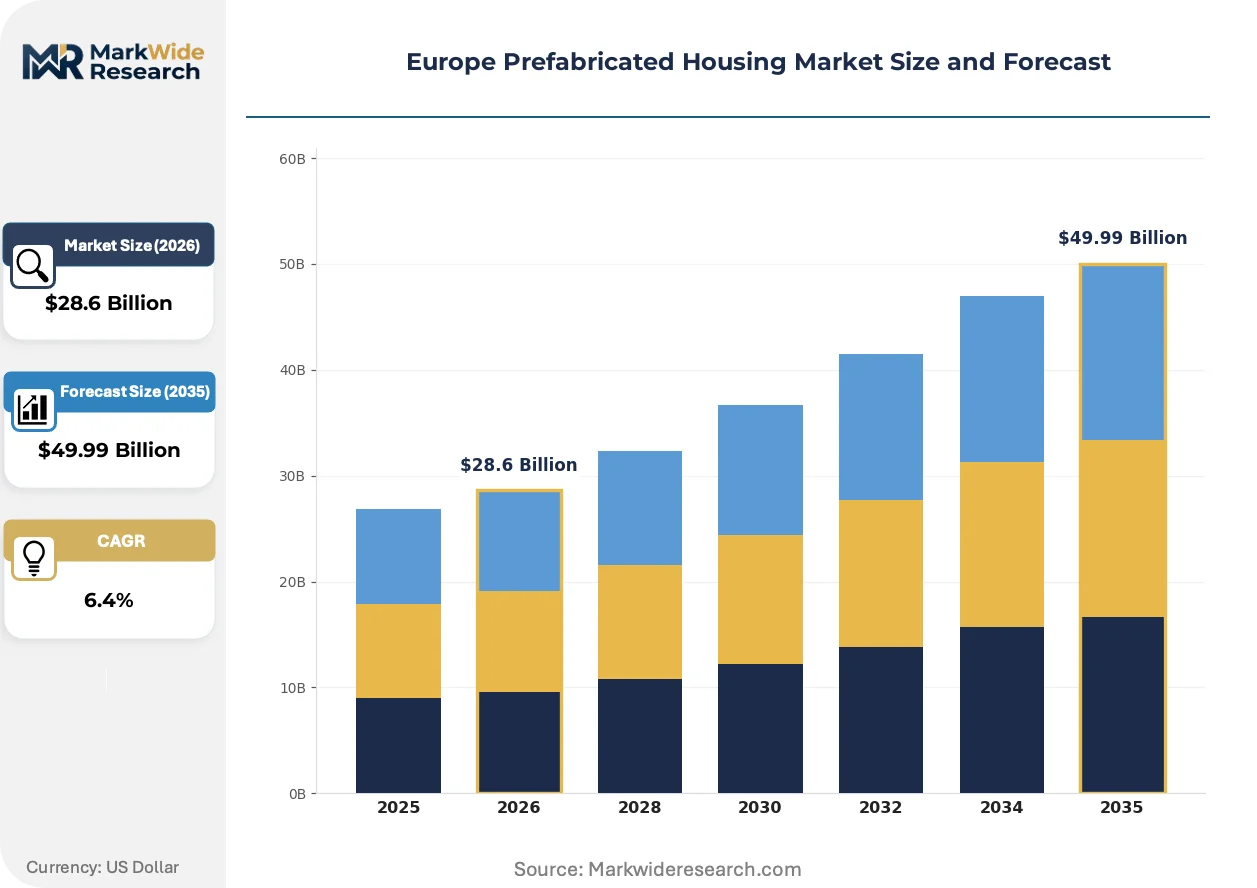
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Pre-Cut Homes, Tiny Houses Material: Wood, Steel, Concrete, Composite Application: Residential, Temporary Housing, Remote Areas, Disaster Relief End User: Individuals, Developers, Government, NGOs |
| Companies Covered | SchwörerHaus KG, Hanse Haus GmbH, WeberHaus GmbH & Co., Bien-Zenker GmbH, ScanHaus Marlow GmbH, Skanska AB, Bouygues Construction, Danwood S.A., FingerHaus GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Prefabricated Housing Market Shifts & Advancements
Digital fabrication and regulatory carbon accounting are converging to redefine competitive advantage around precision, speed, and documented environmental performance rather than traditional material cost minimization.
Robotic timber cutting and CNC milling is collapsing the customization cost premium that historically separated prefabricated housing from architect-designed site-built homes. Scandinavian developers now specify one-off facade geometries at volumes below 50 units without penalty pricing. The technology is collapsing the market distinction between bespoke and production housing, forcing mid-tier factories to automate or retreat to commodity segments.
France's RE2020 environmental regulation mandates whole-building lifecycle carbon calculations from 2025, embedding factory producers with process documentation advantages over site-built competitors. Industrial facilities already meter embodied carbon per module, while masonry supply chains lack comparable traceability. Social housing authorities in Lyon and Marseille are prioritizing tenders from suppliers with verified Environmental Product Declarations.
Direct-to-developer digital platforms are displacing traditional construction intermediary networks across Germany and the Netherlands. Factory producers now maintain configurators that generate binding quotes from uploaded site plans, compressing pre-construction phases from months to days. Municipal housing corporations in Amsterdam and Rotterdam are piloting procurement through these interfaces, bypassing general contractors entirely.
Europe Prefabricated Housing Market Segmentation
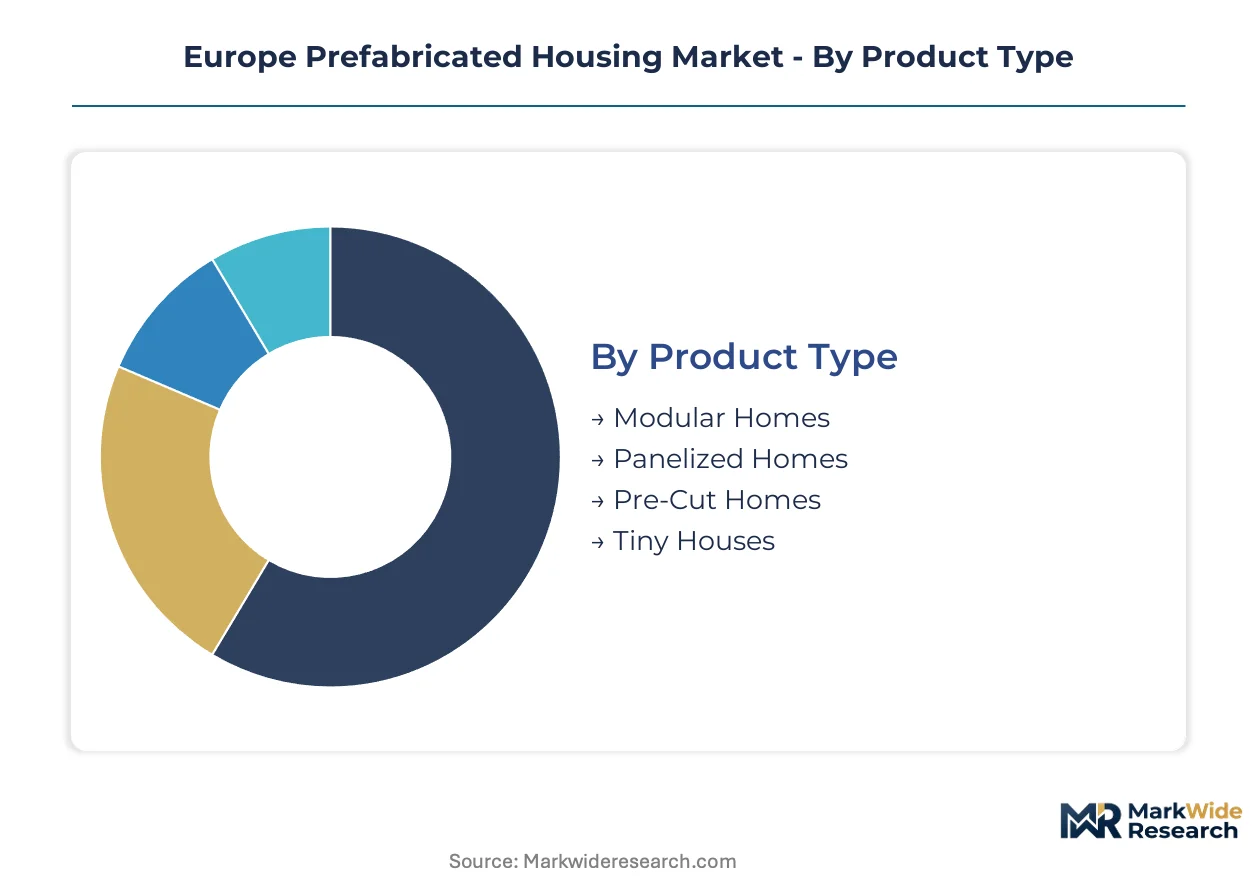
Segmentation in Europe's prefabricated housing market reveals how factory production methods, material choices, and procurement channels create distinct competitive arenas. Each dimension carries different margin structures, regulatory exposure, and capital intensity requirements that shape supplier positioning across Northern and Southern Europe.
Product Type:
Mature volumetric systems dominate Northern European markets while emerging formats test price-sensitive Southern European adoption.
- Modular Homes:Three-dimensional volumetric units factory-fitted with MEP systems achieve U-values below 0.15 W/m²K through integrated thermal envelopes. German developers in Berlin and Munich specify these for multi-story apartment blocks where RE2020 energy compliance is mandatory and site labor costs are prohibitive.
- Panelized Homes:Flat-packed wall and roof panels shipped to sites for crane-assisted assembly enable architect-specified geometries previously restricted to site-built construction. Scandinavian single-family builders leverage robotic timber cutting to deliver customized facades at production economics, capturing margin in premium suburban markets around Stockholm and Oslo.
- Pre-Cut Homes:Precision-milled timber packages with numbered components for on-site assembly serve cost-conscious rural buyers in Poland and Romania where transportation infrastructure limits module haulage.
- Tiny Houses:Sub-50 square meter mobile units on wheeled chassis target remote Alpine tourism operators and seasonal agricultural workers in Spain's Extremadura region.
Modular Homes handle the majority of throughput; Tiny Houses are gaining share fastest among alternative dwelling formats.
Material:
Cost tier stratification separates premium bio-based systems from commodity mineral alternatives with divergent carbon accounting treatment under EU Green Deal frameworks.
- Wood:Cross-laminated timber and glulam systems from Austrian and Nordic sawmills now span 12-meter structural bays enabling mid-rise modular construction. French social housing tenders under RE2020 award procurement preference to timber-framed suppliers with verified Environmental Product Declarations.
- Steel:Cold-formed galvanized framing dominates multi-story student housing and co-living developments in Dutch cities where fire resistance ratings exceed timber capabilities and floor-to-floor heights are compressed.
- Concrete:Precast panel systems from Bouygues Construction and similar industrialized concrete specialists anchor French social housing programs where acoustic separation and thermal mass are specified.
- Composite:Glass-reinforced polymer and fiber-cement hybrids serve coastal Mediterranean markets in Portugal and Greece where salt corrosion degrades conventional steel and untreated timber.
Wood commands the highest volume across factory output; Composite materials are expanding most quickly in corrosion-exposed coastal applications.
Application:
Customer type concentration varies sharply between permanent residential installations and contingency procurement with radically different sales cycle dynamics.
- Residential:Permanent owner-occupied and rental housing constitutes the core revenue base across German-speaking markets where mortgage lenders now recognize certified modular suppliers for standard construction financing.
- Temporary Housing:Construction site accommodation and event infrastructure modules serve cyclical demand from infrastructure projects including Germany's rail network expansion and Olympic preparation clusters.
- Remote Areas:Off-grid cabin systems with integrated solar and composting sanitation address tourism operators in Scottish Highlands and Norwegian fjord regions beyond utility connection reach.
- Disaster Relief:Pre-positioned rapid-response inventory held under civil defense contracts in earthquake-prone Italy and flood-exposed Belgium requires 72-hour deployment capability from standby factory capacity.
Residential absorbs the dominant share of production capacity; Disaster Relief exhibits the steepest expansion trajectory as climate adaptation budgets harden across EU member states.
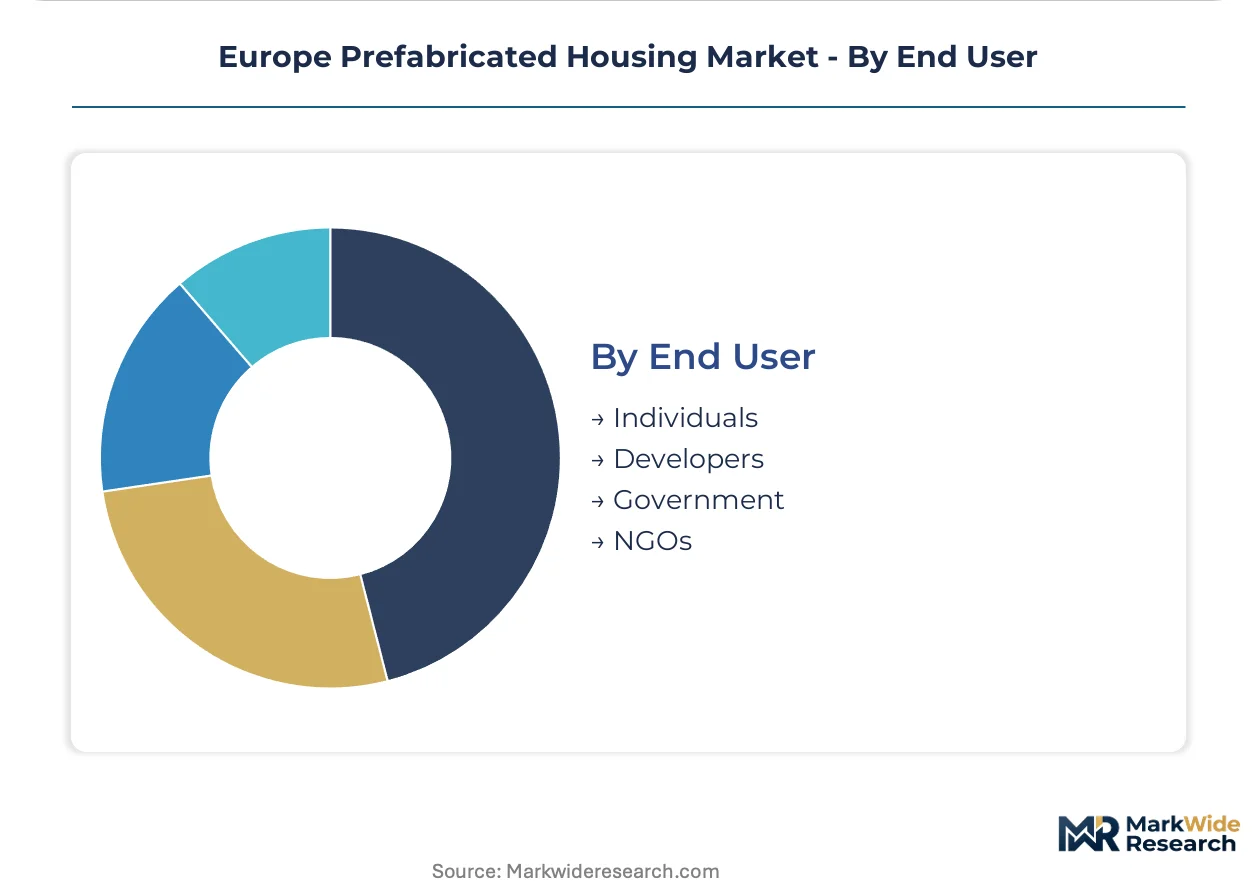
End User:
Procurement authority concentration determines contract scale and specification complexity, from individual customization to standardized institutional tendering.
- Individuals:First-time buyers and young families in German urban corridors drive certified modular adoption where guaranteed delivery timelines contrast with site-built uncertainty.
- Developers:Multi-unit residential builders in Amsterdam and Rotterdam pilot direct-to-factory digital procurement platforms that bypass general contractor intermediaries entirely.
- Government:Municipal housing corporations and social housing authorities in Lyon and Marseille mandate Environmental Product Declarations and lifecycle carbon accounting in tender specifications.
- NGOs:Refugee accommodation and affordable housing nonprofits in Greece and Italy operate on constrained capital cycles favoring lease-purchase financing structures over outright module acquisition.
Developers control the largest contract values; Government procurement is climbing fastest as social housing programs industrialize under EU Green Deal renovation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory capacity clusters along the Rhine corridor and Nordic timber belt concentrate supply-side leverage for cross-border delivery into housing-deficit urban centers. German and Scandinavian producers dominate volumetric output while Southern European markets remain structurally underpenetrated by modular systems.
Germany
First-time buyers in Berlin, Munich, and Hamburg are funneling mortgage capital toward certified modular suppliers with guaranteed delivery timelines. The national building code enforces energy efficiency thresholds that factory production reliably satisfies through integrated thermal envelopes. SchwörerHaus KG and Hanse Haus GmbH anchor industrial clusters in Baden-Württemberg and Lower Saxony where timber-frame engineering depth supports premium volumetric deliveries.
France
Social housing authorities in Lyon and Marseille are tendering industrialized units under RE2020 environmental regulations mandating lifecycle carbon accounting. Bouygues Construction scales precast concrete panel systems for municipal programs where acoustic separation and thermal mass are specified. The Île-de-France corridor around Paris concentrates demand for mid-rise modular apartments compliant with tightening embodied carbon limits.
Sweden
Robotic timber cutting enables architect-specified facade geometries at production economics for suburban markets around Stockholm and Oslo. Cross-laminated timber and glulam systems from Nordic sawmills achieve structural spans exceeding 12 meters for multi-story configurations. Skanska AB leverages industrialized construction platforms to compress project timelines for municipal housing corporations piloting direct-to-factory procurement.
Poland
Lower labor costs and proximity to German demand corridors position Central European greenfield factories to capture margin from Western European incumbents. Pre-cut timber packages with numbered components serve cost-conscious rural buyers where transportation infrastructure limits module haulage. Manufacturing expansion in Silesia and Greater Poland targets cross-border supply into Berlin and Prague housing markets.
Italy
Civil defense agencies in earthquake-prone regions are tendering multi-year rapid-response housing reserves with 72-hour deployment requirements. Site-built masonry contractors continue to underbid modular alternatives where energy codes remain less stringent and labor costs suppress factory premiums. Northern industrial clusters around Milan and Turin test timber-frame adoption for Alpine tourism operators seeking off-grid cabin systems.
Europe Prefabricated Housing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying engineered timber, insulation substrates, and facade assemblies. The vendor base stratifies across three tiers: premium timber-frame engineers with proprietary thermal envelope systems, mid-scale volumetric assemblers serving social housing tenders, and regional panelized producers competing on delivery speed. Strategic moves concentrate on backward integration into cross-laminated timber supply and automated manufacturing quality systems aligned with emerging EU AI Act conformity requirements.
Among German fabricators, SchwörerHaus KG, Hanse Haus GmbH, and WeberHaus GmbH & Co. occupy positions within the premium modular tier where timber-frame engineering depth and controlled distribution networks create defensive moats. These GmbH-structured entities exemplify the archetype of family-held engineering specialists that dominate certified volumetric deliveries across German-speaking markets. Their positioning reflects a broader pattern where geographic origin and corporate form signal capability depth in factory-controlled energy performance compliance.
| Leading Market Players |
|---|
| SchwörerHaus KG |
| Hanse Haus GmbH |
| WeberHaus GmbH & Co. |
| Bien-Zenker GmbH |
| ScanHaus Marlow GmbH |
| Skanska AB |
| Bouygues Construction |
| Danwood S.A. |
| FingerHaus GmbH |
| Others |
Supply & Pricing Matrix
Undercapacity in Nordic cross-laminated timber mills is compressing order backlogs beyond fourteen months and forcing German modular producers to absorb input premiums or pass through escalation clauses to municipal housing authorities tendering under RE2020 mandates.
Pricing Analysis
France's RE2020 environmental regulation dictates the pricing tier structure across the European prefabricated housing market. Pricing stratifies across premium timber-frame systems with verified Environmental Product Declarations, standard steel-framed volumetric units for Dutch student housing, and economy pre-cut timber packages for Polish rural buyers. Price differentiation centers on certification grade and embodied carbon documentation, with RE2020-compliant modules commanding procurement preference in Lyon and Marseille social housing tenders. Cost compression in the economy tier is intensifying because Central European greenfield factories leverage lower labor costs to underbid Western European incumbents on cross-border deliveries into Berlin and Prague markets. Municipal housing corporations exhibit the highest price sensitivity due to fixed budget allocations, while Alpine tourism operators seeking off-grid cabin systems show the least.
Supply Chain Analysis
EU dual-use export controls on advanced timber processing equipment limit technology transfer to non-member manufacturing jurisdictions and constrain capacity expansion outside established Nordic and Austrian sawmill clusters. Supply concentrates in Germany, Austria, and Sweden for engineered timber inputs, with Polish and Romanian factories drawing from these upstream sources for cross-laminated timber and glulam systems. Raw material dependencies rest on Nordic spruce and pine feedstock, galvanized steel coil from German rolling mills, and bio-based insulation substrates from French agricultural waste processors. Single-source vulnerability runs through Austrian sawmill capacity for premium cross-laminated timber grades specified in multi-story modular configurations. Distribution runs through direct-to-developer digital platforms that bypass general contractor intermediaries across Amsterdam and Rotterdam procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as direct-to-factory digital procurement interfaces displace traditional construction intermediary networks across Northern European municipal housing corporations.
For Market Incumbents: Insulate timber-frame engineering margins by securing captive supply contracts with Nordic sawmill operators before Austrian capacity constraints harden into structural shortages. Accelerate backward integration into cross-laminated timber production in Baden-Württemberg and Lower Saxony industrial clusters to defend against Central European greenfield entrants exploiting labor cost differentials. Prioritize CE marking pre-submission for novel composite wall systems to circumvent notified body inspection backlogs exceeding eight months.
For New Entrants and Emerging Players: Disaster relief pre-positioning contracts in earthquake-prone Italy and flood-exposed Belgium represent the most penetrable entry point for rapid-response housing reserves with seventy-two-hour deployment requirements. Polish and Romanian manufacturing greenfields targeting German demand corridors offer second-mover advantage through lower labor costs and proximity to Berlin and Prague housing markets. Lead with lease-purchase financing structures tailored to Greek and Italian NGO capital cycles rather than outright module acquisition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated timber processing lines as robotic cutting and CNC milling collapse customization cost premiums and force mid-tier factories to automate or retreat to commodity segments. Acquisition targets should prioritize family-held German GmbH-structured engineering specialists with proprietary thermal envelope systems and controlled distribution networks across German-speaking markets. Monitor CE marking timeline compression for novel composite wall systems as an early signal of regulatory friction affecting innovative thermal envelope product market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cross-Laminated Timber Supply | Captive Nordic sawmill capacity insulates German producers from Austrian input bottlenecks extending order backlogs. |
| Direct-to-Developer Digital Platform Deployment | Amsterdam and Rotterdam municipal housing corporations pilot procurement interfaces bypassing general contractor intermediaries entirely. |
| Automated Manufacturing Quality System Investment | EU AI Act emerging conformity requirements intersect with factory robotics before capital commitment to new production lines. |
| Disaster Relief Pre-Positioning Contract Capture | Italian civil defense agencies tender multi-year rapid-response housing reserves with seventy-two-hour deployment requirements. |
| Environmental Product Declaration Certification | Lyon and Marseille social housing authorities mandate verified lifecycle carbon accounting in tender specifications under RE2020. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with factory production managers at German and Scandinavian modular producers, municipal housing procurement officers in Lyon and Marseille, civil defense agency logistics directors in Italy and Belgium, and timber-frame engineering specialists at Austrian and Nordic sawmill operators. Secondary validation drew from EU Construction Products Regulation filings, French RE2020 regulatory guidance documents, German national building code energy efficiency thresholds, and CE marking notification body inspection records. Bottom-up capacity assessments at named factory clusters were triangulated against top-down demand modeling from social housing tender databases.
Calibration against historical production volumes and announced capacity expansions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material substrate, application category, and end-user procurement authority. CAGRs were derived from slope analysis of segment-level growth trajectories. Industry-specific forecast inputs incorporated cross-laminated timber supply lead times and RE2020 embodied carbon limit phase-in schedules.
Practitioners should monitor Nordic sawmill capacity utilization rates and EU AI Act conformity guidance publication for early signals of input cost pressure and regulatory compliance burden shifts. Cross-checking against German federal building permit issuance data and French social housing tender award volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Latin America Residential Construction Market
Residential Construction
UK Residential Construction Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Europe Residential Construction Market
Residential Construction
North America Prefabricated Housing Market
Residential Construction
US Residential Remodeling Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
Siding Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
US Residential Construction Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Austria Prefabricated Housing Market