
 Global Manufactured Homes Market | 2026-2036
Global Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Manufactured Homes Market Foresight
Modular bundling of site preparation, transport, and installation services is expanding buyer choice beyond standalone unit purchases. Clayton Homes leverages captive financing and retail dealership networks to control the full ownership pathway. Skyline Champion Corporation anchors its position through manufacturing scale across multiple US production facilities. Cavco Industries differentiates via specialized product lines targeting both entry-level and retirement-community segments.
Manufactured homes are factory-built residential structures constructed on permanent chassis, designed for transport to sites in one or more sections, with HUD Code Title 6 setting minimum standards for design, construction, and performance. Double-wide units dominate volume shipments due to their spatial equivalence with site-built homes at substantially lower cost per square foot. Single-wide configurations retain importance in rural markets and mobile home park infill where lot dimensions constrain placement. Steel frame construction leads material selection for structural durability and transport tolerance, though wood frame alternatives compete in certain climate zones.
The Department of Housing and Urban Development enforces the Manufactured Home Construction and Safety Standards, while the Environmental Protection Agency regulates formaldehyde emissions in composite wood products used for interior finishes. State-level installation and siting requirements create additional compliance layers that manufacturers must navigate for market access. Stakeholders should monitor evolving federal energy-conservation standards and local zoning reforms that could unlock or restrict placement opportunities across jurisdictions.

Market Dynamics
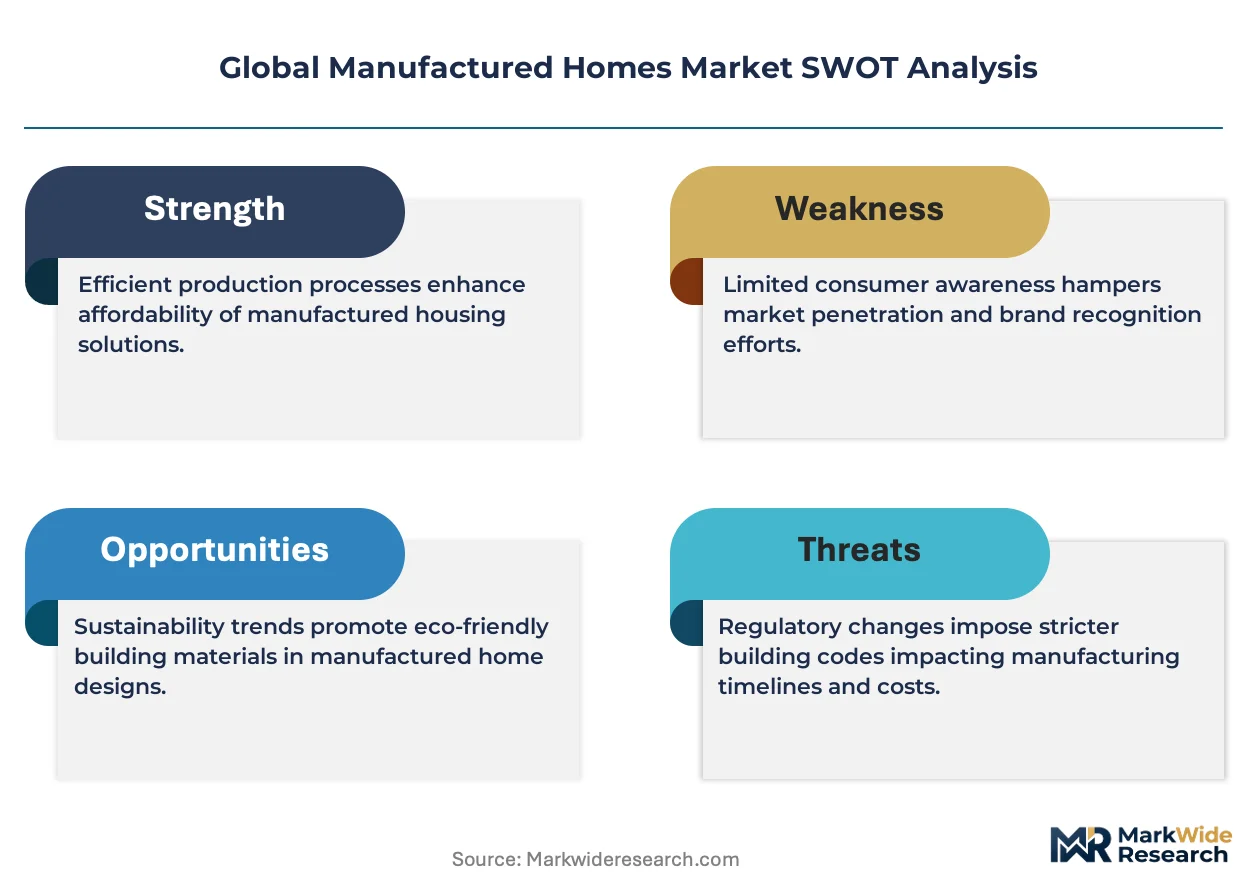
HUD Code Title 6 energy-efficiency thresholds are compressing manufacturing margins while simultaneously unlocking placement opportunities in jurisdictions that previously restricted factory-built dwellings. This regulatory compression is forcing producers to absorb compliance costs or exit non-compliant markets entirely.
Growth Catalysts
- Sun Belt migration patterns:Florida, Texas, and Arizona are absorbing disproportionate domestic relocation flows, concentrating demand for affordable detached housing in jurisdictions with permissive zoning for manufactured dwellings.
- HUD Code Title 6 updates:The Department of Housing and Urban Development's tightened thermal envelope standards are improving product legitimacy among municipal planners previously hostile to factory-built housing.
- Cross-laminated timber integration:Engineered wood products are displacing steel framing in certain climate zones, reducing transport weight and expanding design flexibility for multi-section configurations.
Market Restraints
- Lumber and steel input volatility:Structural material costs fluctuate with commodity cycles, compressing margin predictability for producers locked into fixed-price retail contracts.
- Transport radius economics:Factory-to-site logistics costs escalate beyond 500-mile radii, fragmenting production into regional silos that forfeit national scale advantages.
- Site-built substitution in appreciating markets:Conventional construction regains cost competitiveness when land values climb sufficiently to absorb higher per-unit construction expenses.
Strategic Opportunities
- India affordable housing shortfall:The country's national housing regulator has identified factory-built solutions as eligible for subsidized credit under PMAY-Urban, opening import or licensing pathways for compliant foreign producers.
- Community land-lease models:Purpose-built retirement enclaves are converting from site-built to manufactured product, accepting shorter depreciation schedules in exchange for amenity bundling and maintenance outsourcing.
- Modular-service bundling:Turnkey packages combining unit, transport, foundation, and utility connection are capturing buyers who previously self-coordinated these elements.
Industry Challenges
- Installation contractor certification gaps:State-level siting requirements vary in stringency, creating compliance failures when uncertified crews execute foundation or anchoring work.
- Utility interconnection standardization:Local electrical and plumbing inspection regimes impose non-uniform connection protocols, delaying occupancy permits and triggering warranty disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Manufactured Homes Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wide, Double-Wide, Triple-Wide, Modular, Park Model Construction Material: Steel Frame, Wood Frame, Composite Panels, Vinyl Siding, Fiber Cement End User: Residential Occupants, Seasonal Dwellers, Affordable Housing Developers, Vacation Property Owners, Mobile Home Parks Distribution Channel: Direct Sales, Dealers & Distributors, Online Platforms, Real Estate Agencies, Auction Sales |
| Companies Covered | Clayton Homes, Skyline Champion Corporation, Cavco Industries, Champion Home Builders, Palm Harbor Homes, Fleetwood Homes, Karmod Prefabricated Technologies, Adria Mobil, Redman Homes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Manufactured Homes Market Shifts & Advancements
Factory automation and digital design tools are compressing production cycles while enabling mass customization previously incompatible with assembly-line economics. These capabilities are rewriting competitive rules around lead time and configuration flexibility.
Building-integrated photovoltaics and smart-home pre-wiring are rewriting how manufacturers position product against site-built alternatives. Retirement-community developers in Arizona and Florida are specifying these features as standard, not optional, compressing the upgrade cycle from post-purchase retrofit to factory installation. This shift is collapsing the historical price gap between manufactured and conventional housing at the point of sale.
The Environmental Protection Agency's formaldehyde emission standards for composite wood products are tightening interior finish specifications. Manufacturers sourcing particleboard and medium-density fiberboard must now certify compliance through third-party testing, adding documentation burden but improving indoor air quality credentials for health-conscious buyers. European producers exporting to the United States face parallel REACH obligations that complicate cross-border supply chains.
Buyer aggregation through online configurators is displacing traditional dealership walk-ins. First-time purchasers in Texas and Georgia are completing specification and financing pre-approval digitally before visiting physical display centers, compressing the sales cycle and reducing field staff overhead. This channel migration is most pronounced among buyers under 45 seeking primary residences rather than secondary or retirement dwellings.
Global Manufactured Homes Market Segmentation
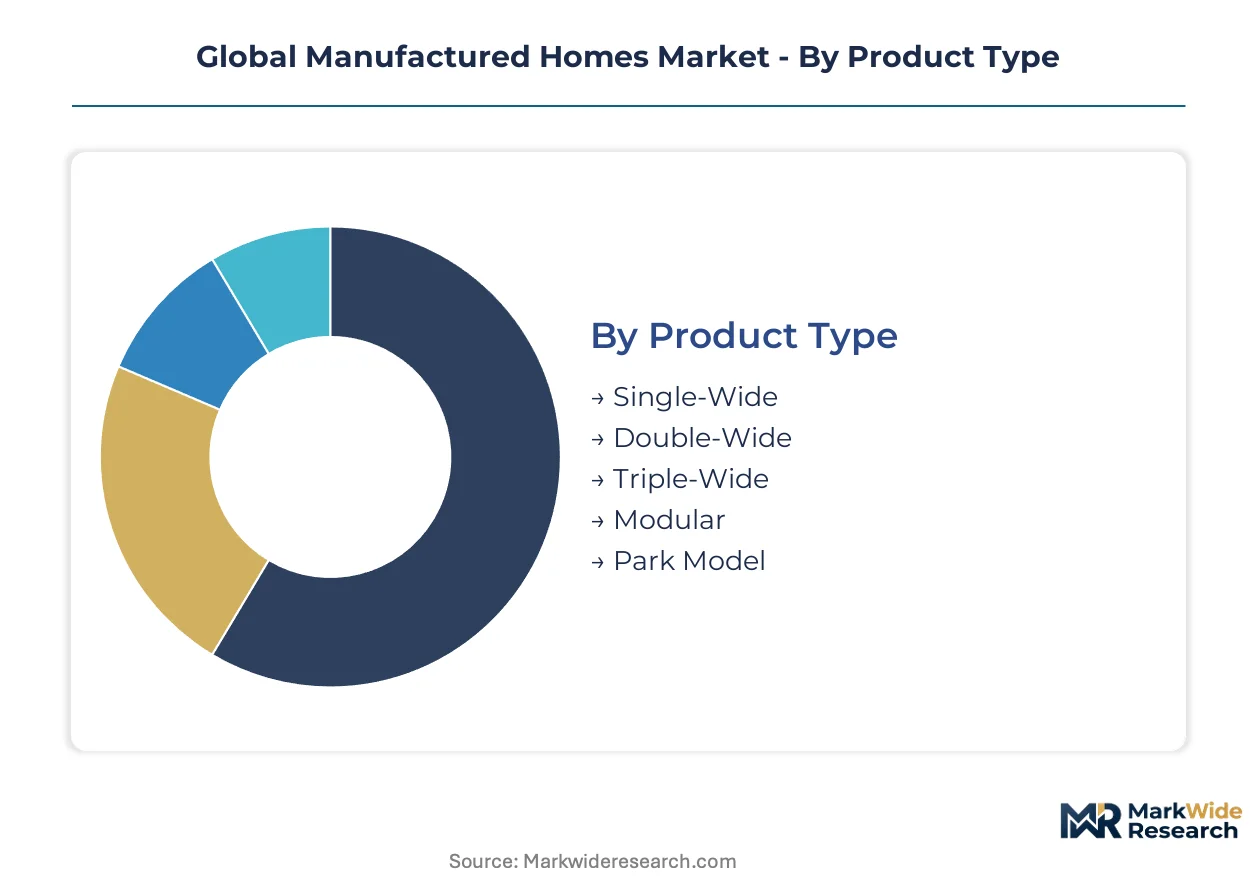
Segmentation in manufactured housing reveals how factory-built dwellings compete across distinct buyer calculus—spatial requirements, structural permanence, and financing access. Each dimension maps to different margin structures and regulatory exposure, shaping where producers concentrate R&D and distribution investment.
Product Type:
The volume-premium split in manufactured housing pivots on section count and transport logistics, with double-wide configurations anchoring mainstream affordability while modular designs command price premiums through site-built equivalence.
- Single-Wide:Factory-built units constructed in one transportable section, typically 14-18 feet wide. Demand concentrates in rural Texas and Arizona mobile home park infill where lot dimensions constrain placement and entry-level buyers prioritize payment minimization over spatial expansion.
- Double-Wide:Two-section configurations joined on-site, delivering 1,000-2,300 square feet of living space. Florida retirement-community developers specify these as standard inventory, accepting shorter depreciation schedules in exchange for amenity bundling and maintenance outsourcing that conventional construction cannot match.
- Triple-Wide:Three-section luxury configurations exceeding 2,500 square feet. Custom estate applications in high-appreciation Sun Belt counties.
- Modular:Factory-built to local building codes rather than HUD Title 6, enabling multi-story designs and permanent foundation anchoring. Premium suburban infill in jurisdictions with restrictive zoning for traditional manufactured housing.
- Park Model:Compact recreational units under 400 square feet, designed for seasonal occupancy. Vacation property clusters in Arizona and Florida retirement enclaves.
Today's leader: Double-Wide. Tomorrow's challenger: Modular.
Construction Material:
Material selection in manufactured housing trades off transport durability against climate-zone performance, with steel and wood framing dominating structural decisions while exterior finishes respond to local aesthetic regulation and maintenance cost sensitivity.
- Steel Frame:Galvanized steel chassis and wall framing engineered for highway transport stress and seismic tolerance. Dominates production across Texas and Arizona facilities where thermal expansion management and structural longevity outweigh first-cost premiums.
- Wood Frame:Dimensional lumber or engineered wood products replacing steel in certain climate zones. Gaining share fastest in Pacific Northwest and upper Midwest production where reduced transport weight and design flexibility for multi-section configurations offset termite vulnerability.
- Composite Panels:Structural insulated panels combining OSB sheathing with rigid foam cores. Emerging in energy-code-stringent jurisdictions.
- Vinyl Siding:PVC exterior cladding offering color retention and minimal maintenance. Standard specification for entry-level inventory.
- Fiber Cement:Cementitious composite siding replicating wood grain with fire resistance and hail tolerance. Premium upgrade path in wildfire-prone Colorado and California counties.
Steel Frame commands current volume. Wood Frame is climbing the fastest as cross-laminated timber integration matures.
End User:
Buyer type segmentation exposes divergent decision criteria—primary residence occupants prioritize monthly payment affordability while developers optimize for installation speed and portfolio standardization.
- Residential Occupants:Primary residence buyers seeking ownership at payment levels below equivalent site-built rent. Florida and Texas first-time purchasers under 45 complete specification digitally before dealership visits, compressing sales cycles.
- Seasonal Dwellers:Snowbird households maintaining manufactured winter residences in Arizona and Florida while retaining northern site-built homes. Demand seasonal climate systems and low-maintenance exterior specifications.
- Affordable Housing Developers:Institutional buyers scaling HUD-code compliant inventory for subsidized and workforce housing portfolios. Scaling orders under Department of Housing and Urban Development updated construction standards.
- Vacation Property Owners:Recreational buyers seeking lake and mountain retreat dwellings. Park model and single-wide specifications dominate.
- Mobile Home Parks:Land-lease community operators acquiring inventory for rental or rent-to-own programs. Concentrated across Sun Belt states with permissive zoning.
Residential Occupants anchor present demand. Affordable Housing Developers represent the steepest expansion trajectory as federal and state subsidy programs expand factory-built eligibility.
Distribution Channel:
Channel structure in manufactured housing reflects the complexity of coordinating factory production with site-specific installation, creating intermediation opportunities for parties managing transport, foundation, and utility connection.
- Direct Sales:Manufacturer-owned retail networks controlling financing origination and installation coordination. Clayton Homes leverages captive finance subsidiaries to capture full ownership pathway margin.
- Dealers & Distributors:Independent retail networks displaying inventory and managing buyer qualification. Skyline Champion Corporation anchors position through exclusive dealership relationships across multiple production facilities.
- Online Platforms:Digital configurators enabling specification and financing pre-approval before physical display center visits. Expanding most quickly among under-45 buyers in Texas and Georgia.
- Real Estate Agencies:Traditional brokerage participation in manufactured home resale and land-home package transactions. Concentrated in appreciating Sun Belt markets.
- Auction Sales:Distressed inventory and repossession disposition through specialized manufactured housing auctioneers. Liquidation pathway for non-performing paper.
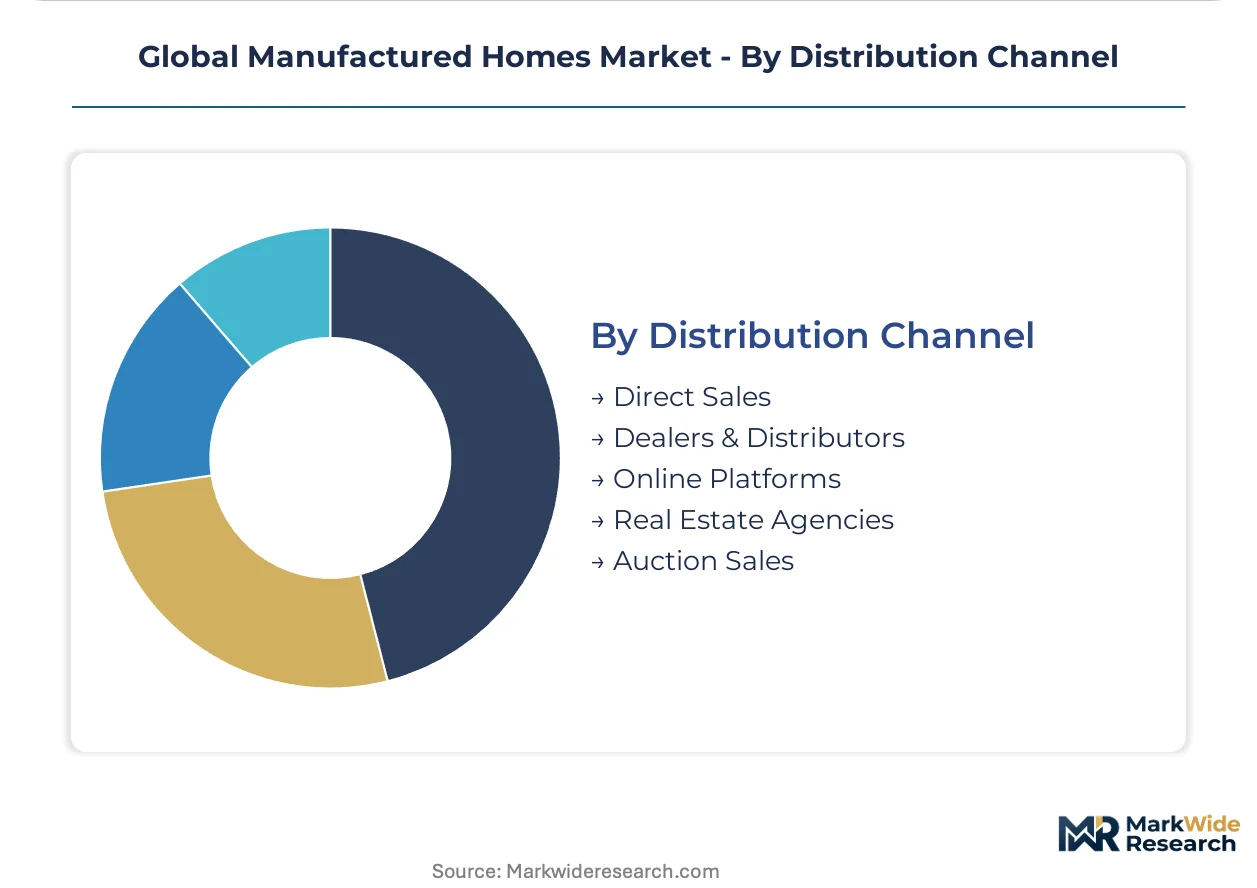
Dealers & Distributors maintain channel dominance. Online Platforms are gaining share fastest as digital-native buyers enter the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory-built housing originated in the United States during the postwar period, with HUD Code standardization creating the regulatory template later adopted or adapted by other national jurisdictions. Production scale and regulatory maturity in North America established the foundational economics that subsequent regional markets modified for local building codes and climate conditions.
United States
Sun Belt migration into Florida, Texas, and Arizona concentrates demand for detached affordable housing in jurisdictions with permissive zoning for manufactured dwellings. The Department of Housing and Urban Development enforces Manufactured Home Construction and Safety Standards while tightening energy-efficiency thresholds under updated Title 6 provisions. Production clusters across the Southeast and Southwest supply double-wide configurations to retirement-community developers accepting shorter depreciation schedules.
Canada
Provincial building codes in British Columbia and Alberta increasingly recognize factory-built alternatives for workforce housing shortfalls in resource-extraction communities. Natural Resources Canada administers energy-efficiency labeling requirements that parallel but exceed baseline HUD thermal envelope standards. Manufacturing concentration in Ontario and Quebec serves both domestic placement and cross-border export to northern US states with similar climate-loading requirements.
Germany
Prefabricated timber-frame construction commands premium positioning in energy-efficiency-conscious markets, with factory-built methods displacing conventional construction in Bavarian and Baden-Württemberg suburban infill. The KfW development bank channels subsidized credit toward compliant units meeting EnEV thermal performance standards. Industrial concentration in southern Länder supplies modular configurations to neighboring Swiss and Austrian markets with compatible regulatory frameworks.
India
The national housing regulator has identified factory-built solutions as eligible for subsidized credit under PMAY-Urban, opening import or licensing pathways for compliant foreign producers. State-level building bye-laws in Maharashtra and Karnataka are relaxing placement restrictions for disaster-relief and urban slum rehabilitation applications. Manufacturing partnerships in Gujarat and Tamil Nadu are scaling steel-frame production for affordable housing developers targeting tier-two city expansion corridors.
Australia
Granny flat legislation in New South Wales and Queensland is normalizing factory-built ancillary dwellings as infill solutions in high-appreciation metropolitan markets. The National Construction Code mandates structural and energy performance standards administered by the Australian Building Codes Board. Production concentration in Queensland and Victoria supplies park-model and single-wide configurations to coastal retirement enclaves and mining camp accommodation contracts.
Global Manufactured Homes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across financing integration and installation-service bundling capabilities. The vendor base organizes into three tiers: vertically integrated conglomerates controlling captive finance and retail networks, multi-facility manufacturers scaling through exclusive dealership relationships, and regional fabricators competing on customization flexibility and local regulatory navigation. Dominant competitive moves include backward integration into component manufacturing to offset material cost volatility, and geographic expansion through acquisition of distressed production assets in high-demand Sun Belt corridors.
Within the integrated-tier, Clayton Homes exemplifies the full-ownership-pathway model combining manufacturing, retail, and finance subsidiaries. Skyline Champion Corporation and Cavco Industries occupy positions as multi-facility scale players anchoring market presence through manufacturing footprint breadth across multiple US production locations. These three entities collectively represent the structural archetypes—integrated conglomerate, scale manufacturer, and segment specialist—that define competitive positioning in factory-built residential supply.
| Leading Market Players |
|---|
| Clayton Homes |
| Skyline Champion Corporation |
| Cavco Industries |
| Champion Home Builders |
| Palm Harbor Homes |
| Fleetwood Homes |
| Karmod Prefabricated Technologies |
| Adria Mobil |
| Redman Homes |
| Others |
Supply & Pricing Matrix
Lumber and steel futures indices transmit commodity volatility directly into factory-floor cost structures, compressing margins at the economy tier while producers with captive material sourcing defend premium positioning through after-sales service bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by financing access and installation complexity. Price differentiation hinges on HUD Code energy-efficiency certification tier and geographic delivery radius from production facilities. Cost compression in the economy tier is intensifying because raw material volatility outpaces contract renegotiation cycles. First-time residential occupants in rural Texas and Arizona exhibit highest price sensitivity, while retirement-community developers in Florida absorb premiums for turnkey amenity packages.
Supply Chain Analysis
Refurbishment flows for repossessed units create secondary market inventory that competes with new production in price-sensitive segments. Manufacturing concentrates in the United States, Canada, and Germany, with steel frame chassis and cross-laminated timber panels as critical inputs. Single-source vulnerability in engineered wood products from Pacific Northwest suppliers exposes producers to regional climate disruption. Distribution runs through manufacturer-owned retail networks and independent dealerships coordinating transport, foundation, and utility connection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in factory automation investments that compress production cycles and premium-tier positioning through energy-efficiency certification that unlocks previously restricted municipal markets.
For Market Incumbents: Deploy captive financing subsidiaries to lock in buyer relationships before competitors replicate the full-ownership-pathway model. Absorb HUD Code Title 6 compliance costs through backward integration into component manufacturing rather than passing through to price-sensitive segments. Cross-laminated timber entrants from European markets threaten steel-frame dominance in climate zones where transport weight reduction commands logistics savings. For New Entrants and Emerging Players: Land-lease community operators represent the most penetrable channel partner type for factory-built inventory scaling. Target India's PMAY-Urban subsidized credit eligibility for steel-frame export partnerships with Gujarat and Tamil Nadu manufacturing joint ventures. Digital configurator platforms enable specification completion before physical display center visits, compressing customer acquisition costs among under-45 buyers. For Investors and Strategic Acquirers: Asymmetric upside sits with modular construction specialists holding local building code compliance capabilities that bypass HUD Code zoning restrictions. Long-term viability over the five-to-ten year window favors producers with multi-facility geographic diversification insulating against regional demand shocks. Monitor state-level zoning reform trajectories in Sun Belt jurisdictions as inflection indicators for placement opportunity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Component Manufacturing | Captive steel frame and CLT production insulates margin from commodity volatility cycles. |
| Community Land-Lease Model Expansion | Purpose-built retirement enclaves in Arizona and Florida accept shorter depreciation for amenity bundling. |
| Digital Configurator Platform Launch | Online specification completion captures Texas and Georgia buyers before dealership visits. |
| Energy-Efficiency Certification Investment | HUD Code Title 6 compliance unlocks municipal markets previously hostile to factory-built housing. |
| India Manufacturing Joint Venture | PMAY-Urban eligibility opens subsidized credit pathways for steel-frame production partnerships. |
Research Methodology
Multiple input streams — executive interviews with manufactured housing production managers, regulatory affairs specialists at HUD and EPA, affordable housing developer procurement directors, and land-lease community operators — were reconciled against secondary validation from HUD construction standard filings, EPA formaldehyde emission compliance databases, and state-level zoning ordinance repositories. Bottom-up unit shipment aggregation and top-down construction spending allocation were triangulated to anchor volume estimates.
Historical production data from Southeast and Southwest US manufacturing clusters were cross-referenced against panel input from industry participants to model shipment trajectories across the projection horizon. Segmentation dimensions included product type, construction material, end user category, and distribution channel. CAGRs were derived from regression analysis of unit volume against demographic migration patterns and regulatory compliance cost absorption.
Revisions become necessary when HUD Code energy-efficiency threshold updates accelerate, commodity input volatility exceeds historical bands, or municipal zoning reforms materially expand or restrict placement opportunities. Practitioners should monitor state-level installation contractor certification requirements and utility interconnection standardization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Swimming Pool Construction Market
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
North America Residential Construction Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
US Residential Construction Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Residential Roofing Market
Residential Construction
Japan Residential Construction Market
Residential Construction
US Residential Remodeling Market
Residential Construction
North America Prefabricated Housing Market