
 Canada Manufactured Homes Market | 2026-2036
Canada Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Manufactured Homes Market Outlook
Digital design-to-fabrication workflows is rewriting how Canadian manufacturers coordinate engineering, supply procurement, and module assembly. Champion Home Builders leverages vertical integration across its Alberta and Ontario plants to compress delivery schedules for remote-resource projects. Maple Leaf Homes anchors its competitive position through R&D intensity in energy-efficient envelope systems purpose-built for northern climate zones. Alta-Fab Structures dominates Western Canada's industrial workforce housing segment through controlled channel relationships with oil sands operators and mining developers.
Canada manufactured homes are prefabricated dwelling units built in climate-controlled factories to CSA Z240 MH and CSA A277 standards, then transported in one or more sections to permanent or semi-permanent installation sites. These structures employ engineered wood floor systems, steel chassis frames, and insulated roof assemblies designed to withstand highway transport stresses while meeting provincial building code thermal performance thresholds. Single-section units retain cost leadership in rural retirement and First Nations reserve applications where foundation simplicity reduces total project expenditure. Multi-section configurations generate the fastest expansion in urban infill corridors around Toronto, Calgary, and Vancouver as municipalities relax accessory dwelling unit restrictions. Modular products command premium positioning through CSA A277 certification pathways that grant full building code equivalency and broader mortgage financing access.
Health Canada, the Canada Mortgage and Housing Corporation, and provincial adoption of the National Building Code collectively govern factory-built housing standards, energy efficiency mandates, and installation compliance across Canadian jurisdictions. CMHC's securitization programs and provincial land-lease regulations shape demand accessibility by determining financing availability and tenure security for manufactured home purchasers. Stakeholders must monitor evolving municipal zoning reforms that determine whether manufactured housing gains density credit parity with site-built alternatives in Canada's most supply-constrained housing markets.
Market Dynamics
CMHC's factory-built housing standardization is compressing provincial approval timelines from eighteen months to under six, fundamentally altering how developers stage capital across Canadian jurisdictions.
Growth Catalysts
- Accessory Dwelling Unit Liberalization:Municipal zoning reforms in Toronto, Calgary, and Vancouver corridors are legalizing backyard manufactured housing on single-family lots, unlocking density without land assembly.
- CSA A277 Certification Pathway:Full building code equivalency for modular products is expanding mortgage financing access beyond chattel loans, attracting first-time buyers previously excluded from conventional construction markets.
- Remote Resource Economics:Alberta oil sands operators and Quebec mining developers are specifying multi-section workforce housing to avoid fly-in-fly-out labor premiums and site-built weather delays.
Market Restraints
- Lumber Input Volatility:Engineered wood floor systems face cost pressure from British Columbia timber supply constraints and cross-border tariff exposure on dimensional lumber.
- Transport Infrastructure Bottlenecks:Highway weight restrictions and bridge clearances in the Canadian Shield limit single-section widths, forcing costly multi-piece transport for northern Quebec and Ontario deliveries.
- Site-Built Substitution in Urban Core:High-rise concrete construction retains municipal preference for transit-oriented density, capping manufactured housing penetration in Vancouver and Toronto downtown zones.
Strategic Opportunities
- First Nations Reserve Deployment:Federal infrastructure commitments to Indigenous housing are creating dedicated procurement streams for CSA Z240 MH certified units with simplified foundation requirements.
- Energy Retrofit Integration:Deep energy retrofit mandates under the National Building Code are positioning factory-built envelope systems as faster-to-deploy alternatives to site-built deep retrofits.
- Industrial Workforce Channel Partnerships:Direct specification relationships with oil sands and mining camp operators are bypassing traditional dealer networks, capturing full project lifecycle value.
Industry Challenges
- Certified Installer Scarcity:Provincial licensing requirements for manufactured home installation are outpacing training program throughput, creating bottlenecks in Alberta and British Columbia.
- Foundation Interface Standardization:Lack of unified pier and anchoring specifications across Ontario, Quebec, and Western provinces forces case-by-case engineering, inflating project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Manufactured Homes Market |
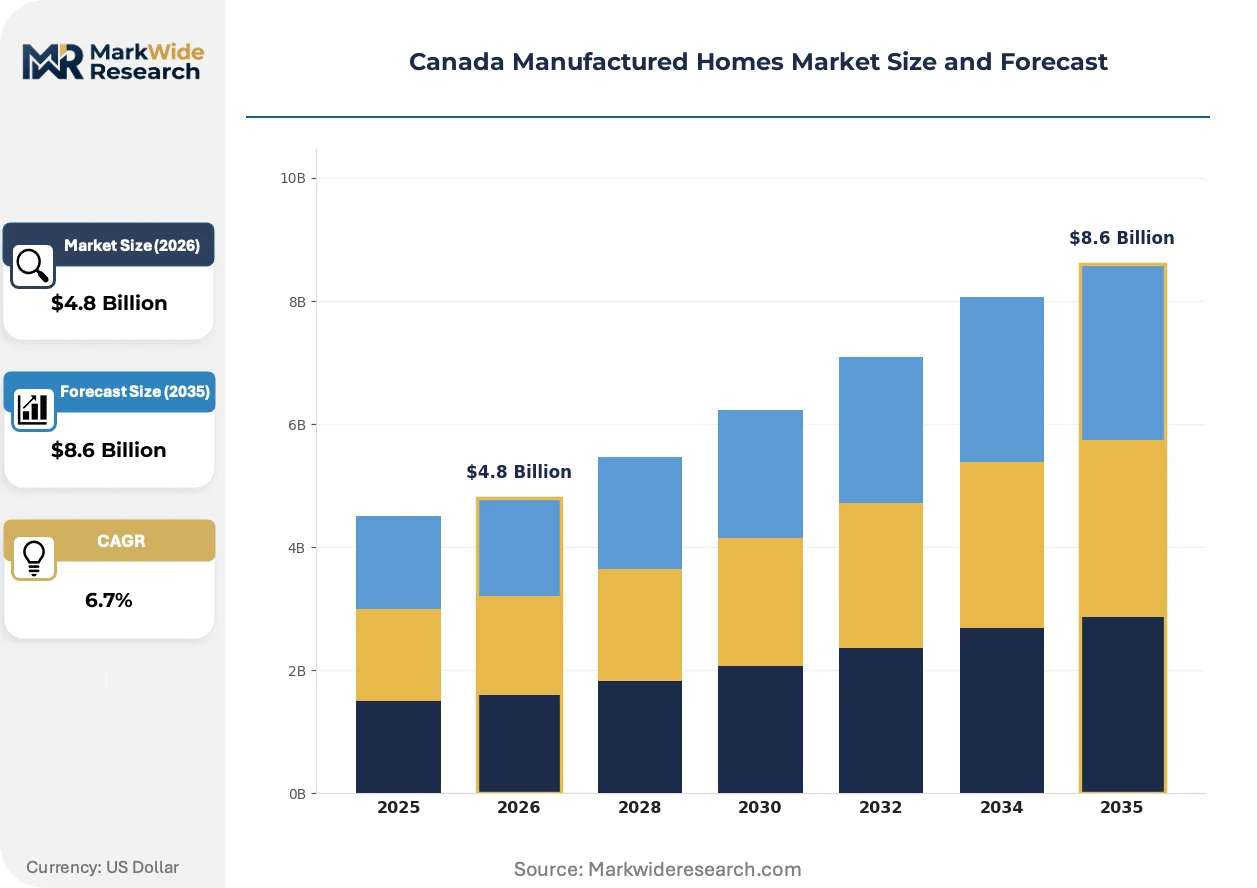
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Section, Multi-Section, Modular, Park Model End User: Individuals, Developers, Rental Companies, Investment Firms Installation: On-Site, Off-Site, Permanent, Temporary Sales Channel: Direct Sales, Dealers, Online Platforms, Auctions |
| Companies Covered | Triple M Housing, ATCO, Champion Home Builders, NRB Modular Solution, Alta-Fab Structures, Guildcrest Homes, Maple Leaf Homes, Stack Modular, SRI Homes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Manufactured Homes Market Strategic Shifts
Digital fabrication workflows are collapsing the traditional sequential handoff between architectural design, structural engineering, and factory floor production, compressing concept-to-occupancy timelines for Canadian developers.
Cross-laminated timber panel systems are hybridizing with conventional steel chassis frames to achieve higher thermal performance ratings required for northern climate zones. Alberta and Ontario plants are adopting these hybrid assemblies for remote-resource projects where energy costs dominate operating budgets. The technology is hybridizing procurement specifications, forcing steel suppliers and mass timber producers into coordinated supply relationships previously managed separately.
Health Canada's harmonized factory-built housing standards under the National Building Code are eliminating provincial variance in fire safety and structural load requirements. Manufacturers now engineer single product lines compliant from Newfoundland to British Columbia, collapsing SKU complexity and inventory carrying costs. Quebec and Atlantic Canada are responding fastest, where previous provincial deviations had forced market-specific production runs.
Buyers in Ontario and British Columbia are consolidating purchases through direct-to-manufacturer contracting for multi-unit rental projects, bypassing traditional dealer networks. Developers are negotiating volume-based specification locks eighteen months ahead of factory slotting, securing delivery priority during peak construction seasons. This channel compression is most visible in Calgary and Vancouver infill corridors where municipal density bonuses reward rapid project completion.
Canada Manufactured Homes Market Segmentation
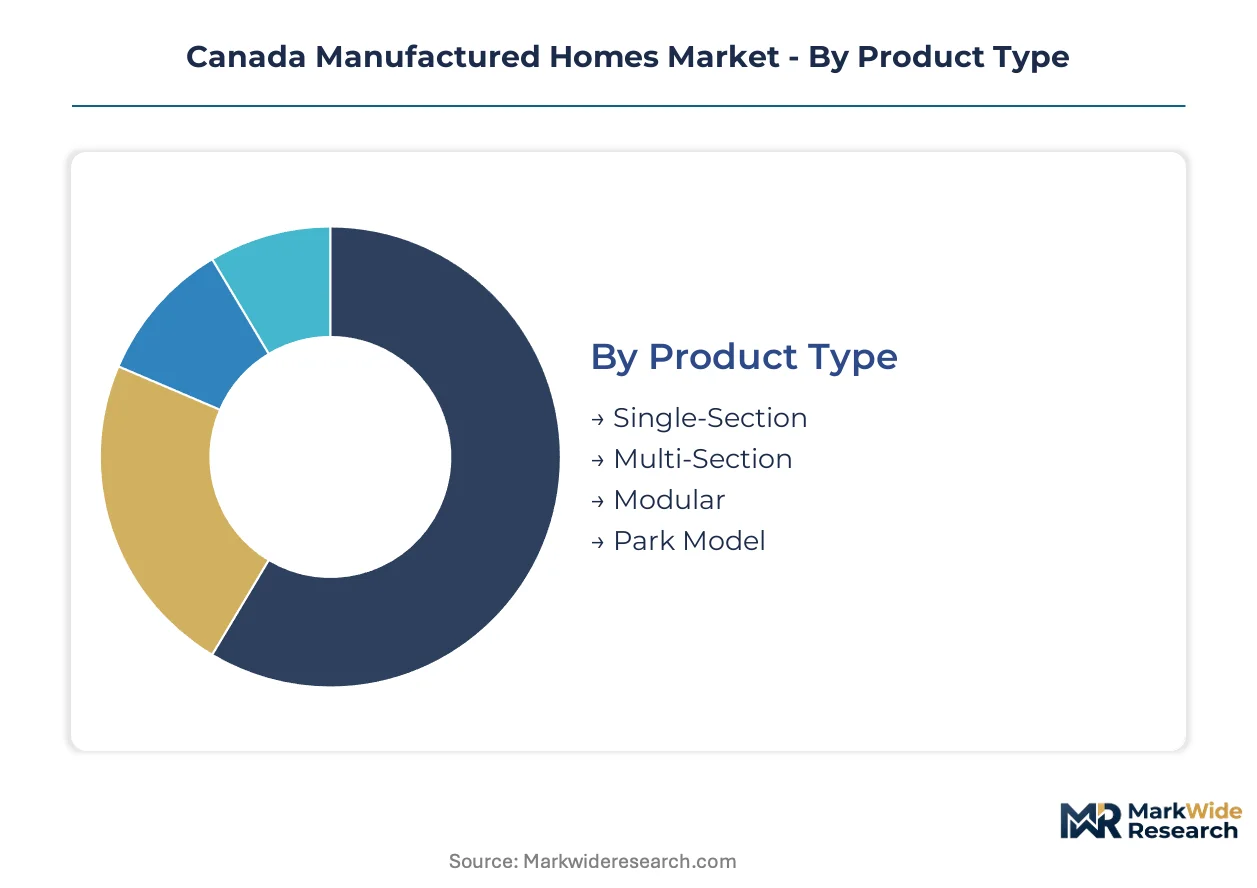
Segmentation in Canada's manufactured homes market reveals how product specifications, customer economics, and regulatory pathways determine pricing power and channel access. Manufacturers engineer distinct production lines for each segment, with certification requirements and foundation complexity driving margin dispersion across the value chain.
Product Type:
Cost tier determines foundation complexity, transport logistics, and financing access across Canadian manufactured housing products.
- Single-Section:Factory-built units measuring 14-18 feet wide deploy engineered wood floor systems on steel I-beam chassis for highway transport. Demand concentrates in rural Alberta retirement communities and First Nations reserves where pier foundations slash installation costs below multi-section alternatives.
- Multi-Section:Two or more modules joined on-site create configurations exceeding 2,000 square feet. Ontario and British Columbia first-time buyers are gravitating toward these units as conventional construction affordability deteriorates in Toronto and Vancouver corridors.
- Modular:CSA A277 certification grants full building code equivalency and conventional mortgage eligibility. Health Canada's harmonized standards are collapsing provincial variance, enabling single production lines compliant from Newfoundland to British Columbia.
- Park Model:Recreational dwelling units under 400 square feet target seasonal occupancy in Quebec lake regions and British Columbia retirement clusters. CSA Z240 MH certification maintains simplified compliance pathways.
Single-Section commands the established base. The steepest expansion runs through Multi-Section.
End User:
Customer type dictates specification complexity, procurement channel, and project timeline compression strategies.
- Individuals:First-time buyers and downsizing retirees purchase through dealer networks or direct manufacturer relationships. CMHC's standardized factory-built housing codes are compressing their approval timelines from eighteen months to under six.
- Developers:Multi-unit rental project sponsors negotiate volume-based specification locks eighteen months ahead of factory slotting. Calgary and Vancouver infill corridors reward their rapid project completion with municipal density bonuses.
- Rental Companies:Portfolio operators specify durable envelope systems for workforce housing in Alberta's energy-sector communities. Their procurement bypasses traditional retail markups through direct manufacturer contracting.
- Investment Firms:Institutional capital deploys manufactured housing as yield-generating alternatives to conventional multifamily. Quebec's remote-resource regions attract their capital where site-built delivery costs remain prohibitive.
Individuals anchor current volume. Developers are gaining share fastest through channel compression.
Installation:
Foundation permanence and site preparation intensity segment project economics and regulatory oversight.
- On-Site:Modules arrive 90-95% complete requiring utility connection and exterior finish work. British Columbia and Ontario municipalities are streamlining these installations through CMHC's standardized codes.
- Off-Site:Factory-controlled completion includes interior finishes, fixture installation, and quality assurance testing. Quebec and Atlantic Canada manufacturers favor this pathway where weather delays plague site-built alternatives.
- Permanent:Pier, slab, or basement foundations anchor units to real property, unlocking conventional mortgage financing. CSA A277 modular certification is expanding this installation type's addressable market.
- Temporary:Skid or block foundations serve industrial workforce camps and emergency housing deployments. Alberta oil sands operators specify these for rapid camp mobilization and demobilization.
Permanent foundations dominate financed transactions. Temporary installations are climbing fastest through resource-sector demand.
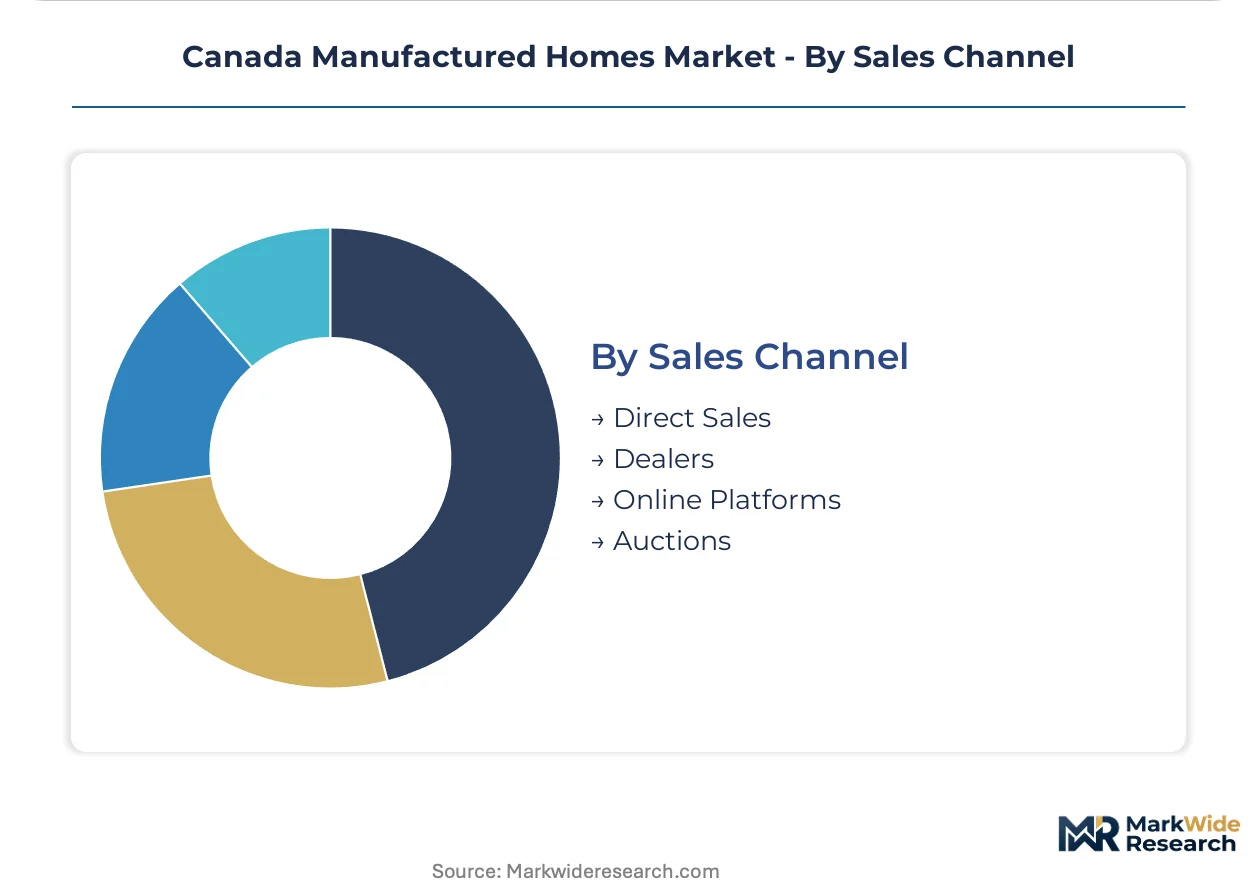
Sales Channel:
Channel structure determines margin capture, specification control, and customer relationship depth.
- Direct Sales:Manufacturers contract directly with developers and industrial operators for multi-unit projects. Champion Home Builders and Alta-Fab Structures leverage this channel for remote-resource and workforce housing verticals.
- Dealers:Independent retail networks dominate individual buyer transactions in Ontario and Western Canada. Their localized site preparation and installation services justify margin premiums over direct channels.
- Online Platforms:Digital configurators and virtual tours are emerging for standardized single-section units. Younger first-time buyers in British Columbia are piloting these platforms for specification and pricing transparency.
- Auctions:Liquidation and distressed inventory channels serve budget-constrained rural markets. Atlantic Canada sees periodic auction activity for repossessed units and dealership closeouts.
Dealers retain the volume base. Direct sales are expanding most quickly through developer channel compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's manufactured homes sector maintains a modest export surplus with the United States while importing specialized components from Asian supply chains. Cross-border regulatory harmonization through the National Building Code is compressing delivery timelines for interprovincial projects.
Ontario
First-time buyers in the Greater Toronto Area are gravitating toward multi-section units as conventional construction affordability deteriorates. CMHC's standardized factory-built housing codes are compressing municipal approval timelines from eighteen months to under six. The Golden Horseshoe corridor is witnessing developer-led channel compression through direct-to-manufacturer contracting for infill rental projects.
Quebec
Remote-resource mining developers are specifying modular workforce housing to avoid fly-in-fly-out labor premiums. Health Canada's harmonized standards are eliminating previous provincial deviations that forced market-specific production runs. The Saguenay-Lac-Saint-Jean region anchors demand for CSA A277 certified units with rapid camp mobilization requirements.
Alberta
Oil sands operators are driving demand for temporary foundation installations with rapid demobilization capabilities. Provincial licensing requirements for certified installers are outpacing training program throughput, creating bottlenecks in Calgary and Edmonton corridors. The Regional Municipality of Wood Buffalo concentrates industrial workforce housing procurement through direct manufacturer relationships.
British Columbia
Younger first-time buyers are piloting digital configurators and virtual tours for standardized single-section units. Municipal zoning reforms in Vancouver are legalizing backyard manufactured housing on single-family lots, unlocking density without land assembly. The Lower Mainland is experiencing the steepest multi-section expansion as accessory dwelling unit restrictions relax.
Atlantic Canada
Rural retirement communities are sustaining single-section demand where pier foundations slash installation costs. Previous provincial deviations in fire safety and structural load requirements had forced market-specific production runs now collapsed under harmonized standards. Nova Scotia's South Shore is responding fastest to standardized CSA Z240 MH certification pathways.
Canada Manufactured Homes Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive control over factory slotting and installation networks. Champion Home Builders and Alta-Fab Structures exemplify this archetype through multi-province plant footprints. A second archetype clusters specialized modular fabricators targeting CSA A277 certification pathways for conventional mortgage eligibility. Strategic moves center on capacity expansion in Alberta and Ontario corridors plus direct channel partnerships with resource-sector developers bypassing traditional dealer markups.
Among the named Canadian fabricators, Champion Home Builders, Alta-Fab Structures, and Maple Leaf Homes occupy distinct positioning vectors. Champion exemplifies the scale-driven integrated archetype with multi-province manufacturing presence. Alta-Fab anchors the industrial workforce housing specialization through oil sands and mining camp relationships. Maple Leaf sits within the energy-efficient envelope R&D tier, representing manufacturers engineering northern climate-specific thermal performance systems. These three collectively illustrate how certification pathways, vertical integration depth, and end-market specialization stratify competitive positioning across the Canadian manufactured homes value chain.
| Leading Market Players |
|---|
| Triple M Housing |
| ATCO |
| Champion Home Builders |
| NRB Modular Solution |
| Alta-Fab Structures |
| Guildcrest Homes |
| Maple Leaf Homes |
| Stack Modular |
| SRI Homes |
| Others |
Value Chain & Pricing Dynamics
British Columbia timber supply concentration anchors engineered wood floor system costs, compressing margin pools at manufacturers dependent on dimensional lumber for single-section chassis assemblies. Cross-border tariff exposure on softwood lumber feeds downstream into multi-section unit pricing, forcing Alberta and Ontario plants to absorb volatility or pass through to resource-sector buyers with long-term camp contracts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for workforce housing deployments. Three-tier pricing structure across premium, standard, and economy levels separates CSA A277 modular certification from CSA Z240 MH compliance from uncertified park model alternatives. Cost compression in standard-tier multi-section units is intensifying because British Columbia timber supply constraints elevate engineered wood input costs. First-time buyers in Toronto and Vancouver corridors exhibit highest price sensitivity, while oil sands operators prioritize rapid mobilization over per-unit economics.
Supply Chain Analysis
Champion Home Builders and Maple Leaf Homes hold captive in-house production capacity across Alberta and Ontario corridors, limiting third-party contract manufacturing penetration. Raw material sourcing draws from British Columbia timber, Chinese steel chassis components, and domestic insulation suppliers. Single-source vulnerability concentrates in cross-border lumber flows subject to periodic tariff renegotiation. Distribution runs through direct manufacturer relationships with resource developers and independent dealer networks serving individual buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMHC's standardized factory-built housing codes are compressing approval timelines from eighteen months to under six, creating a regulatory inflection that rewards manufacturers with pre-positioned certification infrastructure and multi-province installation networks.
For Market Incumbents: Pre-empt channel compression by locking eighteen-month specification contracts with Calgary and Vancouver infill developers before competitor slotting availability tightens. Champion Home Builders' multi-province plant footprint exemplifies the capacity positioning required to capture municipal density bonus timelines. Backward integration into engineered wood floor system production hedges British Columbia timber volatility that threatens standard-tier margins. For New Entrants and Emerging Players: Build out digital configurator platforms targeting British Columbia's younger first-time buyer segment, where virtual specification and pricing transparency remain underdeveloped against traditional dealer networks. Quebec's remote-resource mining camps offer the most penetrable white-space for modular workforce housing, with fly-in-fly-out labor premiums creating urgent demand for rapid camp mobilization. Direct-to-manufacturer contracting bypasses established dealer markups in this segment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabricators holding CSA A277 certification but lacking national installation network scale. The five-to-ten-year viability window favors manufacturers engineering single product lines compliant from Newfoundland to British Columbia under Health Canada's harmonized standards. Monitor municipal zoning reform velocity in Toronto, Calgary, and Vancouver as the signal indicating inflection in accessory dwelling unit addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CSA A277 Certification Investment | Unlocks conventional mortgage eligibility expanding first-time buyer access beyond chattel financing. |
| Direct Channel Partnership Expansion | Bypasses dealer markups capturing full project lifecycle value with oil sands and mining operators. |
| Cross-Laminated Timber Panel Integration | Hybridizes with steel chassis frames achieving northern climate thermal performance ratings. |
| Digital Design-to-Fabrication Workflow Deployment | Collapses sequential handoffs compressing concept-to-occupancy timelines for developer clients. |
| First Nations Reserve Procurement Stream Development | Federal infrastructure commitments create dedicated volume for CSA Z240 MH certified units. |
Study Parameters
A spread of perspectives from manufactured home plant managers, resource-sector procurement leads at oil sands operators, municipal zoning officers in Toronto and Vancouver, CMHC policy specialists, and dealer network owners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through National Building Code adoption tracking, CMHC securitization program disclosures, and provincial land-lease regulation databases. Bottom-up unit economics modeling triangulated against top-down market sizing from construction permit data and factory shipment records.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation modeled across product type, end user, installation permanence, and sales channel dimensions plus climate-zone thermal performance tier as an industry-specific overlay. CAGRs derived from regression analysis against housing affordability indices, resource-sector capital expenditure cycles, and municipal zoning reform adoption curves. Forecast inputs incorporated lumber futures volatility patterns and certified installer training program throughput constraints.
Sensitivities concentrate around British Columbia timber supply disruptions, cross-border tariff renegotiation outcomes, and municipal zoning reform implementation velocity in supply-constrained corridors. Forecasts reflect documented assumptions regarding CMHC standardization adoption rates and provincial licensing harmonization timelines. Quarterly review of municipal accessory dwelling unit ordinance amendments and resource-sector workforce housing procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
North America Prefabricated Housing Market
Residential Construction
Swimming Pool Construction Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Residential Construction Market
Residential Construction
US Residential Remodeling Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Siding Market
Residential Construction
North America Bath Remodeling Market