
 Saudi Arabia Residential Construction Market | 2026-2036
Saudi Arabia Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Residential Construction Market Insights
SASO energy-efficiency certification is unwinding the competitive landscape for residential developers in Saudi Arabia. Nesma & Partners leverages its integrated engineering and construction capabilities to secure large-scale housing contracts across the Kingdom. Saudi Constructioneers Ltd. (Saudico) anchors its position through sustained relationships with government housing programs and public-private partnerships. ROSHN Real Estate dominates the master-planned community segment with standardized designs that compress delivery timelines.
Saudi Arabia residential construction encompasses the planning, design, and erection of dwellings ranging from single-family villas to high-density apartment towers, typically employing reinforced concrete frame systems with block infill and thermal insulation meeting SASO 2857 energy-performance criteria. Its primary purpose is to deliver habitable units aligned with demographic expansion and quality-of-life targets under national transformation programs. Single-family homes and multi-family units together absorb the dominant share of construction value, though modular and prefabricated methods are gaining traction as labor-cost pressures mount and project timelines compress. Sustainable construction methods command premium positioning despite higher upfront material costs, particularly in developments targeting green-building recognition.
The National Housing Company operates under Ministry of Municipal and Rural Affairs and Housing oversight, while SASO enforces building-code compliance and material standards that gate market access for foreign suppliers and local contractors alike. SFDA oversight of imported construction chemicals and coatings adds a secondary compliance layer that shapes procurement decisions for developers sourcing from international markets. Stakeholders must monitor how evolving mortgage-guarantee frameworks and zoning liberalization in secondary cities reshape project feasibility assumptions.
Market Dynamics
SASO energy-efficiency mandates are compressing delivery timelines across Saudi Arabia residential construction, forcing developers to integrate thermal-performance compliance into early design phases rather than retrofitting during final inspection stages.
Growth Catalysts
- Mortgage guarantee frameworks:Government-backed financing instruments under Vision 2030 housing reforms are expanding first-time buyer access. Banks now originate loans with reduced collateral requirements.
- ROSHN master-planned communities:Standardized villa and apartment typologies in Riyadh and Jeddah are accelerating unit delivery. Repetitive construction sequences cut per-unit labor hours.
- SASO 2857 thermal standards:Mandatory insulation specifications for wall and roof assemblies are creating upgrade demand across existing housing stock. Retrofit contractors capture incremental project flow.
Market Restraints
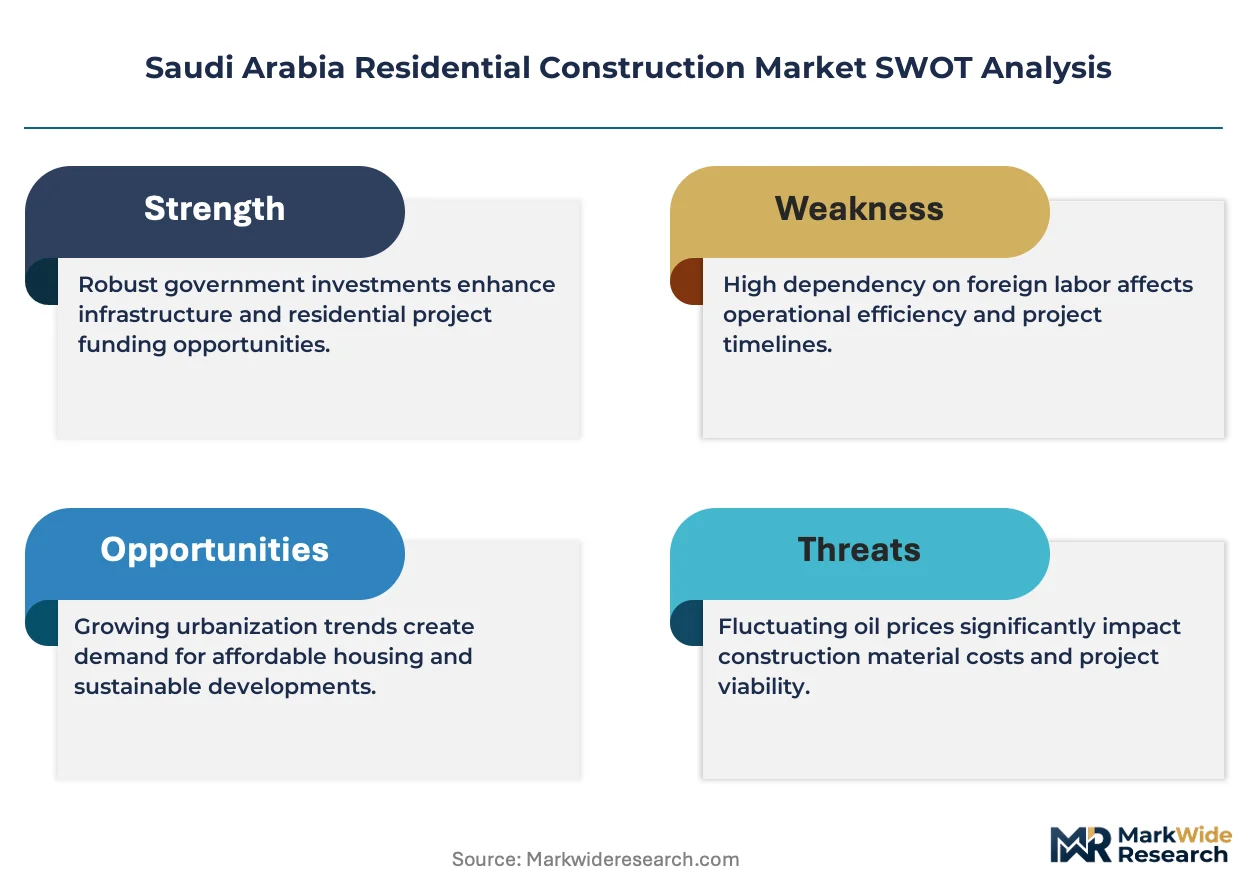
- Steel and cement input volatility:Domestic rebar and clinker prices fluctuate with fuel subsidy adjustments. Developers face margin compression on fixed-price contracts.
- Specialized MEP contractor concentration:Centralized HVAC and electrical subcontractor pools in Riyadh create bottleneck risk. Project delays cascade when demand spikes.
- SFDA chemical import licensing:Construction coatings and adhesives face extended approval timelines. Procurement teams stockpile inventory, tying working capital.
Strategic Opportunities
- Eastern Province secondary cities:Dammam and Khobar zoning liberalization is unlocking greenfield development sites. Land costs run 40 percent below Riyadh equivalents.
- Modular prefabrication:Factory-built bathroom pods and kitchen modules are cutting on-site wet-trade labor. Saudi-based panel plants are scaling capacity.
- Green-building certification premiums:Mostadam-rated developments command rent and resale premiums. Institutional investors target certified assets for ESG mandates.
Industry Challenges
- Quantity surveyor talent scarcity:Cost-estimation expertise for SASO-compliant assemblies is concentrated among mid-tier consultancies. Project controls teams compete for limited specialists.
- Legacy payment cycle friction:Subcontractor retention disputes delay final account settlements. Cash flow stress propagates down the tier-2 supply chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Residential Construction Market |
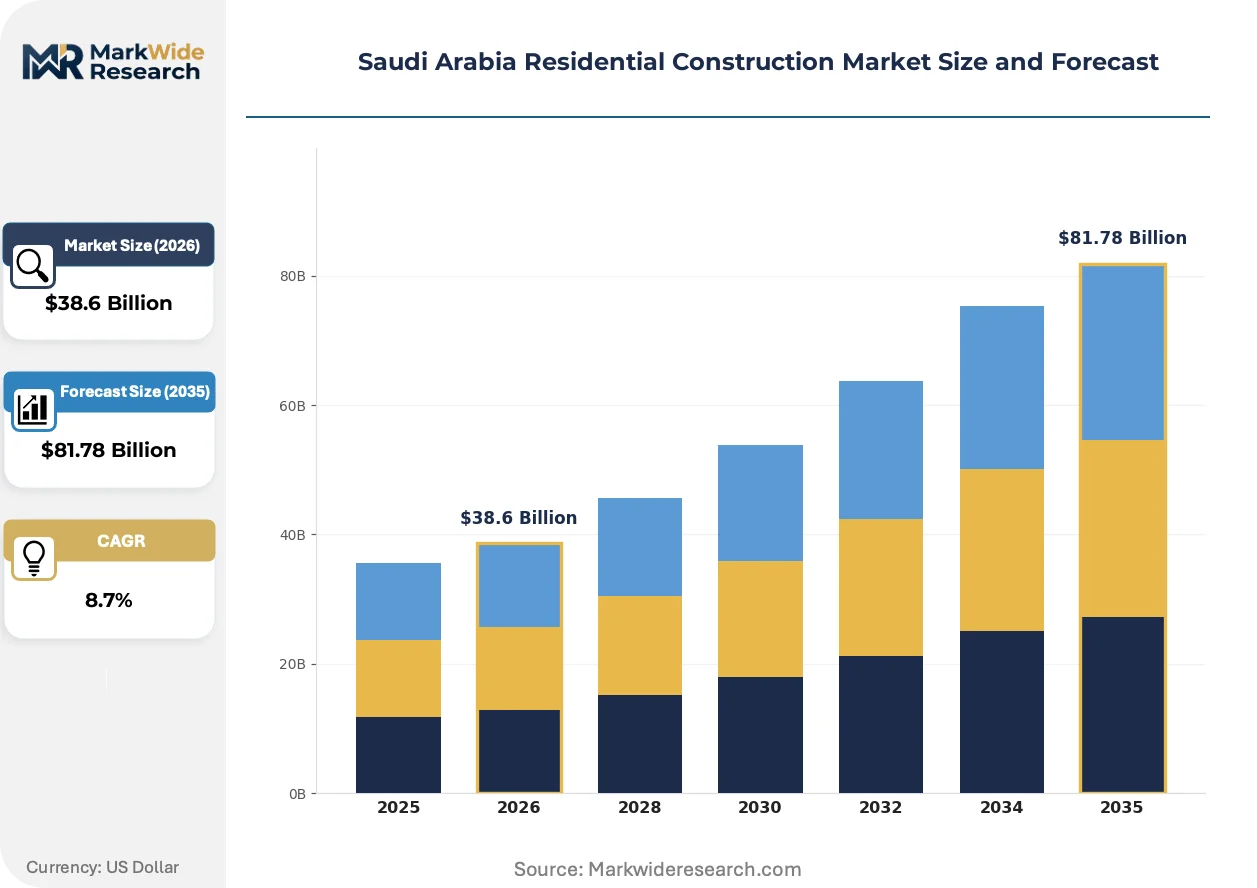
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-family Homes, Multi-family Units, Townhouses, Condominiums Construction Method: Traditional, Modular, Prefabricated, Sustainable Material: Concrete, Steel, Wood, Brick End User: First-time Buyers, Investors, Developers, Property Managers |
| Companies Covered | Saudi Cyprian Construction Co. Ltd., Saudi Constructioneers Ltd. (Saudico), Nesma & Partners, Jabal Omar Development Co., Sedco Development, Al Bawani Co., ROSHN Real Estate, National Housing Company (NHC), Dar Al Arkan Real-Estate Dev., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Residential Construction Market Trends and Innovations
Digital design-to-fabrication workflows and performance-based procurement are restructuring how Saudi developers specify, source, and assemble residential buildings.
Building information modeling paired with automated rebar detailing is fragmenting traditional design-bid-build sequences. Tier-1 contractors now model structural elements in-house before tender release. This compression eliminates drawing interpretation errors and accelerates procurement lead times for complex villa clusters.
SASO is tightening enforcement of the Saudi Building Code energy chapter through mandatory third-party commissioning. Inspectors now verify air-tightness and insulation continuity before occupancy permits issue. Developers in Jeddah are pre-emptively upgrading envelope specifications to avoid rework penalties.
First-time buyers are prioritizing mortgage pre-approval over speculative site visits. Digital lending platforms from local banks now issue conditional approvals within 48 hours. This behavioral shift is concentrating demand in ROSHN and National Housing Company projects with certified financing eligibility.
Saudi Arabia Residential Construction Market Segmentation
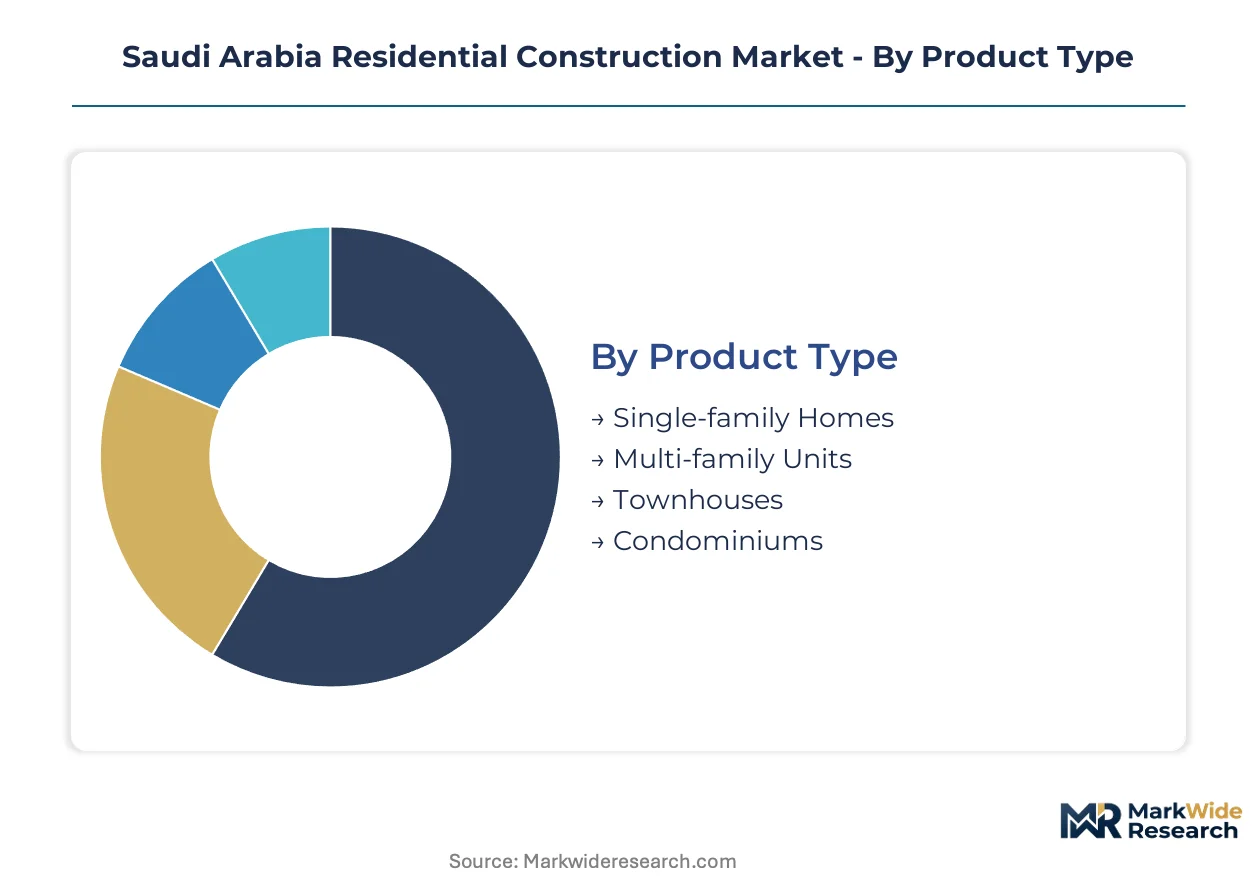
Segmentation in Saudi Arabia residential construction reveals how Vision 2030 housing reforms are redirecting capital flows across product types and construction methodologies. Each dimension exposes distinct procurement patterns, regulatory exposure, and margin structures that shape developer strategy.
Product Type:
Channel distribution varies sharply by product type, with government-backed mortgage eligibility acting as a gatekeeper for volume flows.
- Single-family Homes:Reinforced concrete frame construction with block infill dominates technical specifications. Demand concentrates in ROSHN master-planned communities across Riyadh and Jeddah, where standardized villa typologies accelerate delivery timelines under SASO 2857 thermal compliance mandates.
- Multi-family Units:High-density apartment towers employ post-tensioned slab systems with centralized MEP distribution. Riyadh's eastern ring road corridor absorbs the dominant share of new supply, driven by first-time buyer mortgage pre-approval concentration in bank-eligible developments.
- Townhouses:Mid-rise attached dwellings with shared wall assemblies reduce per-unit land consumption. National Housing Company programs prioritize this format in secondary cities.
- Condominiums:Strata-titled apartment ownership structures with common-area maintenance frameworks. Foreign investor interest is climbing in Jeddah's northern expansion zone.
Single-family homes dominate installed base. Multi-family units are where expansion concentrates.
Construction Method:
Cost tier stratification separates premium developments from mass-market delivery, with construction method selection directly determining labor intensity and timeline risk.
- Traditional:Cast-in-place concrete with on-site wet trades and sequential trade stacking. This method retains share in custom villa segments where buyer customization demands resist standardization.
- Modular:Factory-built volumetric units with 70-90% completion before site delivery. Eastern Province developers are piloting this approach to compress skilled labor exposure.
- Prefabricated:Panelized wall and floor systems with on-site assembly. Dammam-based fabricators are scaling capacity to serve Khobar greenfield sites.
- Sustainable:Mostadam-certified assemblies with enhanced envelope performance and renewable integration. Premium positioning commands rent and resale premiums in institutional investor portfolios.
Traditional methods retain volume leadership. Modular construction is gaining share fastest among tier-1 contractors.
Material:
Supply concentration around domestic rebar and clinker production shapes procurement geography and price volatility exposure.
- Concrete:Ready-mix with locally sourced aggregate and imported cementitious additives. Riyadh's central corridor hosts the densest concentration of batching capacity.
- Steel:Domestic rebar from SABIC-affiliated mills with periodic fuel subsidy adjustment pass-through. Fixed-price contract exposure concentrates margin risk here.
- Wood:Engineered timber and structural lumber for niche villa segments. SFDA import licensing creates extended lead times.
- Brick:Clay and concrete masonry units for infill and facade applications. Local kiln capacity serves regional markets with limited inter-regional trade.
Concrete dominates structural assemblies. Steel is where input cost volatility concentrates most acutely.
End User:
Customer type determines financing channel access and decision velocity, with first-time buyer flows now dominating volume planning.
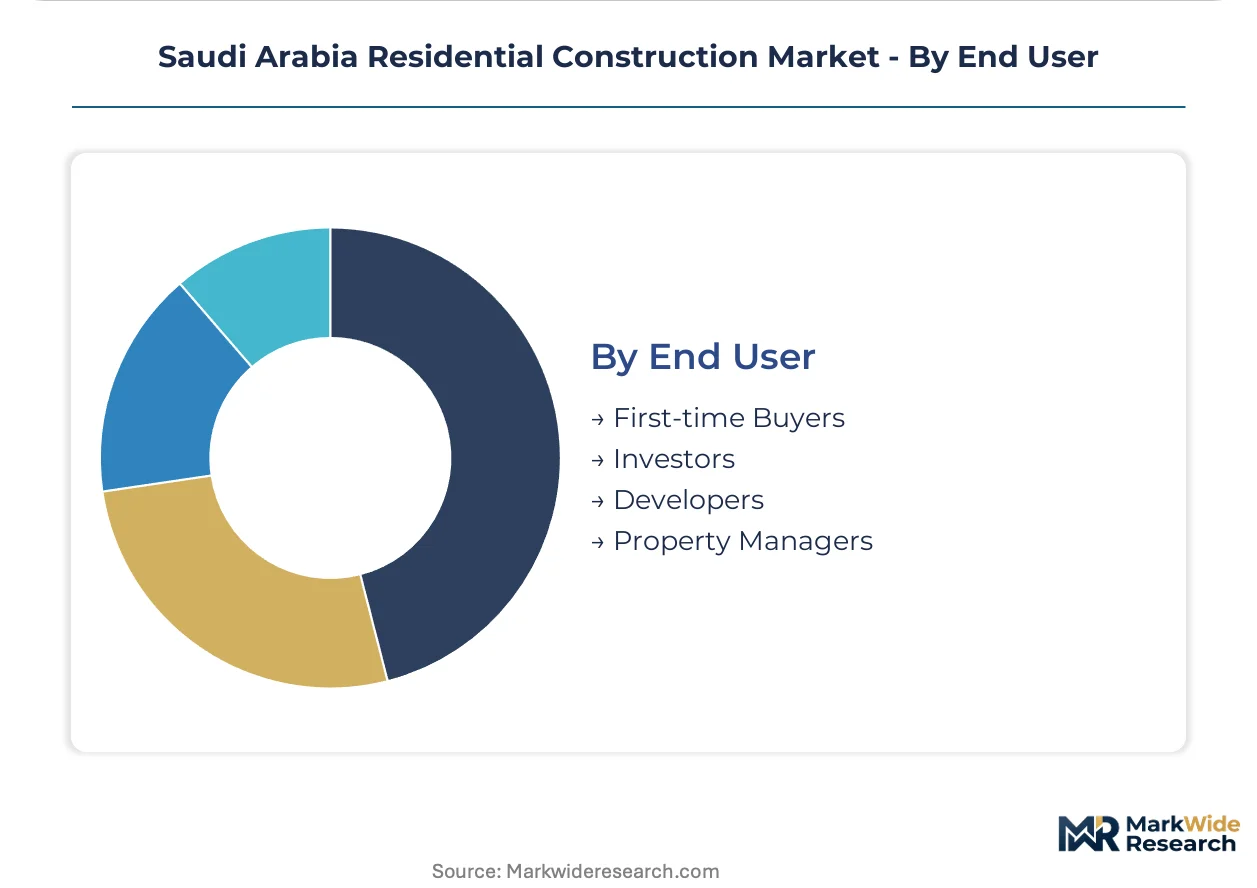
- First-time Buyers:Saudi nationals accessing government-backed mortgage guarantees with reduced collateral requirements. Digital lending platforms from Al Rajhi and Riyad Bank compress approval cycles to 48 hours.
- Investors:Domestic and Gulf-based buyers targeting rental yield and capital appreciation. Institutional capital is prioritizing Mostadam-certified assets for ESG mandate alignment.
- Developers:ROSHN Real Estate and National Housing Company subsidiaries executing master-planned community delivery. Public-private partnership structures govern land allocation and infrastructure timing.
- Property Managers:Professional operators of multi-family rental stock in Jeddah and Dammam. Service charge recovery mechanisms are standardizing across new condominium registrations.
First-time buyers dominate transaction volume. Investors are where pricing power expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
First-time buyer mortgage pre-approval flows are concentrating construction demand in Riyadh and Jeddah, where government-backed financing eligibility gates project selection. Eastern Province secondary cities are absorbing spillover development as land cost differentials widen.
Riyadh
ROSHN Real Estate and National Housing Company master-planned communities dominate residential delivery. SASO 2857 thermal compliance mandates compress design-to-permit timelines. Diriyah Gate and King Salman Park corridors anchor villa and mid-rise apartment absorption.
Eastern Province
Dammam and Khobar zoning liberalization unlocks greenfield sites at 40 percent below Riyadh land costs. Modular prefabrication pilots reduce skilled labor exposure. King Fahd Industrial City hosts scaling panel fabrication capacity.
Western Region
Jeddah's northern expansion zone attracts foreign investor interest in strata-titled condominiums. SFDA chemical import licensing extends construction coating lead times. Obhur Creek corridor concentrates Mostadam-certified premium stock.
NEOM Northwest
THE LINE and Oxagon projects drive experimental construction methodology demand. Factory-built volumetric units achieve 70-90 percent off-site completion. Trojena and Sindalah islands anchor hospitality-residential hybrid development.
Saudi Arabia Residential Construction Market Competitive Landscape
Player mix skews toward integrated engineering-construction conglomerates with government relationship depth. Market structure concentrates around tier-1 contractors capturing master-planned community scale and mid-tier specialists serving retrofit and secondary city segments. Strategic archetypes separate integrated EPC players, state-linked housing delivery vehicles, and private master-planned community developers. Competitive moves center on vertical integration into MEP subcontractor pools and prefabrication capacity builds.
Within the integrated EPC tier, Nesma & Partners and Saudi Constructioneers Ltd. occupy positions defined by sustained government housing program relationships. ROSHN Real Estate anchors the master-planned community archetype through standardized design repetition. National Housing Company sits within the state-linked delivery vehicle category, executing public-private partnership structures for land allocation and infrastructure timing.
| Leading Market Players |
|---|
| Saudi Cyprian Construction Co. Ltd. |
| Saudi Constructioneers Ltd. (Saudico) |
| Nesma & Partners |
| Jabal Omar Development Co. |
| Sedco Development |
| Al Bawani Co. |
| ROSHN Real Estate |
| National Housing Company (NHC) |
| Dar Al Arkan Real-Estate Dev. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory stockpiling of SFDA-licensed construction coatings compresses working capital cycles while amplifying pricing power for domestic distributors holding import permits. This buffer strategy feeds directly into how developers structure procurement contracts and pass through input cost volatility.
Pricing Analysis
Cost-plus contracts with quarterly rebar indexation dominate fixed-price agreements for large-scale housing developments. Price differentiation separates Mostadam-certified premium stock from standard SASO 2857-compliant units, with certification grade commanding measurable buyer premiums. Pricing pressure stems from fuel subsidy adjustments transmitting into domestic clinker and steel mill gate prices. First-time buyers accessing government-backed mortgage guarantees exhibit highest price sensitivity, while institutional investors targeting ESG-mandate alignment show lowest elasticity.
Supply Chain Analysis
Port congestion at Jeddah Islamic Port and container availability constraints on Asia-Gulf trade lanes extend lead times for engineered timber and specialty MEP components. Geographic supply concentration draws from China for construction chemicals, Turkey for ceramic tiles, and Germany for precision HVAC equipment. Raw material dependencies rest on SABIC-affiliated rebar mills, domestic clinker kilns, and imported cementitious additives. Single-source vulnerability concentrates in centralized Riyadh-based MEP subcontractor pools. Distribution runs through tier-1 contractor captive procurement divisions serving ROSHN and National Housing Company master-planned communities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility management and energy-performance monitoring services attach faster than core construction revenue as developers seek recurring income streams from completed housing stock. This service layer expansion justifies upfront technology investment in smart building infrastructure.
For Market Incumbents: Consolidate MEP subcontractor relationships through equity stakes or exclusive capacity reservations to bottleneck emerging competitors. Deepen backward integration into panel fabrication by acquiring Eastern Province modular plants before land cost differentials compress. SASO commissioning enforcement timelines threaten margin recovery on late-completion penalties.
For New Entrants and Emerging Players: SASO energy-efficiency certification fast-tracks market access for retrofit contractors targeting existing housing stock thermal upgrades. Secondary cities in the Eastern Province offer lowest competitive density for greenfield entry. Partner with Al Rajhi and Riyad Bank digital lending platforms to secure certified financing eligibility for project pre-sales.
For Investors and Strategic Acquirers: Long-term, this sits as a utility-like infrastructure play because residential delivery obligations under Vision 2030 housing targets generate contracted revenue visibility. Acquisition candidates include mid-tier consultancies with quantity surveyor talent concentration and Dammam-based prefabrication capacity. Monitor mortgage guarantee framework expansion rates as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Panel Fabrication | Captures land cost arbitrage in Eastern Province while reducing wet-trade labor exposure. |
| Mostadam Green Certification Program | Unlocks institutional capital flows targeting ESG-mandate residential asset allocation. |
| Digital Lending Platform Partnership | Compresses first-time buyer approval cycles to 48 hours through Al Rajhi and Riyad Bank integration. |
| MEP Subcontractor Capacity Reservation | Secures bottlenecked specialized labor pools in Riyadh against demand spike delays. |
| Secondary City Zoning Arbitrage | Exploits 40 percent land cost differential in Dammam and Khobar greenfield developments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SASO technical bulletins, Ministry of Municipal and Rural Affairs housing delivery reports, and SABIC-affiliated mill production disclosures. Primary interviews engaged project directors at tier-1 contractors, procurement leads at ROSHN Real Estate, quantity surveyors at mid-tier consultancies, and mortgage product managers at local banks. Bottom-up unit absorption estimates triangulate against top-down construction value flows across the analysis window.
Segmentation dimensions modeled span product type, construction methodology, material composition, and end-user category with regional sub-clustering across Riyadh, Eastern Province, Western Region, and NEOM Northwest. CAGRs derive from historical delivery volume trajectories, mortgage origination growth patterns, and land supply pipeline verification. Industry-specific inputs include SASO 2857 compliance cost curves and SFDA import licensing timeline distributions.
Underlying assumptions cover sustained Vision 2030 housing target commitments, stable fuel subsidy pass-through mechanisms, and mortgage guarantee framework expansion, with deviation risk concentrated in steel and cement input volatility and specialized contractor availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
US Residential Remodeling Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Italy Manufactured Homes Market
Residential Construction
UK Residential Construction Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Germany Residential Construction Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Europe Manufactured Homes Market