
 UAE Manufactured Homes Market | 2026-2036
UAE Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Manufactured Homes Market Analytics
MOHAP's updated building code for modular structures is expanding compliance requirements for factory-built housing across the Emirates. Karmod leverages its Turkish manufacturing base to supply steel-frame units into Abu Dhabi's worker housing programs. Speed House Group of Companies anchors its position through in-house production of concrete-core modular systems for government contracts. Bespoke Modular Solutions differentiates via customizable layouts targeting high-end residential buyers in Dubai Hills and Al Reem Island.
Manufactured homes in the UAE are prefabricated dwelling units engineered off-site to local wind-load and seismic specifications, then transported and installed on permanent or semi-permanent foundations. These structures typically employ steel or reinforced concrete frames with insulated panel envelopes to meet the country's extreme thermal performance requirements for summer cooling loads. Modular homes dominate value contribution due to their permanent foundation classification and eligibility for mortgage financing through UAE banks. Prefabricated homes with sustainable design features capture expanding margin pools as Dubai Municipality mandates green building ratings for new residential developments. Smart home technology integration represents the fastest-growing feature segment, driven by DEWA's digital infrastructure rollout and buyer expectations for remote climate and security management.
MOHAP, Dubai Municipality, and the Emirates Authority for Standardization and Metrology (ESMA) collectively govern structural safety, fire resistance, and energy efficiency standards for factory-built housing. ESMA's conformity assessment protocols create a regulated pathway for imported modular components while incentivizing domestic assembly capacity. Stakeholders must monitor evolving green building mandates from Dubai Supreme Council of Energy and their cascading impact on material specifications and factory certification requirements.
Market Dynamics
Steel-frame modular construction paired with DEWA's digital infrastructure rollout is compressing delivery timelines while elevating buyer expectations for integrated smart home capabilities across Emirates housing programs.
Growth Catalysts
- MOHAP Building Code Expansion:Updated compliance requirements for factory-built structures are legitimizing modular systems for permanent residential mortgages across Dubai and Abu Dhabi.
- UAE Vision 2031 Housing Mandates:Federal affordable housing targets are channeling government procurement toward prefabricated solutions in worker accommodation corridors.
- Smart Climate Integration:IoT-enabled energy management systems are reducing summer cooling loads by 25-40% in steel-panel envelopes, aligning with Dubai Supreme Council of Energy efficiency mandates.
Market Restraints
- Steel Input Volatility:Galvanized steel coil prices fluctuate with Turkish and Chinese export tariffs, compressing margins for frame manufacturers serving government contracts.
- Foundation Site Readiness:Semi-permanent classification limits financing access for prefabricated units not meeting ESMA's permanent foundation standards.
- Imported Component Dependency:Insulated panel systems and HVAC modules concentrate sourcing from Turkish and Saudi suppliers, exposing projects to Red Sea shipping disruptions.
Strategic Opportunities
- Al Ain and Northern Emirates Undersupply:Sharjah and Ras Al Khaimah lack dedicated modular manufacturing capacity, creating first-mover advantage for domestic assembly facilities.
- Green Building Rating Premiums:Dubai Municipality's mandatory sustainability certifications for new residential developments are expanding margin pools for units with solar-integrated roofs and greywater systems.
- Convergence of Modular and 3D Printing:Concrete additive manufacturing is enabling complex architectural geometries in foundation and core elements previously requiring cast-in-place construction.
Industry Challenges
- Certification Timeline Compression:ESMA conformity assessments for fire-rated panel assemblies currently require 14-18 weeks, delaying project handoffs for time-sensitive government housing programs.
- Skilled Installation Labor Scarcity:Precision alignment of steel-frame modules demands certified rigging crews, with qualified teams concentrated in Dubai Industrial City and limited availability in emerging corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Manufactured Homes Market |
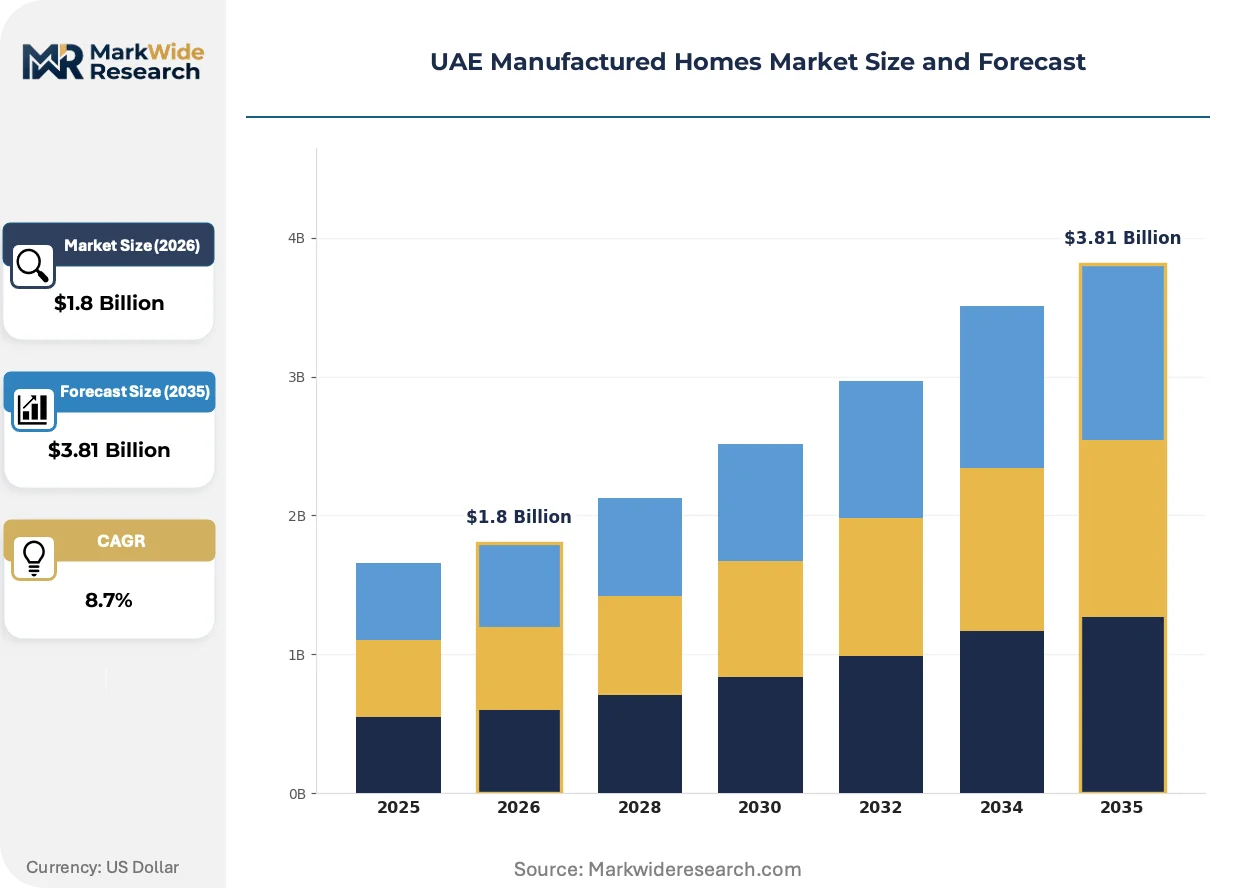
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Homes, Modular Homes, Prefabricated Homes, Tiny Houses End User: Residential Buyers, Construction Companies, Investors, Government Projects Material: Wood, Steel, Concrete, Composite Materials Feature: Sustainable Design, Smart Home Technology, Energy Efficiency, Customizable Layouts |
| Companies Covered | LINQ, Karmod, Bespoke Modular Solutions, Speed House Group of Companies, Al Bait Al Raqi, Red Sea International Company, Masah Al Murabaa Prefab Houses Ind LLC, Al Arab Prefab Houses, Liberty Building System, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Manufactured Homes Market Evolving Landscape
Digital fabrication and regulatory tightening are converging to redefine product specifications and procurement protocols across the Emirates manufactured housing sector.
Building Information Modeling (BIM) integrated with automated CNC cutting systems is automating steel-frame production workflows in Dubai-based factories. Developers of labor accommodation zones in Jebel Ali and Al Quoz are adopting these platforms to compress design-to-delivery cycles from 16 weeks to under 10 weeks. This automation is enabling mass customization of unit layouts without sacrificing line-speed economics.
Dubai Municipality's mandatory green building ratings for new residential developments are elevating thermal performance requirements for envelope assemblies. Manufacturers must now demonstrate compliance with specified U-values for wall and roof systems through third-party testing. High-end residential buyers in Dubai Hills and Al Reem Island are prioritizing certified units, creating a two-tier market split between code-minimum and premium-efficiency product lines.
Direct procurement from factory operators is displacing traditional general contractor intermediaries in government housing programs. Abu Dhabi's worker housing authorities now issue design-build contracts to modular specialists, compressing margin stacks and accelerating accountability. This channel restructuring is most advanced in Mohammed bin Zayed City and Mussafah industrial zones, where consolidated purchasing power favors vertically integrated suppliers with in-house engineering and installation capabilities.
UAE Manufactured Homes Market Segmentation
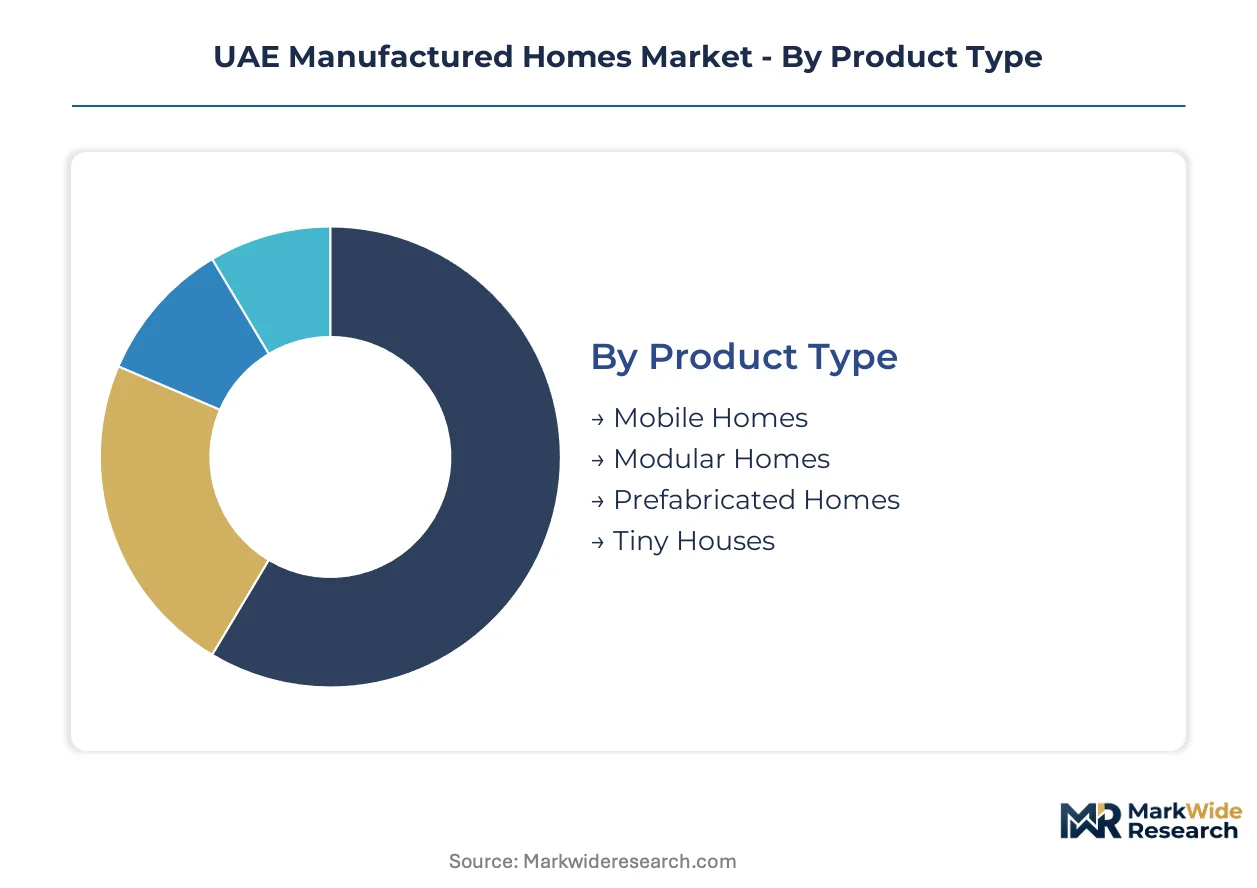
Segmentation in the UAE manufactured homes market reveals distinct procurement patterns across product architectures, buyer categories, and performance specifications. Each dimension carries implications for ESMA compliance pathways, financing eligibility, and installation labor requirements.
Product Type:
Standardization dominates at the volume end while customization concentrates in premium residential corridors.
- Mobile Homes:Semi-permanent units mounted on transportable chassis with limited foundation anchoring. Demand concentrates in temporary worker accommodation zones around Jebel Ali and Al Quoz where ESMA's permanent foundation requirement restricts mortgage access.
- Modular Homes:Factory-built sections assembled on permanent foundations meeting MOHAP's updated building code for full financing eligibility. Abu Dhabi's affordable housing corridors and Dubai Hills residential developments drive specification requirements for steel-frame construction with insulated panel envelopes.
- Prefabricated Homes:Complete dwelling units manufactured off-site to local wind-load and seismic specifications.
- Tiny Houses:Compact sub-400 square foot units targeting single occupants and hospitality micro-developments.
Leading the category by volume: Modular Homes. Growing fastest: Tiny Houses.
End User:
Government procurement scales drive factory capacity planning while private buyers prioritize feature customization.
- Residential Buyers:Individual purchasers in Dubai Hills and Al Reem Island seeking mortgage-eligible permanent housing with smart home integration and customizable layouts. DEWA's digital infrastructure rollout shapes technology expectations for remote climate management.
- Government Projects:Federal and emirate-level housing authorities under UAE Vision 2031 mandating prefabricated solutions for worker accommodation programs. Direct design-build contracts to modular specialists compress procurement timelines in Mohammed bin Zayed City and Mussafah industrial zones.
- Construction Companies:General contractors and project developers sourcing modular units for site offices and labor camps.
- Investors:Institutional and private capital deploying manufactured housing for rental yield portfolios.
Government Projects anchor procurement volume. Residential Buyers command premium pricing tiers.
Material:
Performance requirements and supply chain geography shape material selection across thermal, structural, and cost specifications.
- Steel:Galvanized steel frames with insulated panel envelopes dominate modular construction for permanent residential applications. Turkish and Chinese export tariff exposure creates margin volatility for frame manufacturers serving government contracts.
- Concrete:Reinforced concrete cores and foundation elements meeting seismic specifications for high-wind zones. In-house production of concrete-core systems anchors positioning for government contract eligibility.
- Wood:Timber framing limited by humidity degradation risks and fire resistance requirements under ESMA protocols.
- Composite Materials:Advanced panel systems combining thermal performance with reduced weight for transport efficiency.
Steel commands permanent residential share. Concrete governs government contract specifications.
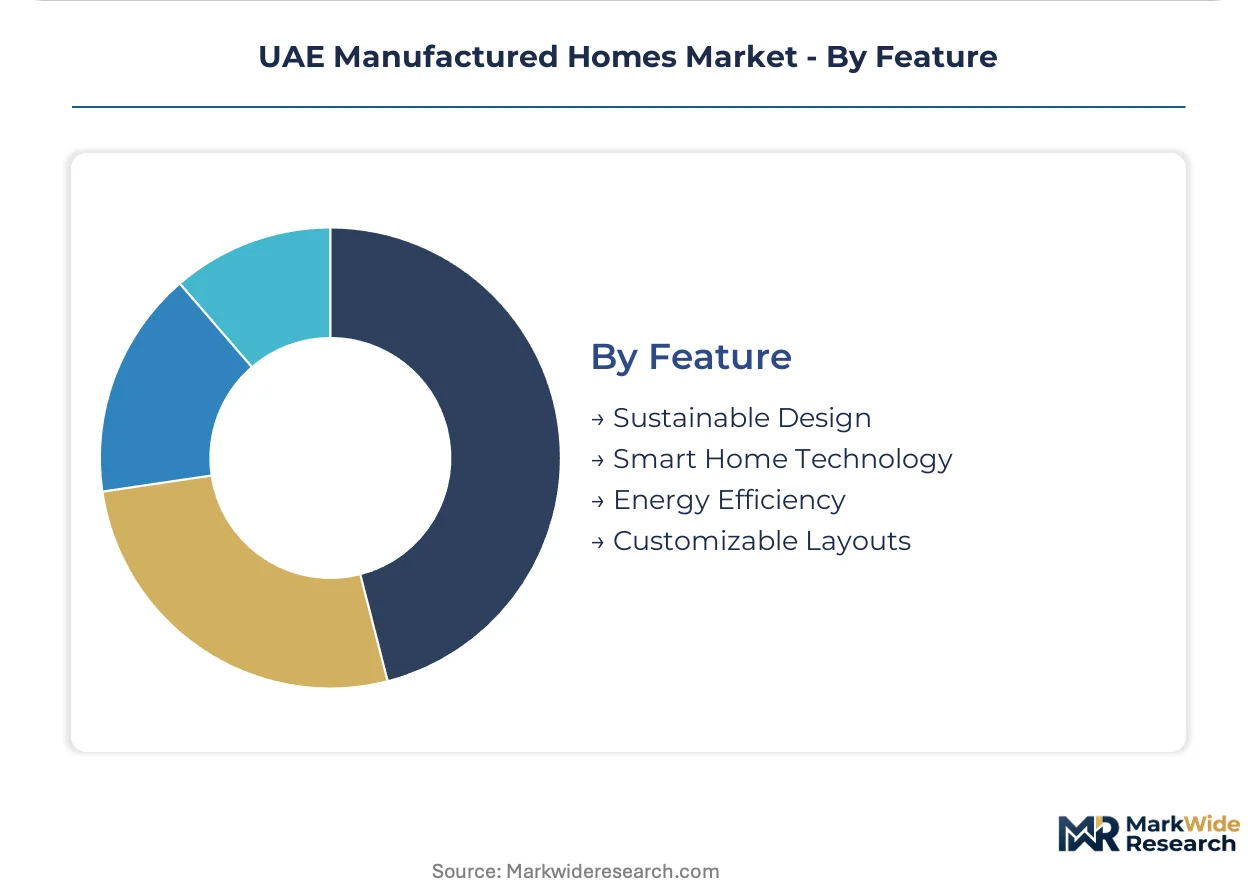
Feature:
Regulatory mandates and buyer expectations are bifurcating the market between code-minimum and premium-efficiency product lines.
- Smart Home Technology:IoT-enabled energy management, remote climate control, and integrated security systems. DEWA's digital infrastructure rollout and buyer expectations for remote management are compressing delivery timelines while elevating technical requirements.
- Sustainable Design:Solar-integrated roofs, greywater systems, and certified thermal envelopes meeting Dubai Municipality's mandatory green building ratings. Third-party U-value testing creates compliance gates for envelope assemblies.
- Energy Efficiency:Insulation specifications and HVAC optimization targeting 25-40% cooling load reduction.
- Customizable Layouts:BIM-enabled mass customization of unit configurations without sacrificing line-speed economics.
Sustainable Design carries regulatory weight. Smart Home Technology is climbing fastest in buyer prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Khalifa Industrial Zone Abu Dhabi (KIZAD) and Dubai Industrial City anchor modular manufacturing capacity through bonded warehousing, streamlined customs, and proximity to port infrastructure serving Gulf markets.
Dubai
Dubai Hills and Al Reem Island residential corridors drive specification requirements for mortgage-eligible modular units with smart home integration. Dubai Municipality mandates green building ratings for new residential developments. Jebel Ali and Al Quoz industrial zones concentrate factory-built housing production for labor accommodation programs.
Abu Dhabi
Mohammed bin Zayed City and Mussafah industrial zones channel government procurement toward steel-frame modular solutions under UAE Vision 2031 housing targets. MOHAP's updated building code legitimizes factory-built structures for permanent residential financing. Khalifa Industrial Zone hosts assembly facilities serving worker housing authorities with direct design-build contracts.
Sharjah
Undersupply of dedicated modular manufacturing capacity creates first-mover opportunity for domestic assembly investment. The emirate's national housing program channels demand toward affordable prefabricated solutions. Industrial areas near Sharjah International Airport concentrate logistics and distribution nodes for Northern Emirates supply.
Northern Emirates
Ras Al Khaimah and Fujairah lack indigenous factory-built housing production, forcing reliance on Dubai and Abu Dhabi suppliers. Federal affordable housing mandates extend procurement reach into these corridors. Coastal industrial zones in Ras Al Khaimah are attracting warehousing investment to support regional distribution.
UAE Manufactured Homes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated structure where government contract eligibility separates scale players from niche operators. Market concentration favors vertically integrated suppliers with in-house engineering and installation capabilities. Three archetypes dominate: Turkish-manufacturing-anchored exporters, domestic concrete-core system producers, and customizable-layout specialists targeting premium residential buyers. Competitive moves center on backward integration into steel-frame production and strategic positioning for direct procurement contracts bypassing traditional general contractor intermediaries.
Among Turkish-manufacturing-anchored exporters, Karmod occupies a position exemplifying offshore production leverage into UAE government housing programs. Speed House Group of Companies and Bespoke Modular Solutions represent contrasting archetypes—one anchored in concrete-core systems for institutional contracts, the other in customizable configurations for high-end residential corridors. These three players illustrate the strategic segmentation between scale-driven government procurement and premium-tier customization.
| Leading Market Players |
|---|
| LINQ |
| Karmod |
| Bespoke Modular Solutions |
| Speed House Group of Companies |
| Al Bait Al Raqi |
| Red Sea International Company |
| Masah Al Murabaa Prefab Houses Ind LLC |
| Al Arab Prefab Houses |
| Liberty Building System |
| Others |
Value Network & Pricing Analysis
Galvanized steel coil indices from Turkish and Chinese export markets cascade through UAE manufactured housing supply chains, compressing margins for frame manufacturers while creating three-tier pricing stratification across premium-certified, standard-code, and economy-grade product lines.
Pricing Analysis
Lead-time premiums for sub-10-week delivery compress procurement budgets in government housing programs, while spot inventory of standard steel-frame units trades at modest discounts. Pricing stratifies across premium, standard, and economy tiers based on ESMA certification grade and volume scale, with customization level and after-sales service bundling driving further differentiation. Cost compression in economy-grade segments is intensifying because of Turkish export tariff exposure. Government procurement authorities show lowest price sensitivity due to mandate-driven volume commitments, while individual residential buyers in Dubai Hills exhibit highest sensitivity to per-square-meter differentials.
Supply Chain Analysis
Regional distribution centers in Dubai Industrial City and Khalifa Industrial Zone Abu Dhabi anchor hub-and-spoke patterns serving Northern Emirates corridors. Manufacturing concentrates in Turkey, China, and domestic UAE assembly facilities. Raw material flows draw from galvanized steel coil producers, insulated panel system manufacturers, and HVAC module suppliers. Single-source vulnerability in Red Sea shipping lanes for Turkish and Saudi component imports creates structural risk exposure. Distribution runs through direct design-build contracts to government housing authorities, displacing traditional general contractor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAE manufactured housing is becoming a vertical-integration race where captive control over steel-frame production and installation labor separates scale winners from margin-squeezed assemblers.
For Market Incumbents: Extend backward integration into galvanized steel coil processing to insulate margin positions from Turkish and Chinese tariff volatility. Secure certified rigging crew capacity in Dubai Industrial City before skilled installation labor scarcity worsens in emerging Northern Emirates corridors. Anchor government contract eligibility through in-house concrete-core system production.
For New Entrants and Emerging Players: MOHAP's updated building code for modular structures in the UAE opens a window for Sharjah and Ras Al Khaimah first-mover assembly facilities. Target undersupplied Northern Emirates corridors where logistics costs from Dubai and Abu Dhabi suppliers create localization premiums. Pursue direct procurement relationships with federal affordable housing authorities under UAE Vision 2031 mandates.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists with captive steel-frame production and ESMA certification infrastructure in Abu Dhabi industrial zones. Long-term viability hinges on positioning for green building rating premiums as Dubai Municipality mandates tighten. Watch for ESMA conformity assessment timeline compression as an inflection signal for factory-built housing acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel-Frame Production | Captive supply of galvanized steel coils insulates margin positions from Turkish and Chinese tariff exposure. |
| Green Building Certification Investment | Dubai Municipality's mandatory sustainability ratings expand margin pools for solar-integrated and greywater-equipped units. |
| Direct Design-Build Contracting | Abu Dhabi worker housing authorities now bypass general contractors, compressing procurement timelines. |
| Smart Home Technology Platform Integration | DEWA's digital infrastructure rollout elevates buyer expectations for IoT-enabled climate and security management. |
| Northern Emirates Assembly Facility Expansion | Sharjah and Ras Al Khaimah undersupply creates first-mover advantage for domestic modular manufacturing capacity. |
Research Methodology
ESMA conformity assessment protocols, Dubai Municipality building permit databases, and Turkish export trade statistics formed the secondary backbone, supplemented by primary interviews with modular factory operations directors, government housing procurement officers, steel-frame engineering leads, and DEWA infrastructure planners. Bottom-up unit shipment data from KIZAD and Dubai Industrial City bonded warehouses combined with top-down federal affordable housing mandate analysis. Triangulation across primary stakeholder inputs and secondary validation anchored volume and value estimates.
Bottom-up modeling tracked product type, end user category, material specification, and feature tier dimensions across the projection horizon. Top-down analysis stress-tested aggregate market size against UAE Vision 2031 housing targets and MOHAP building code expansion timelines. CAGRs derived from segment-level unit economics and financing eligibility evolution. Forecast inputs incorporated ESMA certification timeline compression scenarios and DEWA smart grid infrastructure rollout pacing.
The model assumes a particular technology adoption path; alternative pathways for concrete additive manufacturing in foundation elements would alter the outlook for traditional cast-in-place construction displacement. Forecasts reflect assumptions regarding Turkish steel export tariff stability and Red Sea shipping lane reliability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
North America Residential Construction Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
UK Residential Construction Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Swimming Pool Construction Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
Germany Residential Construction Market
Residential Construction
Japan Residential Construction Market