
 Asia-Pacific Prefabricated Housing Market | 2026-2036
Asia-Pacific Prefabricated Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Prefabricated Housing Market Outlook
Aftermarket service revenue is fragmenting as manufacturers compete for recurring maintenance contracts and retrofit upgrades across installed prefabricated housing bases. Toyota Housing Corporation leverages its dealership network to capture long-term service relationships. Daiwa House Industry anchors margin pools through integrated facility management offerings. Sekisui House differentiates by controlling the full lifecycle from factory production to post-occupancy energy monitoring.
Prefabricated housing encompasses factory-built structural units assembled from standardized panels, modular volumetric sections, or precast concrete elements with specified fire ratings and thermal performance values, then transported to sites for installation. The primary purpose is compressing construction schedules while achieving repeatable quality control absent from traditional stick-built methods. Modular homes and steel-frame systems dominate volume in Japan and Australia where labor scarcity elevates factory automation economics. Panelized homes compete aggressively in India's cost-sensitive tier-two cities where on-site finishing trims logistics exposure. Prefab concrete occupies the emergency housing and government project channels across Southeast Asia due to durability perceptions and rapid deployment capacity.
Japan's METI enforces seismic performance benchmarks that effectively filter out non-compliant foreign suppliers while accelerating domestic factory innovation. Australia's National Construction Code and India's BIS certification for precast concrete elements create layered compliance costs that reshape competitive positioning among regional and multinational firms. China's GB standards for modular building materials, administered by SAMR, constrain import penetration while subsidizing local steel-frame ecosystem development. Stakeholders must track how evolving green building mandates across the region recalibrate material specifications and factory capital deployment timelines.
Market Dynamics
Japan's METI seismic resilience mandates are compressing supplier qualification timelines while simultaneously filtering out non-compliant foreign manufacturers from government procurement channels.
Growth Catalysts
- Seismic Performance Mandates:Japan's METI building codes now require steel-frame and modular panel systems to meet specific resilience benchmarks, accelerating factory innovation among domestic producers.
- Affordable Housing Procurement:Southeast Asian governments are expanding mass housing programs that favor prefab concrete for rapid deployment and durability in tropical climates.
- Urban Corridor Density:India's tier-one and tier-two cities face acute worker housing shortages that compress construction schedules and elevate factory-built solutions over stick-built methods.
Market Restraints
- Steel Price Volatility:Input cost swings for structural steel and rebar compress margins for steel-frame system manufacturers across Australia and Japan.
- Compliance Layering:Australia's National Construction Code and India's BIS certification for precast concrete elements impose overlapping testing requirements that extend product approval cycles.
- Site Labor Dependency:Panelized systems in cost-sensitive Indian markets still require substantial on-site finishing, limiting logistics savings versus volumetric modular alternatives.
Strategic Opportunities
- Integrated Facility Management:Post-occupancy service contracts for energy monitoring and retrofit upgrades represent recurring revenue pools currently underexploited by most factory builders.
- Emergency Housing Channels:Southeast Asian disaster response agencies are formalizing rapid-deployment procurement frameworks for prefab concrete shelters.
- Green Building Alignment:Evolving energy efficiency mandates across Singapore, South Korea, and Japan recalibrate material specifications toward high-performance thermal panels.
Industry Challenges
- Skilled Installation Shortage:Volumetric module crane operators and precision alignment technicians remain scarce in Australia's remote construction sites.
- Certification Bottlenecks:Cross-border recognition of factory quality systems between Japan's JIS standards and Australia's NCC compliance pathways remains fragmented.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Prefabricated Housing Market |
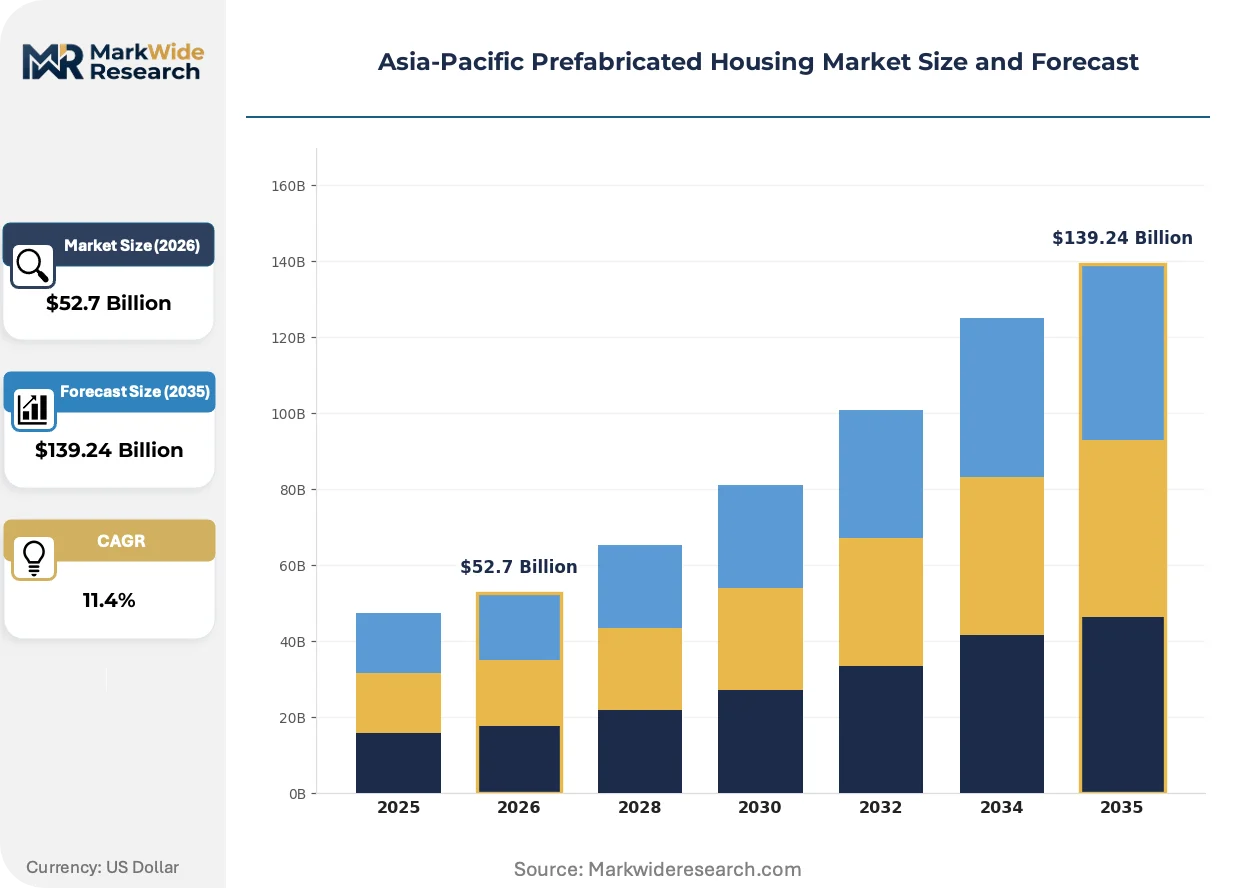
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Prefab Concrete, Steel Frame Delivery Mode: On-Site Construction, Off-Site Manufacturing, Hybrid Solutions, Custom Designs End User: Residential Buyers, Commercial Developers, Government Projects, Non-Profit Organizations Application: Single Family, Multi-Family, Vacation Homes, Emergency Housing |
| Companies Covered | Toyota Housing Corporation, Broad Group, Daiwa House Industry, Ausco Modular, Larsen & Toubro, Sekisui House, Ichijo, China State Construction Engineering Corporation, Panasonic Homes, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Prefabricated Housing Market Strategic Shifts
Factory automation economics are compressing production timelines while digital twin integration is reshaping how builders coordinate design-to-installation workflows across dispersed project sites.
Cross-laminated timber and engineered bamboo composites are migrating from niche sustainable projects to mainstream mid-rise residential construction in Australia and Japan. Institutional developers in Melbourne and Sydney are specifying these materials for five-story apartment blocks. The shift is migrating from boutique environmental certification targets toward cost-competitive structural performance.
China's GB standards for modular building materials, administered by SAMR, are tightening import constraints while subsidizing domestic steel-frame ecosystem development. Foreign suppliers face additional factory audit requirements for structural connection hardware. The policy is forcing regional manufacturers to establish captive production within China's free trade zones or exit the market.
Long-term service contracts are unbundling from initial equipment sales as buyers demand outcome-based facility management. Japanese housing corporations now bundle energy performance guarantees with modular home purchases. The model is visible across Tokyo's suburban corridors where post-occupancy monitoring drives repeat procurement decisions.
Asia-Pacific Prefabricated Housing Market Segmentation
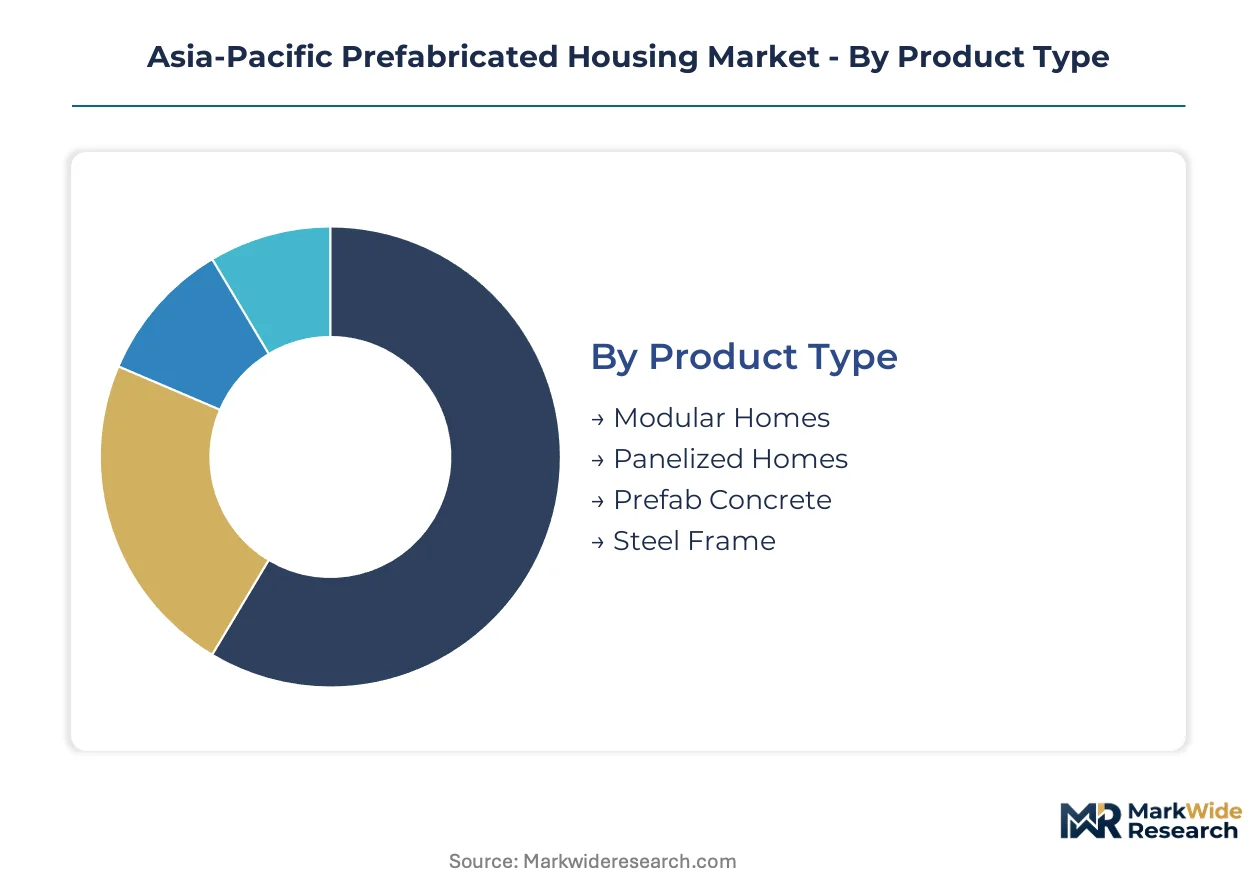
Segmentation in prefabricated housing reveals how factory production methods, delivery logistics, and buyer procurement patterns create distinct margin profiles. Each category exposes different competitive intensities and aftermarket service opportunities across the Asia-Pacific region.
Product Type:
After-sales-service intensity varies sharply by structural system, with volumetric modular units demanding ongoing facility management while panelized systems require periodic thermal performance audits.
- Modular Homes:Factory-built volumetric sections arrive 80-95% complete, requiring only foundation connection and utility hookup. Demand concentrates in Japan's seismic zones where METI-mandated steel-frame resilience standards favor precision factory welding over site assembly.
- Panelized Homes:Wall and roof panels ship flat-packed for on-site erection, trimming transport costs for India's tier-two urban corridors where road infrastructure limits module dimensions. On-site finishing dependency constrains total cost savings versus volumetric alternatives.
- Prefab Concrete:Precast structural elements with specified compressive strength ratings dominate Southeast Asian government housing tenders. Tropical durability perceptions drive procurement from disaster response agencies across Indonesia and the Philippines.
- Steel Frame:Light-gauge and structural steel systems anchor Japan's suburban residential construction, with JIS-certified connection hardware filtering non-compliant imports. Australia's remote mining camps specify corrosion-resistant galvanized frames for rapid deployment cycles.
By volume, Panelized Homes leads. By growth pace, Modular Homes is ahead.
Delivery Mode:
Supply chain configuration determines which delivery modes capture margin in high-labor-cost versus low-infrastructure markets across the region.
- On-Site Construction:Traditional stick-built methods persist where local labor costs undercut factory automation economics, particularly in India's rural districts with abundant construction workforces.
- Off-Site Manufacturing:Centralized factory production with quality-controlled environments dominates Australia's remote project sites where skilled trades scarcity elevates prefabrication premiums. Volume concentration in Melbourne and Sydney factory clusters.
- Hybrid Solutions:Partial factory pre-assembly combined with localized finishing balances logistics exposure against customization flexibility. Emerging preference among South Korean developers for mid-rise residential blocks.
- Custom Designs:Architect-specified non-standard configurations command pricing premiums in Japan's high-end suburban markets where buyers prioritize aesthetic differentiation over volume efficiency.
Off-Site Manufacturing commands the revenue pool. Hybrid Solutions are expanding most quickly.
End User:
Procurement sophistication and contract scale separate end-user segments, with government tenders demanding lifecycle cost guarantees unavailable to residential buyers.
- Residential Buyers:Individual purchasers prioritize mortgage accessibility and customization options, concentrating in Japan's first-time buyer corridors and Australia's outer suburban rings.
- Commercial Developers:Institutional builders specify repeatable designs for multi-unit rental portfolios, with Singapore's REIT-driven residential development favoring standardized modular specifications.
- Government Projects:Mass housing tenders across Indonesia, Vietnam, and the Philippines mandate durability certifications and rapid deployment capacity, channeling volume toward prefab concrete suppliers.
- Non-Profit Organizations:Disaster relief and social housing providers operate on constrained budgets with accelerated timelines, sourcing from regional factory networks with established humanitarian procurement frameworks.
Government Projects anchor procurement volume. Commercial Developers are gaining share fastest.
Application:
Application segments diverge by construction timeline pressure and regulatory scrutiny, with emergency housing bypassing standard approval cycles that constrain permanent residential development.
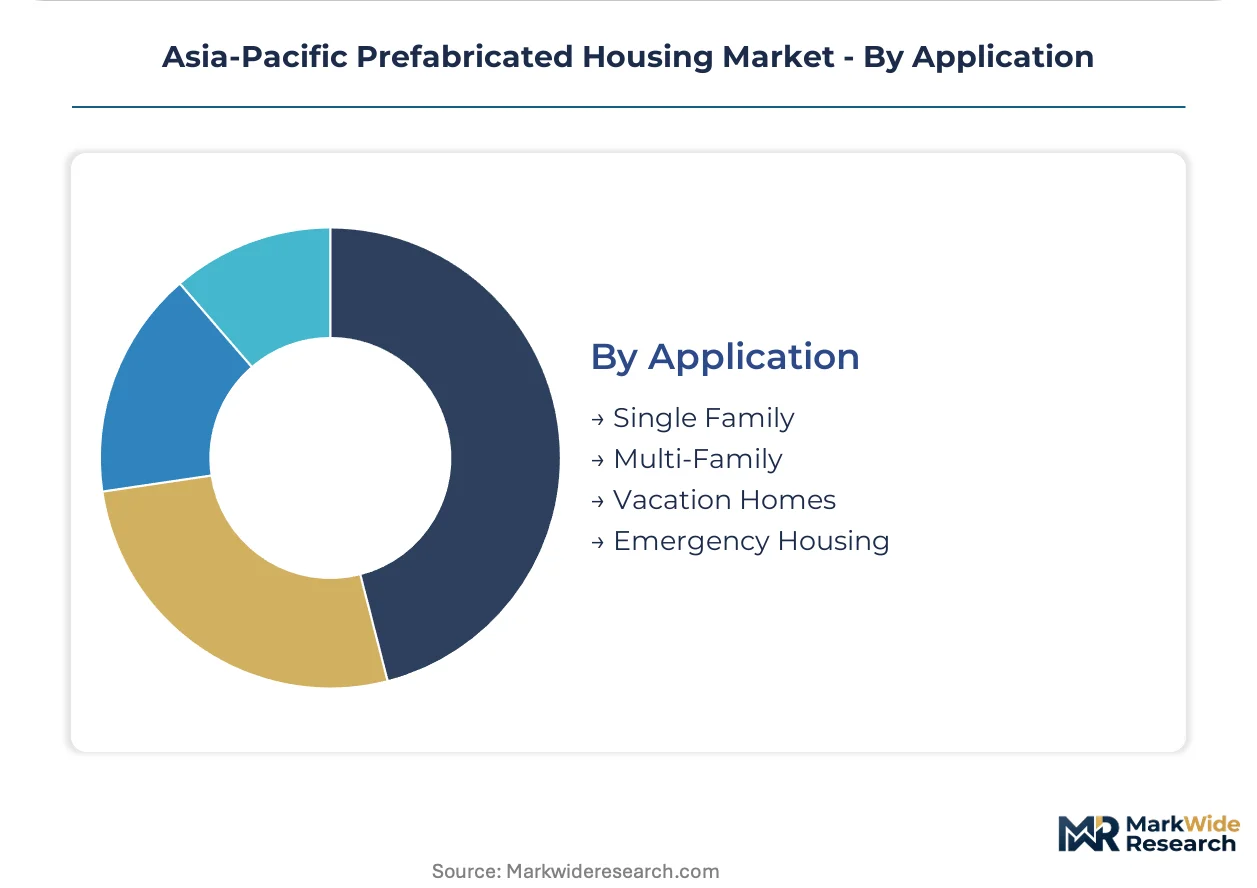
- Single Family:Detached dwellings dominate Australia's prefabrication uptake, where labor scarcity and remote site access costs compress factory-built economics against traditional construction.
- Multi-Family:Mid-rise apartment blocks in Tokyo and Osaka specify modular bathroom pods and kitchen units to accelerate critical-path schedules on constrained urban sites.
- Vacation Homes:Seasonal and secondary residences in New Zealand's coastal zones and Japan's ski regions favor lightweight panelized systems for difficult terrain access.
- Emergency Housing:Rapid-deployment shelters for cyclone and earthquake response across Southeast Asia require minimal foundation preparation, with prefab concrete dominating durability specifications.
Multi-Family leads by installed base. Emergency Housing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan deploys volumetric steel-frame systems for seismic resilience, while India favors flat-packed panels to navigate constrained logistics corridors. Australia's remote mining camps drive off-site manufacturing premiums distinct from Southeast Asia's government concrete tenders.
Japan
Seismic retrofit demand and suburban densification propel factory-built housing adoption. METI building codes mandate specific resilience benchmarks for steel-frame and modular panel systems. Toyota Housing Corporation and Sekisui House anchor production clusters across the Kanto corridor, shipping precision-welded volumetric units nationwide.
India
Urban corridor worker housing shortages compress construction timelines for mass residential projects. BIS certification requirements for precast concrete elements reshape supplier qualification pathways. Larsen & Toubro dominates factory deployment across Maharashtra and Gujarat, supplying prefab concrete for government-subsidized housing schemes.
Australia
Remote site access costs and skilled trades scarcity elevate off-site manufacturing economics. The National Construction Code imposes layered compliance testing that extends product approval cycles. Ausco Modular anchors capacity in Victoria and Queensland, serving mining camp and emergency housing procurement channels.
China
Modular building material standardization accelerates domestic steel-frame ecosystem development. SAMR-administered GB standards constrain import penetration through additional factory audit requirements. Broad Group and China State Construction Engineering Corporation concentrate production in Yangtze River Delta free trade zones, capturing subsidized procurement flows.
Indonesia
Disaster response agencies formalize rapid-deployment frameworks for emergency shelter procurement. Tropical durability requirements channel volume toward prefab concrete suppliers. State-backed housing programs in Java and Sumatra specify compressive strength ratings for mass residential tenders, filtering panelized system competitors.
Asia-Pacific Prefabricated Housing Market Competitive Environment
Capability concentration sits with integrated Japanese housing corporations; scale advantage sits with Chinese state-backed construction enterprises. The market structure tiered between lifecycle service bundlers, steel-frame precision specialists, and concrete volume producers. Strategic archetypes include facility management integrators, seismic compliance specialists, and government tender optimizers. Dominant competitive moves span backward integration into factory automation and geographic expansion through free trade zone production.
Among Japanese housing corporations, Toyota Housing Corporation, Daiwa House Industry, and Sekisui House exemplify the integrated lifecycle archetype. These Tokyo and Osaka-based entities occupy positions spanning factory production through post-occupancy energy monitoring, representing how domestic METI compliance mandates create protective competitive moats. Their dealership networks and facility management bundling anchor recurring revenue pools distinct from project-based competitors.
| Leading Market Players |
|---|
| Toyota Housing Corporation |
| Broad Group |
| Daiwa House Industry |
| Ausco Modular |
| Larsen & Toubro |
| Sekisui House |
| Ichijo |
| China State Construction Engineering Corporation |
| Panasonic Homes |
| Others |
Value Chain & Pricing Dynamics
Steel price volatility in Australia and Japan compresses margin spreads across steel-frame system tiers while simultaneously forcing supply chain reconfiguration toward captive fabrication capacity and regional raw material hedging.
Pricing Analysis
Long-term offtake contracts dominate procurement from Japanese housing corporations and Australian mining camp developers, insulating premium-tier suppliers from spot steel fluctuations. Pricing stratifies across JIS-certified premium systems, BIS-compliant standard concrete elements, and economy panelized units for India's cost-sensitive tier-two corridors. Cost compression in economy tiers intensifies as galvanized steel input costs outpace factory automation savings. Government tender channels exhibit lowest price sensitivity due to lifecycle durability mandates, while individual residential buyers in India's urban corridors drive aggressive economy-tier negotiation.
Supply Chain Analysis
Extended payment terms from Indonesian and Vietnamese government housing agencies strain working capital for prefab concrete suppliers, accelerating supply-chain finance facility adoption among Southeast Asian producers. Manufacturing gravity centers on Japan's Kanto corridor, China's Yangtze River Delta free trade zones, and India's Maharashtra-Gujarat industrial belt. Structural steel, engineered timber composites, and precast concrete admixtures constitute critical input dependencies. Single-source vulnerability concentrates in JIS-certified connection hardware for seismic-compliant Japanese systems. Distribution runs through factory-direct channels for volumetric modular units and regional distributor networks for flat-packed panelized systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory automation economics and METI seismic code evolution are compressing traditional construction timelines, creating asymmetric growth windows for integrated lifecycle service providers versus project-based competitors.
For Market Incumbents: Build regulatory compliance moats through JIS certification depth and BIS precast concrete accreditation. Deepen backward integration into factory automation tooling to offset steel price volatility exposure. Anchor recurring revenue through energy performance guarantee bundling that locks out modular competitors from post-occupancy service relationships. For New Entrants and Emerging Players: Australia's remote mining camp emergency housing channels offer underpenetrated procurement frameworks with compressed qualification timelines versus Japanese METI compliance pathways. Target Southeast Asian disaster response agency rapid-deployment tenders where prefab concrete durability specifications filter out established panelized competitors. Deploy hybrid delivery solutions combining partial factory pre-assembly with localized finishing to circumvent infrastructure constraints in India's tier-two urban corridors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors facility management integrators with captive factory networks over pure-play component suppliers. Five-to-ten year viability hinges on lifecycle service revenue capture rather than unit sales velocity. Monitor METI building code amendment cycles as inflection indicators for seismic resilience technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Captive supply of JIS-certified structural components insulates Japanese producers from import tariff exposure. |
| Facility Management Service Bundling | Toyota Housing Corporation's dealership networks convert one-time sales into recurring energy monitoring contracts. |
| Free Trade Zone Production Establishment | Broad Group's Yangtze River Delta positioning captures SAMR-subsidized procurement flows while circumventing GB standard import barriers. |
| Seismic Resilience R&D Investment | Daiwa House Industry's precision welding automation meets METI benchmarks that filter non-compliant foreign suppliers. |
| Emergency Housing Procurement Framework | Ausco Modular's disaster response agency relationships anchor volume through Indonesia's formalized rapid-deployment channels. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with prefabricated housing factory managers, government tender procurement officers, seismic engineering consultants, and facility management service directors. Secondary validation drew from METI building code filings, BIS certification registries, Australia's National Construction Code amendments, and customs trade data for structural steel and engineered timber imports. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts across the analysis window.
Calibration across historical production volumes and forward contract disclosures anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include structural system type, delivery mode configuration, end-user procurement sophistication, and application timeline pressure. CAGRs were derived from slope analysis of fitted trend lines against policy-inflected demand step-changes. Seismic code amendment schedules and affordable housing program procurement calendars constituted industry-specific forecast inputs.
Practitioners should monitor steel price volatility indices and METI regulatory amendment cycles for early signals of margin compression or compliance pathway disruption. Forecasts reflect assumptions regarding continued government housing program expansion and factory automation cost curves. Macroeconomic deviation in construction credit availability, regulatory acceleration in green building mandates, or technological displacement in panelized assembly methods would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
UK Manufactured Homes Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
US Residential Remodeling Market
Residential Construction
Residential Construction Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
Residential Roofing Market
Residential Construction
Siding Market
Residential Construction
Prefabricated Homes Market
Residential Construction
US Residential Construction Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
North America Bath Remodeling Market