
 Outdoor Living Structure Market | 2026-2036
Outdoor Living Structure Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Living Structure Market Intelligence
Aluminum is hardening its position against traditional wood across pergola and gazebo lines as tariff-adjusted pricing narrows the cost gap. Trex Company leverages its composite formulation expertise to sustain premium positioning in residential decking-adjacent structures. Lowe's Companies anchors North American distribution through contractor-centric fulfillment networks. Royal Building Products differentiates via vinyl-clad hybrid systems that compete on maintenance cycles rather than first cost.
An outdoor living structure is a permanent or semi-permanent architectural element designed to extend usable exterior space, typically fabricated from wood, metal, composite, or fabric assemblies rated for wind loads and UV exposure, and engineered to provide shade, shelter, or spatial definition for residential, commercial, or hospitality environments. Pergolas in composite materials command the fastest expansion as homeowners prioritize 25-year fade warranties over cedar's 8-12 year replacement horizon. Custom-built installation methods retain the deepest margin pools due to design consultation attach rates, while pre-fabricated metal canopies dominate volume in commercial hospitality rollouts where speed-to-open drives procurement.
EPA treated-wood standards and ICC-ES building code evaluations govern structural lumber certification, while OSHA workplace exposure limits shape manufacturing facility compliance costs for domestic producers. The EU Green Deal's embodied carbon thresholds are beginning to filter into import specifications for European-bound metal and composite systems. Stakeholders must monitor whether emerging state-level wildfire-resistant construction mandates in California and Colorado will accelerate metal substitution beyond current coastal corrosion-driven demand patterns.
Market Dynamics
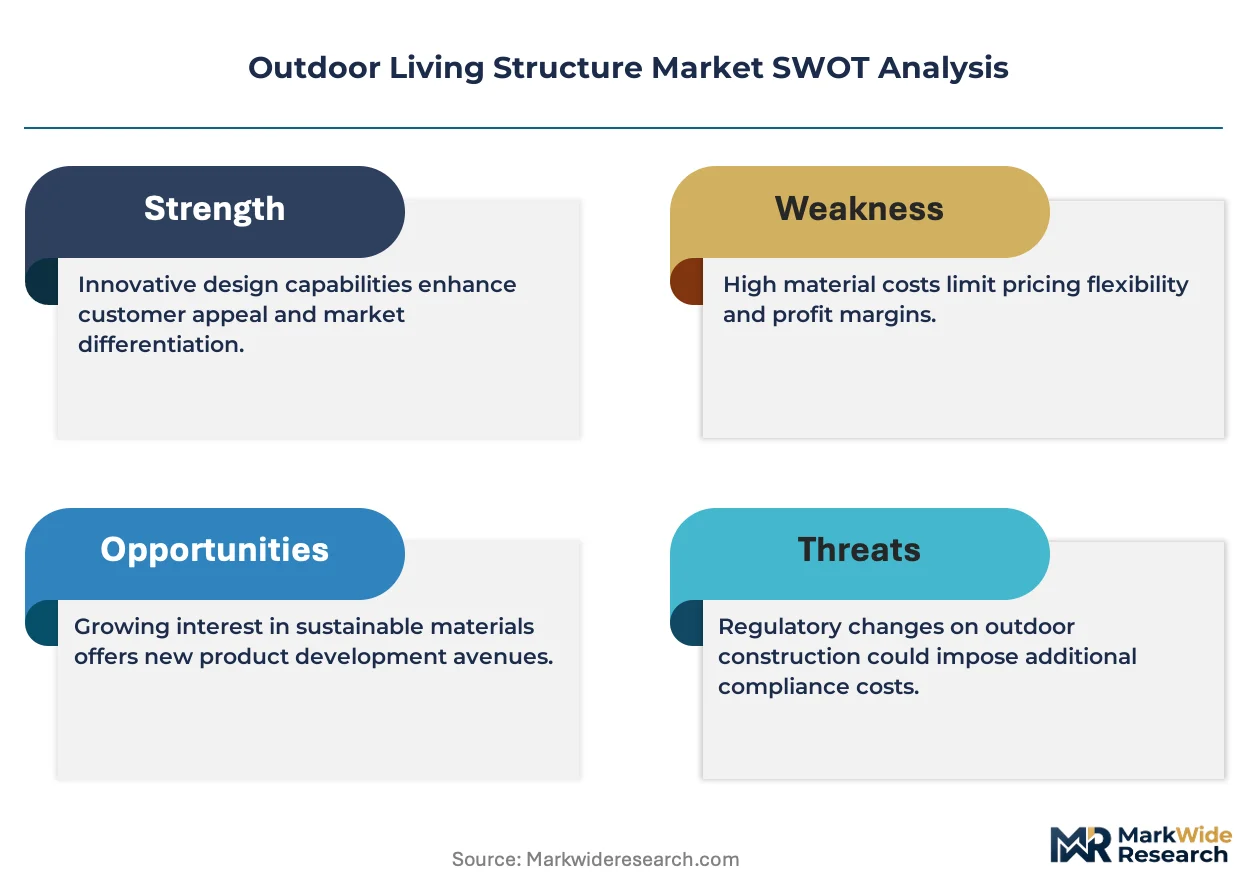
Tariff-adjusted aluminum pricing is compressing the traditional wood cost advantage across Sun Belt residential markets, while EPA treated-wood certification tightening simultaneously elevates compliance burdens for domestic lumber suppliers.
Growth Catalysts
- Suburban Residential Expansion:Sun Belt states with year-round outdoor usability are driving pergola and gazebo installations as homeowners prioritize extended entertaining spaces.
- Composite Material Warranties:25-year fade guarantees on engineered wood alternatives are displacing cedar's 8-12 year replacement cycle in premium residential segments.
- Commercial Hospitality Rollouts:Pre-fabricated metal canopy systems are capturing volume from custom-built methods where speed-to-open dictates procurement timelines.
Market Restraints
- Input Cost Volatility:Aluminum tariff adjustments and engineered resin pricing swings compress margin predictability for metal and composite fabricators.
- Regulatory Friction:EPA guidelines tightening material sourcing requirements extend certification timelines for domestic wood treatment facilities.
- Technical Limitation:Vinyl-clad hybrid systems face thermal expansion constraints in extreme temperature cycling environments, limiting geographic deployment.
Strategic Opportunities
- Wildfire-Resistant Mandates:Emerging California and Colorado state-level construction codes are accelerating metal substitution beyond coastal corrosion-driven demand.
- EU Green Deal Alignment:Embodied carbon thresholds filtering into European import specifications create premium positioning for low-carbon composite system exporters.
- Contractor-Centric Fulfillment:Design consultation attach rates in custom-built installation methods retain the deepest margin pools for specialized fabricators.
Industry Challenges
- Skilled Installation Shortage:Custom pergola and gazebo assembly requires specialized carpentry and metalworking expertise that regional contractor pools struggle to replenish.
- ICC-ES Evaluation Timelines:Building code certification delays for novel composite formulations extend product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Living Structure Market |
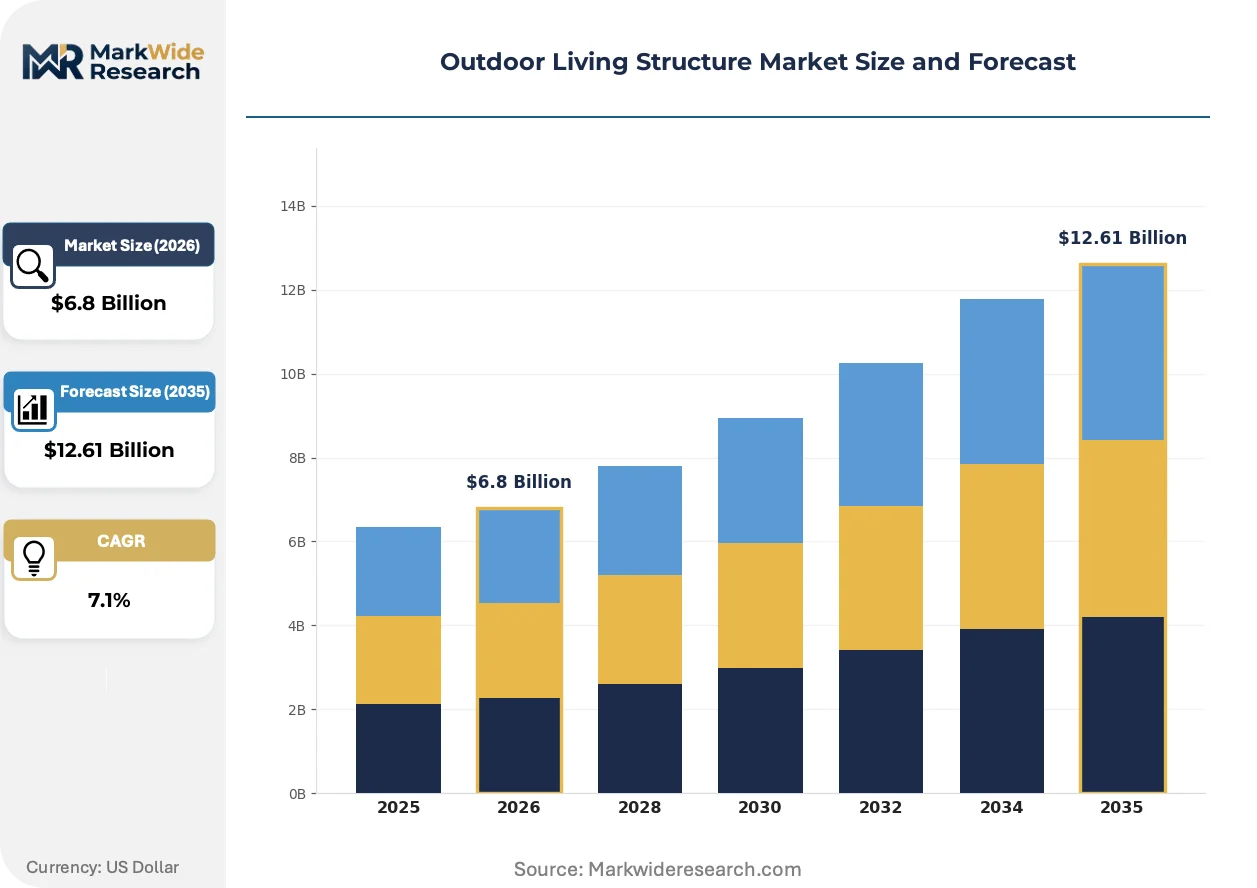
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.61 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pergolas, Gazebos, Arbors, Canopies Material: Wood, Metal, Composite, Fabric End User: Residential, Commercial, Hospitality, Public Spaces Installation Method: Pre-fabricated, Custom-built, DIY, Professional |
| Companies Covered | Lowe's Companies, Aluminum Company of America, Trex Company, Deckorators (UFP Industries), Royal Building Products, Masonite International Corporation, Azek Company, Latham, The Home Depot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Living Structure Market Strategic Shifts & Innovations
Material science advances and regulatory pressure on embodied carbon are converging to redefine competitive positioning across wood, metal, and composite fabrication lines.
Cross-laminated timber and thermally modified hardwood formulations are absorbing moisture-resistance and dimensional stability requirements previously met by pressure-treated lumber. Residential architects in Pacific Northwest and Northeast markets specify these alternatives to satisfy LEED v4.1 material ingredient reporting while avoiding EPA regulated wood preservatives. The technology is absorbing specification share from conventional cedar and redwood grades in high-humidity installations.
OSHA workplace exposure limits for wood dust and formaldehyde emissions are elevating capital expenditure requirements for domestic manufacturing facilities. Fabricators must install enhanced ventilation and monitoring systems to maintain compliance, compressing operating margins for mid-scale producers. Metal and composite-focused facilities face lighter compliance burdens, tilting new capacity investment toward aluminum extrusion and resin compounding operations.
Homeowner preference for maintenance-cycle certainty over first-cost minimization is restructuring channel economics. Big-box retailers emphasize contractor referral programs and extended warranty attach rates, while direct-to-consumer brands invest in augmented reality design tools that reduce consultation friction. This behavioral shift concentrates margin capture in the Sun Belt states where outdoor structure utilization rates justify premium positioning.
Outdoor Living Structure Market Segmentation
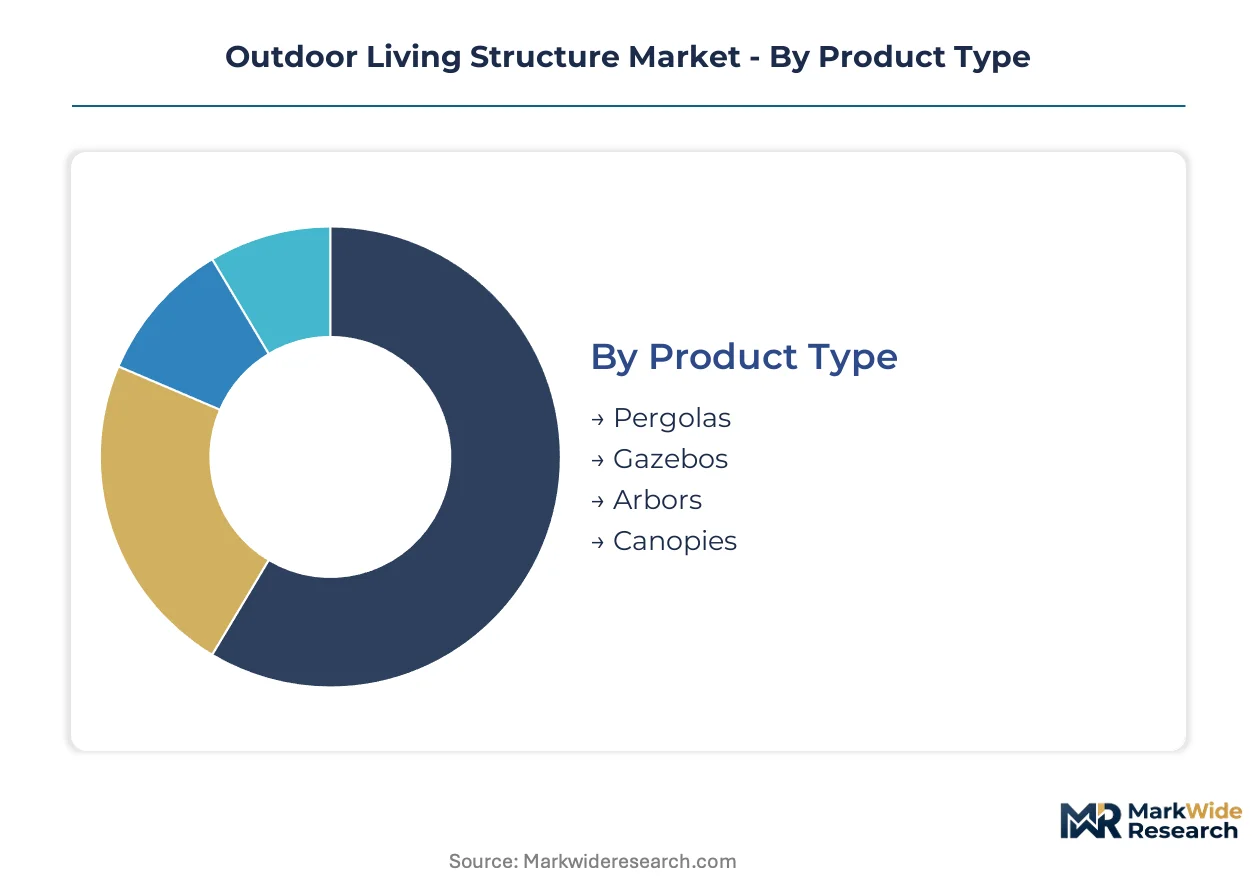
Outdoor living structures fragment across four critical dimensions that determine manufacturing scale, margin capture, and channel strategy. Product type and material selection govern production economics, while end-user verticals and installation methods dictate fulfillment complexity and customer acquisition costs.
Product Type:
Supply concentration in pergola and gazebo fabrication dominates volume, with arbor and canopy specialists occupying niche positions requiring different tooling and distribution partnerships.
- Pergolas:Open-roof lattice structures engineered for partial shade and architectural definition, typically spanning 10-20 feet. Sun Belt residential markets absorb the highest concentration as homeowners prioritize extended entertaining spaces with integrated lighting and ceiling fan mount points.
- Gazebos:Fully enclosed or semi-enclosed pavilion structures with integrated roofing systems rated for snow loads and wind uplift. Commercial hospitality rollouts in Florida, Texas, and Arizona drive procurement where speed-to-open timelines favor pre-engineered systems over site-built alternatives.
- Arbors:Smaller-scale tunnel or gateway structures designed for garden entryways and vertical plant support. Residential landscape architects in Pacific Northwest markets specify these for LEED v4.1 material ingredient compliance.
- Canopies:Tensile fabric or metal roof systems emphasizing rapid deployment and seasonal flexibility. Hospitality pool decks and restaurant patios favor these for code-compliant temporary coverage without permanent foundation requirements.
Today's leader: Pergolas. Tomorrow's challenger: Gazebos.
Material:
Cost tier stratification separates premium composite systems from commodity pressure-treated lumber, with metal and fabric occupying intermediate positions shaped by tariff exposure and maintenance-cycle tradeoffs.
- Wood:Pressure-treated southern yellow pine, cedar, and redwood grades governed by EPA certification standards. Domestic lumber suppliers face tightening compliance timelines that extend certification cycles and elevate working capital requirements.
- Metal:Aluminum extrusion and powder-coated steel systems capturing share from traditional wood as tariff-adjusted pricing narrows the cost gap. Coastal corrosion resistance and emerging wildfire-resistant mandates in California and Colorado accelerate specification.
- Composite:Engineered wood-plastic formulations offering 25-year fade warranties that displace cedar's 8-12 year replacement horizon in premium residential segments.
- Fabric:PVC-coated polyester and acrylic canvas assemblies rated for UV degradation and mold resistance. Seasonal hospitality applications favor these for storage flexibility and lower first-cost positioning.
Composite systems command the steepest expansion trajectory as warranty certainty displaces first-cost minimization in homeowner calculus.
End User:
Application concentration in residential suburban expansion drives volume, while hospitality and commercial verticals concentrate margin through design consultation attach rates and speed-to-open premiums.
- Residential:Single-family homeowners in suburban Sun Belt markets expanding outdoor entertaining spaces. Composite pergola demand concentrates here as 25-year fade warranties justify premium positioning over cedar alternatives.
- Commercial:Restaurant, retail, and office campus installations prioritizing code compliance and maintenance-cycle predictability. Pre-fabricated metal canopy systems dominate procurement where speed-to-open dictates vendor selection.
- Hospitality:Hotel, resort, and entertainment venue rollouts requiring durable structures with integrated amenity mounting. Volume procurement runs through contractor-centric fulfillment networks with extended warranty requirements.
- Public Spaces:Municipal park, trailhead, and community gathering installations subject to competitive bidding and prevailing wage requirements. Wood alternatives face specification pressure from EU Green Deal embodied carbon thresholds filtering into public procurement guidelines.
Residential volume anchors fabrication scale. Hospitality margins attract specialized fabricators with design-build capabilities.
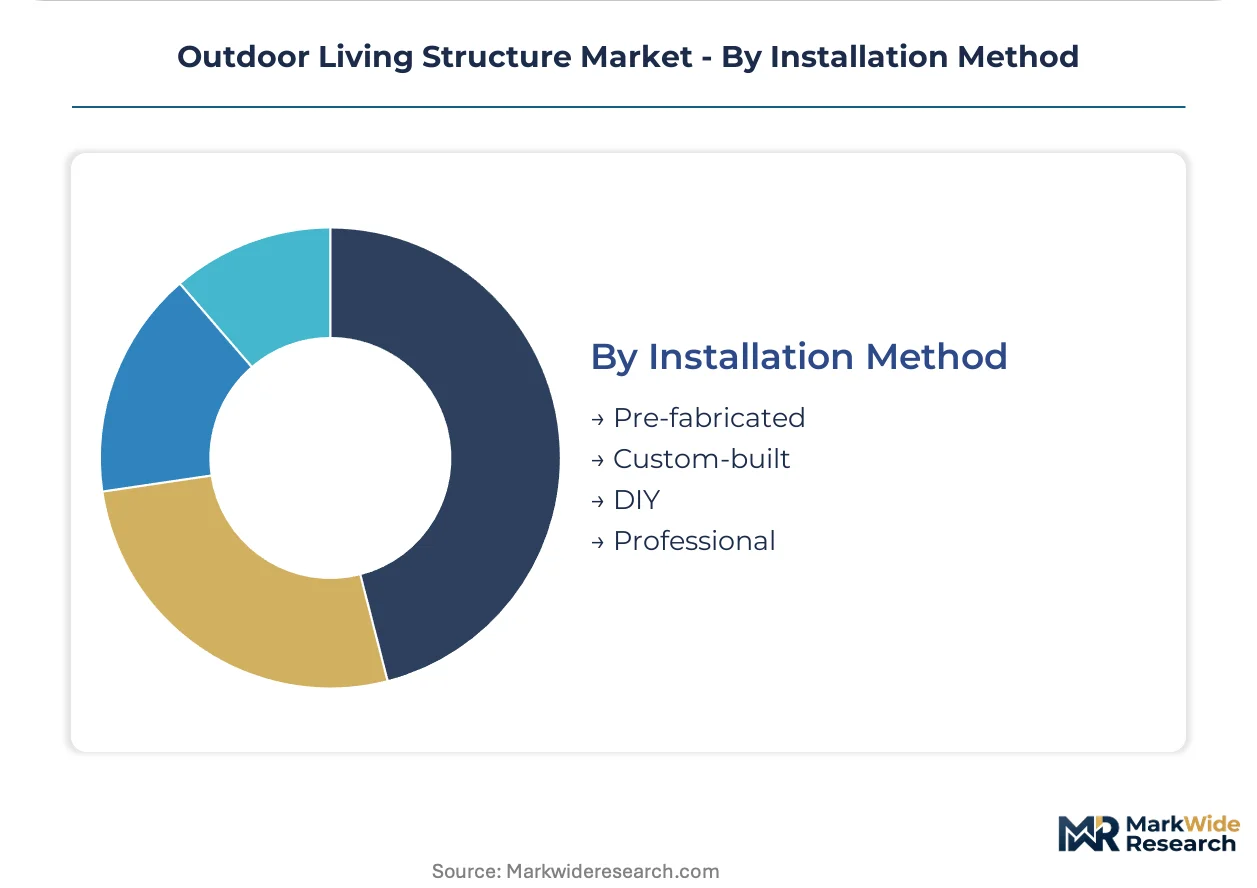
Installation Method:
Customer type segmentation separates professional contractor channels from direct-to-consumer fulfillment, with margin depth correlating to design consultation complexity and permitting navigation.
- Pre-fabricated:Factory-engineered modular systems delivered for rapid site assembly with minimal specialized labor. Commercial hospitality rollouts favor these where speed-to-open compresses project timelines.
- Custom-built:Site-specific design and fabrication capturing deepest margin pools through architectural consultation attach rates. Skilled installation shortage in regional contractor pools constrains capacity expansion.
- DIY:Retail-packaged kits with simplified assembly instructions targeting homeowner self-installation. Big-box retailers emphasize contractor referral programs for structural modifications requiring permit compliance.
- Professional:Turnkey design-build services encompassing permitting, foundation work, and integrated utility rough-ins. Custom pergola and gazebo assembly requires specialized carpentry and metalworking expertise that regional markets struggle to replenish.
Professional installation retains margin concentration. Pre-fabricated methods capture volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sun Belt corridor stretching from Florida through Texas anchors fabrication capacity and demand concentration for residential pergola and gazebo installations, with suburban expansion driving year-round outdoor entertaining space investment.
United States
Sun Belt suburban homeowners in Florida, Texas, and Arizona prioritize extended outdoor entertaining spaces with integrated lighting and ceiling fan mount points. EPA treated-wood certification standards under tightening guidelines extend compliance timelines for domestic lumber suppliers. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate pre-fabricated metal canopy fabrication serving commercial hospitality rollouts.
Canada
Pacific Northwest residential architects specify cross-laminated timber and thermally modified hardwood alternatives to satisfy LEED v4.1 material ingredient reporting requirements. Health Canada's PMRA regulates wood preservative formulations for pressure-treated lumber used in outdoor structures. Greater Vancouver and Toronto metropolitan areas absorb composite pergola demand as homeowners prioritize maintenance-cycle certainty over first-cost minimization.
Germany
EU Green Deal embodied carbon thresholds filter into public procurement guidelines for municipal park and community gathering installations. ECHA REACH compliance shapes resin formulation requirements for engineered wood-plastic composite systems. Bavaria and Baden-Württemberg industrial clusters specialize in aluminum extrusion and powder-coated metal systems capturing specification share from traditional wood.
Australia
New South Wales and Queensland hospitality venues favor tensile fabric canopy systems for pool decks and restaurant patios requiring code-compliant temporary coverage. The country's national building code regulator mandates wind load ratings for UV-exposed fabric assemblies in cyclone-prone coastal zones. Sydney and Melbourne metropolitan areas concentrate distribution networks for contractor-centric fulfillment with extended warranty attach rates.
United Kingdom
Southeast England residential markets drive custom-built pergola demand through architectural consultation attach rates capturing deepest margin pools. UK Building Regulations and British Standards Institute certification govern structural timber grading for outdoor living structures. London commuter belt suburbs concentrate design-build services encompassing permitting, foundation work, and integrated utility rough-ins.
Outdoor Living Structure Market Key Industry Players
Global majors compete with regional champions across material specialization and distribution channel depth, producing a tiered structure where premium composite formulators, metal extrusion specialists, and big-box retailers each occupy defended positions. Three archetypes dominate: vertically integrated material-science firms controlling resin formulation and extrusion, contractor-centric fulfillment platforms with private-label sourcing leverage, and specialized fabricators with design-build capabilities. Capacity expansion in aluminum extrusion and strategic partnerships between composite suppliers and big-box distributors represent the dominant competitive moves reshaping channel economics.
Among North American building products specialists, Trex Company and Royal Building Products exemplify the material-science archetype with composite and vinyl-clad hybrid expertise respectively, while Lowe's Companies anchors the contractor-centric fulfillment platform tier. These three entities represent contrasting strategic positions—formulation control, maintenance-cycle differentiation, and distribution density—without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Lowe's Companies |
| Aluminum Company of America |
| Trex Company |
| Deckorators (UFP Industries) |
| Royal Building Products |
| Masonite International Corporation |
| Azek Company |
| Latham |
| The Home Depot |
| Others |
Cost & Logistics Intelligence
Composite resin compounding advances are compressing per-unit manufacturing costs while simultaneously concentrating production among facilities with EPA-compliant ventilation systems and ICC-ES certification capabilities. This technological shift elevates capital barriers for mid-scale wood treatment operators and tilts margin capture toward aluminum extrusion and engineered material specialists with captive formulation expertise.
Pricing Analysis
Input-cost pass-through from aluminum tariff adjustments and engineered resin pricing volatility is compressing margin predictability for metal and composite fabricators. Three-tier pricing structure across premium, standard, and economy levels separates composite systems with 25-year fade warranties from pressure-treated lumber and vinyl-clad hybrids. Pricing pressure stems from EPA certification timeline extensions elevating working capital requirements for domestic wood suppliers. Residential DIY segments exhibit highest price sensitivity, while hospitality procurement prioritizes speed-to-open premiums over first-cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Chinese aluminum extrusion feedstock and domestic southern yellow pine treatment facilities facing EPA compliance bottlenecks. Geographic supply concentration centers on United States, China, and Germany for raw material processing and finished fabrication. Raw material dependencies draw from aluminum billets, engineered wood-plastic resins, and pressure-treatment chemicals. Tariff exposure on metal inputs represents the dominant structural risk. Distribution runs through contractor-centric fulfillment networks anchored by big-box retailers with private-label sourcing leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in composite formulation control and design-build service attach rates, driven by homeowner preference for maintenance-cycle certainty over first-cost minimization.
For Market Incumbents: Lock in composite resin supply agreements and captive aluminum extrusion capacity to defend against tariff-adjusted pricing volatility. Invest in ICC-ES pre-certification for novel formulations to compress 12-18 month evaluation timelines. Prioritize Sun Belt contractor referral program density to capture professional installation margin pools before regional skilled labor shortages constrain capacity expansion. For New Entrants and Emerging Players: Augmented reality design tools offer a technology-first wedge to reduce consultation friction in direct-to-consumer channels. Target underpenetrated Pacific Northwest and Northeast residential markets where cross-laminated timber and thermally modified hardwood alternatives satisfy LEED v4.1 compliance demand. Pursue hospitality pre-fabricated canopy procurement where speed-to-open requirements favor new vendor qualification over incumbent relationship depth. For Investors and Strategic Acquirers: Roll-up economics work for specialized design-build fabricators because skilled installation shortages in regional contractor pools create scarcity value for turnkey service capabilities. Long-term viability hinges on composite material warranty positioning displacing cedar replacement cycles. Monitor California and Colorado wildfire-resistant mandate adoption as inflection indicator for metal substitution acceleration beyond coastal corrosion-driven demand patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive formulation control insulates margin from engineered plastic pricing volatility and EPA compliance cost pass-through. |
| ICC-ES Pre-Certification Investment | Accelerated building code approval compresses product launch cycles by 12-18 months versus reactive certification pathways. |
| Contractor-Centric Fulfillment Partnership | Design consultation attach rates in professional installation channels capture deepest margin pools in Sun Belt expansion markets. |
| Wildfire-Resistant Product Line Extension | California and Colorado state mandate alignment positions metal systems for specification share beyond coastal corrosion applications. |
| EU Green Deal Compliance Certification | Embodied carbon threshold documentation enables premium positioning for low-carbon composite exports into European public procurement. |
Research Approach
Coverage spans United States, Canada, Germany, Australia, and United Kingdom, with primary inputs from each market cluster. The analysis combines structured interviews with pergola and gazebo fabricators, big-box retail category managers, commercial hospitality procurement directors, and regional contractor installation specialists with secondary validation from EPA treated-wood certification databases, ICC-ES evaluation reports, EU Green Deal public procurement guidelines, and customs trade flow records. Bottom-up demand modeling across product type, material, end user, and installation method segments triangulates against top-down market sizing.
Granularity-level modeling disaggregates volume and value across the projection horizon by pergola, gazebo, arbor, and canopy product types; wood, metal, composite, and fabric material tiers; residential, commercial, hospitality, and public space end users; and pre-fabricated, custom-built, DIY, and professional installation methods. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers and regulatory timeline assumptions. Industry-specific forecast inputs include EPA certification pipeline data, Sun Belt housing permit velocity, and hospitality development pipeline tracking.
The model holds under stable tariff regimes and EPA enforcement continuity; deviation in aluminum trade policy or accelerated wildfire-resistant mandate adoption would shift composite-metal substitution trajectories. Forecasts embed assumptions regarding skilled labor availability and resin supply chain stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Residential Roofing Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
North America Residential Construction Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
UK Residential Construction Market
Residential Construction
US Residential Construction Market
Residential Construction
Germany Residential Construction Market
Residential Construction
Siding Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Europe Residential Construction Market