
 US Modular Construction Market | 2026-2036
US Modular Construction Market Size, Share, and Industry Trends Forecast 2026-2036
US Modular Construction Market Insights
Digital twin integration with offsite fabrication workflows is reconfiguring project delivery timelines and quality assurance protocols across the US modular construction sector. Clayton Homes leverages its manufactured housing scale to dominate single-family volumetric production in the Southeast. Guerdon anchors large-scale commercial modular projects through its Boise manufacturing footprint. WILLSCOT MOBILE MINI HOLDINGS CORP controls the relocatable modular segment with its national fleet and service infrastructure.
US modular construction encompasses factory-built volumetric units, panelized assemblies, and hybrid systems that comply with state-adopted versions of the International Building Code or HUD Code standards for permanent installation or relocation. These structures serve residential, commercial, industrial, and educational applications where schedule compression and labor predictability outweigh traditional stick-built economics. Permanent modular commands the largest value share as developers seek asset-class durability with factory-controlled tolerances. Relocatable modular sustains margins through recurring lease revenue from government agencies and event-driven demand. Volumetric construction methods lead growth in multi-story commercial and hospitality projects where module stacking reduces site labor exposure.
FHA, Fannie Mae, and state-level factory-built housing programs shape financing accessibility and building code adoption across US modular markets. The Department of Housing and Urban Development administers the federal manufactured home construction and safety standards that preempt local codes for qualifying structures. Stakeholders must monitor evolving appraisal methodologies and zoning preemptions that determine whether modular assets achieve parity with site-built collateral in mortgage markets.
Market Dynamics
EPA energy efficiency standards for commercial buildings are compressing traditional construction timelines and forcing developers toward factory-controlled fabrication methods that guarantee compliance before site delivery.
Growth Catalysts
- HUD Code standardization:Federal preemption of local building codes for manufactured housing accelerates permitting velocity and reduces jurisdictional friction for qualifying modular structures.
- Healthcare facility expansion:Hospital systems facing capacity constraints deploy volumetric patient care units to compress activation schedules and limit site labor exposure.
- Texas-Florida-California demand concentration:Housing shortages intersecting with streamlined factory-built housing programs in these states concentrate developer investment and manufacturing capacity.
Market Restraints
- Lumber and steel input volatility:Commodity price swings compress margins for panelized and volumetric producers locked into fixed-price contracts with general contractors.
- Transportation radius limitations:Module dimensional constraints and highway permitting restrict viable manufacturing-to-site distances, concentrating production in specific corridors.
- Site-built financing parity gaps:Fannie Mae and FHA appraisal methodologies that lag factory-built collateral recognition constrain mortgage accessibility for permanent modular buyers.
Strategic Opportunities
- Digital twin convergence:Integration of BIM workflows with factory automation systems enables real-time quality telemetry and predictive maintenance across distributed production networks.
- Federal infrastructure incentives:IRA-aligned energy efficiency credits and state-level factory-built housing programs create subsidy pools for net-zero modular development.
- Relocatable modular leasing:Government agencies and event-driven demand segments favor operational expenditure models over capital deployment for temporary space needs.
Industry Challenges
- Skilled factory technician scarcity:CNC operation and precision assembly expertise pools remain shallow relative to projected capacity expansion requirements.
- Multi-trade coordination complexity:Electrical, plumbing, and HVAC rough-in sequencing within volumetric units demands tighter subcontractor integration than traditional construction.
- State-by-state code fragmentation:Variations in adopted IBC versions create compliance engineering overhead for manufacturers serving multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Modular Construction Market |
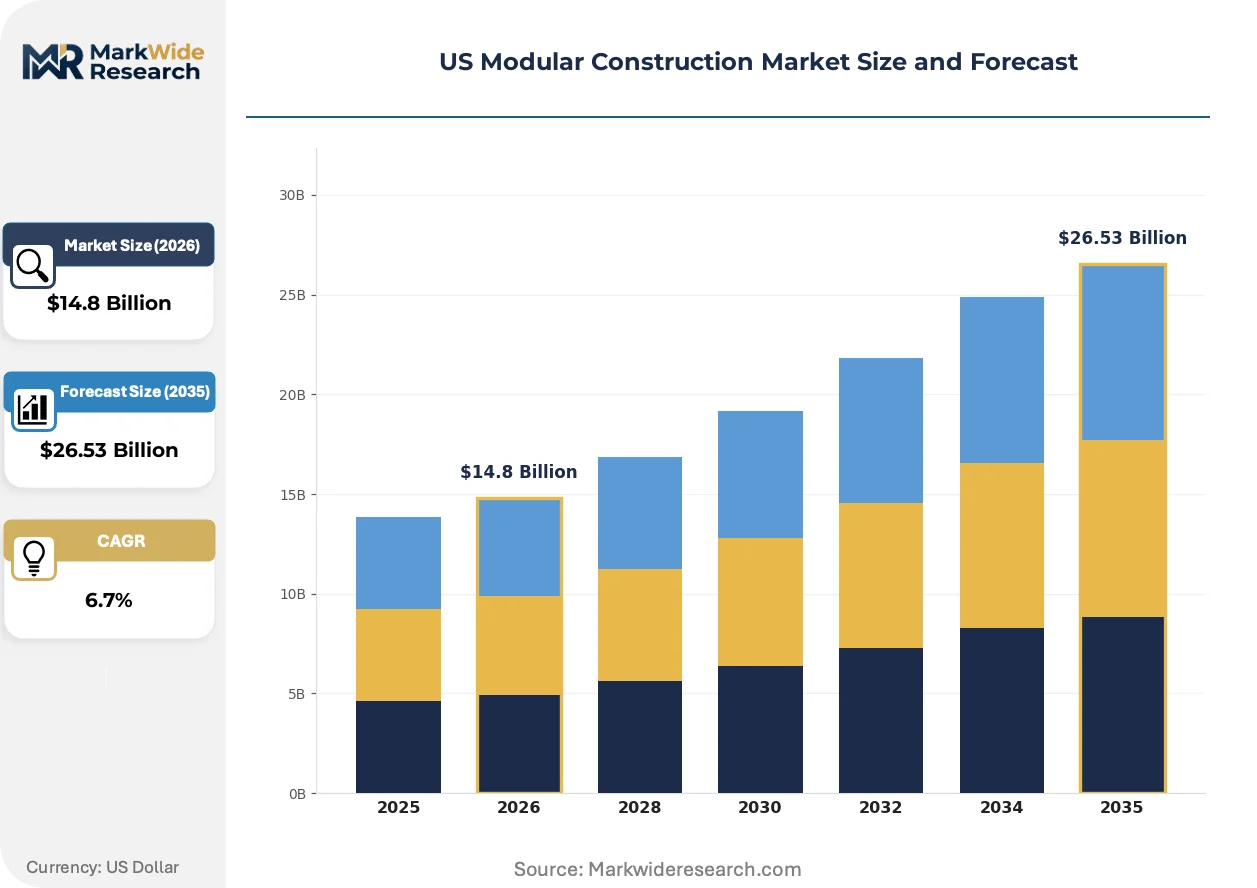
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Modular, Relocatable Modular, Hybrid Modular, Containerized Modular Application: Residential, Commercial, Industrial, Educational Construction Method: Panelized, Prefabricated, Volumetric, Modularization End User: Developers, Contractors, Government Agencies, Private Sector |
| Companies Covered | Lendlease Corporation, WILLSCOT MOBILE MINI HOLDINGS CORP, Clayton Homes, Modular Genius, Modular Building Systems, Cavco Industries, Guerdon, SEA BOX, ATCO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Modular Construction Market Trends and Innovations
Digital fabrication workflows are collapsing the traditional boundary between design engineering and production execution, enabling mass customization at scale economics previously reserved for standardized product lines.
BIM-to-factory data pipelines are virtualizing quality assurance protocols by embedding dimensional tolerance checks directly into CNC cutting and assembly robotics. Healthcare and hospitality developers now require digital twin handoffs as contract deliverables, compressing commissioning timelines and reducing punch-list remediation. This virtualization of inspection workflows is displacing traditional third-party site verification and shifting liability frameworks toward manufacturing entities.
EPA commercial building energy standards are tightening envelope performance requirements that favor factory-controlled assembly environments over site-built methods. The agency's evolving compliance timelines are accelerating prefabrication adoption among Class A office and multifamily developers seeking guaranteed performance certification. California and New York jurisdictions are responding with expedited permitting pathways for modular projects meeting predetermined efficiency benchmarks.
Buyers are consolidating procurement around design-build-modulate contracts that transfer single-source accountability to integrated manufacturing partners. General contractors in the Southeast and Southwest are ceding early-stage design involvement to factory engineering teams, reversing traditional bid-build sequencing. This concentration of procurement authority is most visible in student housing and senior living verticals where repeat developers prioritize schedule certainty over first-cost minimization.
US Modular Construction Market Segmentation
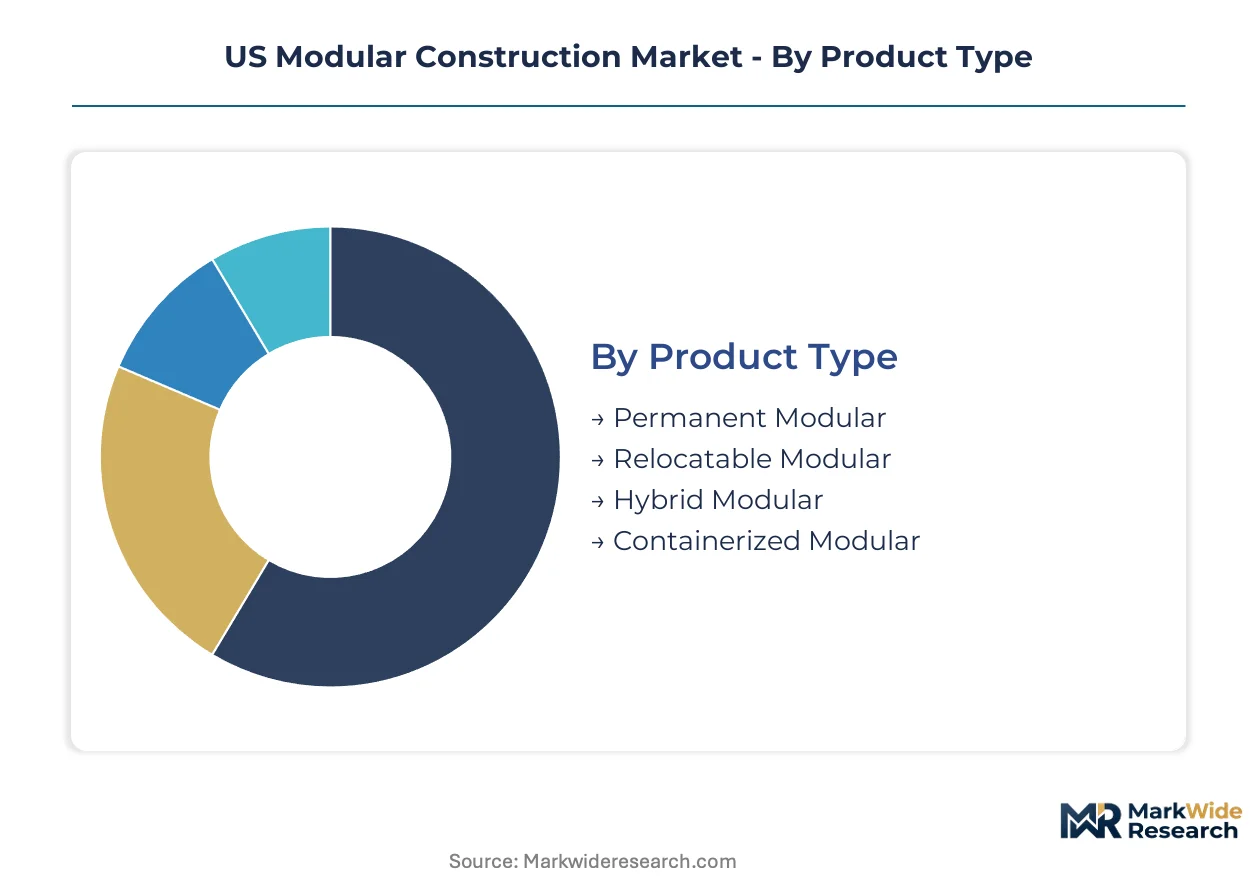
Segmentation reveals how US modular construction demand fragments across product durability tiers, project delivery methods, and procurement authority. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with permanent installations demanding long-term warranty networks while relocatable units require fleet maintenance and redeployment logistics.
- Permanent Modular:Factory-built volumetric units engineered for permanent foundation installation under state-adopted IBC standards. Demand concentrates in Texas multifamily and California senior housing where developers seek asset-class collateral treatment and HUD Code preemption accelerates permitting velocity.
- Relocatable Modular:Transportable structures designed for repeated deployment and lease-based revenue models. WILLSCOT MOBILE MINI HOLDINGS CORP dominates this segment through national service infrastructure serving government agencies and event-driven demand across Florida and the Southwest.
- Hybrid Modular:Combined panelized and volumetric systems blending factory fabrication with site-integrated MEP completion.
- Containerized Modular:Repurposed shipping container structures adapted for commercial and industrial applications.
By volume, permanent modular leads. By growth pace, relocatable modular is expanding most quickly through recurring lease revenue models.
Application:
Cost tier stratification separates premium institutional projects from economy residential deployments, with commercial applications commanding design-build-modulate contract premiums.
- Residential:Single-family and multifamily volumetric production serving housing shortage corridors. Clayton Homes leverages manufactured housing scale across the Southeast where streamlined factory-built programs intersect with affordability constraints.
- Commercial:Class A office and hospitality projects requiring guaranteed EPA energy efficiency certification before occupancy. Guerdon anchors this tier through Boise manufacturing capacity serving multi-story stacking applications.
- Industrial:Manufacturing facilities and warehouse modules prioritizing rapid enclosure and weather-independent scheduling.
- Educational:Student housing and K-12 expansion projects where repeat developers prioritize schedule certainty over first-cost minimization.
By project count, residential dominates. By contract value concentration, commercial is gaining share fastest.
Construction Method:
Customer type determines method selection, with developers favoring volumetric certainty while contractors retain panelized flexibility for site-integrated sequencing.
- Volumetric:Fully enclosed three-dimensional modules with complete MEP rough-in manufactured under factory-controlled tolerances. Healthcare facility developers in California and Texas deploy this method to compress patient care unit activation schedules and limit site labor exposure.
- Panelized:Wall, floor, and roof assemblies fabricated offsite for site-integrated erection. Southeast general contractors favor this approach for design flexibility and reduced transportation radius constraints.
- Prefabricated:Component-level factory production of structural and finish elements.
- Modularization:Process-oriented decomposition of traditional construction into standardized subassemblies.
By adoption breadth, panelized leads. By revenue per project, volumetric shows the steepest expansion trajectory.
End User:
Supply concentration among integrated manufacturers favors developers with consolidated procurement authority over fragmented contractor bidding.
- Developers:Repeat institutional investors in student housing and senior living verticals consolidating procurement around design-build-modulate contracts. This segment transfers single-source accountability to factory engineering teams, reversing traditional bid-build sequencing.
- Government Agencies:Federal, state, and municipal entities favoring operational expenditure models for temporary space needs. The EPA's evolving commercial building standards accelerate compliance-driven prefabrication among agency facility managers.
- Contractors:General contractors ceding early-stage design involvement to factory teams in the Southeast and Southwest.
- Private Sector:Corporate end-users procuring modular solutions for expansion and facility modernization.
By procurement volume, developers lead. By contract growth, government agencies are climbing the fastest through IRA-aligned infrastructure incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas manufacturers ship volumetric modules to California and Florida buyers, while Boise-based fabricators serve multi-story commercial projects across the Mountain West and Pacific states. This corridor structure concentrates production capacity near interstate highway networks and state-level factory-built housing programs.
Texas
Housing shortages in Dallas-Fort Worth and Houston drive multifamily volumetric demand. The Texas Department of Housing and Community Affairs administers factory-built housing programs that streamline permitting velocity. Manufacturing clusters in Central Texas and the Dallas metro supply modules to residential developers seeking HUD Code preemption benefits.
California
EPA energy efficiency standards and senior housing shortages accelerate permanent modular adoption in Los Angeles and Bay Area metros. The California Department of Housing and Community Development enforces Title 25 standards for factory-built housing. Sacramento and Central Valley production facilities serve institutional developers pursuing net-zero certification pathways.
Florida
Climate resilience requirements and rapid population growth concentrate demand in Miami-Dade and Orlando corridors. The Florida Building Commission coordinates state-adopted IBC versions for modular compliance. Tampa and Jacksonville manufacturing hubs supply healthcare and educational projects facing hurricane-resistant construction mandates.
Southeast
Affordability constraints and manufactured housing scale economies dominate single-family production across Georgia, Alabama, and the Carolinas. Clayton Homes leverages regional manufacturing footprints to serve rural and suburban markets. Atlanta and Charlotte distribution networks extend modular reach into secondary markets with streamlined state-level programs.
Pacific Northwest
Seattle and Portland housing affordability crises drive cross-laminated timber and hybrid modular experimentation. Washington State's factory-built housing program and Oregon's reach code amendments favor offsite fabrication. Boise-based Guerdon anchors commercial volumetric production serving multi-story stacking applications across the region.
US Modular Construction Market Competitive Landscape
On the supply side, the industry is bifurcated between scale-driven manufactured housing producers and project-specific commercial volumetric fabricators. Permanent modular specialists compete on engineering credentials and warranty networks, while relocatable operators sustain margins through fleet density and lease-term optimization. Two strategic archetypes dominate: vertically integrated manufacturers controlling design-to-installation workflows, and regional fabricators serving discrete metropolitan markets with transportation-constrained radius strategies. Competitive moves concentrate on capacity expansion along interstate corridors and strategic partnerships with general contractors seeking schedule certainty.
Among scale-driven manufacturers, Clayton Homes and Cavco Industries exemplify the manufactured housing archetype with national production footprints. Guerdon occupies a position within the commercial volumetric tier, anchoring large-scale project capability through Boise manufacturing infrastructure. WILLSCOT MOBILE MINI HOLDINGS CORP represents the relocatable modular archetype, controlling national fleet logistics and service infrastructure for temporary space demand. These three entities illustrate how supply-side positioning fragments across product durability tiers and procurement authority models.
| Leading Market Players |
|---|
| Lendlease Corporation |
| WILLSCOT MOBILE MINI HOLDINGS CORP |
| Clayton Homes |
| Modular Genius |
| Modular Building Systems |
| Cavco Industries |
| Guerdon |
| SEA BOX |
| ATCO |
| Others |
Pricing and Supply Chain Analysis
Central Texas manufacturing clusters anchor volumetric production capacity that feeds California and Florida buyers, concentrating pricing power among fabricators with interstate corridor access and HUD Code preemption capabilities. This geographic supply concentration enables premium capture for EPA-compliant commercial modules while squeezing margins on standardized residential units facing lumber and steel input volatility.
Pricing Analysis
Current-generation volumetric construction with integrated MEP rough-in commands premium-mid-economy pricing differentiation against prior-generation panelized systems and next-generation hybrid digital-fabrication methods. Price differentiation rests on EPA energy efficiency certification tiers, with Class A office developers in California paying premiums for guaranteed envelope performance. Cost compression in economy residential tiers is intensifying because Clayton Homes and Cavco Industries leverage manufactured housing scale across the Southeast. Government agencies exhibit lowest price sensitivity through operational expenditure lease models, while first-time multifamily buyers in Texas face acute affordability constraints.
Supply Chain Analysis
Export-control regimes on advanced CNC fabrication equipment and robotics automation systems limit technology transfer to domestic manufacturers, constraining capacity expansion velocity. Geographic supply concentrates in the United States, with Boise-based Guerdon and Central Texas clusters serving multi-story commercial demand, while Mexican maquiladoras feed component-level panelized inputs. Raw material dependencies span engineered lumber, cold-formed steel, and high-performance insulation systems. Single-source vulnerability in precision assembly robotics creates bottleneck exposure. Distribution runs through factory-direct relationships with developers and general contractor partnerships in the Southeast and Southwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US modular construction sector rewards manufacturers with captive CNC programming expertise and precision assembly technician pipelines, while penalizing capital-light entrants lacking factory automation capabilities. This capability scarcity dynamic intensifies as healthcare and hospitality developers mandate digital twin deliverables as contract requirements.
For Market Incumbents: Harden warranty network density in California and Texas to defend permanent modular market position against emerging hybrid-system competitors. Deepen upstream control over engineered lumber supply through captive supplier agreements, insulating margin structures from commodity volatility. Prioritize EPA certification pre-approval workflows to accelerate compliance-driven project capture. For New Entrants and Emerging Players: Mid-market educational facilities in Florida and the Pacific Northwest represent the most penetrable entry point, as repeat developers consolidate procurement authority and prioritize schedule certainty over incumbent brand loyalty. Relocatable modular leasing for federal infrastructure projects offers recurring revenue traction with lower capital intensity than permanent modular manufacturing. Pursue design-build-modulate contract positioning to transfer single-source accountability from general contractors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because manufacturing capacity constraints and skilled technician scarcity favor scaled operators with established training pipelines. Acquisition targets should emphasize Boise or Central Texas production footprints with interstate corridor access. Monitor EPA commercial building standard tightening velocity as the inflection signal for compliance-premium capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | BIM-to-factory pipelines enable real-time quality telemetry across distributed production networks. |
| EPA Certification Pre-Approval | Expedited permitting pathways in California and New York accelerate project activation timelines. |
| Technician Training Pipeline Development | CNC operation and precision assembly expertise pools remain shallow relative to capacity expansion requirements. |
| Interstate Corridor Capacity Expansion | Manufacturing proximity to Texas-Florida-California demand concentrations reduces transportation radius constraints. |
| Relocatable Modular Fleet Density | Government agency operational expenditure models favor lease-based revenue over capital deployment. |
Research Methodology
Desk research of HUD Code filings, EPA commercial building standard documentation, and state-level factory-built housing program regulations preceded structured interviews with volumetric manufacturing plant managers, healthcare facility development executives, general contractor procurement leads, and CNC automation system engineers. Secondary validation drew from Fannie Mae appraisal methodology publications, Department of Housing and Urban Development administrative records, and Interstate Building Code compliance databases. Bottom-up project pipeline analysis triangulated against top-down manufacturing capacity assessments.
Assumptions held fixed include HUD Code preemption continuity, EPA energy efficiency standard phase-in schedules, and interstate highway permitting regimes for oversized module transport. Variables stress-tested encompass lumber and steel commodity price bands, skilled technician wage inflation, and digital twin technology adoption curves. Segmentation modeling spanned product durability tiers, construction method categories, and end-user procurement authority types. CAGRs derived from unit shipment trajectories and average selling price movements across the projection horizon, with healthcare facility expansion rates and multifamily housing permit volumes as industry-specific demand inputs.
Stress conditions across commodity input costs, transportation fuel pricing, and federal infrastructure incentive allocation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and variable ranges. Material shifts in EPA regulatory enforcement intensity or state-level zoning preemption for factory-built housing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Precast Construction Market
Building Construction
US Offsite Construction Market
Building Construction
Ireland Data Center Construction Market
Building Construction
France Prefab Homes Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
Japan Commercial Construction Market
Building Construction
Guatemala Construction Market
Building Construction
France Prefab Wood Building Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
UAE Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Tanzania Construction Market
Building Construction
Spain Construction Market
Building Construction
Saudi Arabia Construction Market
Building Construction
South Korea Data Center Construction Market