
 Latin America Residential Construction Market | 2026-2036
Latin America Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Residential Construction Market Foresight
Skilled masonry labor availability is unwinding project timelines across Central American job sites. MRV Engenharia leverages prefabrication systems to bypass localized craft shortages. SalfaCorp S.A. anchors its Chilean portfolio with concrete-intensive designs that reduce dependence on specialized trades. Cyrela Brazil Realty S.A. dominates São Paulo's high-rise segment through captive workforce training programs.
Latin America residential construction encompasses the erection of single-family homes, multi-family units, condominiums, and townhouses using steel, concrete, wood, or glass assemblies, typically involving poured foundations, masonry or framed superstructures, and utility-ready finishes for human habitation. Small-scale and medium-scale projects absorb the majority of regional cement and rebar volumes due to fragmented land ownership patterns. Multi-family units generate the densest margin pools where vertical concrete construction achieves repetition economies. Owner-occupied single-family homes retain the largest share of mortgage origination flows across Brazilian and Mexican banking networks.
Brazil's ABNT technical standards, Mexico's CONAVI housing quality protocols, and Chile's Ministry of Housing urban development guidelines collectively dictate structural seismic ratings, energy efficiency thresholds, and social-housing quota requirements. These frameworks elevate compliance costs for imported material assemblies while privileging domestic concrete and steel supply chains. Stakeholders must track how municipal-level zoning liberalization in Colombian and Peruvian cities reshapes land-release velocity and project-bankability assessments.
Market Dynamics
Prefabrication systems are compressing construction timelines across Latin America by decoupling project schedules from localized masonry labor availability. Brazil's updated urban zoning codes and Mexico's CONAVI housing quality protocols are accelerating permitting velocity for standardized designs while penalizing conventional cast-in-place methods.
Growth Catalysts
- Mortgage market deepening:Brazilian and Mexican banking networks are expanding origination flows to middle-class urban buyers, unlocking purchasing power in São Paulo's metropolitan ring and Mexico City's peripheral municipalities.
- CONAVI housing quality protocols:Mexico's certification framework is streamlining approval pathways for repetitive concrete designs, reducing project-bankability assessment cycles for multi-family developers.
- Green building certifications:Mexico's emerging environmental standards are creating preference premiums for energy-efficient assemblies, pulling demand toward certified concrete and steel supply chains.
Market Restraints
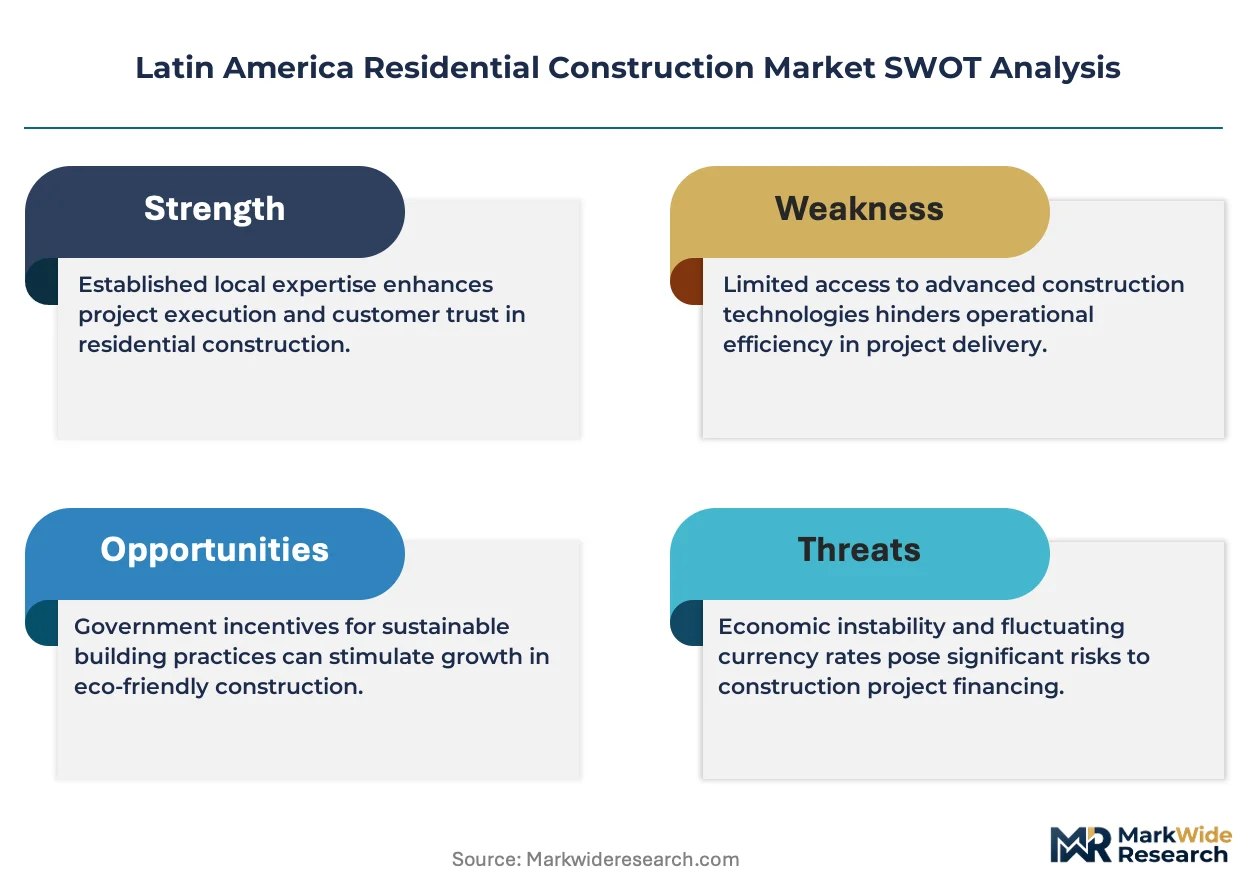
- Skilled masonry labor scarcity:Central American job sites face unwinding timelines due to craft shortages, forcing reliance on costlier prefabricated alternatives or extended training investments.
- Domestic material privileging:Brazil's ABNT technical standards and Chile's Ministry of Housing guidelines elevate compliance costs for imported assemblies, locking builders into concentrated local concrete and rebar suppliers.
- Fragmented land ownership:Small-scale and medium-scale projects absorb disproportionate cement volumes, preventing scale economies that vertical construction achieves in denser markets.
Strategic Opportunities
- Colombian municipal zoning liberalization:Land-release velocity in Colombian and Peruvian cities is accelerating, creating first-mover advantages for developers with pre-positioned permitting capabilities.
- Seismic-rated concrete innovation:Chile's structural seismic rating requirements are pulling demand toward engineered rebar configurations, opening margin pools for technical specification upgrades.
- Captive workforce training:São Paulo's high-rise segment rewards developers with in-house masonry and concrete finishing academies, insulating project timelines from regional labor volatility.
Industry Challenges
- Permitting timeline compression:Brazil's updated urban zoning codes require simultaneous compliance with federal, state, and municipal layers, stretching administrative bandwidth for mid-scale developers.
- Social-housing quota fulfillment:Chile's Ministry of Housing mandates are forcing market-rate developers to integrate below-market units, complicating pro-forma structuring and equity sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Residential Construction Market |
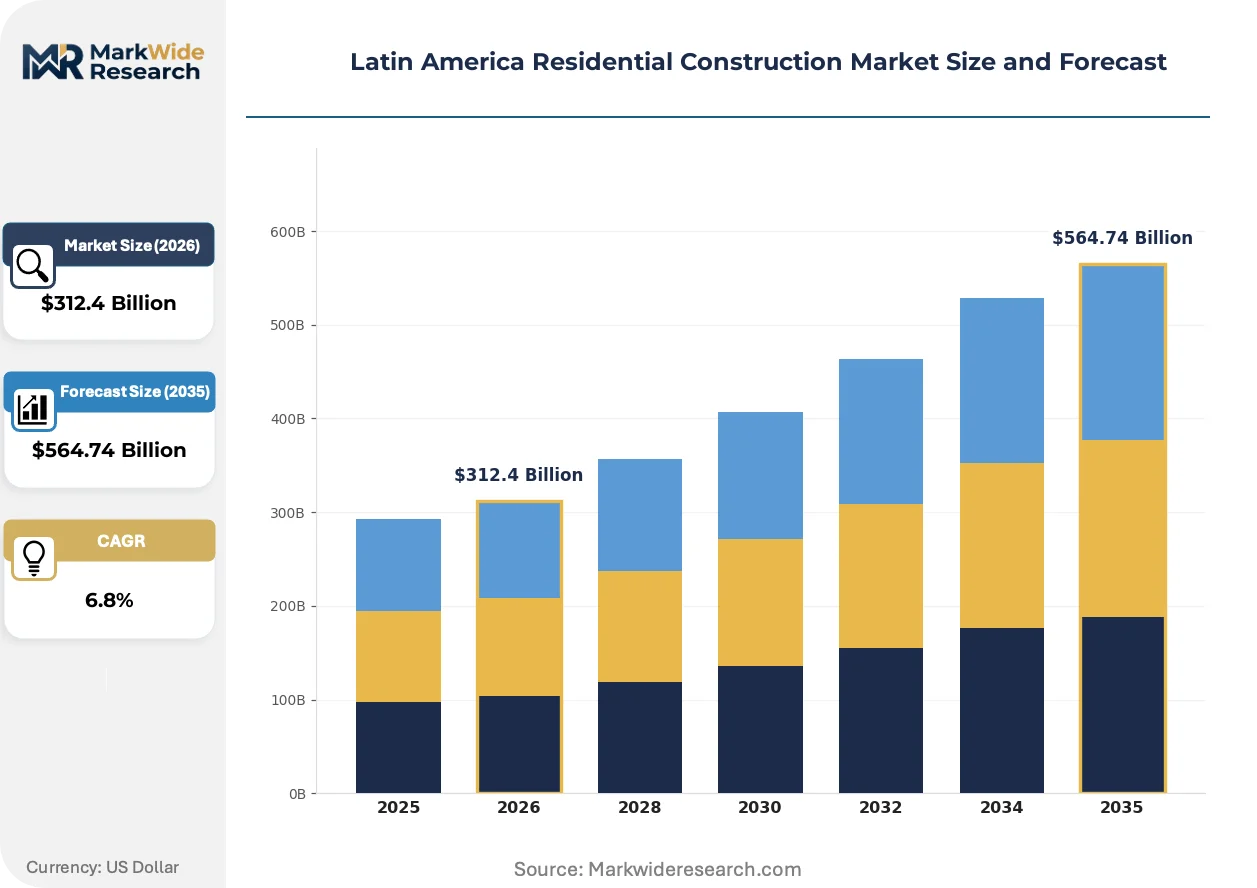
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Family Homes, Multi-Family Units, Condominiums, Townhouses Construction Material: Steel, Concrete, Wood, Glass Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Occupancy Type: Owner-Occupied, Renter-Occupied, Vacation Homes, Investment Properties |
| Companies Covered | Socovesa S.A., Grupo Carso, Hogares Edén, S.A. de C.V., IDEAL, Constructora Meco S.A., Constructora VDZ SpA, MRV Engenharia, SalfaCorp S.A., Cyrela Brazil Realty S.A., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Residential Construction Market Shifts & Advancements
Concrete-intensive design standardization is reshaping competitive positioning across Latin America by reducing project dependency on specialized trades. Regulatory harmonization between national building codes and municipal zoning is compressing approval cycles for repetitive construction methods.
Prefabricated wall and floor systems are supplanting traditional masonry superstructures in Brazilian multi-family developments. MRV Engenharia and similar large-scale developers are adopting panelized concrete assemblies to bypass localized craft shortages. This technology is supplanting conventional block-and-plaster methods, enabling six-month construction cycles that conventional approaches cannot match.
Brazil's ABNT technical standards are tightening structural seismic ratings for mid-rise residential buildings in seismic zones. The industrial consequence is mandatory engineering review for all concrete frame designs above four stories. Multi-family developers in São Paulo's metropolitan ring are responding by pre-certifying repetitive structural modules with accredited laboratories.
Buyer concentration is shifting toward mortgage-ready purchasers as Brazilian and Mexican banks tighten origination standards for informal-income applicants. The broker channel serving self-employed buyers is contracting, replaced by direct bank-developer partnerships targeting salaried public-sector employees. This shift is most visible in Mexico City's peripheral municipalities, where CONAVI-certified projects receive preferential rate pricing.
Latin America Residential Construction Market Segmentation
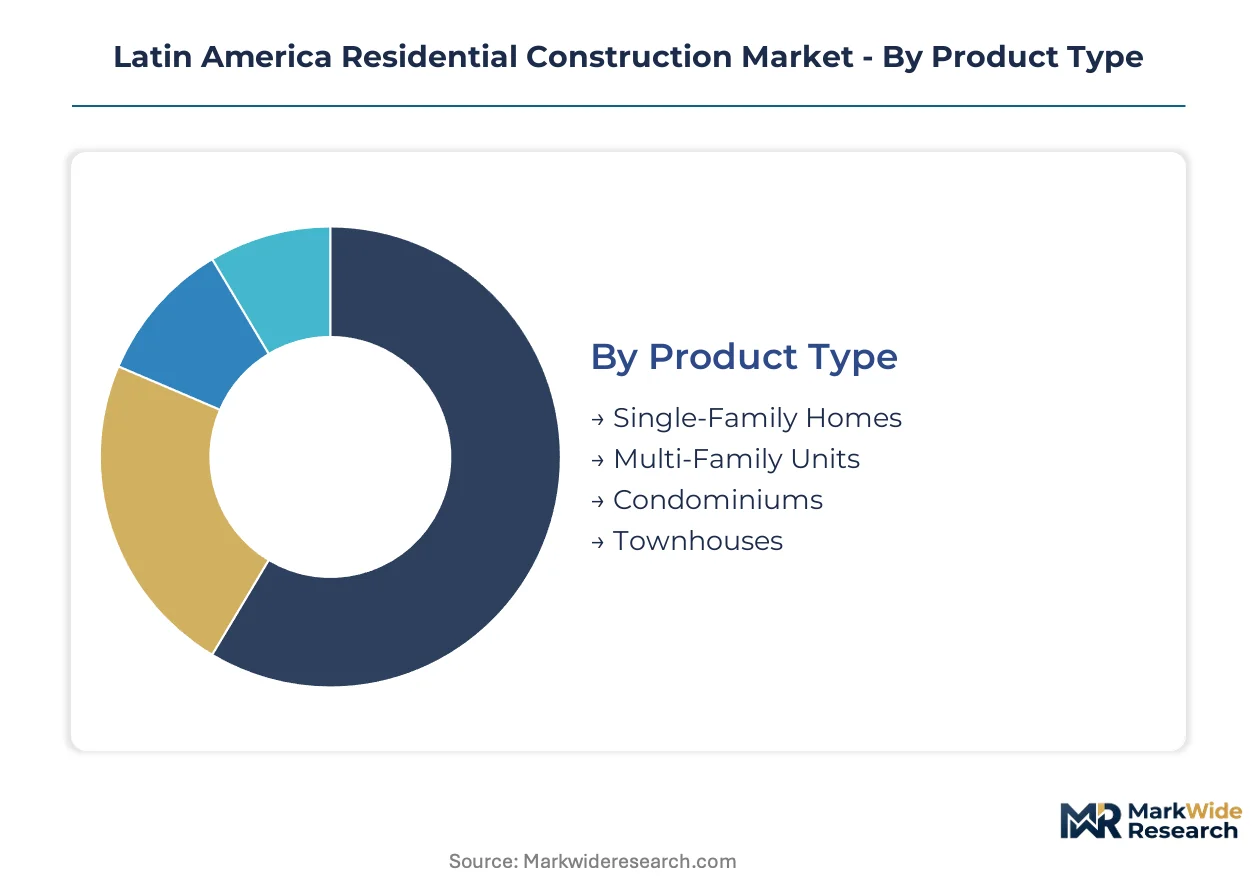
Latin America's residential construction fragmentation demands granular segmentation to isolate where mortgage liquidity, prefabrication scale, and regulatory compliance intersect. Builders targeting São Paulo's metropolitan ring face entirely different material procurement and labor strategies than those operating in Mexico City's peripheral municipalities or Chilean seismic zones.
Product Type:
Domestic demand anchors single-family and multi-family construction across Brazilian and Mexican urban corridors, while vacation homes and investment properties serve export-led demand from North American retirees and regional capital flight.
- Single-Family Homes:Detached structures on individually titled plots dominate mortgage origination flows across Brazilian and Mexican banking networks. Owner-occupied single-family stock concentrates in São Paulo's metropolitan ring and Mexico City's peripheral municipalities where land titling clarity enables secured lending.
- Multi-Family Units:Vertical concrete construction achieves repetition economies through standardized floor plates and pre-certified structural modules. Chile's Ministry of Housing mandates social-housing quotas within these developments, complicating pro-forma structuring for market-rate builders in Santiago's densifying districts.
- Condominiums:Common-interest developments with shared amenity infrastructure attract salaried public-sector employees through direct bank-developer partnerships.
- Townhouses:Attached single-family configurations balance density with individual ownership appeal in Colombian municipal zones experiencing land-release acceleration.
Single-family homes hold the largest share; momentum sits with multi-family units as urban zoning liberalization accelerates vertical permitting velocity.
Construction Material:
Cost tier stratification separates premium engineered systems from commodity domestic supply chains privileged by national technical standards.
- Concrete:Poured foundations and masonry superstructures absorb disproportionate regional cement volumes due to fragmented land ownership patterns. Brazil's ABNT technical standards and Chile's seismic rating requirements pull demand toward engineered rebar configurations in mid-rise construction.
- Steel:Framed superstructures enable rapid assembly in labor-scarce Central American job sites where skilled masonry availability unwinds traditional timelines. Imported steel assemblies face elevated compliance costs under domestic material privileging regulations.
- Wood:Light-frame construction serves vacation home segments in coastal Colombian and Peruvian markets with shorter structural lifespan requirements.
- Glass:Curtain wall systems differentiate premium condominium offerings in São Paulo's high-rise segment through energy efficiency certification premiums.
Concrete commands volume leadership; steel is climbing the fastest as prefabrication systems displace site-dependent masonry methods.
Project Size:
Volume concentration patterns reveal how scale economies fragment across Latin America's dispersed land ownership and concentrated urban finance.
- Small Scale:Individual lot developments by owner-builders or micro-developers absorb majority regional cement and rebar volumes. These projects forfeit scale economies that vertical construction achieves in denser markets.
- Medium Scale:Subdivisions of 10-50 units by regional developers dominate mortgage-ready supply in Mexican CONAVI-certified corridors. Standardized designs streamline approval pathways while reducing project-bankability assessment cycles.
- Large Scale:Master-planned communities by national developers like MRV Engenharia leverage captive workforce training programs to insulate timelines from regional labor volatility.
- Mega Projects:Integrated urban districts require simultaneous federal, state, and municipal compliance layers that stretch administrative bandwidth.
Small-scale projects hold the largest share; large-scale developments are gaining share fastest through prefabrication-enabled timeline compression.
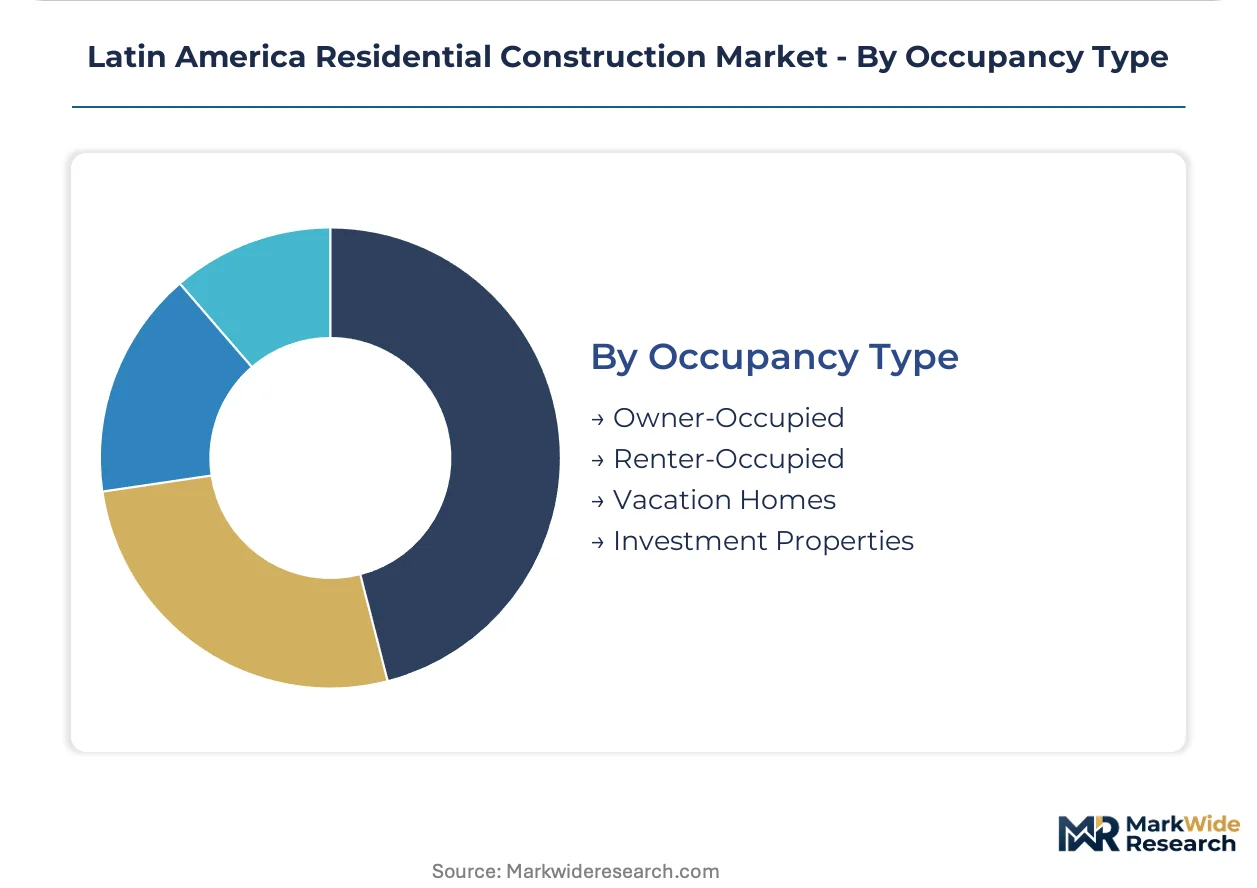
Occupancy Type:
Customer type stratification tracks how mortgage market deepening reshapes builder targeting away from informal-income channels.
- Owner-Occupied:Salaried households with documented income access preferential rate pricing on CONAVI-certified projects. Brazilian and Mexican banks have tightened origination standards, contracting the broker channel serving self-employed buyers.
- Renter-Occupied:Purpose-built rental stock expands in São Paulo's metropolitan ring where institutional investors acquire completed multi-family blocks.
- Vacation Homes:Secondary residences in coastal Brazilian and Colombian markets serve North American retiree demand and regional capital preservation.
- Investment Properties:Speculative acquisition concentrates in Mexico City's peripheral municipalities where infrastructure completion timelines create appreciation windows.
Owner-occupied units hold the largest share; investment properties are expanding most quickly as dollar-denominated capital seeks hard-asset hedges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's building material certification protocols anchor Brazil's regulatory framework, while Mexico's CONAVI housing standards and Chile's Ministry of Housing seismic guidelines create divergent compliance pathways across the region's three largest construction markets.
Brazil
Mortgage origination flows concentrate in São Paulo's metropolitan ring where middle-class buyers access preferential rate pricing. ABNT technical standards tighten structural seismic ratings for mid-rise residential buildings above four stories. MRV Engenharia and Cyrela Brazil Realty S.A. dominate the high-rise segment through captive workforce training programs that insulate project timelines from regional masonry labor volatility.
Mexico
CONAVI housing quality protocols streamline approval pathways for repetitive concrete designs, accelerating permitting velocity for standardized multi-family developments. Mexico City's peripheral municipalities absorb the densest concentration of mortgage-ready purchasers as banks tighten origination standards for informal-income applicants. Direct bank-developer partnerships targeting salaried public-sector employees are displacing the traditional broker channel in these corridors.
Chile
Seismic-rated concrete innovation pulls demand toward engineered rebar configurations mandated by the Ministry of Housing's structural rating requirements. Santiago's densifying districts face social-housing quota mandates that complicate pro-forma structuring for market-rate developers. SalfaCorp S.A. anchors its portfolio with concrete-intensive designs that reduce dependence on specialized trades while meeting compliance thresholds.
Colombia
Municipal zoning liberalization in Bogotá and Medellín accelerates land-release velocity, creating first-mover advantages for developers with pre-positioned permitting capabilities. Townhouse configurations balance density with individual ownership appeal in zones experiencing infrastructure completion. Coastal markets serve vacation home demand from North American retirees seeking secondary residences with shorter structural lifespan requirements.
Argentina
Economic volatility drives speculative acquisition patterns in Buenos Aires where dollar-denominated capital seeks hard-asset hedges through investment properties. Fragmented land ownership patterns absorb disproportionate cement and rebar volumes across small-scale and medium-scale projects. Prefabrication systems remain limited by import restrictions on steel assemblies that face elevated compliance costs under domestic material privileging regulations.
Latin America Residential Construction Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Latin America's residential construction sector. The market fragments between large-scale national developers with captive workforce training programs and regional specialists concentrating on standardized designs for mortgage-certified corridors. Three archetypes dominate: prefabrication-enabled volume builders, concrete-intensive seismic specialists, and integrated land-banking developers. Competitive moves concentrate on vertical integration into material supply chains and strategic partnerships with banking networks for mortgage origination access.
Among Brazilian S.A.-structured developers, MRV Engenharia exemplifies the prefabrication-enabled archetype, while Cyrela Brazil Realty S.A. occupies a position within the integrated land-banking tier. Chile's SalfaCorp S.A. represents the concrete-intensive seismic specialist model. These three entities anchor distinct strategic positions without overlapping capability claims, reflecting how geographic regulatory divergence permits simultaneous specialization across national markets.
| Leading Market Players |
|---|
| Socovesa S.A. |
| Grupo Carso |
| Hogares Edén, S.A. de C.V. |
| IDEAL |
| Constructora Meco S.A. |
| Constructora VDZ SpA |
| MRV Engenharia |
| SalfaCorp S.A. |
| Cyrela Brazil Realty S.A. |
| Others |
Supply & Pricing Matrix
Fragmented land ownership patterns across São Paulo's metropolitan ring and Mexico City's peripheral municipalities prevent cement producers from achieving capacity utilization thresholds that would compress per-ton price floors. This scale fragmentation simultaneously elevates procurement costs for small-scale developers and locks regional supply chains into concentrated domestic concrete and rebar networks privileged by national technical standards.
Pricing Analysis
São Paulo commands a 15-20% premium over Central American corridors for equivalent structural concrete specifications, reflecting transport friction and ABNT compliance overhead. Three-tier pricing structure across premium certified, standard CONAVI-compliant, and economy informal-grade segments stratifies the market, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier is intensifying as informal masonry labor scarcity forces owner-builders toward costlier prefabricated alternatives. Self-employed informal-income buyers exhibit highest price sensitivity, while salaried public-sector employees accessing preferential mortgage rates show lowest elasticity.
Supply Chain Analysis
Brazilian port congestion at Santos and Paranaguá creates chokepoints that delay engineered rebar deliveries to Santiago seismic-rated projects by 3-4 weeks. Geographic supply concentration centers on Brazil, Mexico, and Chile for finished concrete assemblies, with raw material dependencies spanning Colombian cement clinker, Peruvian copper for electrical infrastructure, and domestic rebar production. Single-source vulnerability runs through captive relationships between large developers and accredited concrete laboratories for pre-certification. Distribution runs through direct bank-developer partnerships that bypass traditional broker channels in mortgage-certified corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's residential construction fragmentation creates multiple niche opportunities as mortgage market deepening concentrates demand in certified corridors while informal channels contract. This demand-side shift rewards specialized positioning over undifferentiated scale.
For Market Incumbents: Fortify timeline certainty through captive workforce training programs that insulate São Paulo high-rise developments from regional masonry labor volatility. Secure backward integration into pre-certified structural module production to defend against prefabrication-enabled entrants. ABNT seismic rating tightening for mid-rise buildings above four stories threatens developers dependent on conventional cast-in-place methods without engineering review capabilities. For New Entrants and Emerging Players: Mortgage-ready purchaser services represent a service-layer gap where incumbents under-serve self-employed buyers now excluded from tightened origination standards. Target Colombia's municipal zoning liberalization corridors in Bogotá and Medellín where land-release acceleration outpaces established permitting capabilities. Deploy direct-to-developer digital origination platforms that compress assessment cycles for CONAVI-certified projects. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors prefabrication-enabled volume builders with demonstrated six-month construction cycle capabilities over conventional site-dependent operators. Long-term viability across a 5-10 year window hinges on regulatory harmonization between national building codes and municipal zoning that compresses approval velocity. Acquisition targets should demonstrate pre-positioned permitting capabilities in Colombian or Peruvian acceleration corridors. The signal to watch is CONAVI protocol expansion beyond Mexico into Central American markets as regional regulatory convergence indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication System Deployment | Panelized concrete assemblies bypass masonry labor scarcity and compress São Paulo construction cycles. |
| Captive Workforce Academy Investment | In-house concrete finishing training insulates MRV Engenharia timelines from regional craft volatility. |
| CONAVI Certification Pre-Positioning | Early protocol adoption accelerates Mexico City peripheral municipality permitting velocity. |
| Seismic-Rated Rebar Specification Upgrade | Engineered configurations meet Chile Ministry of Housing mandates and open technical margin pools. |
| Direct Bank-Developer Partnership | Bypass of broker channels targets salaried public-sector employee mortgage origination flows. |
Research Methodology
Initial hypotheses were tested against primary input from project development executives at national builders, municipal permitting officers in São Paulo and Mexico City, concrete supply chain managers, mortgage origination specialists at Brazilian and Mexican banking networks, and seismic engineering consultants in Santiago. These perspectives were refined through secondary validation against ABNT technical standard publications, CONAVI housing quality protocol documentation, Chile Ministry of Housing seismic guideline filings, Colombian municipal zoning ordinance updates, and customs data tracking cement and rebar trade flows. Bottom-up project pipeline assessments were triangulated against top-down national construction output estimates.
Variance-decomposition across product type, construction material, project scale, and occupancy type dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segmented growth trajectory modeling that weighted mortgage market deepening velocity against regulatory compliance cost inflation. Industry-specific forecast inputs incorporated prefabrication adoption curves in Brazilian multi-family developments and seismic-rated concrete specification upgrade rates in Chilean mid-rise construction.
Forecasts assume regulatory continuity in Brazil's ABNT framework, Mexico's CONAVI protocols, and Chile's Ministry of Housing guidelines; material policy shifts would require re-modeling of permitting timeline and compliance cost assumptions. Specific risk factors include municipal zoning reversal in Colombian liberalization corridors, import restriction tightening on steel assemblies in Argentina, and banking network origination standard volatility affecting mortgage-ready purchaser access. Practitioners should keep alternative scenarios live as regulatory harmonization negotiations between national building codes and municipal zoning evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Swimming Pool Construction Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
North America Residential Construction Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Japan Residential Construction Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Siding Market
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
North America Prefabricated Housing Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Outdoor Living Structure Market